
 Primary Packaging Labels Market | 2026-2036
Primary Packaging Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Packaging Labels Market Analytics
Polyethylene terephthalate (PET) film is hardening as the preferred substrate over conventional polyvinyl chloride in shrink sleeve applications due to recyclability mandates and improved mechanical performance. Avery Dennison Corporation leverages its materials science portfolio to dominate pressure-sensitive adhesive development for pharmaceutical serialization. CCL Industries Inc. sustains manufacturing scale across European pharmaceutical hubs through specialized cleanroom label production. UPM Raflatac anchors sustainable paper and film substrate supply to brand owners targeting circular packaging commitments.
Primary packaging labels are pressure-sensitive, sleeve, or adhesive-backed substrates applied directly to consumer product containers, typically specified with print resolutions of 120 lines per centimeter and moisture resistance thresholds to ensure barcode legibility through distribution cycles. These labels serve regulatory compliance, brand communication, and supply chain traceability functions across consumer goods industries. Pressure sensitive labels lead volume globally due to versatility across container geometries and compatibility with high-speed applicators, while digital printing technology captures the fastest expansion as brands reduce minimum order quantities and accelerate versioning for regional campaigns. Shrink sleeve formats command premium positioning in personal care and beverage segments where full-body decoration drives shelf differentiation.
The European Medicines Agency enforces serialization and anti-tampering standards under the Falsified Medicines Directive, compelling pharmaceutical label investments with integrated security features. The EU Green Deal and national Extended Producer Responsibility frameworks in France and Germany mandate recyclability disclosures that reshape material selection and adhesive specification. REACH chemical restrictions further constrain solvent-based ink formulations, pushing converters toward water-based and UV-curable alternatives. Stakeholders must monitor evolving packaging waste directives and digital watermarking standards to align capital allocation with compliance timelines and recycling infrastructure readiness.
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are compressing converter lead times while forcing capital redeployment into track-and-trace infrastructure across European packaging hubs.
Growth Catalysts
- EMA Serialization Mandates:The European Medicines Agency's anti-tampering standards compel pharmaceutical manufacturers to integrate 2D barcodes and tamper-evident features, driving specialized cleanroom label investments.
- PET Film Substitution:Recyclability targets under France and Germany's Extended Producer Responsibility frameworks are accelerating displacement of polyvinyl chloride with polyethylene terephthalate in shrink sleeve applications.
- Digital Print Adoption:Brand owners in beverage and personal care segments are deploying inkjet and toner systems to compress versioning cycles for regional campaign launches.
Market Restraints
- Adhesive Raw Material Volatility:Acrylic resin and silicone release liner supply disruptions from petrochemical feedstock fluctuations constrain margin stability for pressure-sensitive label converters.
- REACH Chemical Restrictions:The European Chemicals Agency's solvent-based ink limitations are forcing premature equipment write-downs and reformulation costs across narrow-web flexo operations.
- Recycling Infrastructure Gaps:Inconsistent European collection and sorting capabilities for multi-layer label-film combinations limit circular packaging claims and create greenwashing exposure.
Strategic Opportunities
- Cleanroom Expansion in Switzerland:Swissmedic's stringent pharmaceutical packaging standards create premium positioning for converters with ISO 14644-certified production environments.
- Digital Watermark Integration:The HolyGrail 2.0 initiative's machine-readable packaging markers enable automated sortation, creating first-mover advantage for label suppliers embedding compatible graphic elements.
- UV-Curable Ink Convergence:Combination of LED curing systems with low-migration formulations addresses both REACH compliance and high-speed production requirements in food contact applications.
Industry Challenges
- Serialization Data Architecture:Pharmaceutical customers demand real-time verification system integration, requiring converters to build IT capabilities foreign to traditional print operations.
- Multi-Substrate Certification Timelines:Migration testing for new adhesive-face stock combinations under EU 10/2011 food contact regulations extends product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Packaging Labels Market |
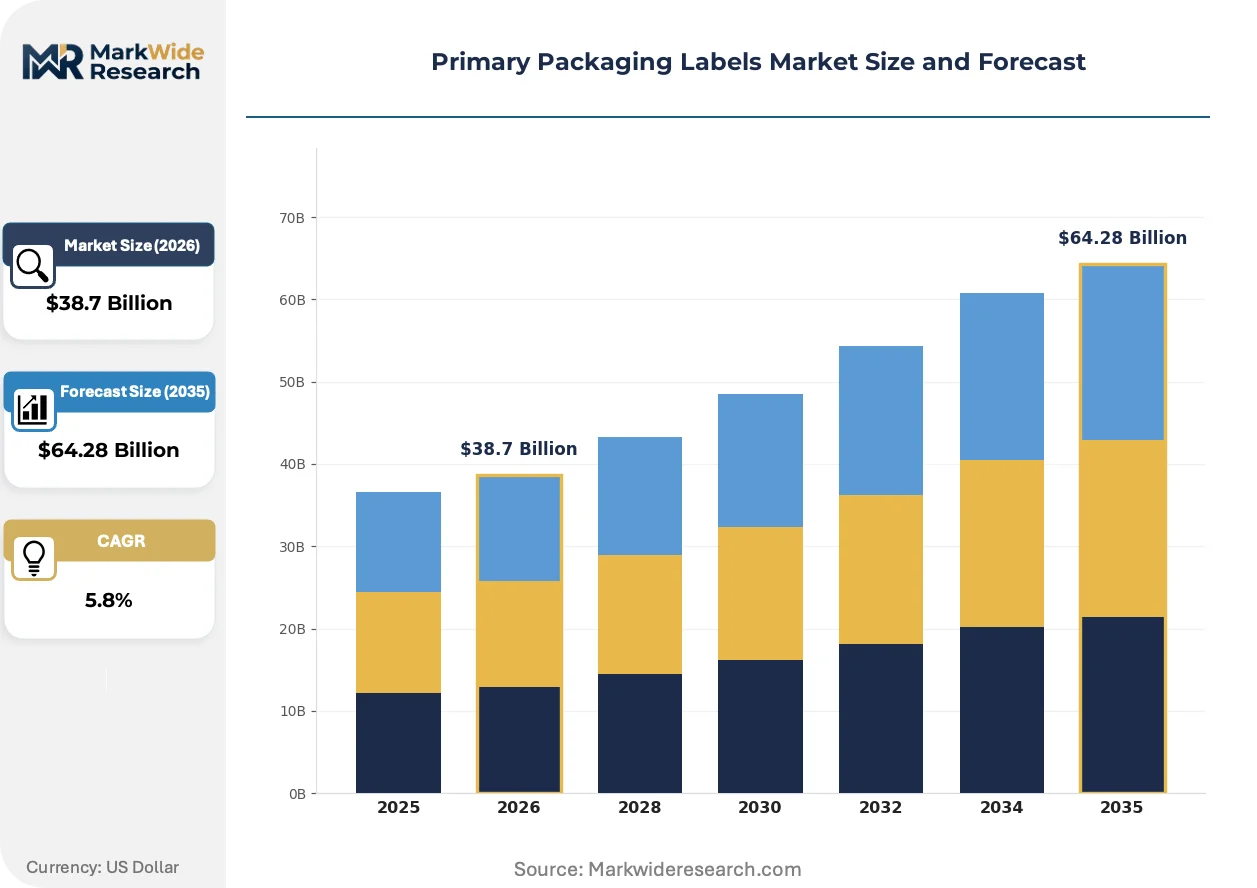
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Pressure Sensitive, Shrink Sleeve, In-Mold, Glue Applied Material: Paper, Plastic, Foil, Vinyl End Use Sector: Food & Beverage, Pharmaceuticals, Personal Care, Chemicals Printing Technology: Flexographic, Digital, Lithographic, Gravure |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Multi-Color Corporation, UPM Raflatac, WestRock Company, Huhtamaki Oyj, Fuji Seal International Inc., Amcor plc, SATO Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Packaging Labels Market Evolving Landscape
Track-and-trace functionality is migrating from regulatory checkbox to competitive differentiator as pharmaceutical and food brands exploit serialization data for consumer engagement and supply chain optimization.
Digital printing infrastructure is modularizing converter operations by decoupling prepress from production, enabling pharmaceutical contract packagers in Germany and France to absorb versioning demand without minimum order quantity penalties or plate inventory carrying costs.
REACH Article 33 disclosure requirements are forcing systematic chemical inventory audits across European label supply chains, compelling converters to document Substances of Very High Concern in adhesives and coatings while accelerating substitution programs for bisphenol-containing thermal papers.
Brand technical buyers are consolidating supplier panels around circular packaging credentials, with French and German beverage manufacturers now mandating recyclable film specifications and adhesive wash-off compatibility as gate criteria for primary label procurement decisions.
Primary Packaging Labels Market Segmentation
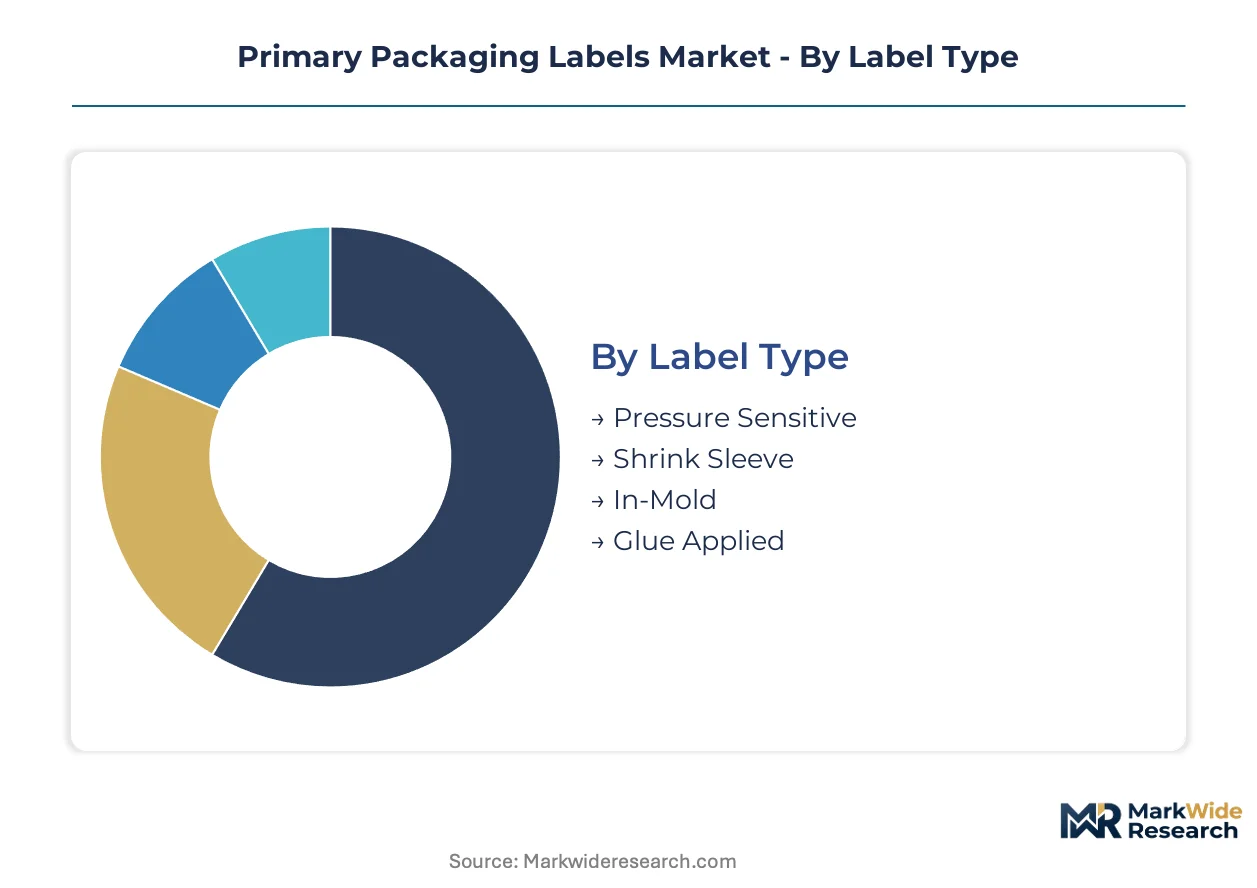
Converters configure production lines around label type and material specifications, while end-use sector demands dictate security features and print resolution requirements. Material selection and printing technology choices determine capital intensity and margin profiles across converter operations.
Label Type:
Capital intensity varies sharply across label formats, with cleanroom infrastructure and serialization systems driving pharmaceutical-grade pressure sensitive investments to multiples of standard beverage equipment.
- Pressure Sensitive:Self-adhesive constructions with release liner and face stock layers, specified for 120 lines per centimeter print resolution. Pharmaceutical serialization mandates in Germany and France absorb the majority of European cleanroom capacity for this format. Pressure sensitive labels dominate volume across container geometries due to applicator compatibility.
- Shrink Sleeve:PET film substrates replacing PVC under recyclability mandates, delivering 360-degree decoration with tamper-evident functionality. Beverage brands in Germany specify shrink sleeves for premium shelf differentiation, though adhesive wash-off requirements complicate circular packaging claims.
- In-Mold:Labels fused directly into container walls during blow molding or injection molding, eliminating secondary application steps. Automotive and durable goods packaging in France deploy in-mold labels for chemical resistance.
- Glue Applied:Wet-glue adhesives applied via rotary or linear systems, remaining cost-competitive for high-volume beverage and food container operations with simple graphics requirements.
Pressure sensitive labels absorb the bulk of installed capacity; shrink sleeve formats are expanding most quickly under PET substitution trends.
Material:
Material selection pivots on end-use durability requirements and circular packaging commitments, with film substrates commanding premium positioning over paper alternatives.
- Paper:Uncoated and coated stocks for short-shelf-life applications, specified for dry goods and secondary packaging where moisture resistance is non-critical. French food manufacturers specify paper labels for organic product lines targeting composting infrastructure.
- Plastic:PET, PP, and PE films delivering moisture barrier and mechanical durability for beverage and personal care segments. German Extended Producer Responsibility frameworks accelerate plastic film specification with recyclable and wash-off adhesive compatibility.
- Foil:Aluminum laminates providing oxygen and light barrier properties for pharmaceutical blister packs and premium cosmetic containers.
- Vinyl:PVC films facing displacement pressure under EU Green Deal recyclability targets, with converters migrating volumes to PET alternatives.
Plastic films capture the steepest expansion trajectory; paper retains volume leadership in cost-sensitive segments.
End Use Sector:
Sector concentration determines regulatory exposure and security feature requirements, with pharmaceutical and food applications subject to the most stringent compliance architectures.
- Food & Beverage:Labels requiring EU 10/2011 food contact migration compliance, with wash-off adhesives and recyclable films now mandatory for procurement by major German and French bottlers.
- Pharmaceuticals:EMA serialization mandates under the Falsified Medicines Directive compel 2D barcode integration and tamper-evident features, driving cleanroom label investments with ISO 14644 certification requirements.
- Personal Care:Full-body shrink sleeve decoration for shelf differentiation, with digital print adoption accelerating versioning for regional campaign launches.
- Chemicals:GHS hazard communication labels requiring solvent-resistant adhesives and UV-stable inks for outdoor storage conditions.
Food and beverage absorbs the bulk of installed capacity; pharmaceuticals is gaining share fastest under serialization mandate deadlines.
Printing Technology:
Technology selection balances run length economics against versioning flexibility, with digital systems disrupting traditional plate-based workflows.
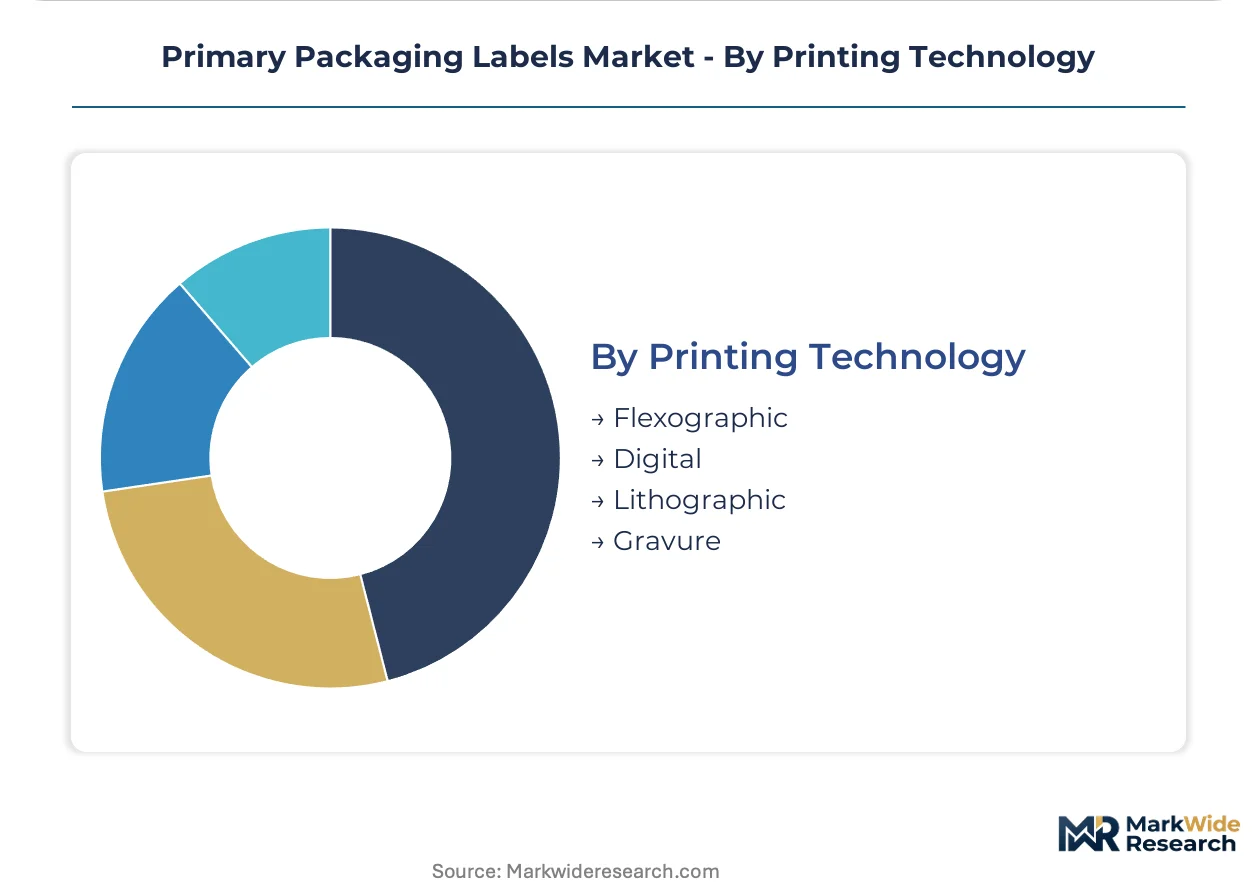
- Flexographic:Rotary letterpress-derived systems dominating long-run beverage and food label production, with narrow-web operations facing REACH solvent-based ink constraints.
- Digital:Inkjet and toner systems decoupling prepress from production, enabling pharmaceutical contract packagers in Germany and France to absorb versioning demand without minimum order quantity penalties.
- Lithographic:Offset printing for high-quality graphics on paper substrates, competitive for premium food and cosmetic applications with longer run lengths.
- Gravure:Engraved cylinder systems for ultra-long-run shrink sleeve and flexible packaging applications with consistent ink density requirements.
Flexographic equipment retains the bulk of installed capacity; digital printing is climbing the fastest as brands compress campaign cycle times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical serialization mandates and Extended Producer Responsibility frameworks concentrate converter investments in Germany, France, and Switzerland, with beverage bottling clusters and pharmaceutical manufacturing hubs driving regional demand patterns.
Germany
EMA anti-tampering standards and the Falsified Medicines Directive compress converter lead times for pharmaceutical serialization labels. Germany's national packaging waste regulator enforces recyclability disclosures under Extended Producer Responsibility frameworks. The Rhine-Main packaging corridor hosts centralized bottling operations where wash-off adhesive specifications now gate procurement decisions.
France
French beverage manufacturers mandate recyclable film substrates and adhesive wash-off compatibility for primary label procurement. ANSM pharmaceutical packaging standards align with EU serialization requirements. The Lyon-Grenoble industrial basin concentrates personal care contract packaging where digital print adoption accelerates regional campaign versioning.
Switzerland
Swissmedic's stringent pharmaceutical packaging standards create premium positioning for ISO 14644-certified cleanroom label production. The country's medical device regulator enforces traceability requirements comparable to EMA mandates. Basel's pharmaceutical manufacturing cluster absorbs specialized converter capacity for tamper-evident and serialization-integrated labels.
United Kingdom
Post-Brexit pharmaceutical labeling regulations maintain serialization alignment with EU Falsified Medicines Directive standards. The Medicines and Healthcare products Regulatory Agency enforces comparable anti-tampering requirements. The M62 corridor pharmaceutical manufacturing belt sustains converter demand for high-resolution barcode labels with integrated security features.
Italy
Italian wine and spirits exporters adopt shrink sleeve formats for premium shelf differentiation in export markets. The Ministry of Health's food contact regulations under EU 10/2011 constrain adhesive migration specifications. The Emilia-Romagna packaging machinery district integrates label applicator systems with digital print workflows for regional beverage brands.
Primary Packaging Labels Market Competitive Landscape
Capacity expansion into cleanroom-certified production environments dominates the current landscape as converters respond to pharmaceutical serialization deadlines. The vendor base organizes around three strategic tiers: multinational materials science conglomerates with adhesive formulation capabilities, specialized pharmaceutical label converters with ISO-certified operations, and regional packaging printers serving beverage and food accounts. Technology licensing agreements for digital print systems and strategic partnerships for recycling infrastructure access represent the dominant competitive vectors.
Within the materials science tier, Avery Dennison Corporation and UPM Raflatac occupy positions anchored in substrate and adhesive development. CCL Industries Inc. exemplifies the pharmaceutical-specialist archetype with cleanroom production scale across European hubs. These three entities represent distinct competitive positions: substrate innovation leadership, sustainable materials supply, and regulated-industry manufacturing compliance.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Multi-Color Corporation |
| UPM Raflatac |
| WestRock Company |
| Huhtamaki Oyj |
| Fuji Seal International Inc. |
| Amcor plc |
| SATO Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Cleanroom-certified converter labor in the Rhine-Main corridor commands wage premiums that widen spreads between pharmaceutical-grade serialization labels and standard beverage formats. Extended Producer Responsibility compliance costs in Germany and France compress margins on economy-tier film substrates while insulating premium cleanroom operations from price erosion.
Pricing Analysis
Volume concentrates in standard pressure-sensitive labels for food and beverage applications, while margins accrue to pharmaceutical serialization formats with integrated 2D barcode and tamper-evident features. Three-tier pricing structure across premium cleanroom-certified, standard industrial-grade, and economy commodity levels separates converters by certification status and applicator speed compatibility. Cost compression in economy film substrates intensifies because of acrylic resin volatility and REACH-driven ink reformulation expenses. Beverage bottlers in Germany exhibit highest price sensitivity due to standardized procurement panels, while Swiss pharmaceutical manufacturers accept premium positioning for Swissmedic-compliant traceability.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale pharmaceutical and beverage buyer demand, bypassing distributor markups for serialization-integrated and wash-off adhesive specifications. Raw material sourcing draws from petrochemical feedstocks in Germany and Belgium for acrylic adhesives, with release liner production concentrated in Finland and Austria. Single-source vulnerability pervades specialized cleanroom substrate supply, where ISO 14644-certified face stock manufacturing clusters in Switzerland and southern Germany create geographic concentration risk. Distribution runs through converter-direct relationships for pharmaceutical serialization mandates, while beverage labels move via packaging machinery OEMs with integrated applicator systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
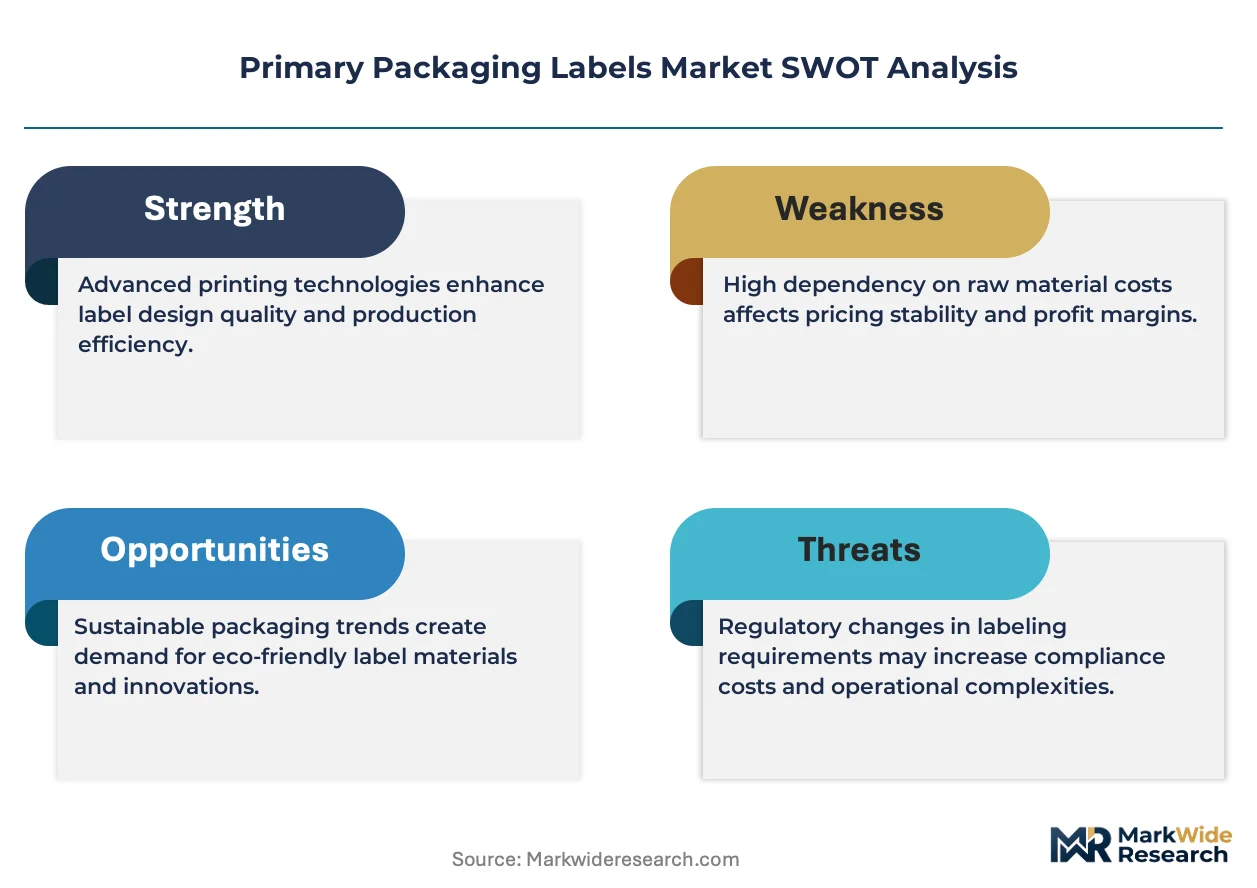
Primary packaging labels function as a consolidation play where REACH chemical restrictions and pharmaceutical serialization capital requirements force sub-scale converters toward exit or acquisition. EMA mandate deadlines compress the window for capability buildout, advantaging incumbents with installed cleanroom infrastructure.
For Market Incumbents: Hedge against adhesive raw material volatility through backward integration into silicone release liner production or long-term offtake agreements with petrochemical suppliers in the ARA refining hub. Defend pharmaceutical market position by accelerating ISO 14644 cleanroom capacity expansion ahead of Falsified Medicines Directive enforcement waves, while digital print module deployment captures versioning demand from contract packagers in France. For New Entrants and Emerging Players: Capture white-space opportunity in digital watermark-compatible label supply for HolyGrail 2.0 automated sortation infrastructure, where incumbent converters lag graphic element integration. Target Italian wine and spirits exporters adopting shrink sleeve formats for premium export positioning, leveraging digital print systems to bypass plate inventory barriers that constrain established flexo operations. For Investors and Strategic Acquirers: The window for entry favors mid-cap converters with latent cleanroom capacity and existing pharmaceutical customer relationships that can absorb serialization mandate volume spikes. Acquisition target archetype: regional European label printers with ISO-certified production environments and undervalued digital print infrastructure. Monitor EMA serialization deadline extensions and EU Green Deal packaging waste directive acceleration as inflection indicators for demand timing and material specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644 certification unlocks pharmaceutical serialization contracts under EMA mandates. |
| Digital Print Module Deployment | Inkjet systems decouple prepress from production for French beverage versioning demand. |
| Backward Integration into Adhesives | Captive acrylic resin supply insulates margins from petrochemical feedstock volatility. |
| Digital Watermark Integration | HolyGrail 2.0 compatibility creates first-mover positioning with automated sortation infrastructure. |
| UV-Curable Ink Reformulation | LED curing systems address REACH solvent restrictions while maintaining food contact compliance. |
Research Methodology
Trade association filings, EMA regulatory submissions, and European packaging waste directive documentation formed the secondary backbone for market sizing and compliance timeline calibration. Primary interviews with pharmaceutical packaging managers, beverage procurement leads at German bottlers, narrow-web flexo converters, and adhesive formulation specialists triangulated against customs data and converter capacity disclosures. Bottom-up label volume estimates by format and material combined with top-down end-use sector spend analysis to anchor projection ranges.
Bottom-up modeling tracked label consumption by pharmaceutical serialization unit requirements, beverage bottling line speeds, and personal care campaign versioning frequency across the analysis window. Segmentation dimensions included label type, substrate material, end-use sector regulatory tier, printing technology capital intensity, and geographic production cluster. CAGRs derived from converter capacity expansion announcements, EMA mandate phase-in schedules, and circular packaging commitment timelines from major brand owners.
The model holds under steady EMA enforcement and Extended Producer Responsibility implementation; deviation in recycling infrastructure buildout delays or REACH chemical restriction acceleration would shift material substitution trajectories. Practitioners should monitor HolyGrail 2.0 pilot scale-up and Swissmedic standard harmonization for early signals of specification change velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Glue Applied Automotive Labels Market
Labels
Barcode Label Market
Labels
Global Laminated Labels Market
Labels
Coated Wet Glue Label Market
Labels
Pre-Gummed Labels Market
Labels
Global Label Adhesive Market
Labels
Glue-Applied Labels Market
Labels
Direct Thermal Labels Market
Labels
Self-Laminating Tags Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Canning Labels Market
Labels
Global Thermal Transfer Label Market
Labels
Pin Feed Labels Market
Labels
Global in-Mold Labels Market
Labels
Die Cut Labels Market
Labels
Freezer Label Market