
 Sheeted Labels Market | 2026-2036
Sheeted Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Sheeted Labels Market Analytics
Direct-to-brand e-commerce channels is rewriting procurement patterns for sheeted labels, cutting out traditional distributor layers. Consolidated Label leverages in-house die-cutting capabilities to capture premium packaging accounts. Hub Labels sustains its position through specialized short-run digital production. Rebsons Labels anchors Southern African supply chains with localized adhesive formulation expertise.
Sheeted labels are individual label units cut into flat sheets, typically produced through rotary or flatbed die-cutting processes with release liners coated in silicone for clean removal; they serve primary functions in product identification, barcode readability, and brand communication on packaging lines. Pressure-sensitive formats dominate volume across food and pharmaceutical verticals due to line-speed compatibility and rework flexibility. Thermal transfer segments command margin pools in inventory tracking applications where solvent-resistant imaging withstands warehouse environmental stress. Paper substrates retain cost leadership in retail branding while polyester gains share in industrial labeling requiring chemical and abrasion resistance.
FDA food contact substance notifications, EPA adhesive volatile organic compound limits, and REACH substance restrictions collectively determine material eligibility and converter compliance costs in North American and European markets. ISO 9001 quality management and ISO 14001 environmental certification function as baseline qualifiers for supplier qualification at multinational brand owners. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recyclability mandates to anticipate specification shifts before they disrupt existing supply agreements.
Market Dynamics
Traceability mandates across food and pharmaceutical packaging lines are compressing procurement cycles and forcing converter investments in digital print infrastructure. Brands now demand lot-level serialization with sub-second scan reliability, reshaping specification standards for release liner chemistry and adhesive rheology.
Growth Catalysts
- EU Green Deal packaging recyclability targets:Mandates for mono-material compatibility are accelerating demand for paper-based release liners and washable adhesives in German and French retail supply chains.
- Food traceability infrastructure:GS1-128 barcode requirements in US cold-chain logistics are expanding thermal transfer label volumes for protein and dairy processors.
- Short-run digital production:Inkjet and toner technologies are enabling SKU proliferation without plate costs, allowing craft beverage brands to rotate seasonal artwork monthly.
Market Restraints
- Silicone release liner supply concentration:Three chemical conglomerates control over 70% of global silicone coating capacity, exposing converters to force majeure pricing volatility.
- REACH substance authorization timelines:ECHA's rolling reviews of adhesive tackifiers are extending qualification periods to 18-24 months, freezing formulation pipelines.
- Direct thermal substitution in logistics:E-commerce parcel sortation systems are migrating to thermal-direct formats for cost reduction, pressuring thermal transfer growth in warehouse applications.
Strategic Opportunities
- Brazilian pharmaceutical serialization:ANVISA's upcoming track-and-trace mandate creates first-mover advantage for converters with established São Paulo distribution partnerships.
- RFID-inlay integration:Convergence of pressure-sensitive labels with UHF RFID chips is opening apparel and automotive component tracking applications previously served by hard tags.
- India PLI scheme for packaging:Production-linked incentives for food processing infrastructure are stimulating label demand in Maharashtra and Gujarat manufacturing corridors.
Industry Challenges
- Color management expertise scarcity:Digital press operators with spectrophotometer calibration and ICC profile generation skills command 40% wage premiums, constraining converter expansion.
- ISO 15378 certification burden:Pharmaceutical primary packaging qualification requires 12-18 month audit cycles, locking working capital in inventory before revenue recognition.
- Legacy ERP integration friction:Mid-sized converters struggle to connect web-to-print storefronts with existing MIS systems, delaying e-commerce channel launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheeted Labels Market |
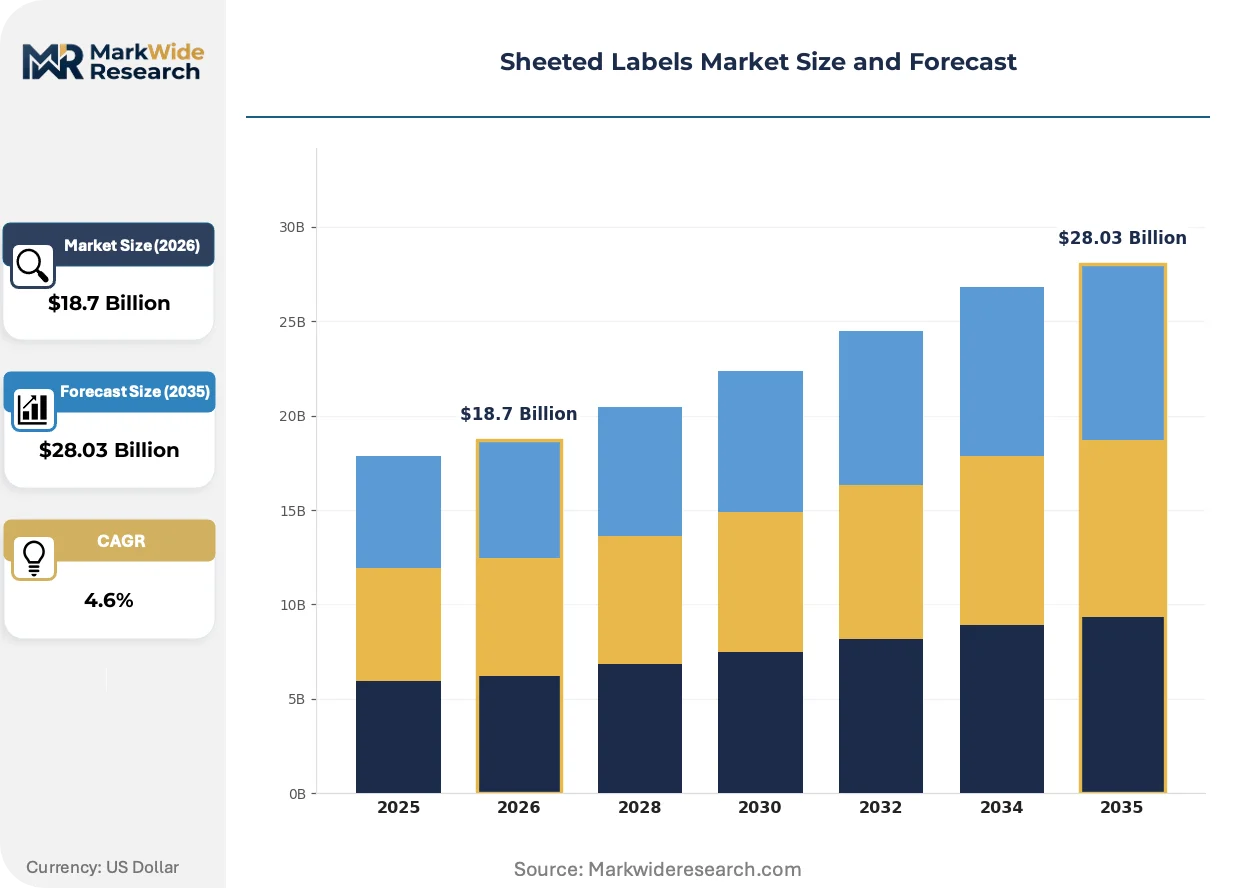
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Adhesive, Non-Adhesive, Thermal Transfer Industry Vertical: Food & Beverage, Pharmaceuticals, Retail, Industrial Application: Packaging, Branding, Product Identification, Inventory Tracking Material: Paper, Plastic, Vinyl, Polyester |
| Companies Covered | RGS Labels, Rebsons Labels, Hub Labels, Consolidated Label, New York Label & Box Works, Coding Solutions, Performance Label Company, Blanco, Ready Print Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheeted Labels Market Evolving Landscape
Digital workflow automation and substrate engineering are converging to collapse lead times from artwork approval to finished goods delivery. These shifts are compressing the traditional converter-distributor-brand owner value chain while elevating technical service capabilities as a competitive differentiator.
Cloud-based prepress systems are virtualizing plate-making and color-proofing workflows for sheeted label converters. Mid-tier packaging buyers in North American craft food segments are adopting these platforms to reduce proofing cycles from five days to 24 hours. This technology is virtualizing the geographic constraints that previously tied converter selection to physical proximity for press checks.
REACH Annex XIV authorization requirements for phthalate plasticizers are forcing adhesive reformulation across European personal care and cosmetics labeling. The industrial consequence is a 15-20% raw material cost premium for compliant hot-melt formulations. German and Benelux converters serving premium skincare brands are absorbing these costs to maintain shelf-space allocations at major retailers.
Brand owners are consolidating supplier panels from 12-15 converters to 3-4 strategic partners with full digital-to-flexo capability suites. This concentration is displacing spot-buy relationships in North American beverage and nutraceutical verticals. The shift is most visible in California and New York, where private-equity-backed brand portfolios are standardizing procurement across portfolio companies.
Sheeted Labels Market Segmentation
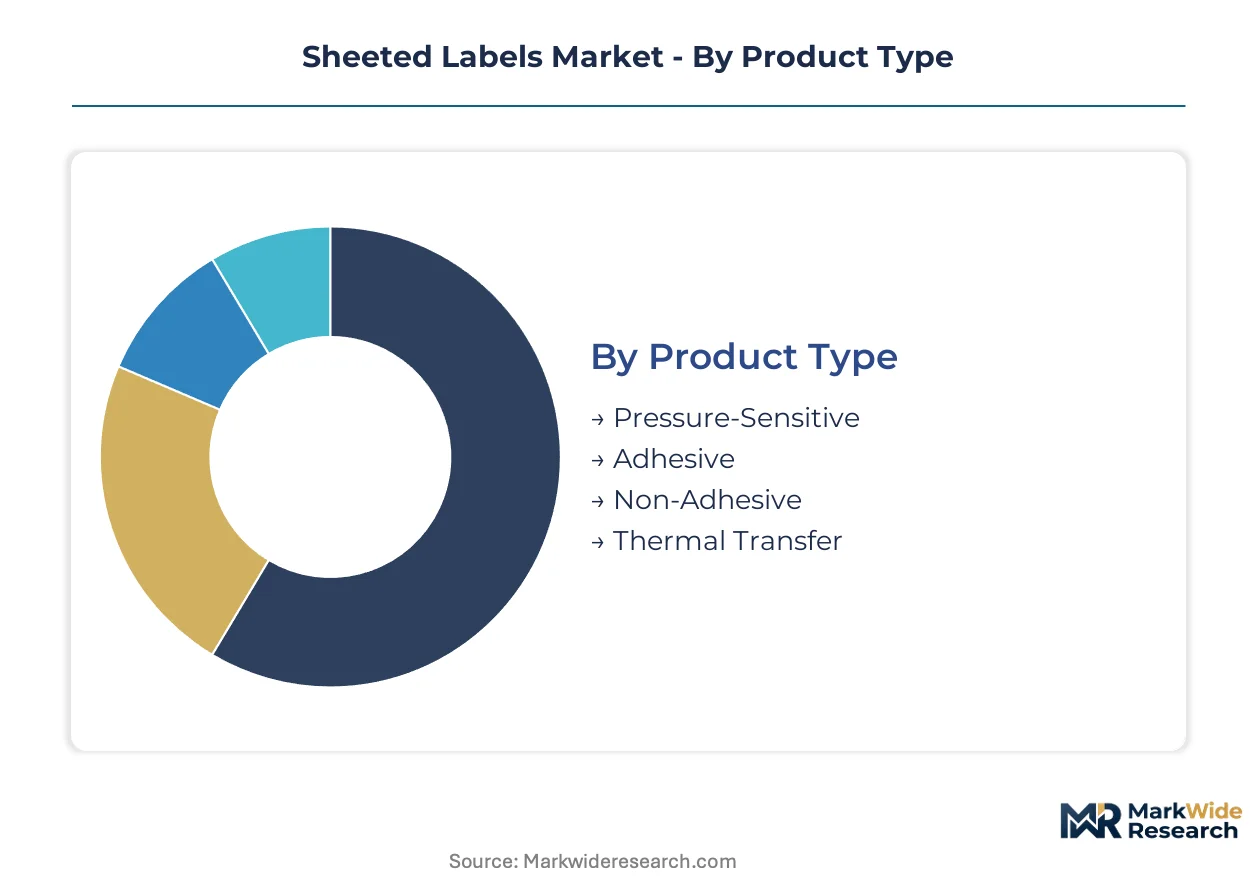
Converters and brand owners configure procurement strategies around four intersecting dimensions that determine specification complexity, compliance burden, and margin structure. Product type and material choices govern line-speed compatibility and recyclability credentials. Industry vertical and application requirements dictate serialization depth and environmental stress resistance.
Product Type:
Cost tier stratification separates commodity formats from premium performance grades, with adhesive chemistry and liner engineering driving the price spread.
- Pressure-Sensitive:Self-adhesive constructions with silicone-coated release liners enable clean application at high line speeds. Food and pharmaceutical packaging lines in Germany and the United States concentrate demand here, driven by rework flexibility and GS1 barcode scan reliability mandates.
- Thermal Transfer:Ribbon-based imaging produces solvent-resistant barcodes for warehouse and cold-chain logistics. Protein processors and dairy distributors are expanding volumes under FDA food traceability infrastructure requirements.
- Adhesive:Permanent and removable tack formulations serve secondary labeling and promotional applications. Craft beverage brands in California rotate seasonal artwork using these formats for short-run flexibility.
- Non-Adhesive:Static-cling and heat-activated alternatives serve temporary promotional and industrial safety marking. Automotive component suppliers specify these for residue-free removal during assembly sequences.
Pressure-Sensitive holds installed capacity. Thermal Transfer is rotating up the share rankings.
Industry Vertical:
Application maturity varies sharply across verticals, with regulatory stringency and SKU velocity determining converter technical service intensity.
- Food & Beverage:Cold-chain logistics and retail branding dominate volume, with lot-level serialization and allergen disclosure requirements compressing procurement cycles. EU Green Deal packaging recyclability targets are accelerating paper-based liner adoption in French and German retail supply chains.
- Pharmaceuticals:Primary and secondary packaging demand ISO 15378 certification and 18-24 month audit qualification periods. Brazilian ANVISA track-and-trace mandates are creating first-mover openings for converters with São Paulo distribution partnerships.
- Retail:Seasonal artwork rotation and private-label proliferation favor digital production workflows. North American craft food segments are adopting cloud-based prepress to collapse proofing cycles.
- Industrial:Chemical resistance and abrasion durability specifications favor polyester substrates and UV-cured adhesives. German automotive component tracking is converging pressure-sensitive formats with UHF RFID inlay integration.
Food & Beverage anchors volume concentration. Pharmaceuticals is climbing the fastest on compliance-driven specification premiums.
Application:
Functional role determines imaging durability requirements and the depth of variable data encoding needed.
- Packaging:Primary label functions spanning product containment integrity and regulatory disclosure. REACH Annex XIV phthalate restrictions are forcing adhesive reformulation across European personal care labeling.
- Branding:Visual differentiation and shelf-impact optimization. Consolidated supplier panels from 12-15 converters down to 3-4 strategic partners are standardizing procurement across private-equity-backed brand portfolios in New York and California.
- Product Identification:Lot codes, expiration dates, and manufacturing origin marks. E-commerce parcel sortation systems are migrating toward thermal-direct substitution, pressuring growth in warehouse applications.
- Inventory Tracking:Warehouse location labels and asset management tags. RFID-inlay integration is opening apparel and automotive component applications previously served by hard tags.
Packaging commands specification authority. Inventory Tracking is gaining share fastest on automation infrastructure buildouts.
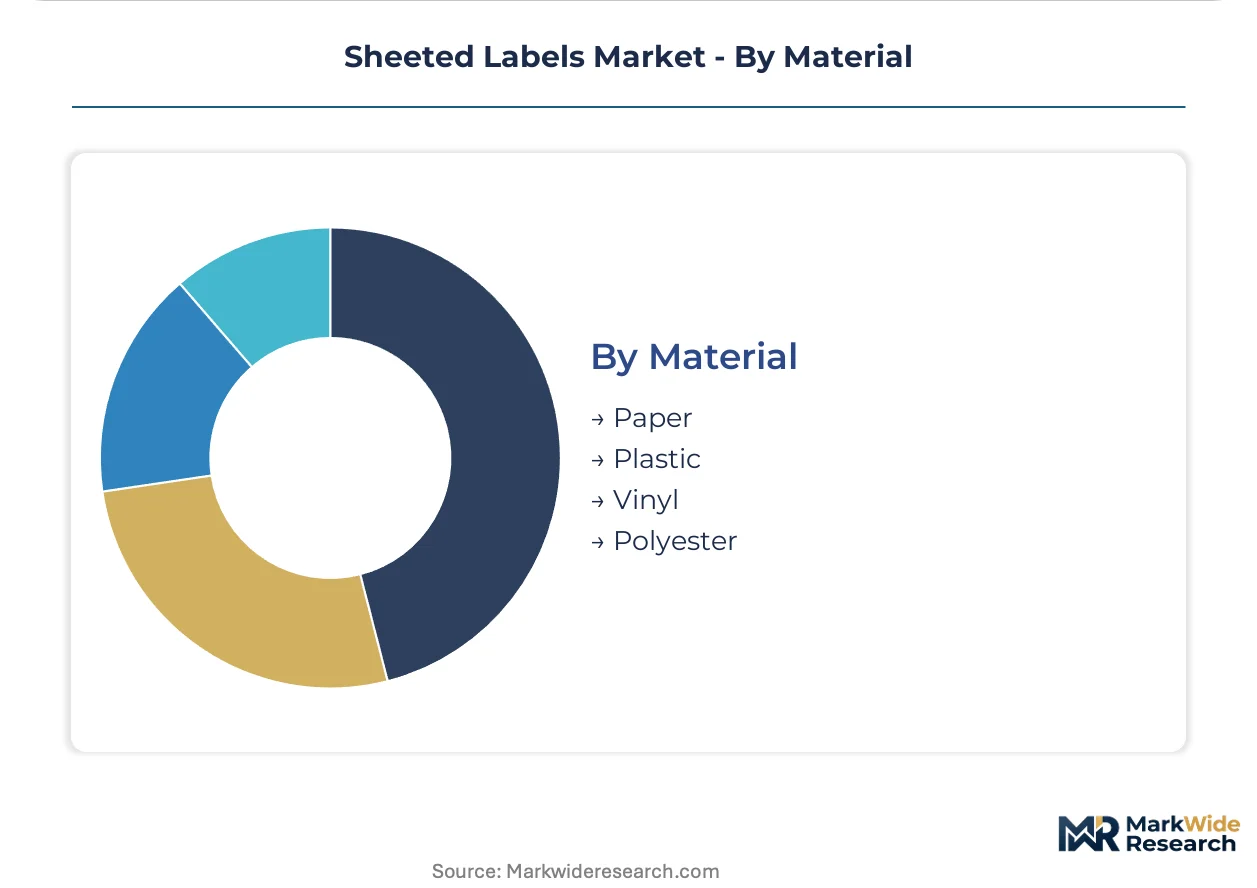
Material:
Substrate selection balances cost position against environmental stress tolerance and end-of-life recyclability credentials.
- Paper:Uncoated and coated stocks retain cost leadership in retail branding and short-life applications. EU mono-material compatibility mandates are accelerating demand for paper-based release liners.
- Polyester:PET films deliver chemical resistance and dimensional stability for industrial and pharmaceutical applications. German and Benelux converters absorb 15-20% raw material cost premiums to maintain shelf-space at premium skincare retailers.
- Plastic:Polypropylene and polyethylene films serve moisture-resistant food packaging. India's PLI scheme for food processing infrastructure is stimulating label demand in Maharashtra and Gujarat manufacturing corridors.
- Vinyl:PVC constructions persist in outdoor durability and curved-surface applications despite recyclability headwinds. Specialized short-run digital production sustains niche positioning for promotional and safety marking.
Paper holds installed capacity. Polyester is rotating up the share rankings on industrial specification migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters capture pricing premiums on REACH-compliant adhesive formulations that Brazilian suppliers cannot yet replicate. This asymmetry shapes procurement patterns across food and pharmaceutical verticals.
Germany
Food traceability mandates and EU Green Deal packaging targets drive specification intensity. ECHA substance authorization timelines extend qualification periods for adhesive tackifiers. The Ruhr industrial corridor hosts concentrated die-cutting capacity serving Benelux skincare brands.
United States
FDA food contact notifications and GS1-128 barcode requirements reshape cold-chain logistics labeling. EPA volatile organic compound limits determine adhesive eligibility. California craft beverage clusters adopt cloud-based prepress to collapse seasonal artwork cycles.
Brazil
ANVISA pharmaceutical serialization mandates create first-mover openings for track-and-trace infrastructure. Production-linked incentives stimulate food processing label demand. São Paulo distribution partnerships anchor converter expansion into serialization-ready formats.
China
Dual carbon goals and evolving GB standards pressure substrate selection toward recyclable mono-materials. SAMR food safety labeling rules tighten lot-code visibility requirements. Yangtze River Delta manufacturing corridors concentrate pressure-sensitive label capacity for export packaging.
India
PLI scheme incentives for food processing infrastructure stimulate label demand in western manufacturing corridors. FSSAI packaging regulations mandate ingredient disclosure clarity. Maharashtra and Gujarat industrial zones attract converter investments for domestic supply chain localization.
Sheeted Labels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation and substrate engineering. The vendor base stratifies across three capability tiers: multinational converters with full digital-to-flexo suites, regional specialists with die-cutting depth, and niche players with adhesive chemistry expertise. Consolidation pressure intensifies as brand owners reduce supplier panels from twelve-to-fifteen relationships down to three-to-four strategic partnerships. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among North American converters, Consolidated Label and Hub Labels exemplify contrasting strategic archetypes. Consolidated Label occupies a position emphasizing in-house die-cutting capabilities for premium packaging accounts. Hub Labels represents specialized short-run digital production sustainability. Rebsons Labels anchors Southern African supply chains through localized adhesive formulation expertise.
| Leading Market Players |
|---|
| RGS Labels |
| Rebsons Labels |
| Hub Labels |
| Consolidated Label |
| New York Label & Box Works |
| Coding Solutions |
| Performance Label Company |
| Blanco |
| Ready Print Limited |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing corridors concentrate pressure-sensitive label capacity for export packaging, giving Chinese converters leverage over spot pricing in European and North American procurement cycles. This geographic concentration of die-cutting and adhesive coating infrastructure creates asymmetry in contract negotiations, particularly when silicone release liner supply tightens.
Pricing Analysis
The customization-premium spread separates configured-to-order specifications from standard catalog formats by 15-25% at the contract level. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15378 certification status and lot-level serialization capability. Cost compression in thermal transfer grades is intensifying because direct thermal substitution in e-commerce logistics erodes warehouse application volumes. Craft beverage brands in California exhibit highest price sensitivity, while pharmaceutical primary packaging buyers absorb specification premiums to secure audit-qualified supply.
Supply Chain Analysis
Upstream feedstock dynamics for silicone-coated release liners and hot-melt adhesive tackifiers center on petrochemical derivatives and specialty paper substrates. Germany, China, and the United States anchor global manufacturing capacity for rotary die-cutting equipment and coating lines. Raw material dependencies include silicone emulsions, synthetic rubber tackifiers, and PET film substrates. Single-source vulnerability for pharmaceutical-grade release liners exposes converters to force majeure disruption. Distribution runs through converter-direct relationships with multinational brand owners, bypassing traditional distributor layers in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across digital production workflows and regional compliance specializations creates niche opportunities for specialists with adhesive chemistry or serialization infrastructure depth. SKU proliferation in craft food and beverage segments multiplies the addressable entry points for targeted service models.
For Market Incumbents: Insulate core pharmaceutical and food accounts through captive adhesive formulation capabilities and ISO 15378 certification maintenance. Backward integration into release liner coating reduces exposure to silicone supply concentration. Defensive capacity additions in São Paulo and Maharashtra manufacturing corridors preempt emerging competitor positioning for ANVISA and PLI-scheme demand waves.
For New Entrants and Emerging Players: Pursue cloud-based prepress service models targeting North American craft beverage brands with seasonal artwork rotation needs. RFID-inlay integration for automotive component tracking represents the most penetrable white-space application. A technical service-heavy go-to-market angle differentiates against incumbent converter-distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with hybrid digital-to-flexo capability suites and established e-commerce storefront infrastructure. Long-term viability rests on supplier panel consolidation momentum among private-equity-backed brand portfolios. The signal to watch is extended producer responsibility framework implementation timelines in European markets, which would accelerate specification shifts toward recyclable mono-material constructions.
| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Formulation Backward Integration | Captive supply of REACH-compliant hot-melt formulations reduces raw material cost volatility exposure. |
| Cloud-Based Prepress Platform Deployment | Virtualized proofing workflows collapse lead times for craft beverage seasonal artwork cycles. |
| RFID-Inlay Integration Capability | Convergence with UHF chips opens apparel and automotive tracking previously served by hard tags. |
| São Paulo Distribution Partnership | ANVISA track-and-trace mandates create first-mover positioning for serialization-ready formats. |
| ISO 15378 Certification Investment | Pharmaceutical primary packaging qualification locks in 12-18 month audit cycles and premium pricing. |
Research Methodology
A standing panel of label converter operations directors, brand owner packaging procurement managers, adhesive formulation chemists, and digital press technology specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA food contact substance notifications, ECHA REACH substance authorization databases, ANVISA regulatory filings, and customs trade flow data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Scenario-bracketing around regulatory implementation timelines and substrate substitution elasticities bounded the projection range across the analysis window. Segmentation dimensions modeled include product type, material substrate, industry vertical, application function, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed capacity expansions and brand owner procurement pattern shifts. Forecast inputs incorporated EU Green Deal packaging recyclability target compliance costs and India PLI scheme infrastructure stimulus effects.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, currency volatility in emerging market manufacturing corridors, or logistics cost spikes would shift the trajectory. Quarterly review of ECHA substance authorization timelines, ANVISA implementation deadlines, and extended producer responsibility framework announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Glue Applied Automotive Labels Market
Labels
Wet Glue Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Wrap Around Labels Market
Labels
Global Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Linerless Labels Market
Labels
Print Label Market
Labels
Global Laminated Labels Market
Labels
Global Automotive Labels Market
Labels
Industrial Label Printers Market
Labels
Tags Market
Labels
Booklet Labels Market
Labels
Non-Adhesive Tags Market
Labels
Retro-Reflective Labels Market