
 Global Starter Fertilizers Market | 2026-2036
Global Starter Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Starter Fertilizers Market Foresight
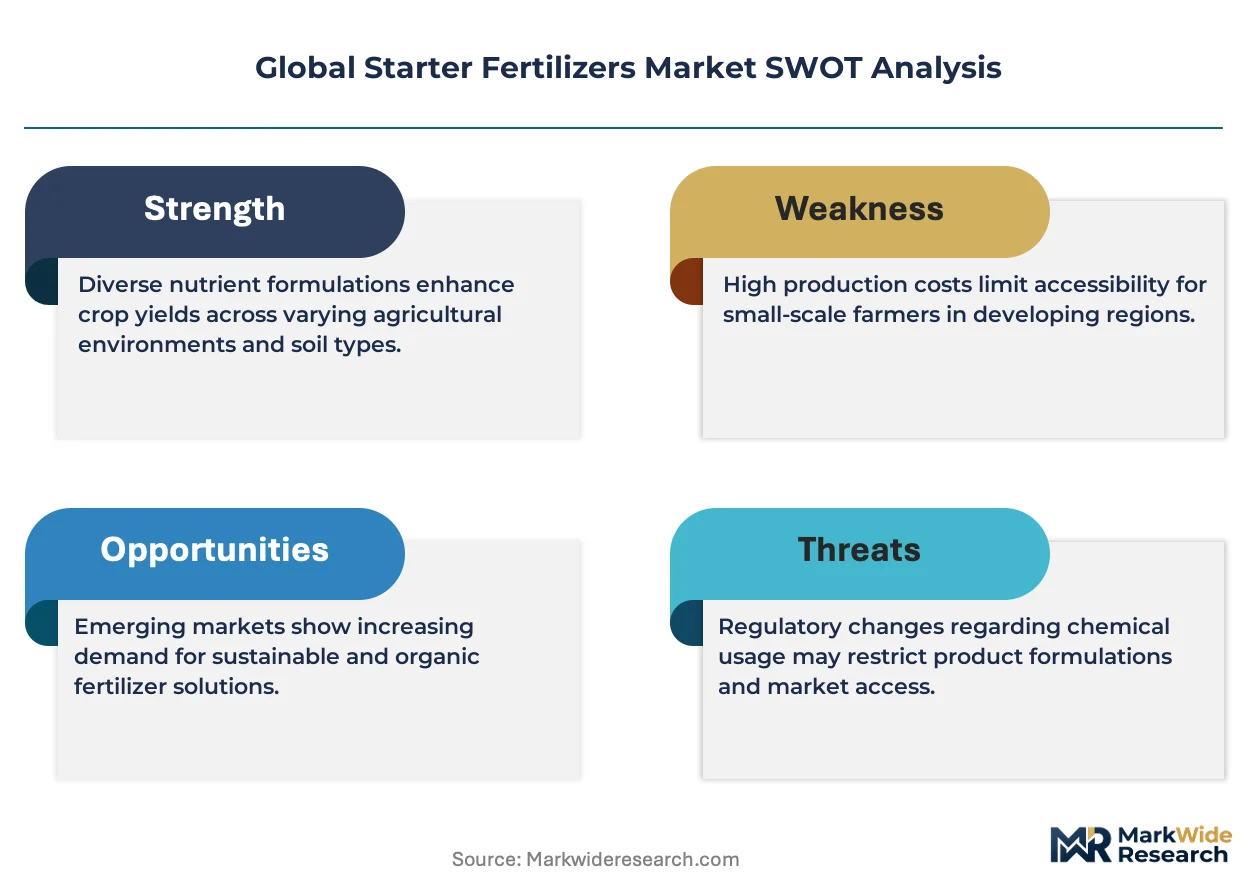
The capital-intensity divergence between integrated phosphate miners and regional blenders is collapsing as input cost volatility erodes margin buffers for non-integrated operators. Yara International ASA leverages its upstream ammonia position to sustain cost-advantaged nitrogen-phosphorus-potassium blend production across Baltic and North American corridors. Nutrien Ltd. anchors its starter fertilizer portfolio through captive potash and phosphate rock access, while The Mosaic Company dominates granular phosphate capacity in Florida and Saskatchewan mining districts.
Starter fertilizers are nutrient-dense formulations applied in proximity to seeds at planting, typically containing 10-20% available phosphorus as orthophosphate to fuel early root establishment before soil reserves mobilize. Monoammonium phosphate concentrates margin pools due to its low salt index and superior seed safety profile in high-value row crops. Diammonium phosphate competes aggressively in bulk grain systems where band application infrastructure supports higher salt tolerance, while nitrogen-phosphorus-potassium blends are capturing share among precision planting operations that demand single-pass efficiency.
EPA water quality standards under the Clean Water Act constrain phosphorus loading in Chesapeake Bay and Mississippi River watersheds, directly shaping starter fertilizer placement protocols and formulation choices. REACH registration requirements in Europe mandate granular disintegration rate disclosures that affect import eligibility for non-EU blenders. Brazil's national fertilizer regulator enforces heavy metal limits on imported phosphate rock that filter supplier qualification for the Cerrado market. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost structure of ammonia-derived starter products before committing to long-term offtake contracts.
Market Dynamics
Precision planting equipment penetration among contract growers is collapsing the historical trade-off between application efficiency and seed safety, forcing formulation chemistry to adapt to narrower placement tolerances and variable-rate delivery systems.
Growth Catalysts
- EU Green Deal nutrient protocols:Phosphorus runoff limits across member states are mandating band-applied starter programs that reduce environmental loading while maintaining yield targets.
- Brazil's Cerrado soybean intensification:Phosphate-heavy starter formulations anchor expansion zones where native soil fertility cannot support commercial production without supplemental orthophosphate at planting.
- Controlled-release coating technologies:Polymer-encapsulated granules extend nutrient availability windows, enabling single-pass application that matches precision planter operating speeds.
Market Restraints
- Ammonia price volatility:Natural gas feedstock fluctuations compress margin buffers for non-integrated nitrogen-phosphorus-potassium blenders lacking captive ammonia supply.
- Florida phosphate rock concentration:Granular phosphate capacity geographic clustering creates supply vulnerability to hurricane disruption and water use permitting delays.
- Organic matter substitution:Compost-based soil amendments compete for capital in regenerative agriculture systems, diverting investment from synthetic starter programs.
Strategic Opportunities
- Ukraine Black Sea corridor recovery:Post-conflict reconstruction of wheat and corn production creates demand for orthophosphate-heavy establishment programs on degraded soils.
- Carbon border adjustment mechanisms:EU CBAM implementation favors low-carbon ammonia sourcing, rewarding producers with renewable hydrogen feedstock integration.
- Drone-based micro-granule application:Aerial distribution platforms bypass ground compaction constraints in no-till systems, opening placement precision previously unattainable.
Industry Challenges
- REACH registration timelines:ECHA granular disintegration rate disclosure requirements extend product approval cycles for non-EU blenders seeking import eligibility.
- Precision agriculture technician scarcity:Variable-rate equipment calibration and prescription map development require skills absent in traditional agronomy training pipelines.
- Legacy blending asset retrofit costs:Existing regional facilities lack automated batching precision for micronutrient inclusion at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Starter Fertilizers Market |
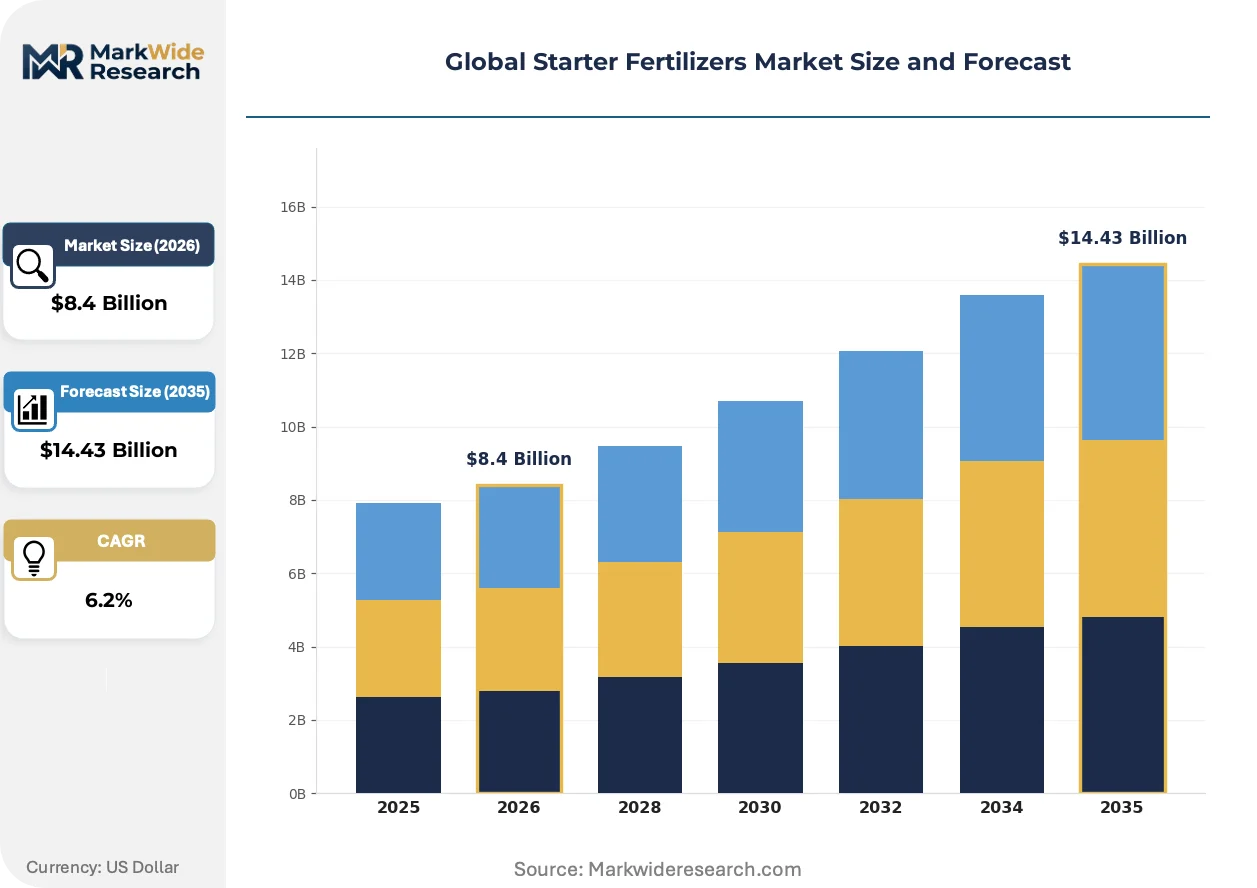
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoammonium Phosphate, Diammonium Phosphate, Nitrogen-Phosphorus-Potassium Blends, Calcium Ammonium Nitrate, Urea Phosphate Crop Type: Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Fiber Crops, Plantation Crops Application Method: Seed Treatment, Band Application, Side Dressing, Foliar Spray, Soil Incorporation End User: Contract Growers, Smallholder Farmers, Agricultural Cooperatives, Agrochemical Companies, Organic Farms |
| Companies Covered | Yara International ASA, Nutrien Ltd., The Mosaic Company, CF Industries Holdings, Inc., ICL Group Ltd, Syngenta, UPL, Nufarm Agri Solutions, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Starter Fertilizers Market Shifts & Advancements
Formulation chemistry and application hardware are converging to eliminate the historical separation between seed safety and nutrient density, compressing product development cycles and reshaping competitive differentiation.
Micro-granule starter formulations with sub-1mm particle sizing are supplanting conventional 2-4mm granular products in high-speed precision planting operations. Row-crop contractors in Iowa and Illinois are adopting these formulations at accelerating rates to match 15-mph planter speeds without seedling salt injury. The technology is supplanting traditional diammonium phosphate bulk programs by enabling in-furrow placement previously considered too risky for germination.
EPA Clean Water Act phosphorus loading constraints in Chesapeake Bay and Mississippi River watersheds are mandating 4R nutrient stewardship protocols that specify placement timing, formulation type, and buffer distances. Fertilizer retailers must now document starter product selection rationale to maintain NRCS cost-share eligibility for grower customers. Band application infrastructure investment concentrates in Minnesota and Wisconsin watersheds facing TMDL enforcement deadlines.
Outcome-based agronomic service contracts are displacing transactional product sales among 10,000+ acre operations in Mato Grosso and Goiás. Brazilian distributors bundle starter formulation guarantees with satellite-verified emergence rates, transferring agronomic risk from grower to supplier. This procurement model compression is most visible in soybean-forward systems where establishment failure carries replanting costs exceeding input savings.
Global Starter Fertilizers Market Segmentation
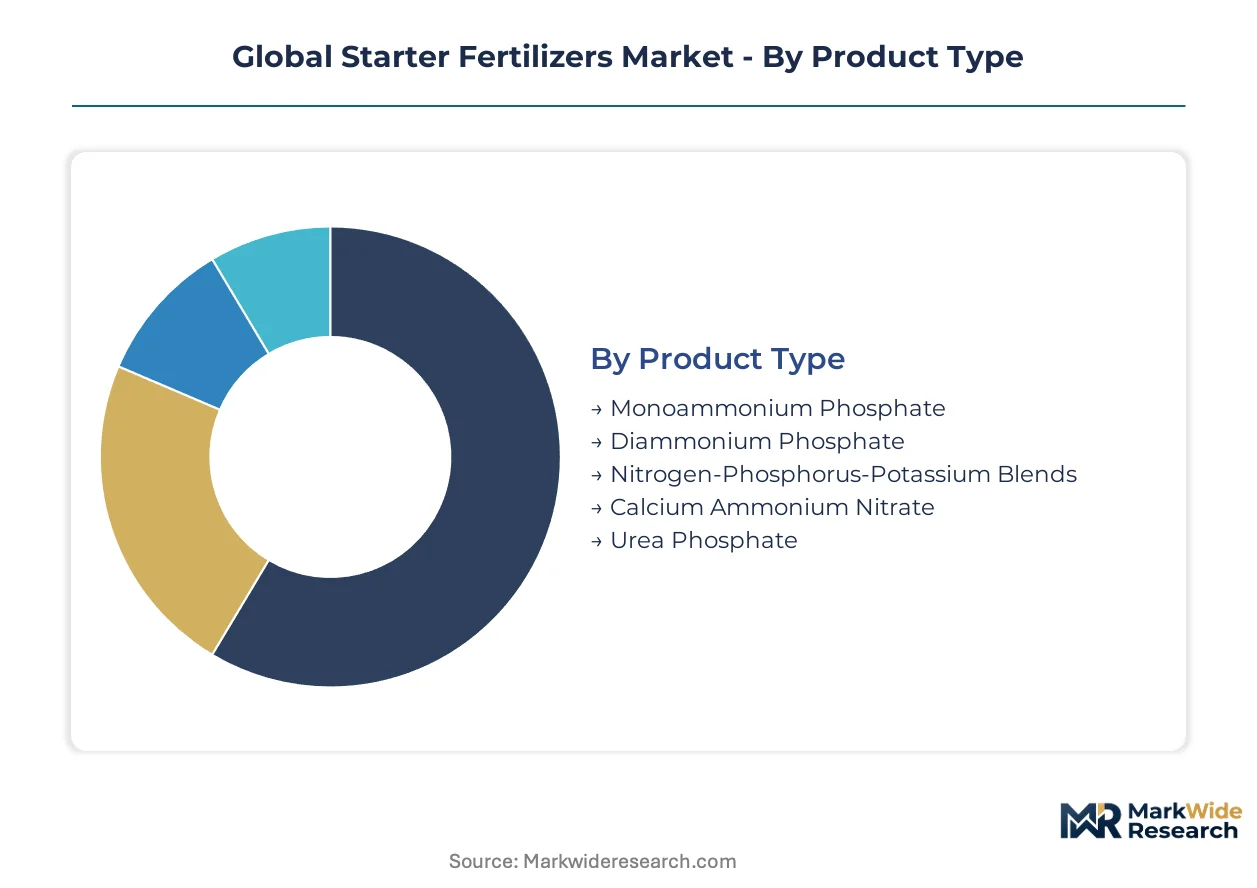
Starter fertilizer segmentation reveals distinct technology-application pairings that determine formulation chemistry, placement protocols, and margin architecture across agricultural systems. Understanding these divisions exposes where precision agriculture investments concentrate and which customer segments command premium pricing for seed-safe, high-density nutrient delivery.
Product Type:
Domestic production clusters anchor phosphate-heavy formulations in mining-adjacent regions, while nitrogen-phosphorus-potassium blending capacity disperses globally to serve import-dependent agricultural corridors.
- Monoammonium Phosphate:Low salt index and superior seed safety profile make this the default choice for in-furrow placement in high-value row crops. Demand concentrates in Iowa and Illinois precision planting zones where 15-mph planter speeds require germination protection. MAP formulations dominate contract grower procurement in these regions due to their compatibility with variable-rate delivery systems.
- Diammonium Phosphate:Higher nitrogen content and aggressive pricing position this for bulk grain systems with established band application infrastructure. Brazilian Cerrado expansion zones favor DAP for soybean establishment programs where soil phosphorus reserves are critically depleted and salt tolerance is manageable through placement depth.
- Nitrogen-Phosphorus-Potassium Blends:Single-pass efficiency drives adoption among precision planting operations seeking complete nutrition in one application.
- Calcium Ammonium Nitrate:Rapid nitrogen availability suits early-season cereals in European Union member states with strict ammonium nitrate security protocols.
- Urea Phosphate:Acidic reaction products enable phosphorus solubility in alkaline soils across Mediterranean and Middle Eastern production zones.
Monoammonium Phosphate commands the established base. The steepest expansion runs through Nitrogen-Phosphorus-Potassium Blends.
Crop Type:
Volume concentration follows commodity crop economics, with oilseed premiums supporting higher input intensity than bulk grain systems allow.
- Cereals & Grains:Wheat and corn establishment programs represent the foundational volume segment, with starter application standard in North American and Black Sea production zones. Band placement dominates due to lower seed value and tolerance for modest salt exposure. Ukrainian reconstruction demand is accelerating orthophosphate-heavy programs on degraded soils.
- Oilseeds & Pulses:Soybean and canola command premium starter investment due to high establishment failure costs and phosphorus hunger during nodulation. Brazilian Mato Grosso and Goiás operations above 10,000 hectares now bundle formulation guarantees with satellite-verified emergence rates, transferring agronomic risk from grower to supplier.
- Fruits & Vegetables:High-value produce justifies micronutrient-inclusive formulations with precise placement requirements.
- Fiber Crops:Cotton establishment programs in Texas and Gujarat rely on starter phosphorus for root system development in sandy soils.
- Plantation Crops:Oil palm and rubber replanting cycles in Indonesia and Malaysia generate periodic demand spikes for heavy phosphate applications.
Cereals & Grains anchor global volume. Oilseeds & Pulses are climbing the fastest as precision agriculture penetration deepens.
Application Method:
Equipment capital requirements stratify adoption, with in-furrow technologies concentrating among large-scale contractors and broadcast methods persisting in smallholder systems.
- Band Application:Placement 2-4 inches below and beside the seed row remains the dominant commercial method, balancing nutrient proximity with salt avoidance. Minnesota and Wisconsin watersheds facing EPA TMDL enforcement deadlines are concentrating infrastructure investment here to satisfy 4R nutrient stewardship protocols. Retailers must document product selection rationale to maintain NRCS cost-share eligibility.
- Seed Treatment:Micro-granule formulations with sub-1mm particle sizing are displacing conventional products in high-speed precision operations. Iowa and Illinois contractors adopt these at accelerating rates to match planter speeds without seedling injury, supplanting traditional diammonium phosphate bulk programs.
- Side Dressing:Split application timing suits nitrogen-heavy programs in regions with leaching risk.
- Foliar Spray:Corrective phosphorus delivery addresses mid-season deficiency in high-value horticulture.
- Soil Incorporation:Pre-plant tillage-based application persists in conventional systems lacking precision planting equipment.
Band Application holds the volume majority. Seed Treatment is gaining share fastest as micro-granule chemistry matures.
End User:
Scale and procurement sophistication determine formulation access, with integrated operations capturing precision technologies unavailable to fragmented smallholder channels.
- Contract Growers:Large-scale row-crop contractors above 5,000 acres drive precision agriculture adoption, demanding variable-rate compatible formulations and outcome-based service contracts. Their equipment penetration is collapsing the historical trade-off between application efficiency and seed safety, forcing chemistry adaptation to narrower placement tolerances.
- Agricultural Cooperatives:Consolidated purchasing power enables blended product access for member farms, though legacy blending assets often lack automated batching precision for micronutrient inclusion at commercial scale.
- Smallholder Farmers:Price-sensitive demand concentrates in bulk diammonium phosphate through informal distribution networks.
- Agrochemical Companies:Integrated input providers bundle starter formulations with crop protection portfolios.
- Organic Farms:Compost-based amendments compete for capital, diverting investment from synthetic starter programs in regenerative systems.
Contract Growers dominate premium formulation demand. Agricultural Cooperatives are expanding most quickly as consolidation accelerates across production regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Starter fertilizer consumption patterns diverge sharply across agricultural systems, with precision planting corridors in North America demanding seed-safe formulations while tropical expansion zones prioritize bulk phosphate loading for soil building.
United States
Iowa and Illinois contract growers drive micro-granule adoption for 15-mph planter compatibility, while Minnesota and Wisconsin watersheds face EPA TMDL enforcement deadlines that mandate 4R nutrient stewardship documentation. NRCS cost-share eligibility now requires retailers to justify starter product selection rationale. The Corn Belt's precision agriculture penetration is collapsing the historical trade-off between application efficiency and seed safety.
Brazil
Mato Grosso and Goiás operations above 10,000 hectares bundle formulation guarantees with satellite-verified emergence rates, transferring agronomic risk from grower to supplier. ANVISA enforces heavy metal limits on imported phosphate rock that filter supplier qualification for Cerrado market entry. The expansion zones rely on phosphate-heavy starter programs where native soil fertility cannot support commercial soybean production without supplemental orthophosphate at planting.
Germany
EU Green Deal nutrient protocols are tightening phosphorus runoff limits across member states, mandating band-applied starter programs that reduce environmental loading while maintaining yield targets. ECHA REACH registration requirements demand granular disintegration rate disclosures that extend product approval cycles for non-EU blenders. The Baltic corridor serves as a blending hub for nitrogen-phosphorus-potassium formulations serving Central European precision agriculture operations.
China
The country's national fertilizer regulator monitors ammonia-derived starter products as carbon border adjustment mechanisms reshape cost structures for long-term offtake contracts. Yangtze River Delta precision planting zones are adopting variable-rate delivery systems that demand formulation chemistry adaptation to narrower placement tolerances. Domestic phosphate rock processing capacity concentrates in mining-adjacent provinces serving both domestic row-crop establishment and export blending operations.
Canada
Saskatchewan potash and phosphate mining districts anchor captive supply positions for integrated producers serving North American prairie grain systems. Prairie Provinces wheat and canola establishment programs represent foundational volume for band-applied starter formulations, with lower seed value tolerating modest salt exposure compared to high-value row crops. Provincial environmental agencies are aligning phosphorus management protocols with emerging federal carbon accounting frameworks for agricultural inputs.
Global Starter Fertilizers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with upstream phosphate rock and ammonia access determining margin sustainability amid feedstock volatility. The market structure rewards backward integration into mining and gas feedstocks while penalizing non-integrated blenders exposed to input cost swings. Three archetypes dominate: captive-resource majors with full supply chain control, regional blenders with distribution density, and precision formulation specialists serving high-speed planting systems. Competitive moves concentrate on portfolio diversification into micronutrient-inclusive blends and geographic expansion through distribution partnerships in emerging agricultural corridors.
Among integrated majors with captive resource positions, Yara International ASA, Nutrien Ltd., and The Mosaic Company exemplify the upstream-control archetype that sustains cost-advantaged production across Baltic, North American, and Florida-Saskatchewan mining districts. These entities represent the resource-anchored tier where ammonia and phosphate rock access insulates margin buffers from natural gas feedstock fluctuations. Regional blending operations lacking such integration occupy a more vulnerable position as carbon border adjustment mechanisms and REACH registration timelines reshape import eligibility and cost structures for cross-border formulation trade.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien Ltd. |
| The Mosaic Company |
| CF Industries Holdings, Inc. |
| ICL Group Ltd |
| Syngenta |
| UPL |
| Nufarm Agri Solutions |
| Corteva Agriscience |
| Others |
Supply & Pricing Matrix
EU REACH registration requirements gate both supplier qualification and price differentiation simultaneously, extending product approval cycles for non-EU blenders while rewarding compliant operators with premium positioning in band-applied starter formulations. Carbon border adjustment mechanisms now reshape cost structures for ammonia-derived products, compressing margin buffers for non-integrated nitrogen-phosphorus-potassium blenders lacking captive hydrogen feedstock access.
Pricing Analysis
Long-term offtake contracts dominate procurement above 10,000 hectares in Brazil's Mato Grosso and Goiás, while spot transactions persist for smallholder channels. Pricing stratifies across premium, standard, and economy tiers based on seed safety certification and micronutrient inclusion density. Cost compression in nitrogen-phosphorus-potassium blends is intensifying because natural gas feedstock volatility erodes non-integrated operator margins. Contract growers above 5,000 acres exhibit least price sensitivity due to outcome-based service bundling, while smallholder farmers in informal distribution networks drive aggressive diammonium phosphate spot market competition.
Supply Chain Analysis
Florida phosphate rock concentration creates hurricane exposure and water use permitting delays that threaten granular phosphate capacity. Supply draws from mining-adjacent districts in Florida, Saskatchewan, and Morocco's OCP corridor, with ammonia sourcing tethered to Gulf Coast and Baltic petrochemical complexes. Raw material dependencies center on phosphate rock, natural gas feedstock, and potash from Belarusian and Canadian mines. Single-source vulnerability runs through Florida's Bone Valley mining district where water discharge regulations constrain expansion timelines. Distribution runs through regional blending facilities serving Corn Belt precision planting corridors and Cerrado expansion zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision planting equipment penetration among contract growers signals early-cycle expansion, with micro-granule chemistry adaptation creating differentiated value capture opportunities ahead of mainstream formulation commoditization.
For Market Incumbents: Secure captive ammonia positions through backward integration into Gulf Coast or Baltic hydrogen feedstock corridors before carbon border adjustment mechanisms fully phase in. Defend margin buffers by retrofitting legacy blending assets for automated micronutrient batching precision, addressing the technician scarcity that constrains variable-rate prescription map development. For New Entrants and Emerging Players: Differentiate on drone-based micro-granule application systems that bypass ground compaction constraints in no-till soybean and corn establishment programs. White-space concentration sits with aerial distribution platforms for Iowa and Illinois contractors seeking 15-mph planter speed compatibility without seedling salt injury. Target outcome-based agronomic service contracts in 10,000+ acre Brazilian operations where satellite-verified emergence guarantees transfer replanting risk from grower to supplier. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision formulation segments requiring polymer-encapsulated controlled-release coating technologies. Long-term viability favors integrated majors with upstream phosphate rock and ammonia access that insulate margin buffers from feedstock volatility. Acquisition target archetype: regional blenders with distribution density in Corn Belt watersheds facing EPA TMDL enforcement deadlines. Signal to watch: REACH registration timeline extensions for non-EU blenders crossing 18-month approval cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive hydrogen feedstock access insulates margin buffers from EU CBAM cost compression. |
| Micro-Granule Formulation Scale-Up | Sub-1mm particle sizing enables 15-mph planter compatibility for Iowa and Illinois contractors. |
| Outcome-Based Service Contract Bundling | Satellite-verified emergence guarantees transfer replanting risk in Brazilian Mato Grosso operations. |
| Automated Micronutrient Batching Retrofit | Legacy blending assets gain precision agriculture technician efficiency for variable-rate delivery. |
| Drone-Based Aerial Distribution Partnership | Aerial platforms bypass ground compaction constraints in no-till Chesapeake Bay watershed systems. |
Research Methodology
Cross-validation between primary interviews with agronomists, precision agriculture technicians, fertilizer procurement managers, and blending facility operators anchors the qualitative findings against secondary validation from EPA water quality filings, ECHA REACH registration databases, ANVISA heavy metal limit disclosures, and Brazilian national fertilizer regulator import records. Bottom-up triangulation across product type, crop type, application method, and end user segmentation converges with top-down demand modeling from agricultural census data and precision planter equipment deployment statistics.
Sensitivity analysis frames volume and value outputs across the projection horizon, with segmentation dimensions spanning formulation chemistry grade, placement technology compatibility, and regional regulatory cluster intensity. CAGRs derive from fitted growth curves applied to historical adoption patterns in precision planting corridors and Cerrado expansion zones. Industry-specific forecast inputs include ammonia price volatility indices and phosphate rock mining capacity utilization rates from Florida and Saskatchewan districts.
Decision-makers should treat outputs as directional under assumptions of sustained precision agriculture equipment penetration and stable EU Green Deal nutrient protocol enforcement; material deviation in natural gas feedstock costs or REACH registration timeline extensions would warrant model refresh. Revision becomes warranted when carbon border adjustment mechanism implementation crosses thresholds that restructure ammonia-derived product cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Global Urea Market
Fertilizers
South America Fertilizers Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
France Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market