
 Europe Liquid Fertilizers Market | 2026-2036
Europe Liquid Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Liquid Fertilizers Market Foresight
CE marking under the EU Fertilizing Products Regulation is unwinding market access for non-compliant blenders and importers. Yara International ASA leverages its integrated ammonia-to-nutrient network across Nordic and Baltic production sites. EuroChem anchors its position through captive phosphate rock sourcing and deep formulation expertise in water-soluble NPK grades.
Europe liquid fertilizers comprise aqueous or suspension nutrient solutions engineered for precision delivery via fertigation, foliar spray, or direct soil injection, typically formulated with nitrogen contents ranging from twenty-eight to thirty-two percent by weight for urea-ammonium nitrate solutions. These products serve commercial agriculture by enabling calibrated nutrient timing that matches crop uptake curves and reduces field-level nutrient losses. Urea and ammonium nitrate formulations dominate volume flows across the region's open-field cereal operations, while specialty nutrients capture disproportionate margin pools in high-value greenhouse and permanent crop systems. Application through greenhouse and protected-horticulture channels represents the fastest-expanding demand vector, driven by substrate-based cultivation expansion in the Netherlands and Almería.
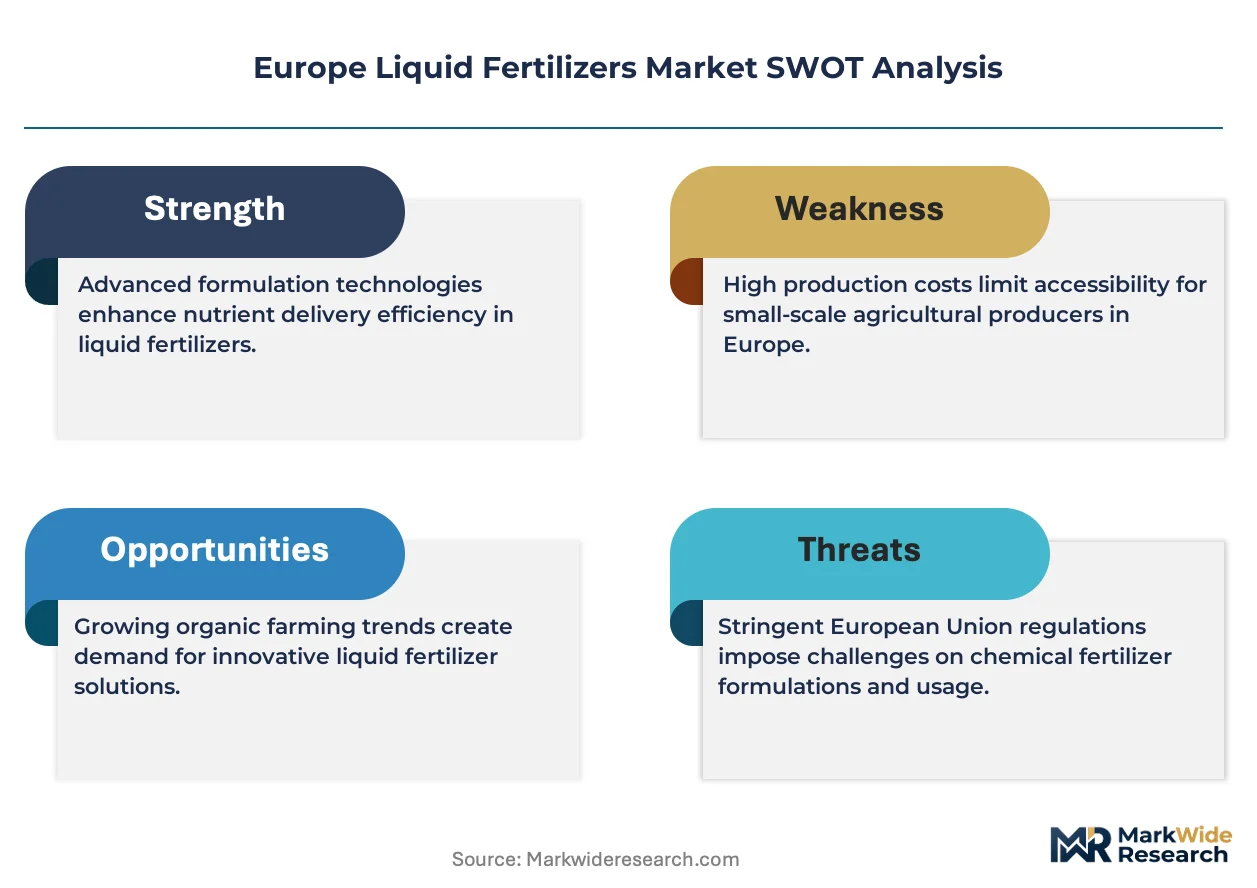
EMA and national competent authorities under the EU Fertilizing Products Regulation set cadmium limits and labeling standards that determine which phosphate-based liquids gain market access across member states. REACH compliance and the EU Green Deal's nutrient-loss reduction targets are forcing reformulation toward lower-carbon production pathways and enhanced-efficiency additives. Stakeholders must monitor evolving cadmium threshold debates and carbon-border adjustment mechanics to anticipate which production configurations retain cost-competitive access to European growers.
Market Dynamics
CE marking requirements under the EU Fertilizing Products Regulation are forcing blenders and importers to reconfigure supply chains, consolidating market access around compliant producers while marginalizing non-certified operators across member states.
Growth Catalysts
- EU Green Deal nutrient-loss mandates:The Farm to Fork Strategy's reduction targets are accelerating replacement of granular systems with precision liquid delivery in France's cereal belt and the Netherlands' greenhouse cluster.
- Fertigation infrastructure expansion:Specialty crop growers in Spain's Almería province and Italy's Po Valley are retrofitting irrigation networks to accommodate water-soluble NPK grades.
- Enhanced-efficiency additive adoption:Urease and nitrification inhibitors are gaining traction in urea-ammonium nitrate formulations, enabling growers to synchronize nutrient release with crop uptake curves.
Market Restraints
- Natural gas price volatility:Ammonia synthesis costs fluctuate with TTF hub pricing, compressing margins for nitrogen-based liquid producers without backward integration into feedstock supply.
- Phosphate rock concentration:Dependence on Moroccan and Russian phosphate reserves exposes European blenders to supply disruption and cadmium content variability.
- REACH compliance burden:Registration, evaluation, and authorization requirements for novel additives extend product development timelines and elevate fixed costs for specialty formulation entrants.
Strategic Opportunities
- Poland's underpenetrated arable sector:Large-scale cereal operations in Greater Poland Voivodeship remain reliant on conventional granular application, creating conversion potential for fertigation system suppliers.
- Carbon-border adjustment positioning:The CBAM's phased implementation favors domestic and near-shore ammonia producers with verified low-carbon production pathways.
- Biostimulant-liquid convergence:Integration of seaweed extracts and microbial inoculants into suspension fertilizers opens premium positioning in organic-transitioning permanent crop systems.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-soluble NPK stability and compatibility testing concentrates among aging specialists in Germany and the Netherlands, constraining R&D expansion.
- CE marking timeline compression:Harmonized standard updates for cadmium limits and labeling requirements force rapid product re-registration, straining regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Liquid Fertilizers Market |
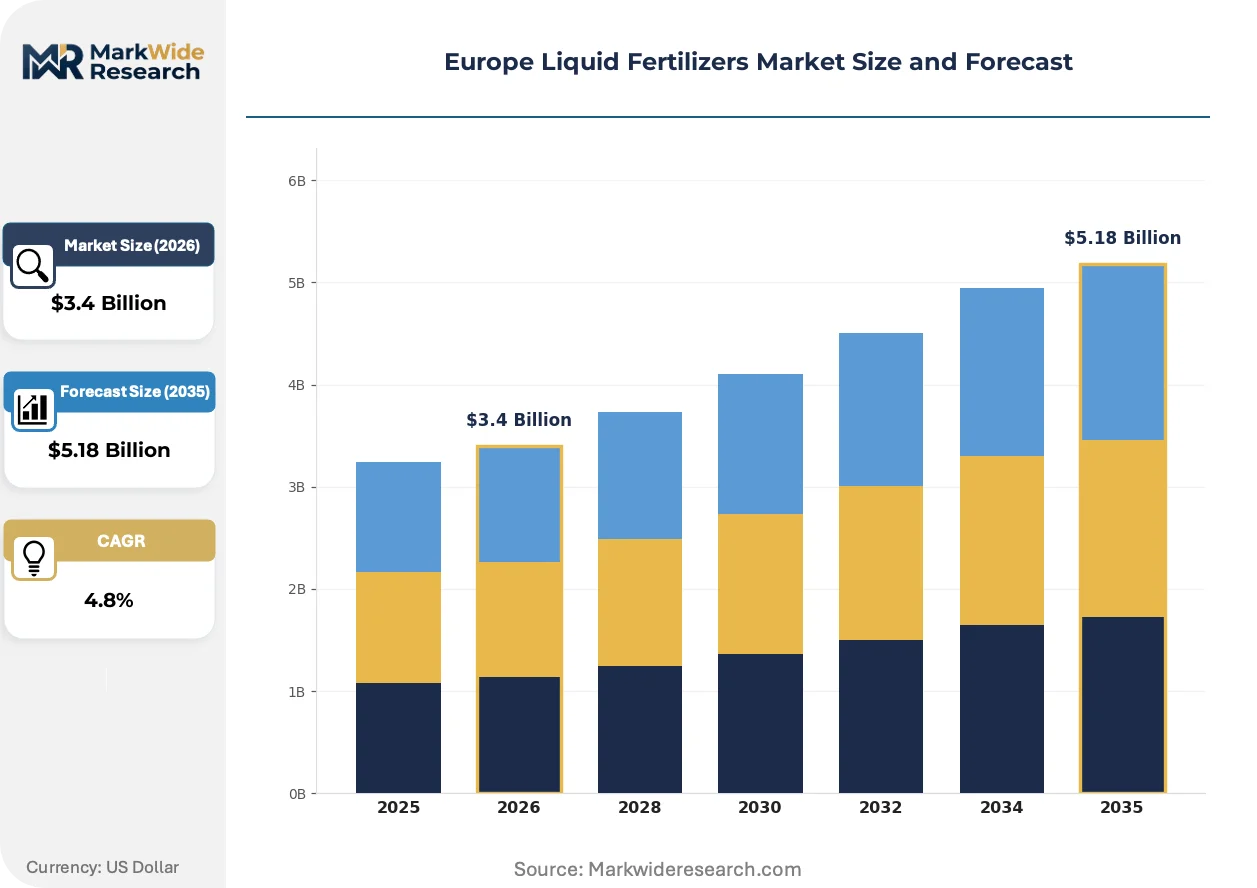
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
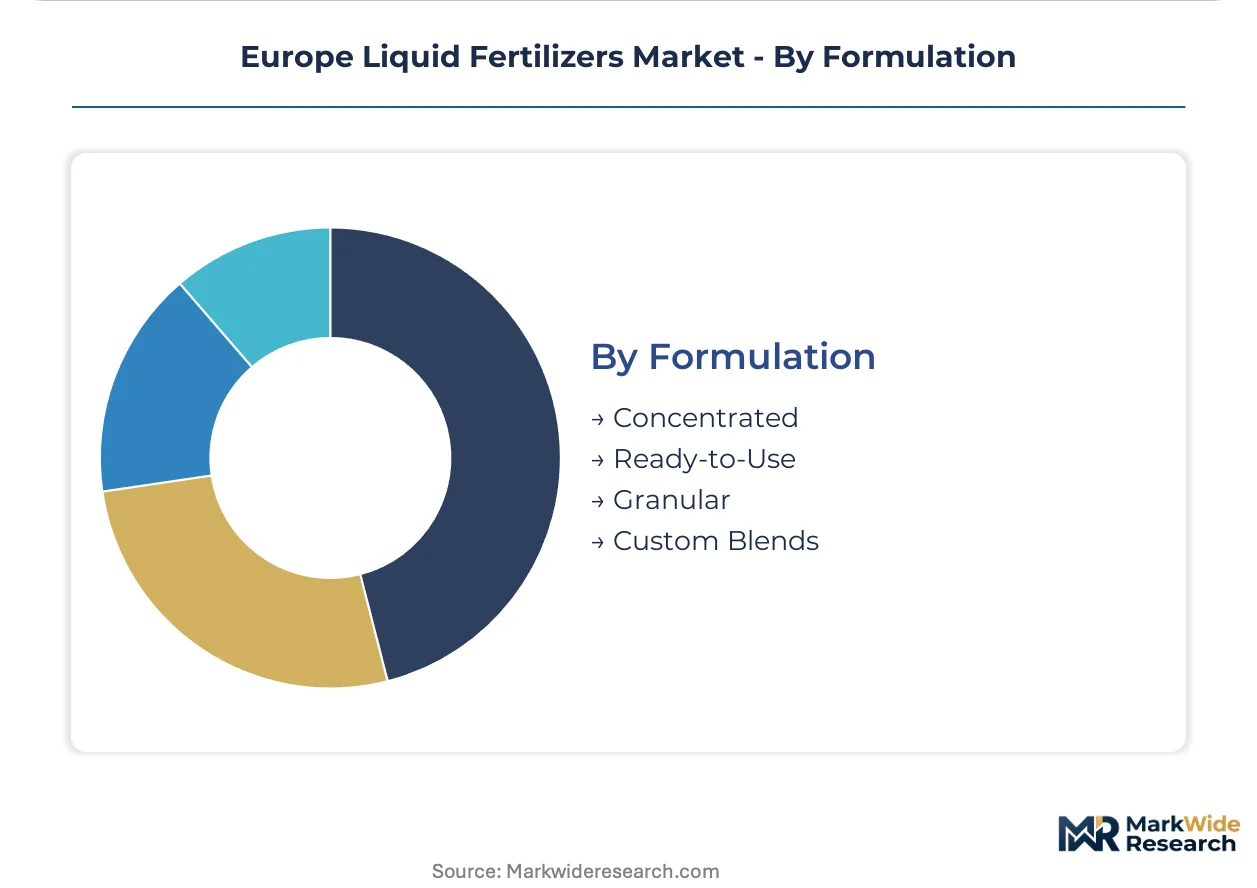
| Segmentation | Product Type: Urea, Ammonium Nitrate, Potassium Nitrate, Specialty Nutrients Application: Crops, Gardens, Lawns, Greenhouses Distribution Channel: Retail Stores, Online Stores, Wholesale Distributors, Agronomy Services Formulation: Concentrated, Ready-to-Use, Granular, Custom Blends |
| Companies Covered | Yara International ASA, ICL Group Ltd, Grupa Azoty S.A., CF Industries Holdings, Inc., Sociedad Quimica y Minera de Chile SA, EuroChem, OCI N.V., BASF SE, K+S AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Liquid Fertilizers Market Shifts & Advancements
Precision agriculture hardware and controlled-release chemistry are converging to redefine application economics, shifting competitive advantage from commodity nutrient sourcing to integrated system design and data-driven dosing protocols.
Controlled-release polymer coatings for liquid urea-ammonium nitrate solutions are supplanting conventional unprotected formulations in high-value greenhouse operations. Dutch substrate growers in Westland and Aalsmeer are adopting these technologies to reduce leaching losses and comply with groundwater nitrate directives. The shift is compressing demand for standard-grade liquids while expanding margin pools for additive-enhanced specialty grades.
REACH authorization requirements for nitrification inhibitors are tightening substance eligibility criteria, forcing reformulation toward bio-based alternatives. ECHA's evaluation of 3,4-dimethylpyrazole phosphate and other established chemistries is prompting blenders to accelerate dossier preparation for replacement compounds. Greenhouse operators in Belgium and Denmark are piloting amino-acid-based stabilizers as regulatory hedges against conventional inhibitor restrictions.
Subscription-based nutrient management contracts are displacing transactional bulk purchasing among large-scale arable cooperatives. French cereal farmers in Île-de-France and Centre-Val de Loire are contracting integrated fertility services combining soil testing, variable-rate application, and seasonal formulation adjustments. The model transfers inventory risk from growers to suppliers while locking in multi-year offtake commitments.
Europe Liquid Fertilizers Market Segmentation
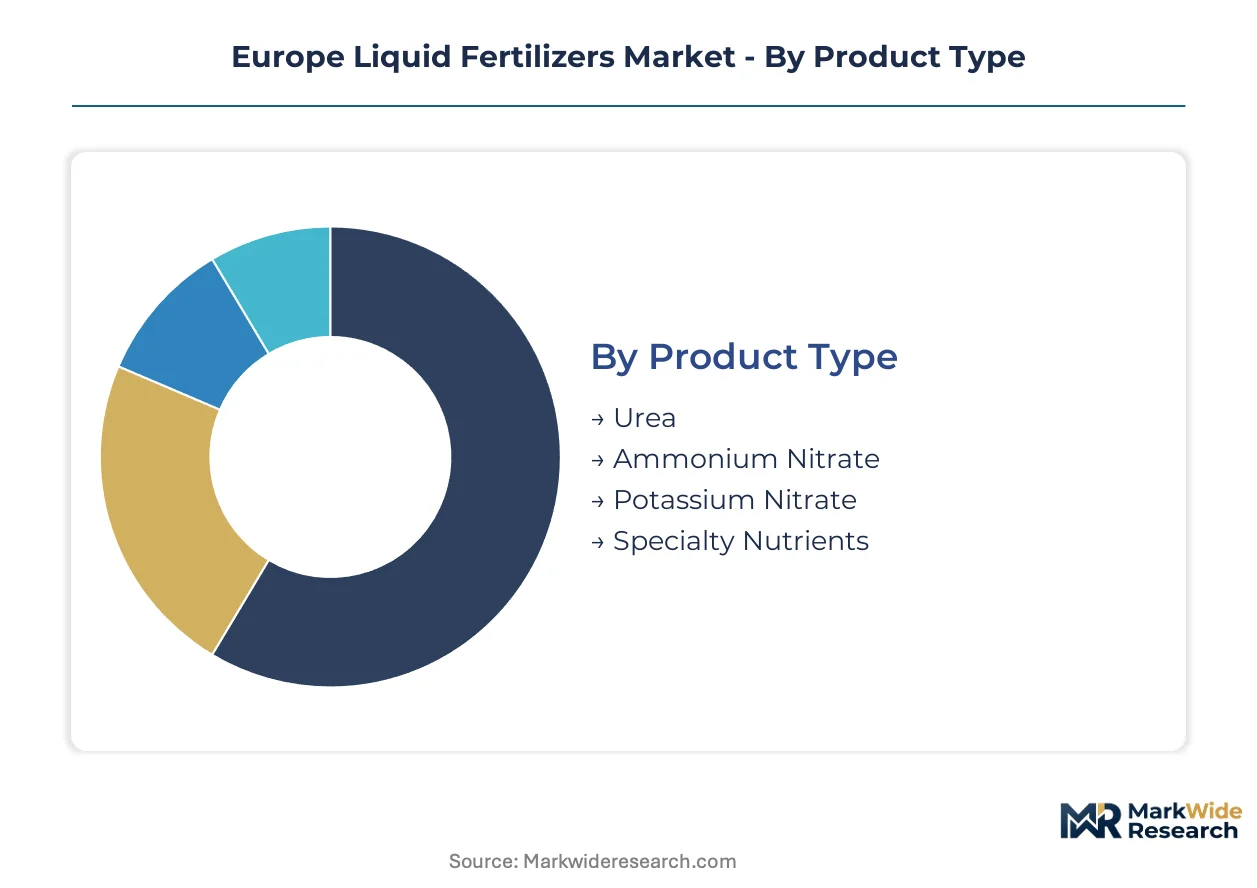
Liquid fertilizer segmentation in Europe reflects divergent pressure points across product chemistry, application environment, and supply chain configuration. Each dimension carries distinct substitution threats that reshape competitive positioning and margin capture.
Product Type:
Substitution pressure concentrates on commodity nitrogen grades facing regulatory constraints and cost volatility, while specialty nutrients build defensive moats through formulation complexity.
- Urea:Aqueous solutions containing forty-six percent nitrogen by weight serve as the baseline input for bulk cereal operations across France and Germany. TTF-linked ammonia costs compress margins for non-integrated blenders serving the Paris Basin.
- Ammonium Nitrate:Water-soluble formulations with thirty-four percent nitrogen content dominate open-field applications where rapid crop uptake is critical. CE marking requirements under EU Fertilizing Products Regulation are accelerating consolidation among compliant producers.
- Potassium Nitrate:Dual-nutrient solutions supply protected horticulture in the Netherlands with chloride-free potassium essential for substrate-based cultivation.
- Specialty Nutrients:Chelated micronutrient suspensions target high-value permanent crops in Italy's Po Valley and Spain's citrus belt.
Urea retains volume leadership; specialty nutrients hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity field applications from precision-managed protected systems with divergent input economics.
- Greenhouses:Substrate-based cultivation in Westland and Almería demands calibrated nutrient dosing through fertigation infrastructure. Dutch growers prioritize water-soluble NPK stability to comply with groundwater nitrate directives.
- Crops:Large-scale cereal operations across Poland's Greater Poland Voivodeship and France's cereal belt rely on bulk urea-ammonium nitrate for seasonal top-dressing.
- Gardens:Consumer-scale ready-to-use formulations serve amenity horticulture through retail channels in Germany and the UK.
- Lawns:Turf management applications concentrate in municipal contracts and golf course maintenance across Scandinavia.
Crops retain volume leadership; greenhouses hold the steepest expansion curve.
Distribution Channel:
Customer type fragmentation splits procurement between transactional bulk purchasing and integrated service relationships with divergent loyalty dynamics.
- Agronomy Services:Subscription-based nutrient management contracts combining soil testing, variable-rate application, and seasonal adjustments are displacing spot purchasing among French cereal cooperatives in Île-de-France.
- Wholesale Distributors:Regional blenders with captive storage infrastructure anchor supply to arable operations across Germany's northern plains.
- Retail Stores:Garden center networks serve amenity and smallholder segments through packaged ready-to-use formulations.
- Online Stores:Direct-to-farm platforms are gaining traction among tech-adopting growers in Denmark and the Netherlands seeking price transparency.
Wholesale distributors retain volume leadership; agronomy services hold the steepest expansion curve.
Formulation:
Maturity differentiation separates established concentrated grades from emerging custom configurations with divergent technical service requirements.
- Concentrated:High-density solutions requiring dilution prior to application dominate bulk logistics economics for cereal operations across Eastern Europe.
- Custom Blends:Site-specific NPK ratios formulated to match soil test results and crop uptake curves command premium positioning in high-value greenhouse systems.
- Ready-to-Use:Pre-diluted solutions packaged for consumer and amenity segments reduce handling complexity for non-specialist applicators.
- Granular:Suspension formulations with suspended solid nutrients bridge liquid delivery convenience with slow-release characteristics for permanent crops.
Concentrated formulations retain volume leadership; custom blends hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale arable cooperatives in France's cereal belt and Dutch greenhouse consortiums in Westland dominate procurement volumes, while specialty crop operations in Spain and Italy drive premium-grade formulation demand.
France
Île-de-France and Centre-Val de Loire cereal cooperatives are converting to subscription-based nutrient management contracts. The EU Green Deal's nutrient-loss reduction targets are accelerating granular-to-liquid transitions in the Paris Basin. Variable-rate application services now cover over sixty percent of cooperative acreage in the Beauce region.
Netherlands
Westland and Aalsmeer greenhouse clusters demand calibrated water-soluble NPK stability for substrate-based cultivation. REACH compliance requirements for nitrification inhibitors are forcing reformulation toward bio-based stabilizers. Dutch growers pilot amino-acid-based alternatives to conventional 3,4-dimethylpyrazole phosphate chemistries.
Spain
Almería province specialty crop growers are retrofitting irrigation networks for fertigation programs. The EU Fertilizing Products Regulation's cadmium limits are filtering non-compliant phosphate-based imports. Protected horticulture expansion in El Ejido and Roquetas de Mar concentrates demand for chloride-free potassium nitrate solutions.
Italy
Po Valley permanent crop operators seek chelated micronutrient suspensions for high-value fruit systems. ECHA evaluations of established inhibitor chemistries are prompting accelerated dossier preparation. Citrus belt operations in Sicily and Calabria represent conversion targets for organic-transitioning biostimulant-liquid formulations.
Poland
Greater Poland Voivodeship cereal operations remain reliant on conventional granular application. CE marking requirements under EU Fertilizing Products Regulation are consolidating market access around compliant producers. Large-scale farms in Wielkopolska present conversion potential for fertigation system suppliers targeting underpenetrated acreage.
Europe Liquid Fertilizers Market Competitive Landscape
Player mix skews toward integrated nitrogen producers with captive ammonia supply and regional blenders with formulation expertise. Three tiers structure the vendor base: multinational nutrient majors with backward integration into feedstock networks, mid-scale regional compounders with deep water-soluble NPK capabilities, and niche specialists in micronutrient suspensions. Capacity expansion and strategic partnerships dominate competitive moves, with players securing low-carbon ammonia pathways ahead of carbon-border adjustment implementation.
Among integrated nitrogen majors, Yara International ASA and EuroChem occupy positions exemplifying divergent sourcing strategies. Yara leverages Nordic and Baltic production sites with integrated ammonia-to-nutrient networks. EuroChem anchors its market presence through captive phosphate rock control and formulation depth in water-soluble grades. CF Industries Holdings, Inc. represents the North American-originated entrant competing on scale and Gulf Coast feedstock access.
| Leading Market Players |
|---|
| Yara International ASA |
| ICL Group Ltd |
| Grupa Azoty S.A. |
| CF Industries Holdings, Inc. |
| Sociedad Quimica y Minera de Chile SA |
| EuroChem |
| OCI N.V. |
| BASF SE |
| K+S AG |
| Others |
Supply & Pricing Matrix
CE marking under the EU Fertilizing Products Regulation gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where compliant producers command premium positioning while non-certified operators face margin compression or exit.
Pricing Analysis
Cost-plus contracts with TTF hub indexation dominate nitrogen-based liquid procurement, tying formulation costs to volatile natural gas benchmarks. Pricing stratifies across CE-certified premium grades, compliant standard formulations, and non-certified economy blends. Cost compression in commodity urea-ammonium nitrate runs through TTF-linked ammonia synthesis expenses. Polish cereal cooperatives exhibit highest price sensitivity; Dutch greenhouse consortiums prioritize formulation stability over unit cost.
Supply Chain Analysis
Strategic stockpiling of phosphate rock and ammonia feedstock prevails over just-in-timemodels given supply disruption risks and cadmium content variability. Production gravity centers on Norway, Russia, and Morocco for phosphate and ammonia inputs. European blenders draw from Moroccan phosphate reserves and TTF-indexed natural gas. Single-source vulnerability concentrates in phosphate rock supply. Distribution runs through regional blenders with captive storage infrastructure serving arable belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as CE marking requirements and carbon-border adjustment mechanics splinter homogeneous demand into compliance-tiered niches requiring specialized supply configurations.
For Market Incumbents: Fortify backward integration into low-carbon ammonia pathways ahead of CBAM phased implementation. Secure captive phosphate rock sourcing to insulate against cadmium limit variability and Moroccan supply disruption. Expand formulation chemist capacity in Germany and the Netherlands to address R&D bottlenecks.
For New Entrants and Emerging Players: Differentiate on biostimulant-liquid convergence for organic-transitioning permanent crop systems in Italy and Spain. Target Poland's underpenetrated Greater Poland Voivodeship with fertigation system bundles converting granular-dependent cereal operations. Pursue direct-to-farm digital platforms leveraging price transparency demand among Danish and Dutch tech-adopting growers.
For Investors and Strategic Acquirers: Carbon-border adjustment implementation reshapes the acquisition landscape toward domestic and near-shore ammonia producers with verified low-carbon credentials. Five-to-ten-year viability favors mid-scale regional compounders with deep water-soluble NPK capabilities and established CE marking compliance. Monitor cadmium threshold debates as inflection indicator for phosphate-based liquid market access restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Ammonia | CBAM positioning secures cost-competitive access for Nordic and Baltic production sites. |
| CE Marking Compliance Investment | Regulatory affairs capacity expansion accelerates product re-registration under harmonized standard updates. |
| Biostimulant-Liquid Formulation Development | Seaweed extract integration captures premium positioning in organic-transitioning citrus and vineyard systems. |
| Fertigation Infrastructure Partnership | Retrofit alliances with Almería and Po Valley irrigation networks lock in multi-year offtake commitments. |
| Subscription-Based Nutrient Management Contracts | Integrated fertility services transfer inventory risk from French cereal cooperatives to suppliers. |
Research Methodology
Desk research of trade customs data, EU regulatory filings, and industry association reports preceded structured interviews with formulation chemists, procurement leads at agricultural cooperatives, distribution channel partners, and regulatory affairs directors at major blenders. Primary fieldwork combined telephone and video interviews with secondary validation against ECHA substance registrations, CE marking databases, and ammonia production cost disclosures. Bottom-up volume estimates triangulated with top-down macroeconomic indicators.
Variance decomposition across product type, application environment, formulation complexity, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate aggregation weighted by baseline value shares. Industry-specific forecast inputs included TTF natural gas price trajectories and EU Green Deal nutrient-loss reduction target implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained CE marking enforcement or carbon-border adjustment mechanics would require recalibration. Forecasts reflect assumptions regarding regulatory timeline adherence and feedstock price regime stability. Revision becomes warranted when cadmium threshold debates or phosphate rock supply disruptions cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
North America Fertilizers Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Fertilizer Tester Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Mineral Fertilizers Market