
 China Specialty Fertilizer Market | 2026-2036
China Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
China Specialty Fertilizer Market Outlook
Shandong Province is fragmenting as domestic water-soluble fertilizer capacity expands across the North China Plain. Hebei Monband Water Soluble Fertilizer Co. Ltd leverages its regional supply chain to dominate water-soluble product lines. Yara International ASA competes through technology leadership in precision nutrient formulations. Haifa Group anchors its position with specialty potassium and micronutrient portfolios tailored to intensive horticulture.
Specialty fertilizers encompass value-added nutrient products engineered with controlled-release coatings, chelated micronutrients, or solubility-optimized formulations to match specific crop growth stages and soil conditions. These products deliver targeted nutrient availability, reducing leaching losses while improving nitrogen use efficiency in high-value cropping systems. Slow-release formulations command premium positioning as greenhouse operators seek labor-saving application schedules. Liquid fertilizers capture expanding share through fertigation compatibility with drip irrigation networks. Solid fertilizers retain volume leadership in broadacre agricultural crops where mechanized spreading dominates.
China's Ministry of Agriculture and Rural Affairs sets fertilizer registration and quality standards, while GB standards under SAMR mandate nutrient content labeling and heavy metal limits. The Ministry of Ecology and Environment enforces emissions controls on ammonia and nitrous oxide from fertilizer manufacturing, reshaping plant investment decisions. Stakeholders must monitor evolving carbon intensity benchmarks and water-use efficiency mandates as regulatory thresholds tighten across provincial agricultural zones.
Market Dynamics
China's dual carbon goals and MEE emissions standards are forcing specialty fertilizer manufacturers to retool production lines, while Shandong Province's greenhouse vegetable belt drives formulation demand toward water-soluble and controlled-release products. This regulatory-demand tension is compressing legacy ammonium nitrate capacity and accelerating low-carbon technology adoption across the North China Plain.
Growth Catalysts
- Dual carbon policy framework:China's 2030 carbon peak and 2060 neutrality targets compel fertilizer plants to adopt ammonia emission controls and energy-efficient coating technologies, expanding addressable market for low-carbon specialty formulations.
- Greenhouse horticulture intensification:Shandong Province's protected vegetable cultivation area exceeds 1.3 million hectares, creating concentrated demand for fertigation-compatible water-soluble fertilizers with precise NPK ratios.
- Precision irrigation penetration:Drip and micro-sprinkler systems now cover over 60% of North China Plain high-value cropland, necessitating specialty fertilizers engineered for solubility and compatibility with automated nutrient delivery infrastructure.
Market Restraints
- Potash import dependency:China sources 50% of potassium chloride from Belarus, Canada, and Russia, exposing water-soluble fertilizer margins to seaborne freight volatility and geopolitical supply disruptions.
- MEE emissions compliance costs:Ammonia and nitrous oxide abatement equipment mandates require capital outlays of 15-25 million RMB per production line, disadvantaging small-scale compound fertilizer plants without captive technical resources.
- Synthetic nitrogen substitution:Organic farming zones in Zhejiang and Jiangsu provinces are piloting microbial inoculant programs that reduce synthetic urea application rates by 20-30% in leafy vegetable systems.
Strategic Opportunities
- Western China horticulture expansion:Gansu and Xinjiang autonomous regions are constructing 200,000+ hectares of solar greenhouse complexes, creating greenfield demand for controlled-release formulations adapted to arid climates and saline-alkali soils.
- Carbon credit monetization:China's national ETS expansion to agriculture sector anticipated by 2027 would allow specialty fertilizer producers to certify and trade emission reductions from enhanced-efficiency product lines.
- Biostimulant-nutrient convergence:Integration of seaweed extracts and humic acids with NPK granules is opening premium positioning for manufacturers with fermentation biotechnology capabilities and SAMR biostimulant registration expertise.
Industry Challenges
- Formulation chemist scarcity:Mastery of polymer coating kinetics and chelation chemistry for micronutrients remains concentrated among senior researchers at state agricultural academies, constraining product development velocity for private manufacturers.
- GB standard compliance timelines:SAMR's 2024 heavy metal limit revisions for phosphate fertilizers require 18-24 month re-registration cycles, freezing product portfolios during technical documentation and field trial phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Specialty Fertilizer Market |
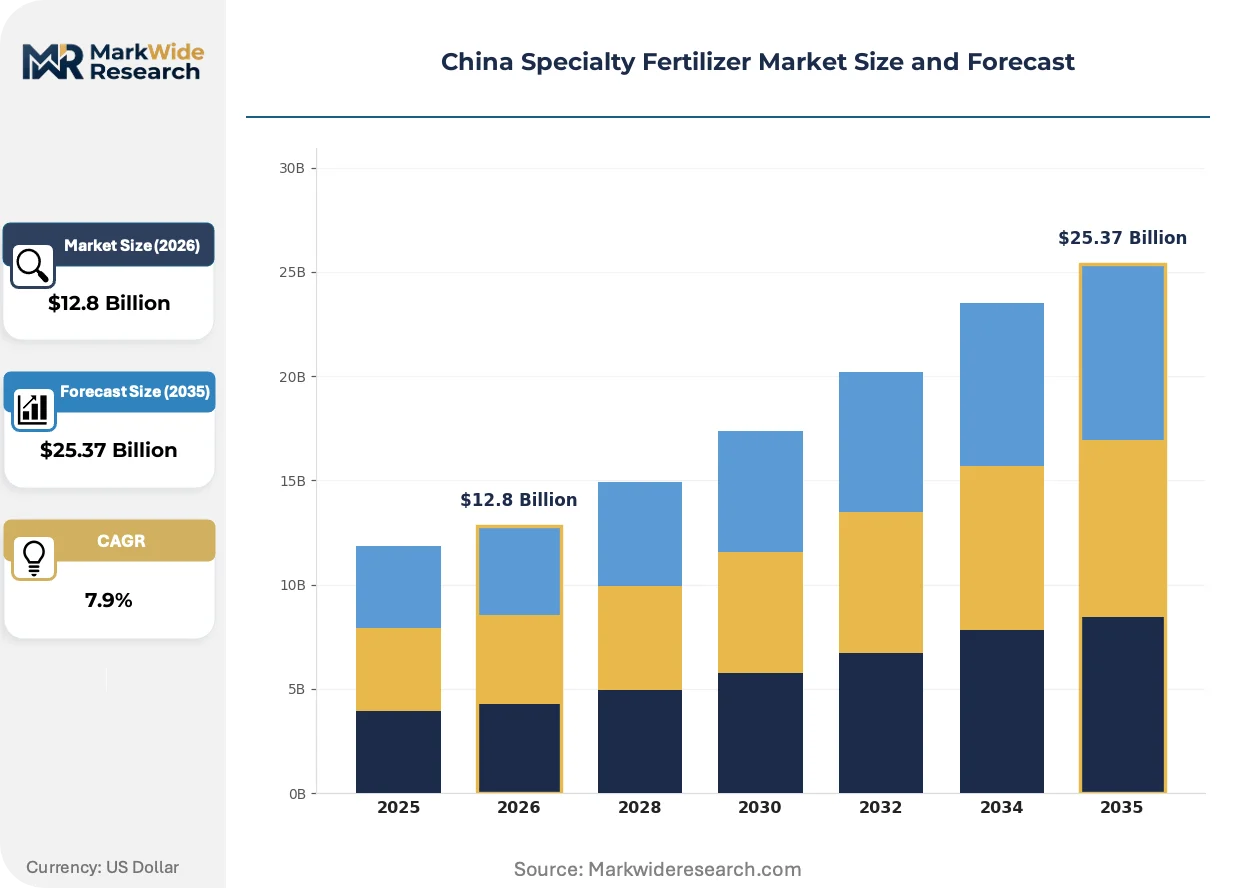
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $25.37 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slow-release, Liquid Fertilizers, Solid Fertilizers, Foliar Fertilizers Application: Agricultural Crops, Horticulture, Turf Management, Greenhouse Formulation: Granular, Powder, Liquid, Suspensions End User: Farmers, Agricultural Cooperatives, Retailers, Distributors |
| Companies Covered | Hebei Monband Water Soluble Fertilizer Co. Ltd, Grupa Azoty S.A. (Compo Expert), Yara International ASA, Hebei Sanyuanjiuqi Fertilizer Co., Ltd., Haifa Group, ICL Group Ltd, Hebei Woze Wufeng Biological Technology Co., Ltd, Sinofert Holdings Limited, Henan XinlianXin Chemicals Group Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Specialty Fertilizer Market Strategic Shifts
Polymer coating technologies and bio-based release mechanisms are collapsing the performance gap between commodity fertilizers and precision nutrient delivery systems. Regulatory carbon accounting and buyer procurement sophistication are simultaneously reshaping product development priorities and competitive positioning across China's agricultural input sector.
Controlled-release urea with polyurethane membrane coatings is collapsing the labor cost advantage of conventional split-application regimes. Shandong greenhouse operators now specify 90-day release curves for tomato and cucumber production cycles, compressing seasonal fertilizer handling expenses while maintaining yield targets. The technology is collapsing price premiums as domestic coating chemical production scales at Linyu and Zibo industrial clusters.
MEE's 2023 Technical Guidelines for Fertilizer Industry Pollution Control mandate continuous emissions monitoring for ammonia and particulate matter. Plants in Hebei and Henan provinces are installing selective catalytic reduction systems and baghouse filtration, absorbing compliance costs through operational consolidation rather than price pass-through. The policy is reshaping investment decisions most acutely among nitrogen-phosphate compound manufacturers with legacy fixed-bed ammonia synthesis.
County-level agricultural service cooperatives are consolidating procurement decisions for 40% of North China Plain specialty fertilizer volume, displacing individual grower purchasing. These cooperatives negotiate multi-year supply agreements with manufacturers offering soil testing and prescription mapping services, compressing traditional distributor margins. The behavioral shift is most visible in Shouguang and Qingzhou vegetable production districts, where cooperative-managed acreage exceeds 80,000 hectares.
China Specialty Fertilizer Market Segmentation
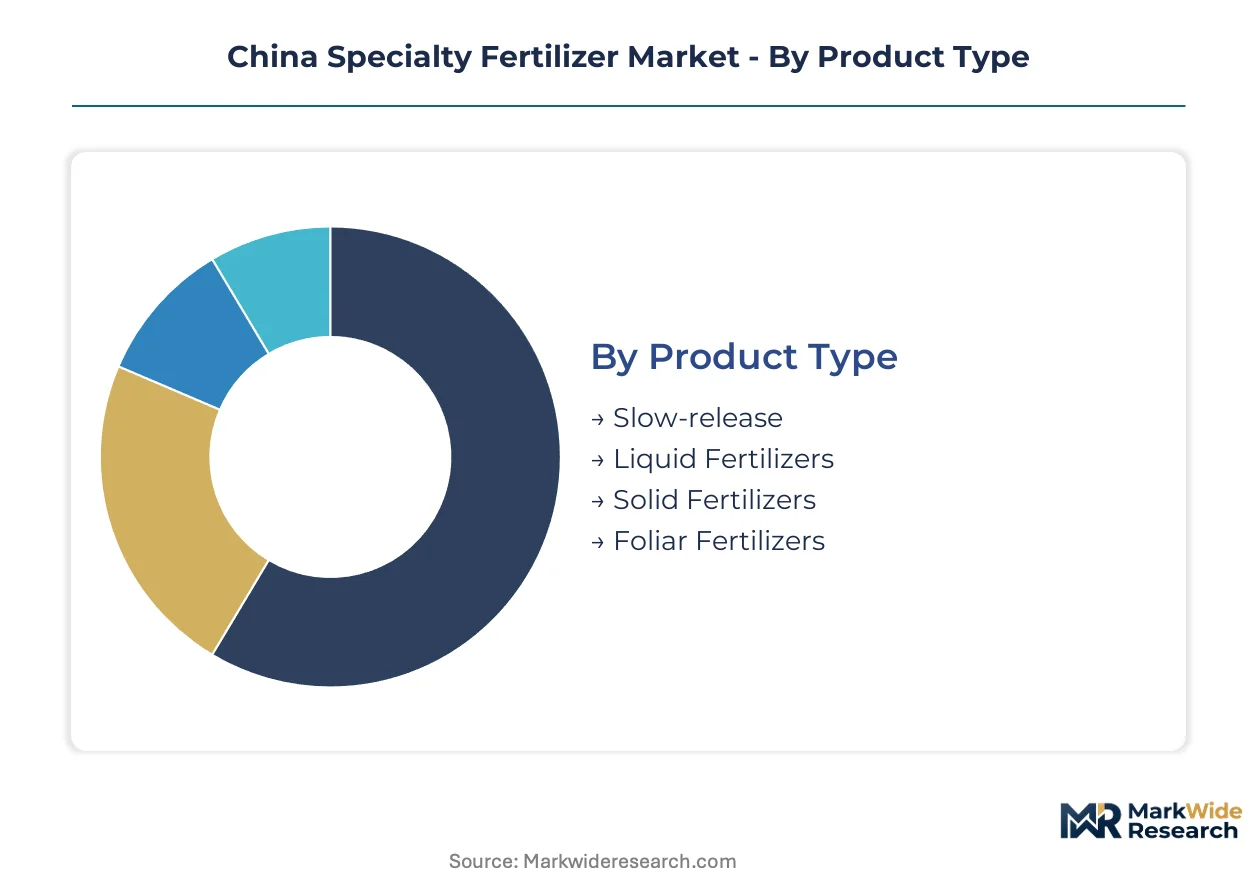
Specialty fertilizer segmentation in China reflects the tension between legacy agricultural practices and precision horticulture expansion. Product formulation choices directly determine compatibility with Shandong's drip irrigation networks and Hebei's emissions-controlled production corridors.
Product Type:
Mature controlled-release technologies coexist with emerging liquid formulations across China's agricultural input sector.
- Slow-release:Polymer-coated urea and sulfur-coated formulations deliver nitrogen over 60-90 day cycles. Shandong greenhouse operators specify these products for tomato and cucumber production to reduce seasonal labor costs.
- Liquid Fertilizers:Fully soluble NPK concentrates and micronutrient chelates engineered for fertigation compatibility. Demand concentrates in North China Plain counties where drip irrigation penetration exceeds 60% of high-value cropland, driven by water-use efficiency mandates from the Ministry of Ecology and Environment.
- Solid Fertilizers:Granular and prilled specialty compounds retain dominance in broadacre wheat and maize systems across Henan and Hebei provinces.
- Foliar Fertilizers:Micronutrient sprays for corrective feeding during critical growth stages in intensive vegetable production.
Solid fertilizers retain volume leadership; liquid formulations hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity grain systems from premium horticulture operations.
- Horticulture:Protected cultivation of vegetables, fruits, and ornamental crops demanding precise nutrient timing. Shandong Province's 1.3 million hectares of greenhouse infrastructure generate concentrated procurement of water-soluble and controlled-release products.
- Greenhouse:Climate-controlled production environments requiring fertigation-compatible formulations with exact NPK ratios and low electrical conductivity. County-level agricultural cooperatives in Shouguang and Qingzhou districts negotiate multi-year supply agreements for these specialized inputs.
- Agricultural Crops:Open-field grain and oilseed production utilizing broadcast-applied specialty fertilizers for yield optimization.
- Turf Management:Golf courses and municipal landscaping in Beijing and Shanghai metropolitan zones driving slow-release nitrogen demand.
Agricultural crops retain volume leadership; greenhouse applications hold the steepest expansion curve.
Formulation:
Supply concentration in coastal chemical clusters shapes regional formulation availability.
- Liquid:Fully dissolved nutrient solutions with guaranteed solubility for drip irrigation systems. Hebei Monband and Yara International production facilities near Tianjin port leverage imported potash for high-analysis water-soluble concentrates.
- Granular:Coated and compacted products for mechanized spreading in broadacre systems across the North China Plain.
- Powder:Dry-mix formulations for on-farm dissolution and custom blending by agricultural service cooperatives.
- Suspensions:Concentrated nutrient slurries with extended stability for specialized fertigation equipment.
Granular formulations retain volume leadership; liquid suspensions hold the steepest expansion curve.
End User:
Customer type determines procurement scale and technical service requirements.
- Agricultural Cooperatives:County-level organizations consolidating 40% of North China Plain specialty fertilizer volume through multi-year supply agreements. These entities demand soil testing and prescription mapping services from manufacturers, compressing traditional distributor margins.
- Farmers:Individual growers in Zhejiang and Jiangsu organic farming zones piloting reduced synthetic nitrogen programs through microbial inoculant integration.
- Distributors:Regional wholesalers managing inventory and logistics for manufacturers without direct county-level presence.
- Retailers:Township-level input shops serving smallholder plots with bagged specialty fertilizer products.
Agricultural cooperatives retain volume leadership; farmer direct procurement holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty fertilizer manufacturing clusters along the North China Plain dominate domestic capacity, with provincial emissions standards and horticulture intensification creating divergent demand profiles across sub-regional markets.
Shandong Province
Greenhouse vegetable cultivation exceeding 1.3 million hectares drives concentrated procurement of water-soluble and controlled-release formulations. MEE emissions guidelines force coating chemical plants at Linyu and Zibo to install continuous monitoring systems. Shouguang and Qingzhou districts host county-level cooperatives managing 80,000+ hectares of cooperative-managed acreage with multi-year supply agreements.
Hebei Province
Intensive wheat and maize systems sustain granular specialty fertilizer demand while precision irrigation penetration reshapes product mix toward liquid concentrates. Dual carbon policy frameworks compel nitrogen-phosphate compound manufacturers to retrofit selective catalytic reduction systems. Tianjin port proximity enables Hebei Monband and comparable processors to leverage imported potash for high-analysis water-soluble production.
Henan Province
Broadacre agricultural crops retain volume leadership in open-field grain production utilizing broadcast-applied specialty compounds. SAMR heavy metal limit revisions for phosphate fertilizers trigger 18-24 month re-registration cycles freezing product portfolios. Zhengzhou-centered chemical corridors concentrate formulation capacity serving Central China distribution networks.
Xinjiang Autonomous Region
Solar greenhouse construction exceeding 200,000 hectares creates greenfield demand for controlled-release formulations adapted to arid climates and saline-alkali soils. Western China horticulture expansion programs channel agricultural modernization investment toward drip irrigation infrastructure. Urumqi and Korla industrial zones attract specialty fertilizer distribution hubs serving Central Asian export corridors.
Zhejiang and Jiangsu Provinces
Organic farming zones pilot microbial inoculant programs reducing synthetic urea application rates in leafy vegetable systems. Provincial agricultural bureaus enforce water-use efficiency mandates accelerating precision nutrient delivery adoption. Hangzhou and Nanjing biotechnology clusters incubate biostimulant-nutrient convergence products requiring SAMR registration expertise.
China Specialty Fertilizer Market Competitive Environment
Domestic water-soluble specialists and multinational precision nutrient formulators split the market along technology and supply-chain vectors. Consolidation pressure concentrates among nitrogen-phosphate compound manufacturers facing MEE compliance costs of 15-25 million RMB per production line. Three archetypes dominate: regional supply-chain integrators with captive distribution, technology-led multinationals with formulation R&D capabilities, and state-linked fertilizer traders with import-access advantages. Competitive moves center on backward integration into coating chemical production and multi-year service contracts with county-level cooperatives.
Within the domestic specialist tier, Hebei Monband Water Soluble Fertilizer Co. Ltd and Hebei Sanyuanjiuqi Fertilizer Co., Ltd represent regional supply-chain integrators leveraging North China Plain manufacturing corridors. Yara International ASA occupies a position exemplifying technology-led multinational entry through precision nutrient formulation capabilities. Haifa Group anchors the specialty potassium and micronutrient segment with portfolios tailored to intensive horticulture applications. These named entities illustrate archetype positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Hebei Monband Water Soluble Fertilizer Co. Ltd |
| Grupa Azoty S.A. (Compo Expert) |
| Yara International ASA |
| Hebei Sanyuanjiuqi Fertilizer Co., Ltd. |
| Haifa Group |
| ICL Group Ltd |
| Hebei Woze Wufeng Biological Technology Co., Ltd |
| Sinofert Holdings Limited |
| Henan XinlianXin Chemicals Group Company Limited |
| Others |
Value Chain & Pricing Dynamics
Belarusian and Canadian potash concentration upstream anchors margin capture at the formulation tier, where water-soluble fertilizer specialists translate import dependency into premium positioning for high-analysis NPK concentrates. Domestic coating chemical production at Shandong industrial clusters is collapsing historical price premiums for controlled-release formulations.
Pricing Analysis
MEE emissions compliance mandates dictate the pricing tier structure across China's specialty fertilizer sector, separating premium low-carbon formulations from legacy ammonium nitrate products facing retrofit cost absorption. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale procurement by county-level cooperatives. Pricing pressure stems from county-level cooperative consolidation capturing 40% of North China Plain volume through multi-year supply agreements. Agricultural cooperatives exhibit lowest price sensitivity due to bundled technical service requirements, while individual smallholders in township retail channels remain most responsive to per-bag cost differentials.
Supply Chain Analysis
Extended payment terms from agricultural cooperatives are reshaping working capital requirements for manufacturers, driving supply-chain finance facility adoption among mid-scale compound fertilizer plants. Potassium chloride draws from Belarus, Canada, and Russia; polymer coating chemicals source from domestic Shandong petrochemical clusters; nitrogen feedstock rests on captive ammonia synthesis at state-linked complexes. Single-source vulnerability concentrates in seaborne potash lanes through Baltic and Pacific routes. Distribution runs through county-level agricultural service cooperatives displacing traditional township retailer networks across Shouguang and Qingzhou vegetable districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's specialty fertilizer market represents an early-cycle expansion story, with western horticulture construction and carbon credit monetization creating penetration tailwinds ahead of national ETS agriculture sector inclusion.
For Market Incumbents: Harden technical service capabilities around soil testing and prescription mapping to defend multi-year cooperative contracts against emerging biostimulant-nutrient convergence specialists. Secure backward integration into coating chemical production at Linyu and Zibo clusters to capture margin compression from domestic polyurethane membrane scaling. MEE compliance cost concentration among nitrogen-phosphate compound manufacturers without captive technical resources presents acquisition opportunities for consolidated low-carbon capacity. For New Entrants and Emerging Players: Pursue greenfield formulation demand in Xinjiang's 200,000+ hectare solar greenhouse expansion, where saline-alkali soil adaptation requirements favor controlled-release specialists over incumbent broadacre players. Target biostimulant registration expertise at Hangzhou and Nanjing biotechnology clusters as the fastest-penetrable capability gap. Lead with SAMR biostimulant-nutrient convergence products requiring fermentation biotechnology capabilities that incumbent mineral fertilizer plants lack. For Investors and Strategic Acquirers: Capital is best deployed toward technology-led multinationals with precision nutrient formulation R&D capabilities and established SAMR registration pathways, positioned for sustained viability across the 5-10 year dual carbon policy horizon. The signal to watch is MEE's anticipated carbon intensity benchmark tightening for provincial agricultural zones, which would accelerate low-corn specialty formulation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemicals | Domestic polyurethane membrane production at Shandong clusters collapses import dependency for controlled-release formulations. |
| Biostimulant-Nutrient Convergence | SAMR registration of seaweed extract-NPK granules opens premium positioning beyond commodity mineral fertilizers. |
| County-Level Cooperative Multi-Year Contracts | Soil testing and prescription mapping services lock in 40% of North China Plain volume through technical bundling. |
| Western China Horticulture Expansion | Xinjiang and Gansu solar greenhouse construction creates greenfield demand for arid-climate adapted formulations. |
| Carbon Credit Certification Investment | National ETS agriculture sector inclusion would monetize emission reductions from enhanced-efficiency product lines. |
Study Parameters
Cross-validation between primary interviews with formulation chemists at state agricultural academies and secondary analysis of SAMR fertilizer registration databases anchors the qualitative findings in documented regulatory pathways. Plant managers at Hebei and Shandong production facilities, procurement leads at county-level agricultural cooperatives, distribution channel partners in North China Plain logistics corridors, and technical R&D directors at water-soluble specialists provided operational perspective. Customs and trade data, MEE emissions disclosure filings, GB standards revision notices, and provincial agricultural bureau investment plans supplied quantitative grounding. Bottom-up volume modeling triangulates against top-down macroeconomic agricultural input intensity benchmarks.
Calibration against historical adoption curves for precision irrigation and controlled-release technologies refines the analytical framework across the projection horizon. Segmentation dimensions include product formulation type, application environment, end-user procurement scale, and regional regulatory compliance tier. CAGRs derive from elasticity-adjusted intensity projections and technology substitution curves. Potash import dependency ratios and MEE compliance cost absorption capacity at legacy nitrogen-phosphate plants inform scenario-weighted outputs.
Macroeconomic conditions sit as an overlay; deviation in agricultural credit availability, seaborne freight rates, or provincial water-use efficiency enforcement would shift the trajectory. Forecasts reflect documented assumptions around dual carbon policy implementation pace and cooperative procurement consolidation rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Fertilizers Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Russia Fertilizers Market
Fertilizers
United States Micronutrient Fertilizer Market