
 Russia Micronutrient Fertilizer Market | 2026-2036
Russia Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Micronutrient Fertilizer Market Analytics
Buyer concentration among large-scale agroholdings in Russia's southern grain belt is expanding, pulling volume away from fragmented smallholder channels. PhosAgro Group of Companies leverages its captive phosphate base to integrate boron and zinc formulations into compound fertilizer lines. EuroChem Group anchors distribution through dedicated agronomic service teams embedded in Krasnodar and Rostov farming corridors. Yara International ASA competes via precision agriculture partnerships that tie micronutrient prescriptions to satellite-guided variable-rate application.
Micronutrient fertilizers deliver essential trace elements—zinc, copper, boron, manganese—in quantities typically below one kilogram per hectare, correcting deficiencies that limit enzymatic activity and protein synthesis in crops. Foliar spray application dominates commercial uptake due to rapid nutrient interception during critical growth windows, while fertigation gains traction in greenhouse vegetable clusters near Moscow and Volgograd. Zinc formulations occupy the largest product-type share, reflecting chronic deficiency across Russia's calcareous chernozem soils; boron demand accelerates fastest in sugar beet and oilseed rotations where reproductive failure thresholds sit below 0.5 ppm available boron.
Russia's Federal Service for Veterinary and Phytosanitary Surveillance (Rosselkhoznadzor) enforces registration requirements for imported micronutrient formulations, creating compliance barriers for non-domestic suppliers. The national Technical Regulation on Fertilizer Safety mandates heavy-metal limits and solubility standards that shape product formulation decisions. BIS-adjacent certification protocols for organic-compatible micronutrients are gaining relevance as export-oriented farms seek EU market access. Stakeholders must monitor how Russia's import-substitution agenda redirects procurement toward domestic blenders with verified local production certificates.
Market Dynamics
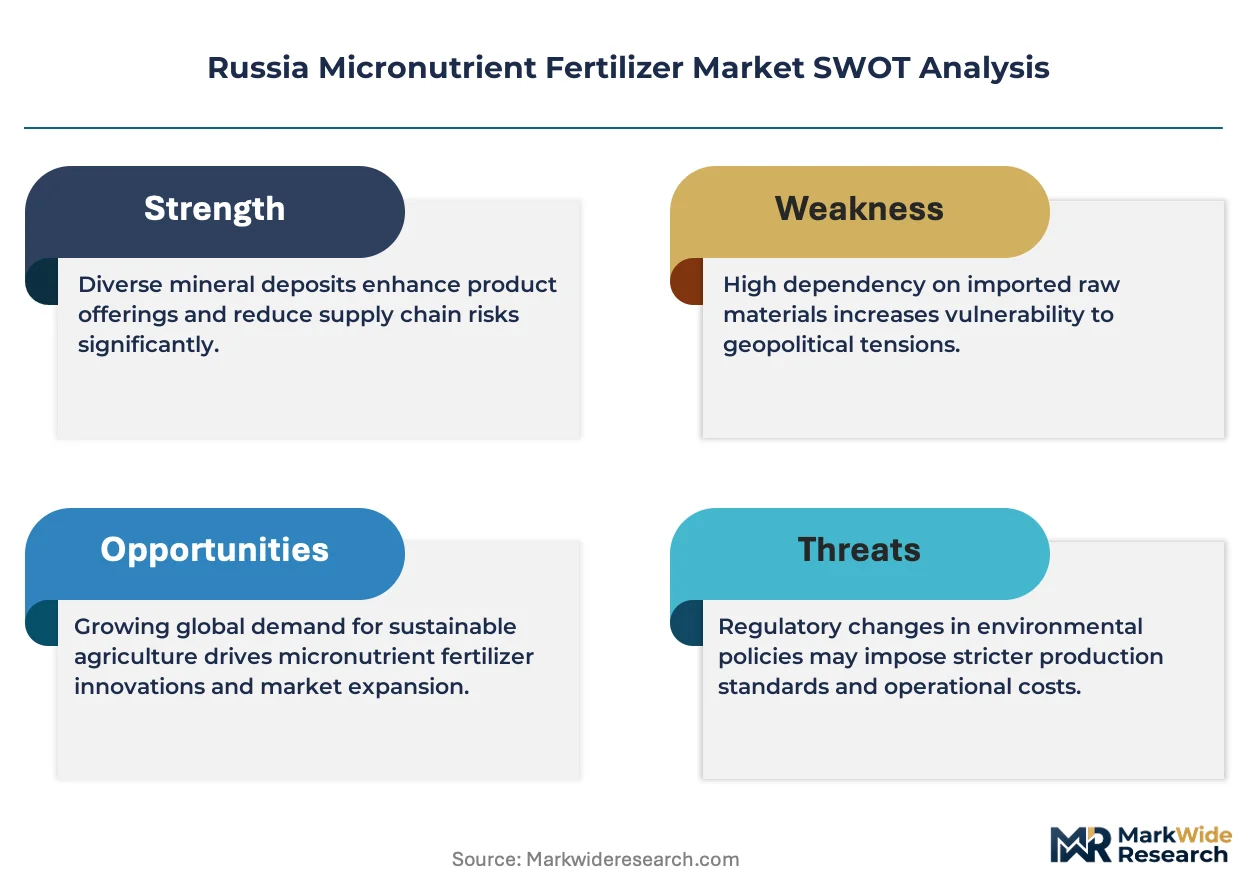
Russia's import-substitution agenda is redirecting procurement toward domestic blenders with verified local production certificates, compressing margins for foreign suppliers while elevating captive phosphate-based integrated producers.
Growth Catalysts
- Soil Fertility Mandates:Russia's national soil fertility program requires micronutrient enrichment in depleted agricultural zones, creating recurring demand cycles in the Central Black Earth region.
- Precision Agriculture Adoption:Satellite-guided variable-rate application technology is expanding micronutrient prescriptions tied to real-time crop monitoring across large-scale agroholdings.
- Sugar Beet Expansion:Oilseed and sugar beet rotations in the southern grain belt drive accelerating boron demand where reproductive failure thresholds sit below 0.5 ppm available boron.
Market Restraints
- Import Registration Barriers:Rosselkhoznadzor enforces stringent registration requirements for imported micronutrient formulations, creating compliance friction for non-domestic suppliers.
- Heavy-Metal Compliance Costs:Russia's Technical Regulation on Fertilizer Safety mandates solubility standards and heavy-metal limits that reshape product formulation economics.
- Calcareous Soil Chemistry:Chronic zinc deficiency across Russia's chernozem soils requires specialized chelated formulations, elevating raw material input costs for blenders.
Strategic Opportunities
- Greenhouse Cluster Expansion:Fertigation systems gain traction in vegetable production clusters near Moscow and Volgograd, opening micronutrient delivery channels beyond foliar spray.
- EU Export Certification:BIS-adjacent organic-compatible certification protocols create premium positioning for farms seeking European market access.
- Volga Federal District Penetration:Large-scale grain producers in this underpenetrated region are expanding micronutrient applications to boost wheat yields.
Industry Challenges
- Agronomic Service Scaling:Embedded agronomic teams require specialized soil science expertise that domestic blenders struggle to recruit in Krasnodar and Rostov farming corridors.
- Application Timing Precision:Foliar spray windows during critical growth stages demand logistics coordination that fragmented smallholder channels cannot execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Micronutrient Fertilizer Market |
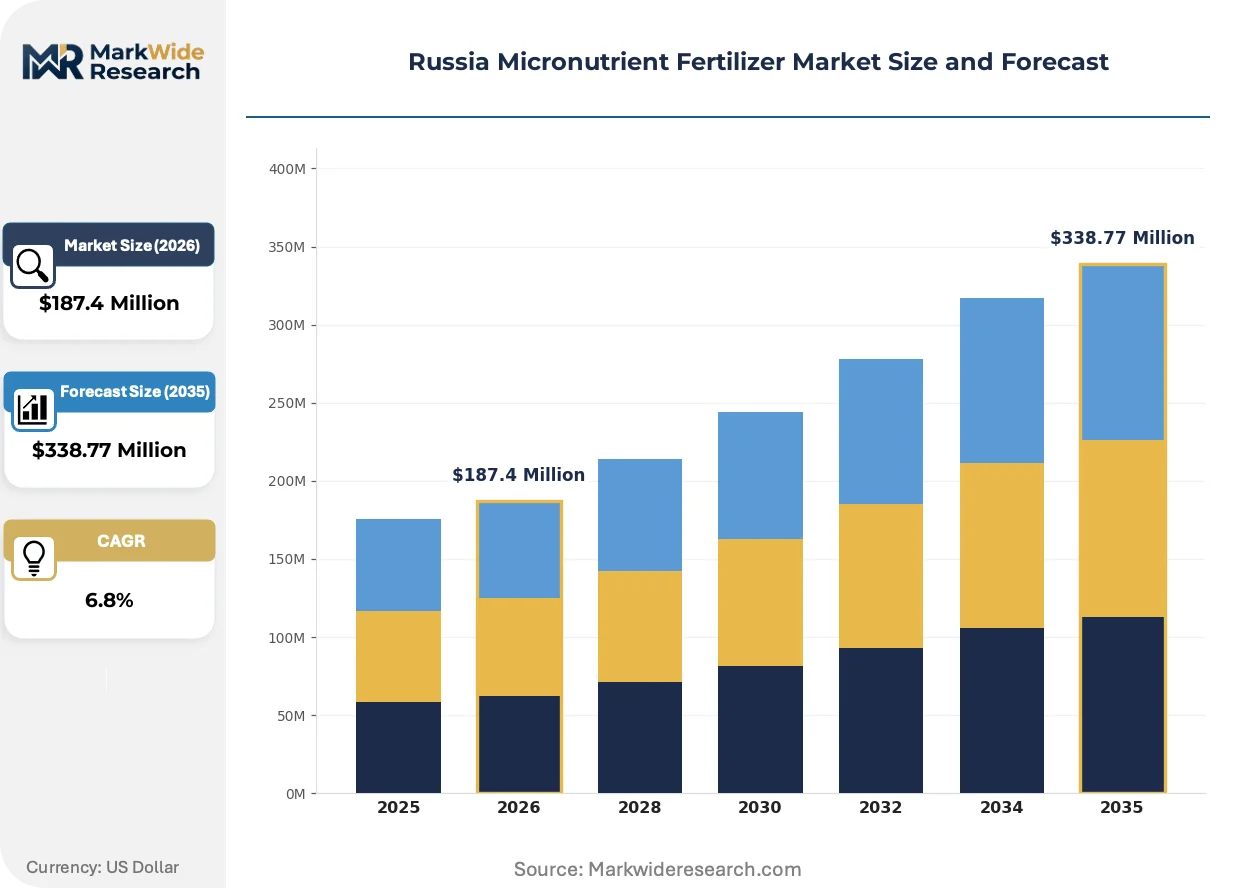
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Copper, Boron, Manganese Application Method: Drenching, Fertigation, Foliar Spray, Soil Application Crops: Cereals, Vegetables, Fruits, Pulses Distribution Channel: Online, Retail, wholesalers, Cooperatives |
| Companies Covered | Biolchim SPA, PhosAgro Group of Companies, Yara International ASA, Haifa Group, Trade Corporation International, ICL Group Ltd, Mivena BV, Valagro, EuroChem Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Micronutrient Fertilizer Market Evolving Landscape
Formulation chemistry and application methodology are converging to address Russia's specific soil deficiencies, with domestic producers leveraging captive mineral bases to customize trace element delivery systems.
Chelated zinc formulations is overtaking inorganic salts in commercial uptake across Russia's calcareous chernozem belt. Large-scale agroholdings in the southern grain belt are adopting these advanced formulations at accelerating pace. This chemistry shift is overtaking price-sensitive commodity micronutrient segments, compressing market share for basic sulfate-based products.
Russia's Technical Regulation on Fertilizer Safety imposes solubility standards and heavy-metal limits that reshape product development priorities. Domestic blenders with verified local production certificates gain preferential market access under the import-substitution agenda. Fertilizer safety compliance is redirecting procurement toward integrated producers with captive phosphate bases and in-house micronutrient formulation capabilities.
Buyer concentration among large-scale agroholdings is consolidating procurement volume away from fragmented smallholder channels. Dedicated agronomic service teams are displacing traditional distributor relationships in Krasnodar and Rostov farming corridors. This channel restructuring concentrates micronutrient demand among fewer buyers with technical sophistication requirements.
Russia Micronutrient Fertilizer Market Segmentation
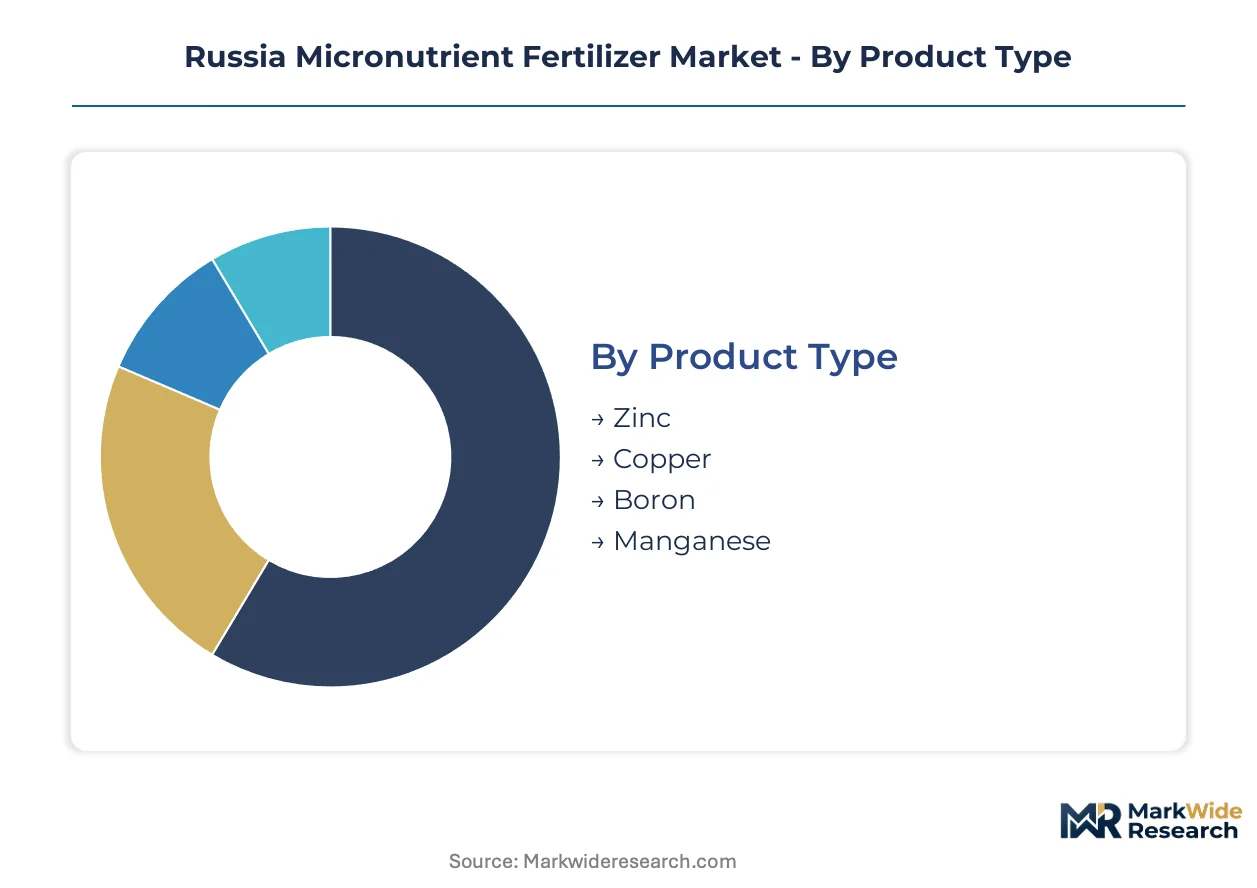
Micronutrient fertilizer segmentation in Russia reflects divergent technical requirements across soil chemistry, crop physiology, and operational scale. Each dimension shapes formulation priorities, application logistics, and channel economics for suppliers navigating the country's import-substitution environment.
Product Type:
Standardized commodity salts compete with customized chelated complexes across this spectrum, with soil chemistry dictating which chemistry commands premium positioning.
- Zinc:Chelated zinc complexes address chronic deficiency across Russia's calcareous chernozem belt where high pH locks conventional sulfates into unavailable forms. Large-scale agroholdings in the Central Black Earth region are standardizing chelated formulations for wheat production, accepting 40-60% price premiums over inorganic salts to guarantee enzymatic activation during grain filling stages.
- Boron:Solubilized borates and polyborate formulations target reproductive-stage crops where deficiency thresholds sit below 0.5 ppm available boron. Sugar beet and oilseed rotations in Krasnodar and Rostov farming corridors are driving accelerating uptake, with reproductive failure risks justifying precision application investments.
- Copper:Sulfate and oxide forms serve cereal systems where deficiency manifests as sterile florets and reduced grain protein.
- Manganese:Sulfate and EDTA-chelated variants address interveinal chlorosis in legumes and certain vegetable systems.
Most installed capacity flows through zinc formulations. Expansion is steepest in boron as oilseed and sugar beet acreage climbs in the southern grain belt.
Application Method:
Volume economics favor soil incorporation at planting, while timing precision and nutrient interception efficiency pull commercial uptake toward foliar and fertigation modalities.
- Foliar Spray:Atomized micronutrient solutions enable rapid correction during critical growth windows when root uptake is insufficient or soil fixation is severe. The method dominates commercial uptake across Russia's large-scale grain operations, with satellite-guided variable-rate equipment enabling prescription accuracy that justifies per-hectare application costs.
- Fertigation:Water-soluble micronutrient injection into irrigation systems enables continuous, low-concentration feeding matched to crop phenology. Greenhouse vegetable clusters near Moscow and Volgograd are adopting this method fastest, where controlled-environment production justifies infrastructure investment and drip irrigation penetration is highest.
- Soil Application:Granular or powder incorporation at tillage remains baseline practice for broadacre cereals with lower per-hectare value.
- Drenching:Root-zone saturation delivers concentrated doses for high-value orchard and vegetable transplant establishment.
Application volume concentrates in foliar systems. Steepest adoption gains are occurring in fertigation as protected cultivation expands near major consumption centers.
Crops:
Commodity grain economics constrain micronutrient investment per hectare, while high-value produce and export-oriented crops support premium formulation uptake.
- Cereals:Wheat, barley, and corn dominate absolute micronutrient demand volume across Russia's southern grain belt, with zinc deficiency correction representing the primary intervention. Large-scale agroholdings in the Volga Federal District are expanding application rates to boost protein content and yield stability for export positioning.
- Vegetables:Greenhouse tomato, cucumber, and pepper production near Moscow and Volgograd requires complete micronutrient programs addressing multiple simultaneous deficiencies. Fertigation-compatible soluble formulations command premium pricing in this segment, with boron and manganese particularly critical for fruit set and quality.
- Fruits:Apple, stone fruit, and berry operations in southern Russia utilize micronutrients for flowering regulation and post-harvest storage quality.
- Pulses:Pea and lentil rotations in the Central Black Earth region require manganese and boron for nodulation efficiency and seed development.
Cereals absorb the largest micronutrient volume by hectare. Vegetables generate the highest per-hectare formulation value and fastest growth in chelated complex adoption.
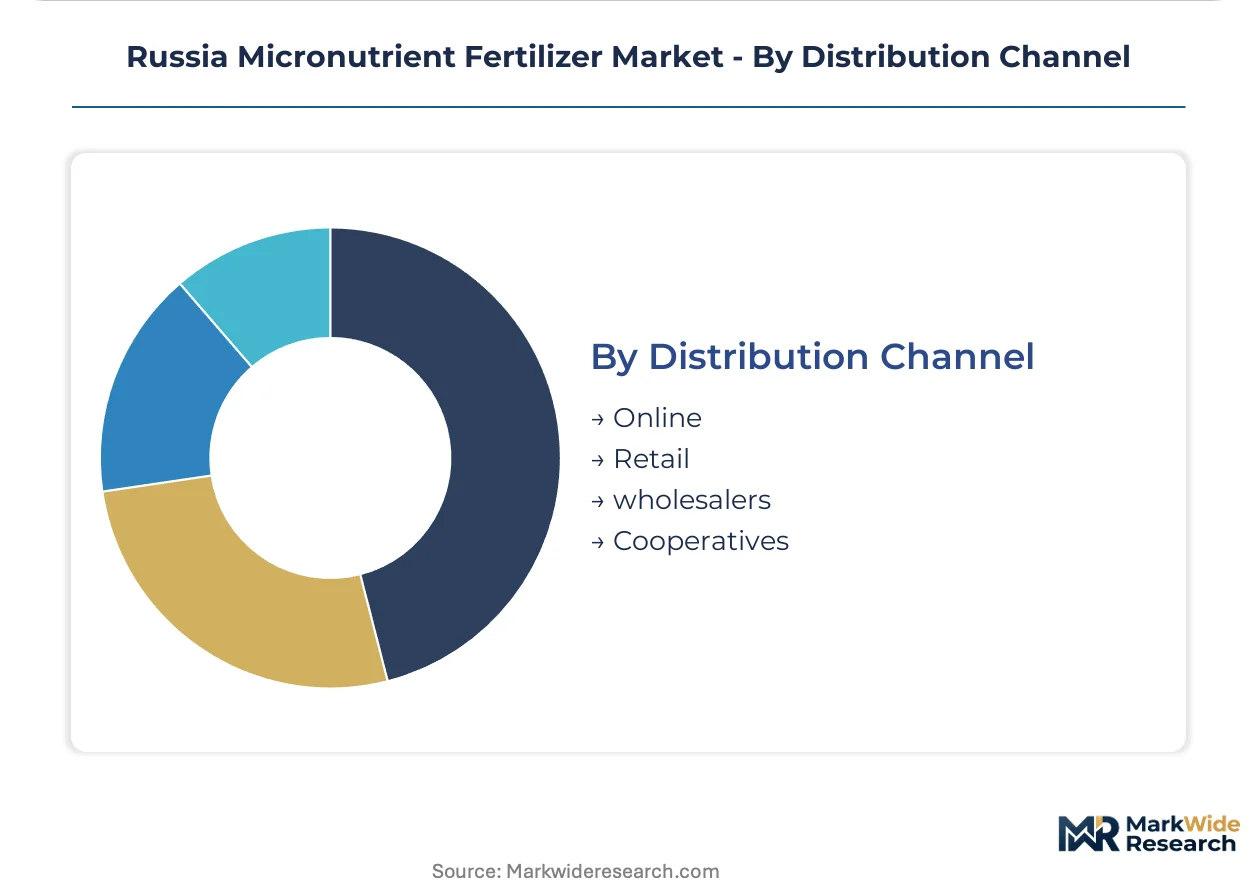
Distribution Channel:
Direct procurement by consolidated buyers is displacing traditional intermediary structures, compressing margin pools available to fragmented retail and cooperative networks.
- Cooperatives:Agricultural purchasing cooperatives aggregate smallholder and mid-scale farm demand, negotiating volume discounts and technical support packages. These entities remain significant in the Central Black Earth region where land fragmentation persists, though buyer concentration among agroholdings is eroding their historical channel dominance.
- Wholesalers:Regional distributors with storage and logistics infrastructure connect domestic blenders to farm-gate delivery, particularly in underpenetrated districts lacking direct manufacturer presence. EuroChem Group and PhosAgro leverage these relationships where embedded agronomic teams are not yet deployed.
- Retail:Farm supply stores and input dealers serve smallholder channels with bagged commodity formulations, facing margin compression from online price transparency.
- Online:E-procurement platforms are emerging for standardized products, though micronutrient prescriptions still require agronomic consultation that resists full digitalization.
Wholesale and cooperative channels currently move the largest micronutrient volumes. Direct manufacturer-to-farm relationships are gaining share fastest as agroholding consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's micronutrient fertilizer demand concentrates in distinct agricultural belts, with the Central Black Earth region outpacing the Volga Federal District in application intensity per hectare. Regional soil chemistry and crop specialization create divergent formulation requirements across federal districts.
Central Black Earth Region
Intensive wheat and sunflower rotations drive recurring zinc and boron replenishment cycles across Voronezh, Kursk, and Belgorod oblasts. Russia's national soil fertility program mandates micronutrient enrichment in these historically depleted zones. Large-scale agroholdings in Voronezh deploy satellite-guided variable-rate application equipment for prescription-based foliar programs.
Volga Federal District
Samara, Saratov, and Penza oblasts are expanding micronutrient applications to boost wheat protein content for export positioning. The region's calcareous chernozem soils lock conventional zinc sulfates into unavailable forms, elevating demand for chelated formulations. Grain producers in the Samara corridor are standardizing enzymatic activation protocols during grain filling stages.
Krasnodar and Rostov Farming Corridors
Sugar beet and oilseed rotations in these southern grain belt territories accelerate boron demand where reproductive failure thresholds sit below 0.5 ppm available boron. Rosselkhoznadzor registration requirements for imported formulations create compliance friction that domestic blenders exploit. Dedicated agronomic service teams from integrated producers are displacing traditional distributor relationships in these corridors.
Moscow and Volgograd Greenhouse Clusters
Protected vegetable cultivation near major consumption centers drives fertigation-compatible soluble micronutrient adoption for tomato, cucumber, and pepper production. Drip irrigation penetration in these clusters enables continuous low-concentration feeding matched to crop phenology. Complete micronutrient programs addressing multiple simultaneous deficiencies command premium pricing in this segment.
Russia Micronutrient Fertilizer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Russia's micronutrient fertilizer market, with integrated phosphate producers leveraging captive mineral bases to capture share from commodity blenders. The vendor base stratifies into three tiers: multinational agricultural input conglomerates with precision agriculture platforms, domestic integrated producers with verified local production certificates, and regional formulators serving fragmented smallholder channels. Two dominant competitive moves define current positioning: backward integration into captive phosphate and micronutrient formulation capabilities, and deployment of embedded agronomic service teams that displace traditional distributor relationships.
Among multinational agricultural input specialists, Yara International ASA and Haifa Group represent the precision agriculture archetype, anchoring market presence through satellite-guided variable-rate partnerships rather than commodity volume. PhosAgro Group of Companies and EuroChem Group exemplify the domestic integrated producer model, leveraging verified local production certificates to secure preferential access under Russia's import-substitution agenda. These four entities collectively illustrate how regulatory compliance and captive mineral access are reshaping competitive positioning.
| Leading Market Players |
|---|
| Biolchim SPA |
| PhosAgro Group of Companies |
| Yara International ASA |
| Haifa Group |
| Trade Corporation International |
| ICL Group Ltd |
| Mivena BV |
| Valagro |
| EuroChem Group |
| Others |
Value Network & Pricing Analysis
Chelated zinc raw material costs flow from Chinese and European specialty chemical producers through domestic Russian blenders, compressing margin pools at each formulation tier while import-substitution mandates redirect procurement toward verified local production certificates.
Pricing Analysis
Capacity additions in Central Russia are reshaping price floors for commodity sulfate-based micronutrients, forcing chelated complex premiums to compress from historical spreads. Three-tier pricing structure across premium chelated, standard soluble, and economy sulfate levels stratifies by certification grade and agronomic service bundling. Pricing pressure stems from Rosselkhoznadzor registration barriers elevating compliance costs for imported formulations. Smallholder channels exhibit highest price sensitivity, while large-scale agroholdings absorb premiums for prescription-based foliar programs.
Supply Chain Analysis
Phosphate rock supply rests on captive mining operations in the Kola Peninsula and Volga basin, with sulfur and potash feedstocks drawn from domestic extraction and Belarusian import streams. Boron and zinc trace element concentrates hinge on Turkish and Kazakh mining output subject to transit logistics volatility. Single-source vulnerability concentrates in chelating agent supply from German and Chinese specialty chemical producers. Distribution runs through embedded agronomic service teams displacing traditional wholesale networks in Krasnodar and Rostov corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's micronutrient fertilizer market represents a late-cycle quality story where chelated formulation premiums are hardening as large-scale agroholdings prioritize yield stability over input cost minimization.
For Market Incumbents: Anticipate margin compression in commodity sulfate segments by accelerating backward integration into captive phosphate and sulfuric acid production. Defensive positioning requires embedding soil science expertise in Voronezh and Samara agronomic teams before EuroChem and PhosAgro consolidate channel control. Certification investment in BIS-adjacent organic-compatible protocols creates differentiation against import-dependent competitors facing Rosselkhoznadzor friction.
For New Entrants and Emerging Players: Regional distributors in the Volga Federal District offer the most penetrable channel entry point, where direct manufacturer presence remains thin and wholesale relationships dominate. White-space targets concentrate in fertigation-compatible soluble formulations for Moscow greenhouse clusters, where drip irrigation penetration enables premium pricing. A technical partnership with precision agriculture equipment providers supplies the go-to-market angle for satellite-guided variable-rate prescription services.
For Investors and Strategic Acquirers: Consolidation pressure builds where domestic blenders lack verified local production certificates under Russia's import-substitution agenda. Long-term viability favors integrated producers with captive mineral bases and in-house chelation capabilities over commodity formulators dependent on imported concentrates. Acquisition target archetypes include regional formulators in the Central Black Earth region with established cooperative relationships. The signal to watch is Rosselkhoznadzor enforcement intensity against non-domestic suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Phosphate | PhosAgro's Kola Peninsula mining base secures sulfuric acid and phosphate feedstock cost control against import volatility. |
| Chelated Formulation Capacity Expansion | Domestic blenders address calcareous chernozem zinc deficiency with EDTA complex production replacing Chinese imports. |
| Embedded Agronomic Service Deployment | EuroChem's Krasnodar technical teams displace wholesale distributors with soil testing and prescription services. |
| BIS-Adjacent Organic Certification | Export-oriented farms in Voronezh access EU market premiums through heavy-metal compliant micronutrient protocols. |
| Precision Agriculture Partnership | Yara's satellite-guided variable-rate alliances tie micronutrient prescriptions to real-time crop monitoring systems. |
Research Methodology
Bottom-up crop-specific modeling reconciled against top-down blender capacity tracking forms the analytical core. Primary interviews with agronomic service directors, procurement leads at agroholdings, Rosselkhoznadzor compliance officers, and cooperative purchasing managers combined with secondary validation from customs trade data, Russian Federal State Statistics Service agricultural input reports, and fertilizer safety technical regulations. Triangulation against regional production databases and embedded service team deployment records verified volume estimates across the analysis window.
Input-output matrices mapped micronutrient consumption by crop type, application method, and regional soil chemistry against domestic blending capacity and import dependency ratios. Segmentation dimensions modeled include product chemistry tier, application technology, crop value intensity, and channel structure. CAGRs derived from regression analysis of historical application rate trends, acreage expansion patterns, and regulatory enforcement intensity. Forecast inputs incorporated chelated formulation adoption curves and precision agriculture equipment penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to import-substitution policy enforcement and EU export certification adoption rates. Forecasts reflect documented assumptions regarding Rosselkhoznadzor registration timelines and domestic chelating agent production scaling. A small set of named triggers warrants ongoing watch: Rosselkhoznadzor import restriction announcements, PhosAgro capacity expansion disclosures, and EU organic market access rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
GCC Fertilizer Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market