
 Chelated Micronutrient Fertilizers Market | 2026-2036
Chelated Micronutrient Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Chelated Micronutrient Fertilizers Market Insights
The EU Fertilizing Products Regulation is repositioning chelated micronutrient formulations across European agriculture by mandating biodegradable chelating agent standards. BASF SE leverages its specialty chemicals portfolio to sustain leadership in ethylenediaminetetraacetic acid alternatives. Yara International ASA anchors its competitive stance through integrated crop nutrition platforms spanning multiple continents. Haifa Group specializes in precision agriculture-grade micronutrient solutions for fertigation systems.
Chelated micronutrient fertilizers consist of metal ions bound to organic chelating agents such as EDTA, DTPA, or EDDHA, forming stable complexes that prevent nutrient precipitation in alkaline soils and enhance foliar absorption efficiency. Their primary commercial purpose centers on correcting trace element deficiencies in high-value crops where conventional inorganic salts exhibit poor bioavailability. Iron chelates dominate product type revenue due to persistent chlorosis treatment demand in calcareous soils, while hydroponics represents the fastest-expanding application channel as controlled-environment agriculture scales. Liquid formulations command premium positioning through compatibility with drip irrigation and aerial spraying infrastructure.
The EPA governs pesticide and fertilizer registration requirements in the United States, while REACH mandates chemical safety documentation for chelating agents entering European markets. India's FSSAI and BIS frameworks increasingly scrutinize heavy metal limits in agricultural inputs, reshaping import specifications for micronutrient manufacturers. Stakeholders must monitor evolving biodegradability mandates across multiple jurisdictions as regulatory thresholds for persistent chelating compounds tighten without uniform international alignment.
Market Dynamics
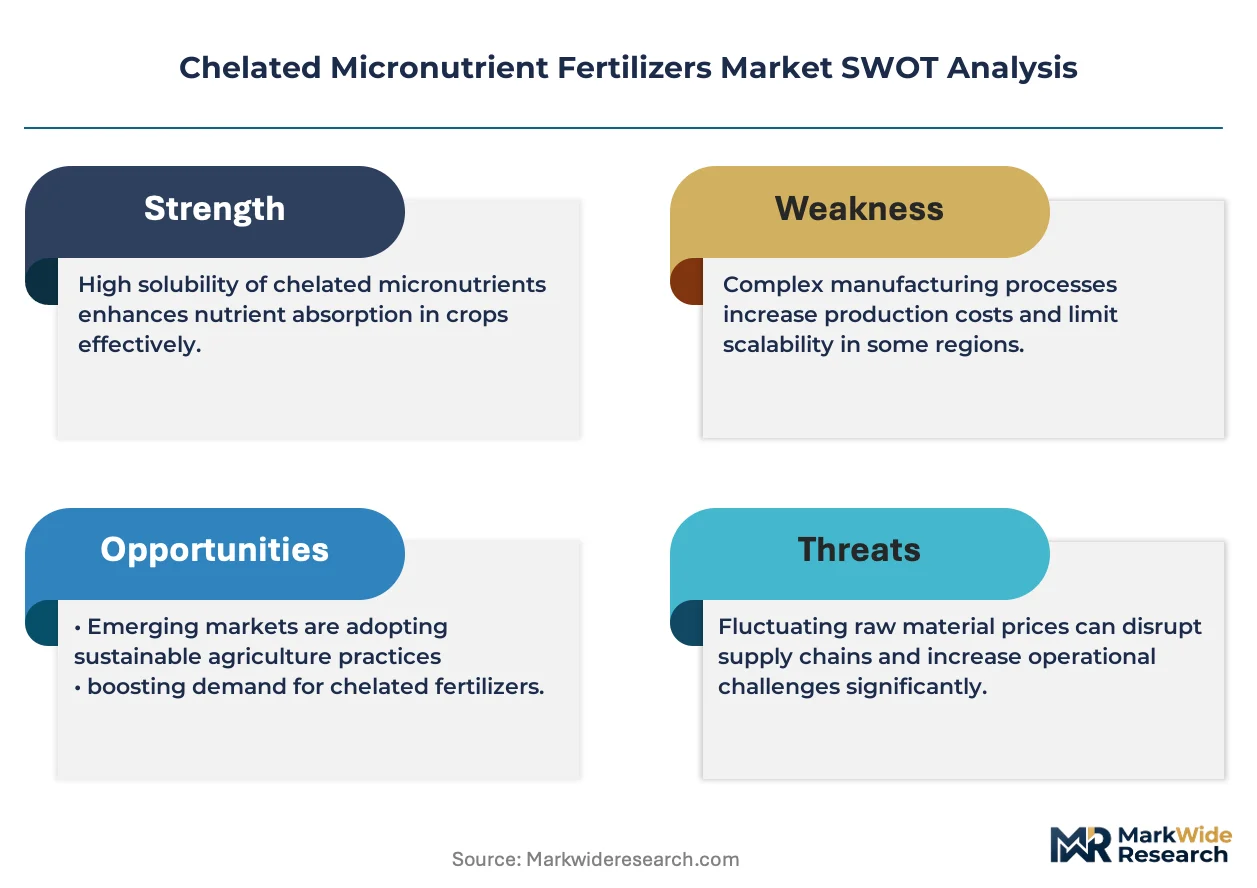
The EU Fertilizing Products Regulation is forcing a wholesale transition from synthetic EDTA chelates to biodegradable alternatives, compressing formulation timelines and redrawing supplier qualifications across European agriculture.
Growth Catalysts
- REACH biodegradability mandates:European manufacturers accelerate EDDHA and IDHA formulation investments to retain market access under tightening ECHA thresholds for persistent organic pollutants in soil amendments.
- Hydroponics infrastructure expansion:Controlled-environment vegetable producers in the Netherlands and Spain adopt precision-dosed liquid chelates to optimize nutrient film technique yields and reduce runoff compliance costs.
- Brazilian Cerrado intensification:Double-cropping soybean and corn operations in Mato Grosso drive premium micronutrient adoption as soil micronutrient depletion outpaces conventional fertilization replacement rates.
Market Restraints
- Biodegradable chelate input costs:EDDHA and IDHA raw material prices trade at substantial premiums to legacy EDTA, compressing margin structures for mid-tier blenders serving price-sensitive broadacre markets.
- EDTA manufacturing concentration:China dominates intermediate synthesis for conventional chelating agents, exposing European formulators to tariff volatility and carbon-border adjustment exposure under EU Green Deal implementation.
- Alkaline soil precipitation risk:Non-chelated inorganic micronutrient salts retain cost advantages in neutral pH zones, limiting chelate penetration in wheat belts where soil chemistry permits cheaper alternatives.
Strategic Opportunities
- Indian horticulture modernization:Protected cultivation acreage expansion under government subsidy programs creates first-mover positioning for fertigation-compatible liquid chelate portfolios in Maharashtra and Karnataka.
- Carbon credit monetization:Biodegradable chelate formulations qualify for soil carbon sequestration protocols under voluntary carbon markets, enabling premium pricing to sustainability-linked procurement programs.
- Drone application compatibility:Ultra-low volume foliar chelate formulations calibrated for unmanned aerial vehicle spraying open technical differentiation against ground-rig dependent competitors in Australian broadacre operations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in metal-ligand stability constant optimization for novel biodegradable agents concentrates within a limited pool of European and Israeli research institutions.
- Multi-jurisdiction registration synchronization:Divergent heavy metal limit specifications between India's FSSAI, Brazil's MAPA, and EU REACH require parallel toxicological dossier preparation, extending product launch timelines.
- Legacy equipment incompatibility:Existing blending infrastructure at regional cooperatives lacks corrosion-resistant materials for acidic biodegradable chelate concentrates, forcing capital reinvestment or third-party tolling arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chelated Micronutrient Fertilizers Market |
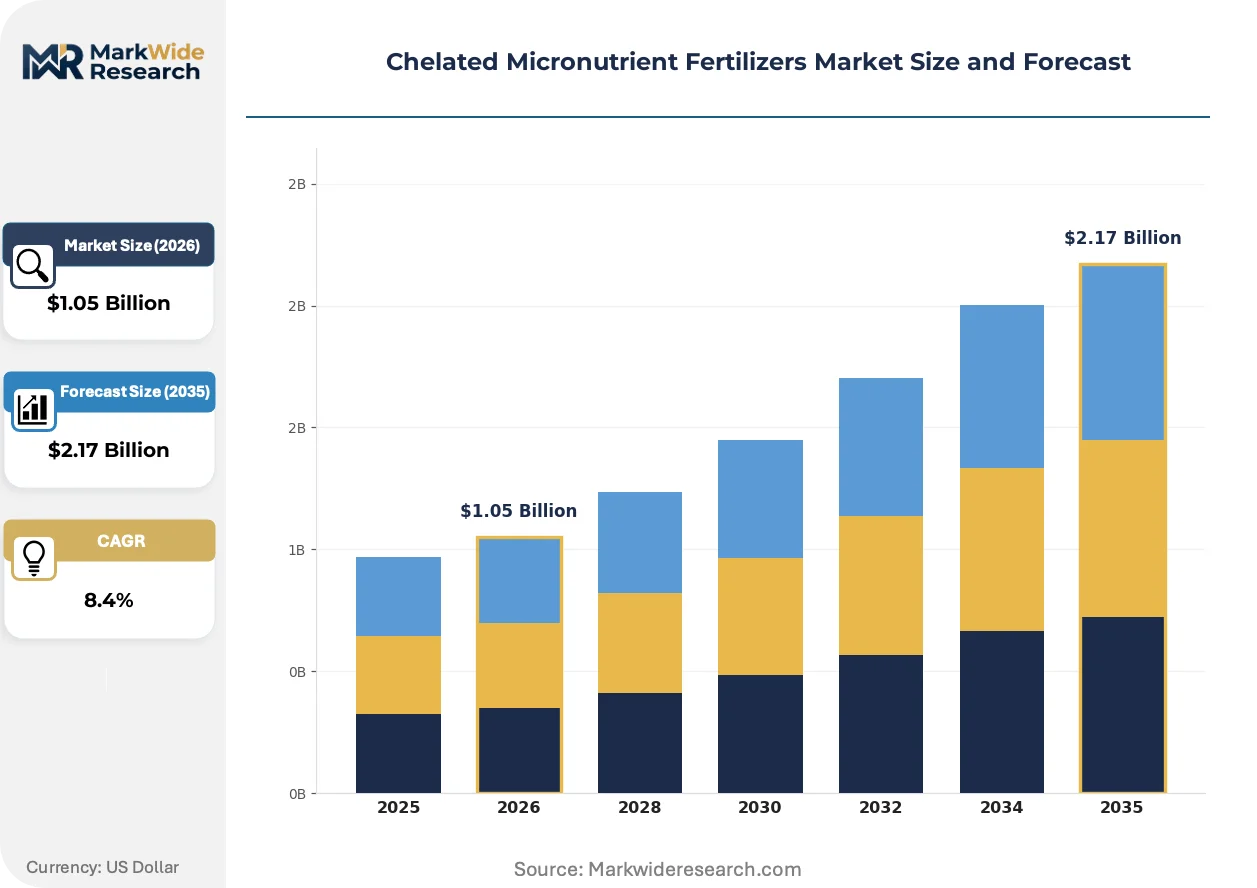
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Chelates, Zinc Chelates, Manganese Chelates, Copper Chelates Application: Agriculture, Horticulture, Turf Management, Hydroponics Distribution Channel: Direct Sales, Retail Stores, E-commerce, Distributors Form: Granules, Liquid, Powder, Soluble |
| Companies Covered | BASF SE, Nouryon, Nufarm, Yara International ASA, Coromandel International Limited, Land O’Lakes, Inc., ICL Group Ltd, Haifa Group, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chelated Micronutrient Fertilizers Market Trends and Innovations
Biodegradable chelating agent chemistry is overtaking legacy synthetic formulations as the dominant R&D allocation priority, while precision application hardware and carbon-accounting integration reshape commercial specifications.
IDHA [iminodisuccinic acid] chelates deliver comparable micronutrient stability to EDTA complexes while meeting OECD 301B biodegradability thresholds. Dutch greenhouse operators and Spanish berry cooperatives are adopting IDHA-based iron and zinc formulations at accelerated procurement cycles. This transition is overtaking EDTA-dependent suppliers in sustainability-certified supply chains, particularly those serving Northern European retail produce specifications.
REACH Annex XVII restrictions on persistent organic pollutants now explicitly classify non-biodegradable chelating agents as substances of very high concern candidate list materials. Formulators face mandatory substitution timelines or market withdrawal from EU-27 fertilizer registrations by 2030. Specialty crop segments in Italy and Greece confront the steepest compliance costs, driving consolidation toward integrated chemical-nutrition platforms with captive biodegradable chelate synthesis.
Certification-driven procurement now dominates specialty crop contracting, with GLOBALG.A.P. and retailer-specific sustainability codes mandating biodegradable input verification. Traditional distributor-led sales models face displacement from direct technical partnerships between chelate manufacturers and grower cooperatives. This pattern concentrates in California's Central Valley and Chile's Central Valley, where consolidated packing houses aggregate input specifications across thousands of contracted hectares.
Chelated Micronutrient Fertilizers Market Segmentation
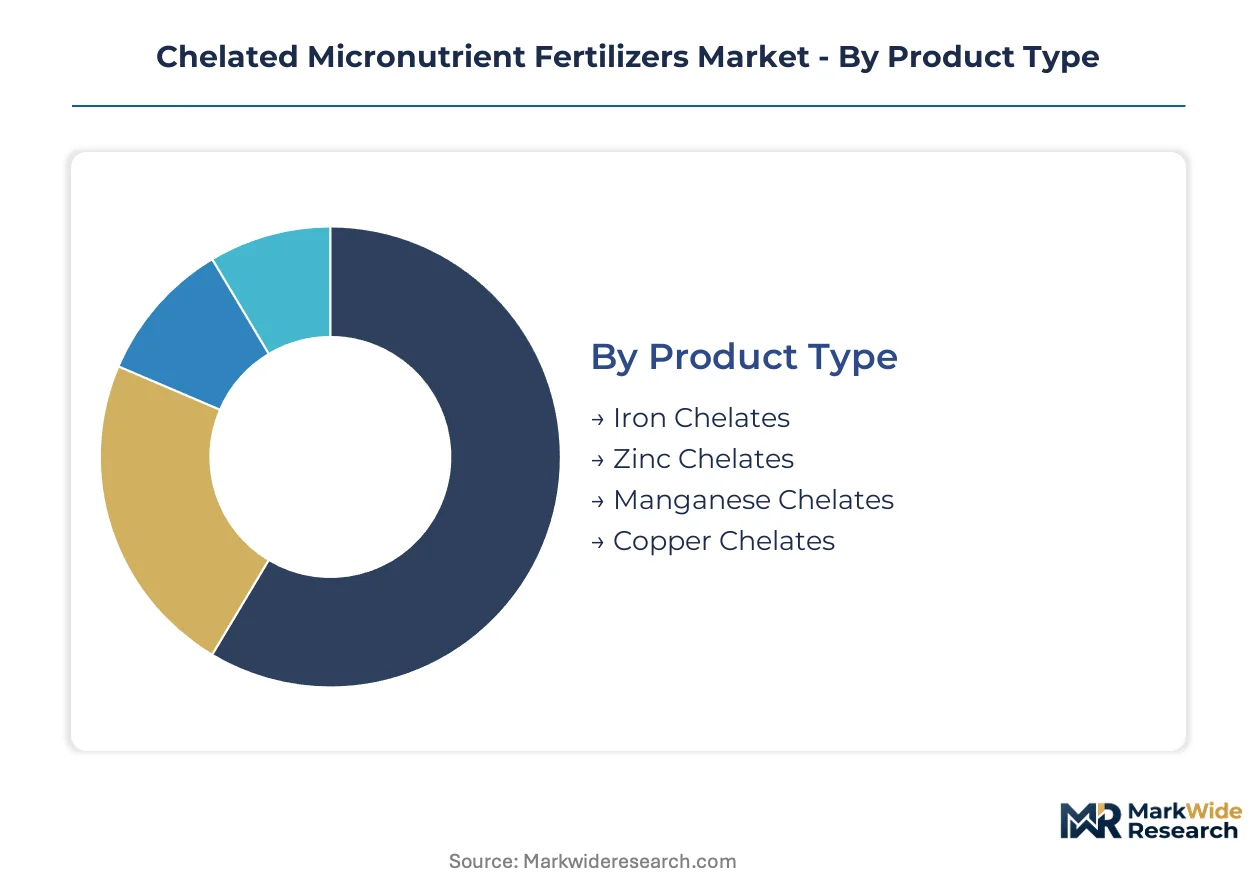
Chelated micronutrient fertilizers segment across formulation chemistry, crop system specificity, and supply chain configuration. Each dimension carries distinct margin structures and regulatory exposure that reshape supplier positioning.
Product Type:
Customization intensity varies from commodity-grade zinc formulations to precision-engineered iron complexes requiring pH-specific stability constants.
- Iron Chelates:EDDHA and HBED ligand complexes deliver plant-available Fe³⁺ across calcareous soils above pH 8.0. Spanish citrus orchards and California almond operations drive specification intensity as chlorosis treatment failures carry direct yield penalties.
- Zinc Chelates:EDTA and DTPA-bound Zn²⁺ formulations address deficiency in high-pH rice paddies and maize systems. Brazilian Cerrado soybean producers prioritize zinc chelates as soil depletion outpaces natural replenishment under intensive double-cropping.
- Manganese Chelates:Mn-EDTA complexes serve specialty crop foliar programs where soil fixation renders inorganic salts ineffective.
- Copper Chelates:Cu-chelate applications concentrate in vineyard and orchard systems with documented deficiency histories.
Leading the category by volume: Iron Chelates. Expanding most quickly: Zinc Chelates as Brazilian acreage intensifies.
Application:
End-use differentiation tracks capital intensity, from open-field broadacre to controlled-environment infrastructure requiring precision dosing systems.
- Agriculture:Row-crop deployment of granular and liquid chelates through ground-rig spraying and fertigation. Mato Grosso soybean operators integrate chelated micronutrients into variable-rate application maps tied to soil grid sampling.
- Hydroponics:Recirculating nutrient film technique systems demand ultra-pure liquid chelates with zero precipitation risk. Dutch greenhouse vegetable producers specify low-iron contamination zinc and manganese formulations to prevent root zone toxicity.
- Horticulture:Protected cultivation of berries and vegetables in Spain's Almería province drives premium chelate adoption under retailer sustainability protocols.
- Turf Management:Golf course and sports field maintenance programs utilize chelated iron for rapid green-up without foliar burn risk.
Dominant by volume: Agriculture. Steepest expansion trajectory: Hydroponics as controlled-environment acreage scales.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and inventory carrying cost tolerance across the value chain.
- Distributors:Regional cooperatives and agricultural supply houses aggregate demand across thousands of growers. India's Maharashtra and Karnataka networks blend chelates into customized NPK formulations at local mixing facilities.
- Direct Sales:Manufacturer-to-grower relationships concentrate in large-scale specialty crop operations. California Central Valley packing houses negotiate direct technical partnerships for sustainability-certified supply chains.
- Retail Stores:Farm supply outlets serve smallholder and hobbyist segments with packaged micronutrient products.
- E-commerce:Online channels gain traction among precision agriculture adopters seeking technical documentation and bulk pricing transparency.
Highest volume channel: Distributors. Gaining share fastest: Direct Sales as procurement consolidates under integrated crop nutrition platforms.
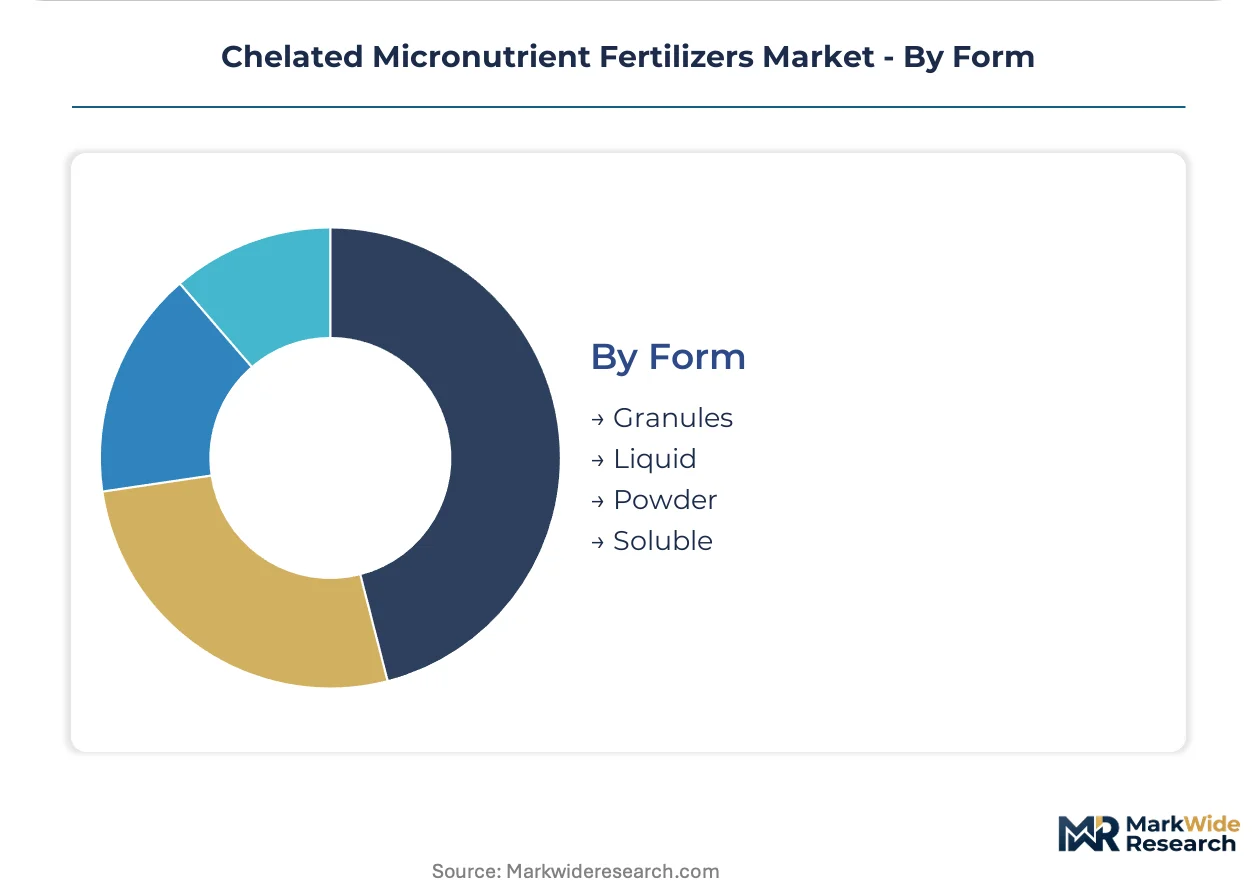
Form:
Physical state determines compatibility with application infrastructure, storage requirements, and dissolution kinetics in target soil or solution environments.
- Liquid:Ready-to-use or concentrate formulations compatible with drip irrigation, aerial spraying, and fertigation systems. Netherlands greenhouse operators specify liquid chelates for automated dosing pumps in recirculating hydroponic systems.
- Granules:Dry-blended with macronutrient fertilizers for broadcast application. Brazilian broadacre cooperatives favor granular iron chelates for compatibility with existing spreading equipment.
- Powder:Technical-grade intermediates for toll blending and export formulation.
- Soluble:Rapid-dissolution crystals for tank-mix flexibility in foliar spray programs.
Volume leader: Liquid. Climbing the fastest: Soluble as drone application and precision foliar systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates intermediate synthesis for conventional chelating agents, while Europe and Brazil drive downstream formulation demand. Consumption concentrates in agricultural regions with calcareous soils and intensive cropping systems. Regulatory divergence between jurisdictions is fragmenting product specifications and registration pathways.
United States
California's Central Valley specialty crop producers expand chelated micronutrient programs to meet retailer-driven sustainability certification requirements. The EPA governs pesticide and fertilizer registration requirements, creating compliance thresholds for imported formulations. Fresno County almond operations and Monterey County vegetable cooperatives negotiate direct technical partnerships for chlorosis treatment and foliar nutrition programs.
Brazil
Double-cropping soybean and corn operations in Mato Grosso drive premium micronutrient adoption as soil depletion outpaces conventional fertilization replacement rates. ANVISA and MAPA frameworks regulate agricultural input quality standards and heavy metal limits. The Cerrado region's intensive mechanized agriculture creates concentrated demand for zinc and iron chelates compatible with variable-rate application systems.
Germany
REACH biodegradability mandates force wholesale transition from synthetic EDTA chelates to biodegradable alternatives, compressing formulation timelines. ECHA thresholds for persistent organic pollutants in soil amendments accelerate EDDHA and IDHA investments. BASF SE leverages its Ludwigshafen specialty chemicals complex to sustain leadership in ethylenediaminetetraacetic acid alternatives.
India
Protected cultivation acreage expansion under government subsidy programs creates first-mover positioning for fertigation-compatible liquid chelate portfolios. FSSAI and BIS frameworks increasingly scrutinize heavy metal limits in agricultural inputs, reshaping import specifications. Maharashtra and Karnataka networks blend chelates into customized NPK formulations at local mixing facilities serving horticulture modernization.
Netherlands
Controlled-environment vegetable producers adopt precision-dosed liquid chelates to optimize nutrient film technique yields and reduce runoff compliance costs. The EU Fertilizing Products Regulation mandates biodegradable chelating agent standards, repositioning formulations across European agriculture. Dutch greenhouse operators in Westland specify IDHA-based iron and zinc formulations at accelerated procurement cycles for sustainability-certified supply chains.
Chelated Micronutrient Fertilizers Market Competitive Landscape
The competitive structure tilts toward integrated chemical-nutrition platforms with captive biodegradable chelate synthesis. Specialty crop segments in Southern Europe confront steep compliance costs, driving consolidation. Three archetypes dominate: diversified chemical conglomerates with agricultural divisions, dedicated crop nutrition specialists, and regional toll blenders serving price-sensitive broadacre markets. M&A activity concentrates on biodegradable chelate technology acquisition, while capacity expansion focuses on IDHA and EDDHA intermediate production.
Within the integrated platform tier, BASF SE and Yara International ASA exemplify multinational positioning across multiple continents. BASF SE anchors its stance through specialty chemicals portfolio breadth, while Yara International ASA occupies a position spanning integrated crop nutrition platforms. Haifa Group represents the precision agriculture specialist archetype, sitting within fertigation-grade micronutrient solution provision.
| Leading Market Players |
|---|
| BASF SE |
| Nouryon |
| Nufarm |
| Yara International ASA |
| Coromandel International Limited |
| Land O'Lakes, Inc. |
| ICL Group Ltd |
| Haifa Group |
| The Dow Chemical Company |
| Others |
Pricing and Supply Chain Analysis
Specialized formulation chemists concentrated in European and Israeli research institutions drive labor-cost differentials that widen pricing-tier spreads between premium biodegradable chelates and legacy EDTA formulations. This workforce scarcity amplifies margin compression for mid-tier blenders while integrated chemical-nutrition platforms capture value through captive synthesis capabilities.
Pricing Analysis
Margin tightening in standard-grade EDTA formulations reflects input cost volatility from Chinese intermediate concentration and carbon-border adjustment exposure under EU Green Deal implementation. Three-tier pricing structure across premium, standard, and economy levels separates IDHA-based biodegradable chelates certified for GLOBALG.A.P. compliance from uncertified commodity zinc formulations. Cost-down pressure on economy-tier granular products accelerates because Brazilian cooperatives prioritize compatibility with existing spreading equipment over chelate stability optimization. Smallholder segments in India's Maharashtra networks exhibit highest price sensitivity, while California Central Valley packing houses demonstrate lowest sensitivity due to retailer-driven sustainability procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from European formulators mandate multi-supplier qualification for EDDHA and IDHA intermediates to mitigate single-source vulnerability. Manufacturing gravity centers on China for conventional EDTA synthesis, Germany for specialty biodegradable agent production, and Israel for precision agriculture-grade formulations. Raw material dependencies rest on ethylenediamine derivatives, succinic acid feedstocks, and technical-grade metal salts. Tariff exposure from EU carbon-border adjustments on Chinese imports represents the dominant structural risk. Distribution runs through regional agricultural cooperatives in Brazil's Mato Grosso, Dutch greenhouse operator consortia, and California Central Valley packing house aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chelated micronutrient fertilizers market sits in a technology-transition phase where IDHA biodegradable chemistry systematically displaces legacy EDTA formulations under regulatory pressure. This substitution dynamic reshapes competitive positioning and capital allocation priorities across supplier tiers.
For Market Incumbents: Deploy captive biodegradable chelate synthesis as the priority lever to defend margin structures against commodity-grade competitors. BASF SE and Yara International ASA should accelerate Ludwigshafen and Norwegian intermediate capacity additions to secure IDHA supply security before 2030 REACH substitution deadlines. Integrated platforms must consolidate toll-blending relationships in Southern Europe where specialty crop compliance costs drive regional cooperative distress.
For New Entrants and Emerging Players: Direct-to-grower digital platforms offer the most penetrable route into fragmented Indian horticulture modernization under government protected cultivation subsidies. Maharashtra and Karnataka protected cultivation acreage expansion creates first-mover positioning for fertigation-compatible liquid chelate portfolios. Technical documentation transparency and bulk pricing visibility through e-commerce channels differentiate against established distributor-dependent competitors serving smallholder segments.
For Investors and Strategic Acquirers: Re-rating potential sits with Israeli precision agriculture specialists given drone application compatibility and carbon credit monetization catalysts. Long-term viability over the next decade hinges on biodegradable formulation expertise concentration within limited research institutions. Acquisition targets should display captive IDHA or EDDHA synthesis capabilities paired with direct technical partnerships in sustainability-certified supply chains. The signal to watch is EU-27 fertilizer registration withdrawal timelines for non-biodegradable chelating agents as inflection indicator for consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Chelate Synthesis | Captive IDHA production at Ludwigshafen secures REACH compliance before substitution deadlines. |
| Direct Technical Partnership with Grower Cooperatives | California Central Valley packing house aggregation bypasses distributor margin capture in certified supply chains. |
| Drone Application Compatibility Development | Ultra-low volume foliar formulations open Australian broadacre technical differentiation against ground-rig competitors. |
| Carbon Credit Protocol Qualification | Biodegradable chelate soil carbon sequestration verification enables premium pricing to sustainability-linked procurement. |
| Regional Cooperative Toll Blending Acquisition | Southern European specialty crop distress consolidation captures compliance-driven formulation demand. |
Research Methodology
Trade databases, EU REACH registration filings, and Brazilian MAPA agricultural input quality standards formed the secondary backbone, cross-referenced with primary interviews involving formulation chemists at European research institutions, procurement leads at Dutch greenhouse cooperatives, and technical directors at Israeli precision agriculture specialists. Bottom-up and top-down triangulation validated volume estimates across biodegradable and synthetic chelate categories.
Bottom-up modeling anchored projections across the analysis window, with segmentation dimensions spanning chelating agent chemistry, crop system specificity, application infrastructure, and supply chain configuration. CAGRs were derived from intensity-of-use coefficients tied to double-cropping expansion rates in Brazil's Cerrado and protected cultivation subsidy uptake in India. Forecast inputs incorporated regulatory substitution timelines under EU Fertilizing Products Regulation and biodegradability threshold evolution at ECHA.
Inputs from customs records and greenhouse operator procurement databases were available through the study window; gaps in smallholder segment consumption tracking introduce uncertainty bands around Indian horticulture modernization trajectory. Deviation in EU-27 enforcement timelines for persistent organic pollutant classification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Soil Conditioners Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Indonesia Fertilizer Market