
 South Africa Food Hydrocolloids Market | 2026-2036
South Africa Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Hydrocolloids Market Analytics
The gap between premium hydrocolloid formulations and commodity-grade substitutes is realigning procurement patterns across South African food manufacturing. Cargill Incorporated leverages its global supply network to secure consistent guar and xanthan streams for industrial bakeries in Johannesburg and Durban. Kerry Group PLC differentiates through specialized texture systems tailored for dairy applications, while CP Kelco anchors its position with microbial fermentation capacity serving the broader Southern African region.
Food hydrocolloids are high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to form viscous solutions or gels, with typical usage levels ranging from 0.1% to 2.0% by weight depending on the desired rheological profile. These functional ingredients primarily control water mobility, stabilize emulsions, and build texture in processed foods. Gelatin and pectin occupy mature volume positions in South African confectionery and dairy, while xanthan gum captures expanding share in gluten-free bakery and clean-label sauces where cold-soluble functionality commands margin premiums. Plant-based sources are gaining fastest traction as manufacturers reformulate away from animal-derived options to meet retailer sustainability specifications.
South Africa's Department of Health administers food additive approvals under the Foodstuffs, Cosmetics and Disinfectants Act, while SABS enforces compositional standards that directly determine which hydrocolloid grades qualify for domestic use. The country's national regulator for agricultural inputs oversees pesticide residue limits on imported seaweed extracts, tightening supply qualification for agar and carrageenan traders. Stakeholders must monitor evolving SABS purity benchmarks and import documentation requirements to avoid border delays that disrupt just-in-time manufacturing schedules.
Market Dynamics
Clean-label reformulation pressure from South African retailers is compressing formulation cycles across Gauteng and Western Cape processing clusters, forcing manufacturers to validate plant-based hydrocolloid alternatives against SABS purity benchmarks within shortened procurement windows.
Growth Catalysts
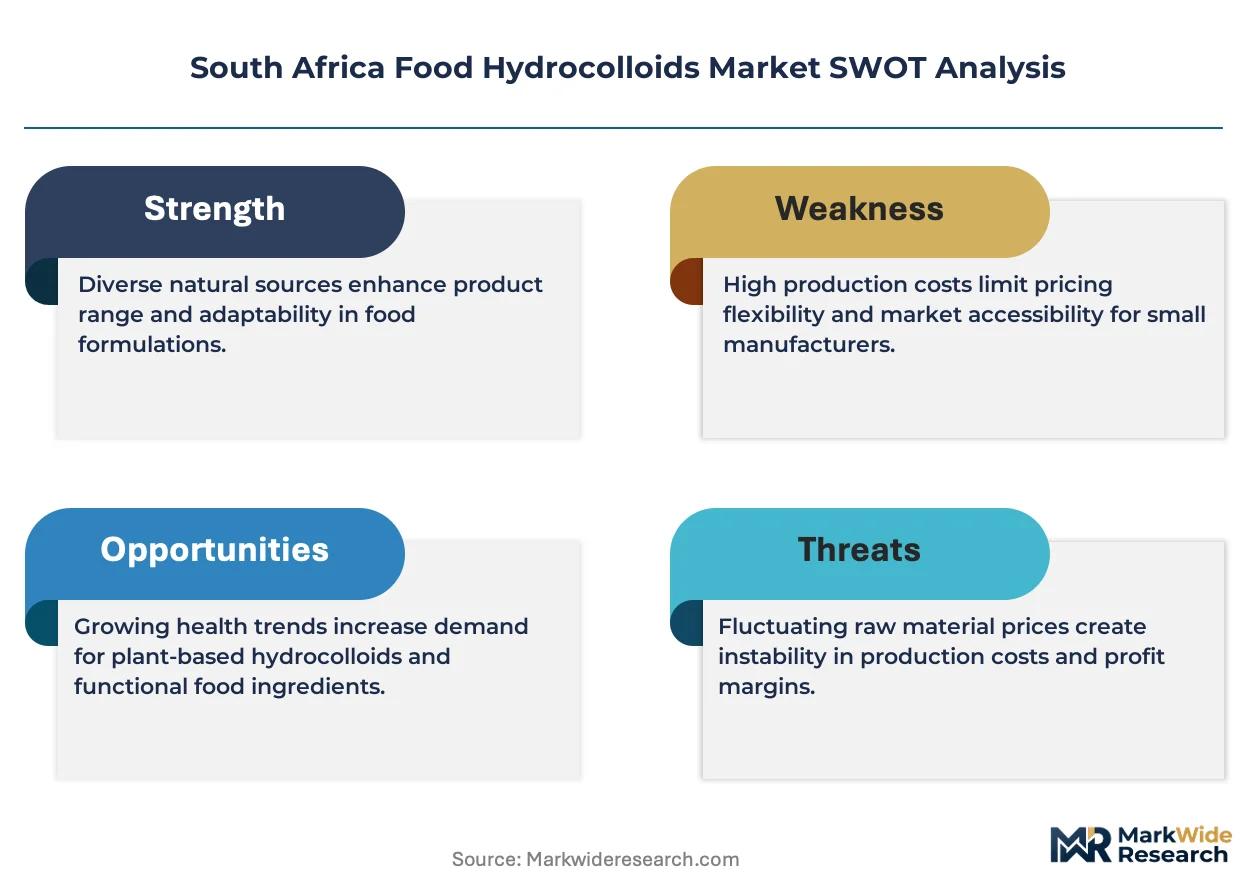
- SABS Standards Modernization:The Department of Health's tightening additive purity requirements under the Foodstuffs, Cosmetics and Disinfectants Act is accelerating qualification of high-grade pectin and xanthan for domestic dairy and confectionery applications.
- Gluten-Free Bakery Expansion:Industrial bakeries in Johannesburg and Durban are cold-processing xanthan gum into bread matrices to replace gluten networks, capturing margin premiums from health-conscious urban consumers.
- Seaweed Extract Import Diversification:Agar and carrageenan traders are qualifying new supply corridors to meet agricultural input regulator residue limits, reducing border delay risks for Western Cape dairy stabilizer manufacturers.
Market Restraints
- Guar Seed Price Volatility:Rainfall-dependent Indian harvests transmit cost spikes through Cargill's global supply network, squeezing margin buffers for Johannesburg industrial bakeries locked into annual volume contracts.
- Fermentation Capacity Concentration:Microbial xanthan production clusters in Denmark and China create single-source vulnerability for Southern African distributors serving just-in-time sauce manufacturers.
- Animal-Derived Gelatin Substitution Ceiling:Confectionery texture requirements for thermo-reversible gels limit complete displacement of bovine and porcine gelatin in premium South African candy segments.
Strategic Opportunities
- Eastern Cape Processing Greenfield:Underdeveloped dairy ingredient blending infrastructure around Gqeberha offers first-mover positioning for hydrocolloid texture system providers targeting expanding cheese analog production.
- Clean-Label Sauce Cold Solubility:Xanthan-guar synergistic blends enabling ambient-stable emulsions without heat activation are penetrating retail condiment private-label programs across Shoprite and Pick n Pay supply chains.
- Biotechnology Investment Incentives:South Africa's Department of Science and Innovation R&D tax credits support domestic microbial fermentation pilot facilities, reducing import dependence for specialty hydrocolloids.
Industry Challenges
- Formulation Scientist Scarcity:Rheology and food polymer chemistry expertise shortages in Gauteng technical service teams extend new product development timelines for bakery and dairy manufacturers.
- Dual Certification Burden:Simultaneous SABS compositional compliance and retailer sustainability audit requirements create documentation bottlenecks delaying ingredient approval for Western Cape exporters.
- Legacy Equipment Retrofit Costs:Cold-soluble hydrocolloid adoption requires pneumatic conveying and high-shear dispersion upgrades incompatible with apartheid-era dry-mix infrastructure still operational in several Durban plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Hydrocolloids Market |
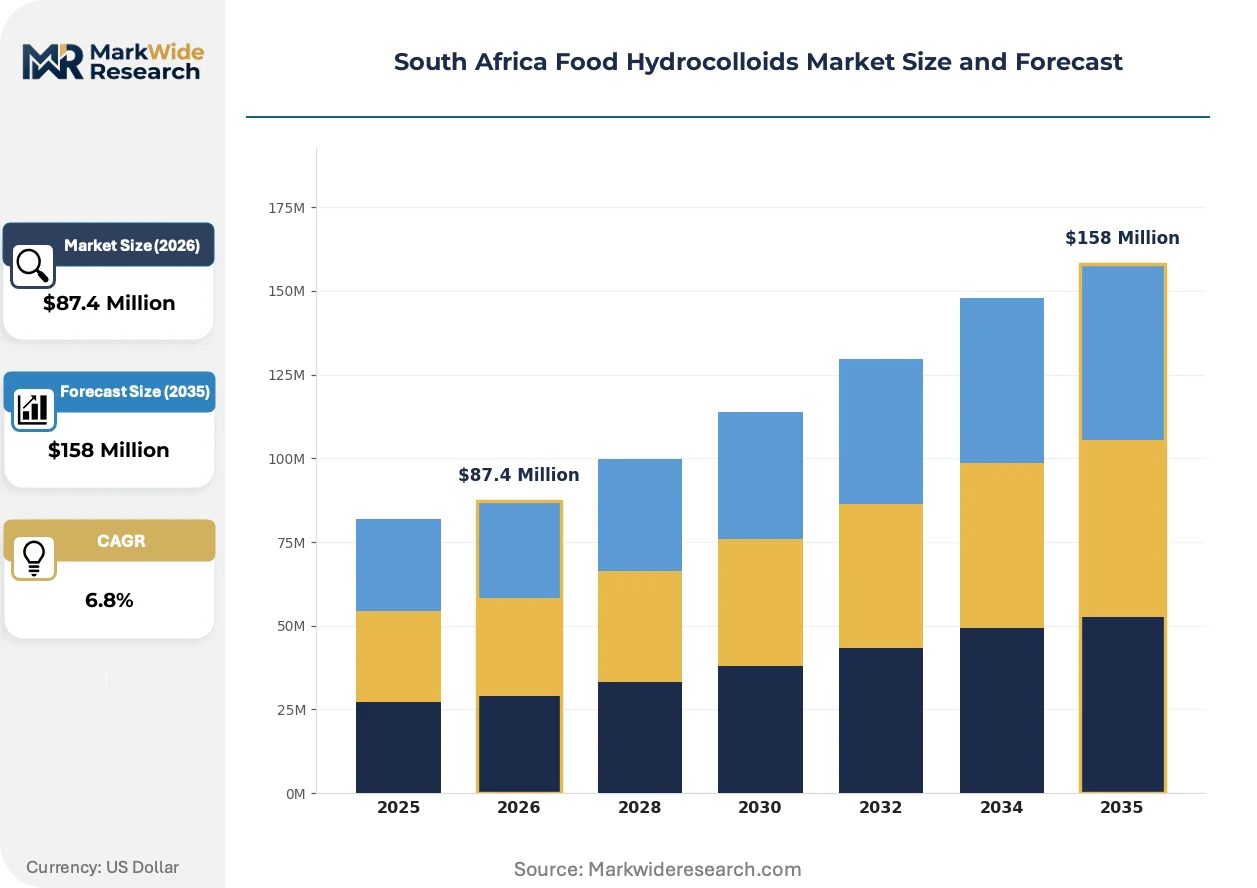
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Xanthan Gum Application: Dairy Products, Confectionery, Bakery, Sauces Source: Animal-Based, Plant-Based, Microbial, Synthetic Form: Powder, Granule, Liquid, Sheet |
| Companies Covered | Tranarc Holdings (Pty) Ltd, Ingredion Incorporated, Palani Group, Cargill Incorporated, Kerry Group PLC, CP Kelco, Koninklijke DSM NV, DuPont de Nemours Inc., Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Hydrocolloids Market Evolving Landscape
Electrification of hydrocolloid functionality—through precision fermentation and enzymatic modification—is collapsing the performance gap between commodity and specialty grades, redrawing competitive boundaries across South African food manufacturing.
Cold-soluble xanthan gum variants produced via controlled fermentation kinetics are electrifying clean-label sauce formulation in Johannesburg and Cape Town retail manufacturing. Mid-tier condiment producers are adopting these grades within eighteen-month equipment refresh cycles, compressing the premium commanded by legacy heat-hydrating hydrocolloids and forcing reformulation service providers to bundle technical support with commodity supply.
South Africa's Department of Health has proposed maximum residue limits for pesticide contaminants in imported seaweed extracts, aligning with agricultural input regulator frameworks governing agar and carrageenan border entry. This regulatory convergence is disqualifying informal trading channels and consolidating import authorization among Durban and Cape Town distributors with dedicated compliance documentation teams.
Direct supplier relationships between hydrocolloid manufacturers and large South African retail private-label programs are displacing traditional ingredient distributor networks in bakery and dairy procurement. Shoprite Holdings and Woolworths Holdings technical teams now specify texture systems directly with Kerry Group and CP Kelco technical service, compressing margin layers for Johannesburg-based intermediaries and accelerating formulation validation timelines.
South Africa Food Hydrocolloids Market Segmentation
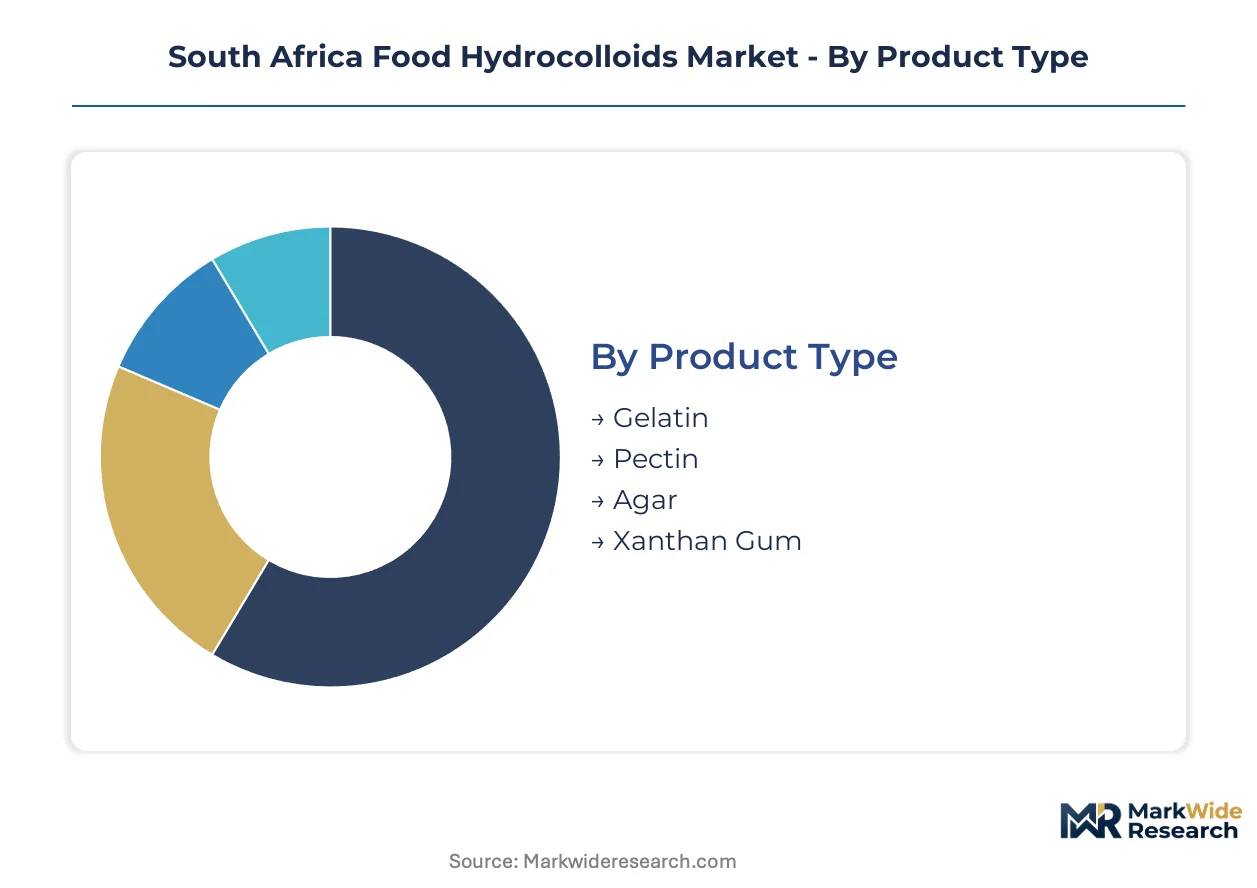
Segmentation in South Africa's food hydrocolloids market reveals distinct capital requirements, sourcing constraints, and regulatory exposure profiles that determine supplier profitability and manufacturer procurement strategy across Gauteng and Western Cape processing corridors.
Product Type:
Capital intensity varies sharply across hydrocolloid chemistries, with fermentation-based production demanding the heaviest upfront investment in sterile bioreactor infrastructure.
- Xanthan Gum:Microbial fermentation via Xanthomonas campestris requires controlled bioprocessing facilities with capital outlays exceeding those of extraction-based alternatives. Johannesburg industrial bakeries and Cape Town sauce manufacturers are accelerating cold-soluble grade adoption to capture clean-label premiums, though SABS purity documentation requirements extend qualification timelines.
- Gelatin:Acid and alkali extraction from bovine and porcine collagen demands rendering plant infrastructure with wastewater treatment systems sized for high organic load. Durban confectionery producers maintain volume positions here despite retailer pressure to reduce animal-derived ingredients, as thermo-reversible gel functionality remains unmatched in premium candy segments.
- Pectin:Citrus peel extraction from imported dried pomace requires acid hydrolysis vessels and alcohol precipitation capacity concentrated among Western Cape dairy stabilizer blenders.
- Agar:Red seaweed harvesting and hot-water extraction face agricultural input regulator residue screening that disqualifies informal import channels for Gauteng microbiology media applications.
Xanthan gum absorbs the bulk of installed fermentation capacity; agar is expanding most quickly as seaweed extract traders qualify compliant supply corridors.
Application:
Application segments diverge by formulation complexity, with multi-hydrocolloid texture systems commanding higher technical service intensity than single-ingredient commodity sales.
- Dairy Products:Yoghurt stabilizer and cream cheese texture applications require pectin-carrageenan synergies with precise calcium sensitivity tuning. Western Cape processing clusters around Stellenbosch and Paarl are retrofitting high-shear dispersion equipment to handle cold-soluble hydrocolloid adoption without heat activation steps.
- Bakery:Gluten-free bread matrices depend on xanthan-guar networks to replace viscoelastic gluten structures, with Johannesburg industrial bakeries validating hydration kinetics against apartheid-era mixing infrastructure limitations.
- Confectionery:Thermo-reversible gel requirements in gummy candy limit complete gelatin displacement despite retailer sustainability specifications.
- Sauces:Ambient-stable emulsions in retail condiment private-label programs favor xanthan-guar cold-soluble blends penetrating Shoprite and Pick n Pay supply chains.
Dairy applications anchor current formulation service revenue; bakery is climbing the fastest on gluten-free segment expansion.
Source:
Source classification determines regulatory exposure and supply chain vulnerability, with microbial and plant-based options attracting procurement preference under tightening retailer sustainability audits.
- Plant-Based:Guar, locust bean, and tara gum extraction from Indian and South American seed crops faces rainfall-dependent harvest volatility that transmits through Cargill's global supply network to Johannesburg industrial bakeries.
- Microbial:Fermentation-derived xanthan and gellan production clusters in Denmark and China create single-source vulnerability for Southern African distributors serving just-in-time sauce manufacturers.
- Animal-Based:Bovine and porcine gelatin rendering operates under Department of Health traceability requirements that extend documentation burdens for Durban confectionery exporters.
- Synthetic:Cellulose derivatives including CMC and HPMC occupy niche pharmaceutical and reduced-calorie food applications with limited South African manufacturing presence.
Plant-based sourcing dominates current procurement volume; microbial is gaining share fastest on clean-label reformulation timelines.
Form:
Physical form selection drives equipment compatibility and dispersion efficiency, with powder grades requiring pneumatic conveying infrastructure that legacy Durban plants often lack.
- Powder:Spray-dried and roller-dried particulates with standardized mesh sizes enable bulk pneumatic handling but demand dust collection systems and high-shear dispersion units for lump-free hydration.
- Liquid:Pre-hydrated colloidal suspensions eliminate dispersion equipment requirements for small-batch sauce manufacturers in Cape Town metropolitan area, though preservative systems add formulation complexity.
- Granule:Agglomerated particles with reduced dusting characteristics suit manual addition protocols still operational in several Eastern Cape dairy ingredient blending facilities.
- Sheet:Dried agar and gelatin films for traditional confectionery and microbiology media applications require manual rehydration protocols with limited automation compatibility.
Powder form commands the greatest installed handling infrastructure; liquid is expanding most quickly among mid-tier condiment producers with compressed equipment refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg anchors South African food hydrocolloid demand through its dense cluster of industrial bakeries and sauce manufacturers concentrated in the Gauteng processing corridor.
Gauteng Province
Gluten-free bakery expansion and clean-label sauce reformulation drive hydrocolloid consumption in Johannesburg and Pretoria manufacturing zones. The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act governs additive approvals here. Industrial bakeries in East Rand and Vereeniging corridors validate xanthan-guar cold-soluble blends against legacy mixing infrastructure constraints.
Western Cape
Dairy stabilizer applications and wine industry byproduct pectin extraction concentrate demand around Stellenbosch and Paarl. SABS compositional standards enforcement determines which hydrocolloid grades qualify for domestic use. Processing clusters retrofit high-shear dispersion equipment to handle cold-soluble hydrocolloid adoption without heat activation steps.
KwaZulu-Natal
Durban's confectionery manufacturers and port logistics infrastructure position the province for seaweed extract import handling. The national agricultural input regulator screens pesticide residue limits on agar and carrageenan shipments entering through Durban harbor. Confectionery producers in Pinetown and Prospecton industrial zones maintain gelatin volume positions despite retailer sustainability pressure.
Eastern Cape
Underdeveloped dairy ingredient blending infrastructure around Gqeberha offers expansion potential for hydrocolloid texture system providers. The Department of Science and Innovation R&D tax credits support pilot fermentation facilities in the region. Cheese analog production growth in Nelson Mandela Bay metropolitan area attracts first-mover hydrocolloid suppliers.
North West Province
Mining belt food service and institutional catering channels create secondary hydrocolloid demand through processed sauce and bakery supply. Provincial health department food safety inspections align with national Department of Health frameworks. Rustenburg and Mahikeng distribution hubs serve as inland logistics nodes for hydrocolloid shipments to Botswana and Namibia border zones.
South Africa Food Hydrocolloids Market Competitive Landscape
Capital-heavy fermentation-based producers compete with asset-light extraction and trading specialists across South African food hydrocolloid supply. The market structures around three tiers: global integrated conglomerates with captive bioprocessing capacity, regional texture system formulators with technical service depth, and import-dependent commodity traders serving price-sensitive mid-tier manufacturers. Dominant competitive moves include strategic partnerships between hydrocolloid manufacturers and retail private-label technical teams, plus portfolio diversification into plant-based alternatives ahead of SABS purity standard tightening.
Within the global integrated tier, Cargill Incorporated and Kerry Group PLC exemplify divergent strategic positioning—Cargill anchoring commodity supply security through global sourcing networks, Kerry occupying specialized texture system formulation with dairy application focus. CP Kelco represents the fermentation-capable specialist archetype with microbial production infrastructure serving broader Southern African regional demand. These three entities illustrate how supplier profitability separates between volume-scale commodity logistics and technical service-intensive formulation partnerships.
| Leading Market Players |
|---|
| Tranarc Holdings (Pty) Ltd |
| Ingredion Incorporated |
| Palani Group |
| Cargill Incorporated |
| Kerry Group PLC |
| CP Kelco |
| Koninklijke DSM NV |
| DuPont de Nemours Inc. |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Indian monsoon variability in guar seed harvests transmits directly through Cargill's global procurement network into Johannesburg industrial bakery input costs, stratifying hydrocolloid procurement across premium fermentation-grade, standard extraction-grade, and economy commodity-tier price bands.
Pricing Analysis
Cold-soluble functionality in xanthan gum commands value-based pricing anchored to clean-label sauce yield improvements and reduced heat-processing energy costs. Three-tier pricing structure across premium, standard, and economy levels separates SABS-certified pharmaceutical-grade hydrocolloids from food-grade commodities and uncertified imports. Cost compression in economy guar segments is intensifying because rainfall-dependent Indian harvests destabilize forward contract pricing. Mid-tier condiment manufacturers exhibit highest price sensitivity, while Western Cape dairy stabilizer blenders accept premium positioning for pectin-carrageenan texture systems.
Supply Chain Analysis
Seaweed extract residue screening failures at Durban harbor generate reverse-logistics flows of non-compliant agar and carrageenan shipments back to Indonesian and Philippine suppliers for reprocessing or alternative market disposition. Fermentation-derived xanthan production concentrates in Denmark and China, while guar seed extraction clusters in India and Pakistan, and gelatin rendering feeds from Brazilian and Argentine bovine processing. Single-source vulnerability in microbial fermentation capacity creates supply chain risk for Southern African distributors serving just-in-time sauce manufacturers. Distribution runs through Johannesburg bulk handling terminals and Cape Town port warehousing for Western Cape dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SABS purity standard tightening under the Foodstuffs, Cosmetics and Disinfectants Act erects a cost-of-compliance barrier that consolidates procurement authorization among documentation-capable distributors and disqualifies informal trading channels.
For Market Incumbents: Deploy technical service bundling as the primary defensive lever against direct manufacturer-retail partnerships displacing traditional distributor networks. Kerry Group and CP Kelco should expand microbial fermentation technical support teams in Gauteng to defend formulation service revenue against Cargill's commodity supply security positioning. Capacity addition in Western Cape high-shear dispersion infrastructure captures dairy retrofit demand. For New Entrants and Emerging Players: Department of Science and Innovation R&D tax credits in South Africa open a window for domestic pilot fermentation facilities to capture biotechnology investment incentives and reduce import dependence. Eastern Cape cheese analog production around Gqeberha represents the most penetrable geography, with first-mover positioning available for texture system providers. Go-to-market angle: partner with Nelson Mandela Bay metropolitan area dairy processors for co-development of clean-label stabilizer blends. For Investors and Strategic Acquirers: SABS documentation team buildout among Durban distributors is the leading indicator that regulatory compliance consolidation is accelerating and margin compression for uncertified traders is structural. Long-term viability favors acquisition targets with captive fermentation capacity or established SABS certification workflows rather than pure-play import traders. Signal to watch: direct supplier relationships between hydrocolloid manufacturers and Shoprite or Woolworths technical teams bypassing distributor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Seed Sourcing | Cargill's Indian procurement network secures supply continuity for Johannesburg industrial bakeries facing rainfall volatility. |
| Microbial Fermentation Capacity Expansion | CP Kelco's bioreactor infrastructure in Denmark reduces Southern African import dependence for specialty xanthan grades. |
| SABS Certification Investment Program | Durban distributors with dedicated compliance documentation teams capture agar and carrageenan import authorization consolidation. |
| Direct Retail Technical Partnership | Kerry Group's formulation collaboration with Shoprite Holdings accelerates private-label sauce development timelines. |
| Cold-Soluble Grade Product Launch | Xanthan-guar synergistic blends penetrate Pick n Pay supply chains with ambient-stable emulsion functionality. |
Research Methodology
Multi-period observation of SABS purity benchmark evolution and retailer sustainability audit adoption anchored the trend analysis, supplemented by interviews with hydrocolloid procurement managers at Johannesburg industrial bakeries, Western Cape dairy stabilizer blenders, Durban seaweed extract traders, and Cape Town sauce manufacturers. Secondary validation drew from Foodstuffs, Cosmetics and Disinfectants Act regulatory filings, SABS compositional standard updates, Department of Science and Innovation R&D tax credit utilization records, and agricultural input regulator residue limit determinations. Bottom-up volume modeling across Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape processing corridors triangulated against top-down expenditure flow analysis.
The input-output matrix framework mapped hydrocolloid consumption to downstream food manufacturing output across bakery, dairy, confectionery, and sauce applications. Segmentation dimensions modeled include product type chemistry, application formulation complexity, source classification, and physical form handling requirements. CAGRs were derived from trend extrapolation of clean-label reformulation adoption rates and gluten-free bakery segment expansion. Industry-specific forecast inputs encompassed SABS standard modernization timelines and cold-soluble grade equipment refresh cycle penetration.
The model assumes a particular technology adoption path for precision fermentation and enzymatic modification; alternative pathways for microbial production scale-up would alter the outlook for specialty-grade pricing premiums. Forecasts reflect assumptions regarding SABS enforcement intensity and retailer sustainability specification tightening. Practitioners should monitor Department of Health residue limit proposals for imported seaweed extracts and direct manufacturer-retail partnership announcements for early signals of distributor network displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Fermentation Defoamer Market