
 Food-Grade Monopotassium Phosphate Market | 2026-2036
Food-Grade Monopotassium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Food-Grade Monopotassium Phosphate Market Analytics
The split between premium and commodity tiers is repositioning procurement patterns across the food-grade monopotassium phosphate value chain. Xingfa Chemicals Group leverages captive phosphate rock mining to sustain cost leadership in bulk powder grades. ICL Phosphate Specialty differentiates through kosher and halal-certified production lines for bakery and beverage clients. Budenheim anchors European supply with dedicated pharmaceutical-grade facilities serving nutraceutical formulators.
Food-grade monopotassium phosphate is a potassium dihydrogen phosphate salt manufactured through controlled neutralization of phosphoric acid with potassium hydroxide, yielding a minimum assay of 98 percent and pH range of 4.2 to 4.6 in aqueous solution. Its primary function spans pH buffering in processed cheese, leavening acid in baking powders, and mineral fortification in sports beverages. Powder formulations dominate volume flows into food additive applications where dispersibility commands premium positioning over granular alternatives. Direct sales channels capture the largest margin pools by locking pharmaceutical and cosmetics end users into multi-year purity agreements.
FDA food additive regulations under 21 CFR 182.1087 and EFSA purity standards for phosphate additives shape formulation specifications and import documentation burdens. China's SAMR enforces GB 25560 national food safety standards that determine market access for domestic and foreign producers. Stakeholders must monitor evolving phosphate intake limits from WHO technical committees and national health agencies.
Market Dynamics
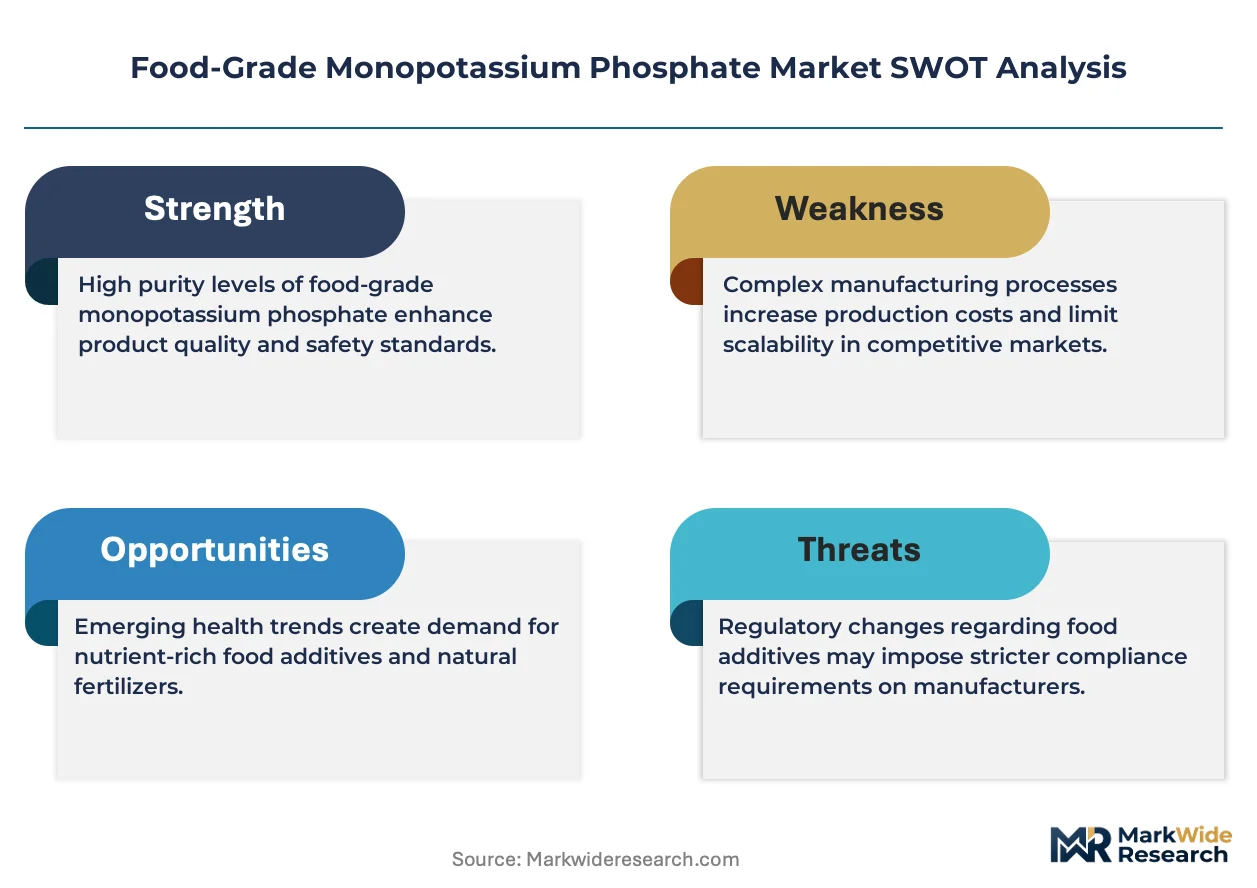
Phosphate rock supply concentration in China's Guizhou and Yunnan provinces is compressing global pricing power into a handful of vertically integrated processors, forcing Western buyers to accept longer contract terms and purity-grade trade-offs.
Growth Catalysts
- EU F-Gas Regulation:Tightening purity thresholds for imported food additives are disqualifying marginal suppliers and consolidating demand around certified producers with dedicated pharmaceutical-grade lines.
- Processed cheese stabilization:Meat and dairy manufacturers are expanding phosphate buffer adoption to extend shelf life and improve emulsion stability in reformulated low-sodium products.
- Sports beverage fortification:Electrolyte mineral enrichment in functional drinks is pulling food-grade monopotassium phosphate into high-volume premix contracts with co-packing networks.
Market Restraints
- Phosphate rock cost volatility:Energy-intensive mining and beneficiation in concentrated Chinese clusters exposes margins to electricity pricing swings and export quota fluctuations.
- REACH compliance friction:ECHA registration requirements and contaminant testing protocols impose documentation burdens that delay market entry for new import sources.
- Citrate substitution threat:Sodium and potassium citrates are displacing phosphates in clean-label bakery applications where phosphate-free positioning commands retail shelf space.
Strategic Opportunities
- India nutraceutical expansion:FSSAI-aligned mineral fortification mandates in infant formula and clinical nutrition are opening import channels for certified food-grade phosphate suppliers.
- Kosher and halal certification premium:Religious dietary certification lines capture margin pools in Middle Eastern and North African markets where import specifications exclude standard-grade material.
- Direct-to-formulator e-commerce:Digital procurement platforms are compressing distributor layers for mid-volume pharmaceutical and cosmetics compounders seeking multi-year purity agreements.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and ion chromatography expertise for heavy metal and fluoride testing is concentrating in legacy phosphate processing regions, constraining quality control scale-up.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and SAMR approval tracks for new production facilities extend commercialization cycles by 18-24 months.
- Legacy ERP integration:Batch traceability systems for 21 CFR Part 117 compliance require retrofitting older phosphate plants with serialized inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food-Grade Monopotassium Phosphate Market |
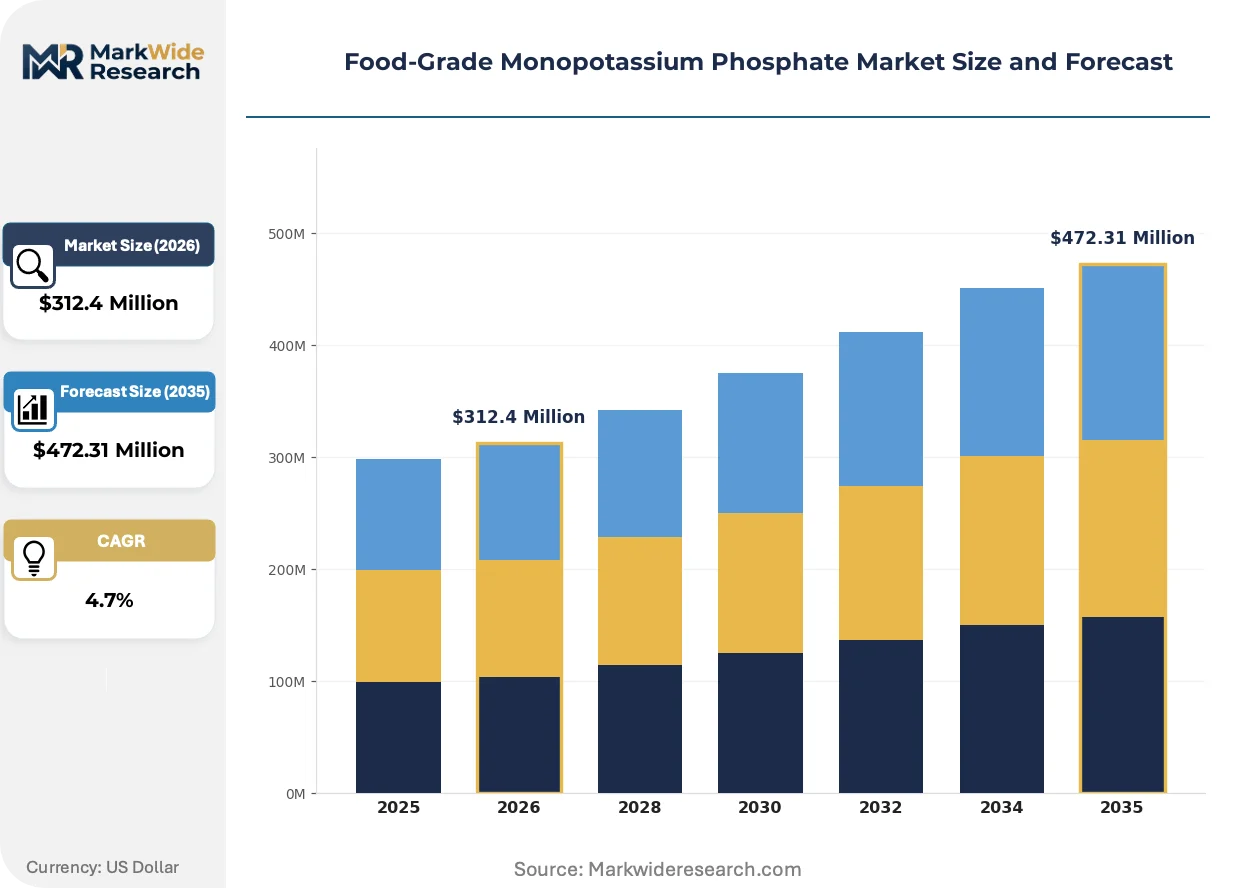
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Tablet Application: Food Additive, Fertilizer, Animal Feed, Nutraceuticals End User: Food Processing, Agriculture, Pharmaceutical, Cosmetics Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Xingfa Chemicals Group, Chengxing Industrial Group, Hawkins Inc., Choice Chemicals Ltd., Mianyang Aostar, ICL Phosphate Specialty, Blue Sword Chemical, Shijiazhuang Lemandou, Budenheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food-Grade Monopotassium Phosphate Market Evolving Landscape
Spray-dried agglomeration technology and real-time process analytical chemistry are compressing specification variance and enabling just-in-time contract manufacturing for regional food processors.
Spray-dried monopotassium phosphate agglomerates are replacing conventional milled powders in automated dosing systems for industrial bakeries. European and North American co-manufacturers are retrofitting pneumatic conveying lines to handle engineered particle densities. This technology shift is unifying dispersibility performance across humidity-variable production environments, collapsing the traditional powder-versus-granular grade distinction.
EFSA's revised acceptable daily intake evaluations for phosphate additives are triggering reformulation audits across processed meat and cheese categories. Manufacturers are submitting updated safety dossiers to retain existing uses while defending against downward pressure on maximum permitted levels. The beverage sector faces the steepest compliance curve, as sports drink formulators must reconcile mineral fortification claims with cumulative phosphate exposure calculations.
Compounders are consolidating supplier relationships around dual-certified producers capable of delivering pharmaceutical and food-grade material from common production assets. Long-term offtake agreements with minimum purity floors are displacing spot market purchases for strategic mineral inputs. This concentration is most pronounced in Germany and the Netherlands, where nutraceutical contract manufacturers are qualifying single-source partners for multi-year supply security.
Food-Grade Monopotassium Phosphate Market Segmentation
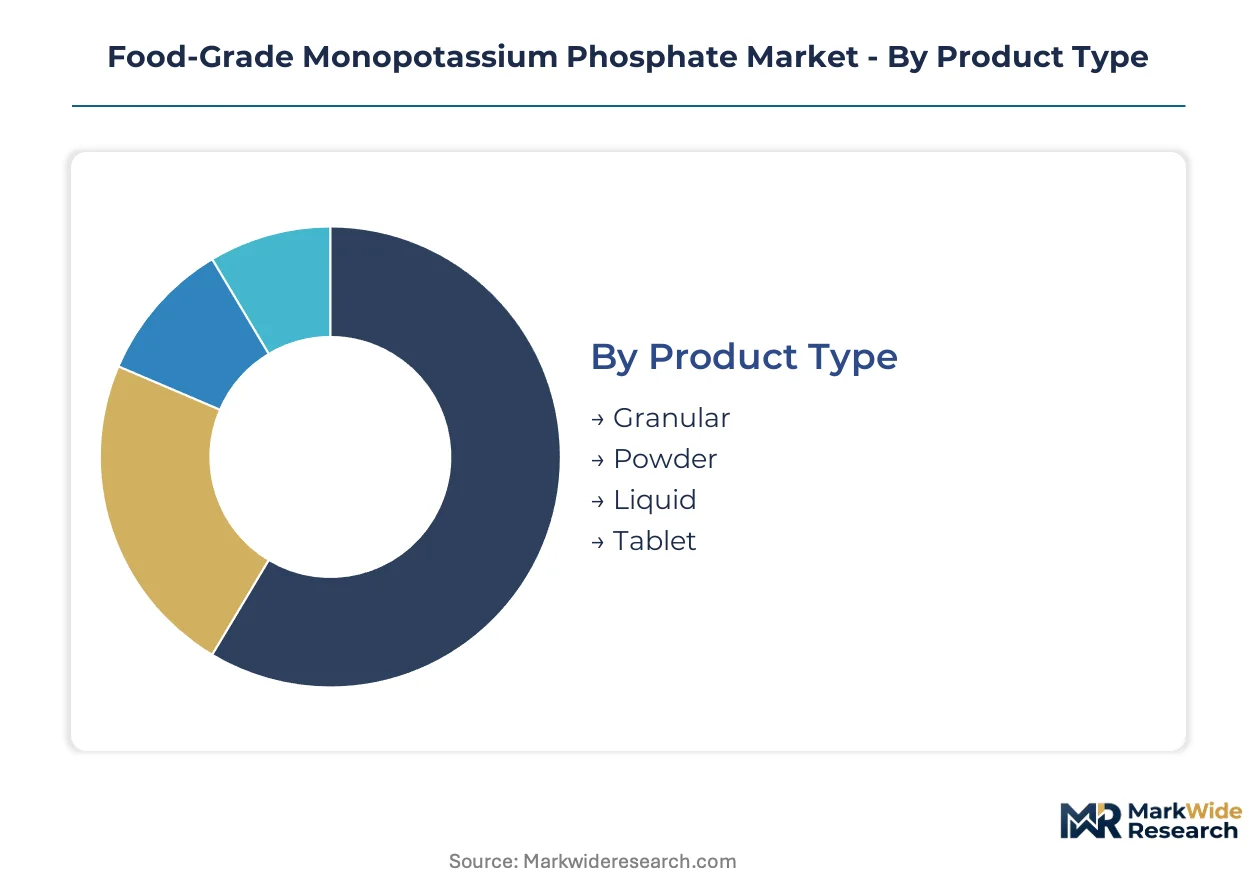
Food-grade monopotassium phosphate exhibits divergent margin profiles across physical forms and customer touchpoints. Procurement patterns split between bulk industrial buyers seeking specification consistency and specialized formulators demanding certified purity tiers.
Product Type:
Capital intensity escalates from simple milling operations to engineered agglomeration systems requiring spray-drying towers and real-time particle size control.
- Powder:Milled crystalline material with controlled particle size distribution dominates food additive volumes. Demand concentrates in processed cheese manufacturers across Wisconsin and Bavaria seeking rapid dispersibility in high-shear mixing environments. pH buffering specifications from FDA 21 CFR 182.1087 and EFSA additive regulations lock powder grades into multi-year supply agreements with minimal substitution risk.
- Granular:Compacted agglomerates with engineered bulk density serve automated dosing systems in industrial bakeries. European co-manufacturers in the Netherlands and northern Italy are retrofitting pneumatic conveying lines to handle these engineered particle densities, collapsing traditional powder-versus-granular performance distinctions.
- Liquid:Pre-dissolved aqueous solutions eliminate dust handling for beverage compounders.
- Tablet:Compressed mineral supplements target direct-to-consumer nutraceutical channels.
Most installed capacity flows through Powder. Expansion is steepest in Granular.
Application:
Regulatory burden varies sharply across end-uses, with food additive registrations demanding multi-jurisdiction dossier submissions while fertilizer applications face simpler purity declarations.
- Food Additive:pH buffering, leavening acid, and emulsion stabilization functions in processed cheese, baked goods, and meat products. Demand clusters in reformulated low-sodium dairy lines where phosphate buffers extend shelf life. SAMR's GB 25560 enforcement in China and EFSA's revised acceptable daily intake evaluations are triggering reformulation audits across processed meat categories.
- Nutraceuticals:Mineral fortification in sports beverages, infant formula, and clinical nutrition products. German and Dutch contract manufacturers are consolidating supplier relationships around dual-certified producers capable of delivering pharmaceutical and food-grade material from common production assets.
- Fertilizer:Agricultural-grade applications with lower purity thresholds.
- Animal Feed:Livestock mineral supplementation with regional feed safety compliance.
Food Additive commands the dominant revenue share. Nutraceuticals is expanding most quickly.
End User:
Customer scale determines contract structure, with multinational food processors locking multi-year offtake agreements while regional cosmetics compounders tolerate spot market variability.
- Food Processing:Meat, dairy, and bakery manufacturers requiring batch-to-batch specification consistency. Processed cheese stabilization demand is pulling phosphate buffers into high-volume premix contracts with co-packing networks across the American Midwest and northern France.
- Pharmaceutical:Excipient and active mineral source applications with USP-grade purity requirements. Direct sales channels capture the largest margin pools by locking pharmaceutical end users into multi-year purity agreements with guaranteed heavy metal and fluoride thresholds.
- Agriculture:Fertilizer blenders and feed mills with price-sensitive procurement.
- Cosmetics:Buffer systems for personal care formulations.
Food Processing absorbs the greatest volume. Pharmaceutical offers the steepest margin expansion trajectory.
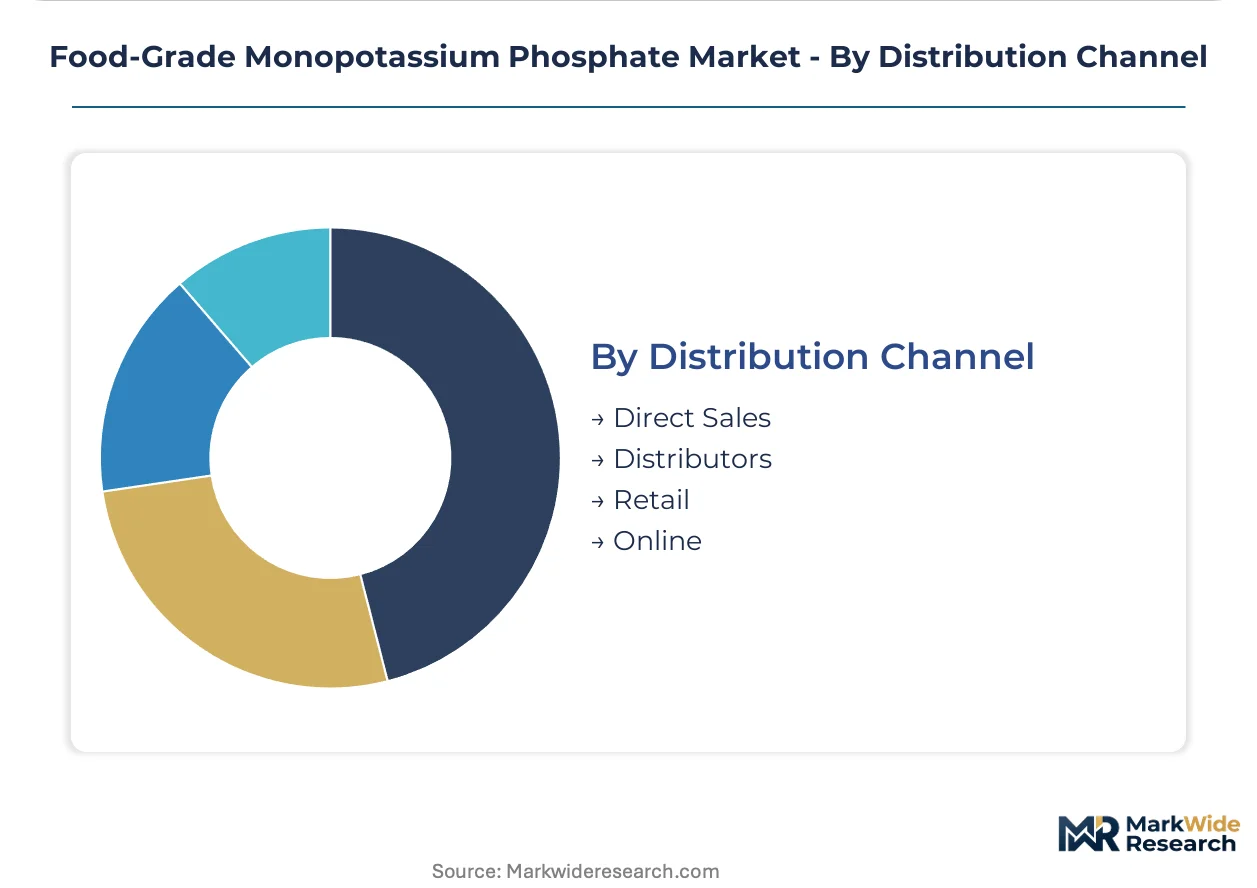
Distribution Channel:
Channel economics reflect customer technical sophistication, with certified buyers bypassing distributor markups while smaller formulators rely on technical service intermediaries.
- Direct Sales:Producer-to-formulator relationships for pharmaceutical and cosmetics compounders. Long-term offtake agreements with minimum purity floors are displacing spot market purchases for strategic mineral inputs, particularly in Germany and the Netherlands.
- Distributors:Technical service intermediaries serving mid-volume food processors.
- Online:Digital procurement platforms compressing distributor layers for mid-volume pharmaceutical and cosmetics compounders.
- Retail:Packaged goods for small-scale nutraceutical and cosmetics formulators.
Direct Sales anchors value capture. Online channels are gaining share fastest among mid-tier buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands phosphate rock processing capacity while Germany anchors European pharmaceutical-grade demand, creating divergent procurement geographies for food additive versus nutraceutical applications.
China
Guizhou and Yunnan provinces host vertically integrated phosphate mining clusters supplying domestic food processors and export markets. SAMR's GB 25560 enforcement tightens purity documentation for both local manufacturers and foreign importers seeking market access. Xingfa Chemicals Group leverages captive phosphate rock mining to sustain cost leadership in bulk powder grades serving processed cheese and bakery stabilizer demand.
Germany
Nutraceutical contract manufacturers in North Rhine-Westphalia consolidate supplier relationships around dual-certified producers. EFSA's revised acceptable daily intake evaluations trigger reformulation audits across processed meat categories. Budenheim anchors European supply with dedicated pharmaceutical-grade facilities serving nutraceutical formulators in the Netherlands and Belgium.
United States
Wisconsin dairy processors drive phosphate buffer demand for processed cheese stabilization and low-sodium reformulations. FDA 21 CFR 182.1087 locks powder grades into multi-year supply agreements with minimal substitution risk. Hawkins Inc. occupies a position among domestic distributors serving mid-volume food processors across the American Midwest.
India
FSSAI-aligned mineral fortification mandates in infant formula and clinical nutrition open import channels for certified suppliers. Maharashtra and Gujarat host expanding nutraceutical manufacturing clusters seeking pharmaceutical-grade phosphate inputs. Domestic food processors in Haryana and Delhi-NCR adopt phosphate buffers for bakery and dairy applications.
Netherlands
Co-manufacturers in northern provinces retrofit pneumatic conveying lines for engineered granular phosphate densities. REACH compliance requirements impose documentation burdens that delay market entry for new import sources. Rotterdam logistics hubs facilitate distribution of certified material into German and Belgian nutraceutical markets.
Food-Grade Monopotassium Phosphate Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification, while commodity-grade processors compete on phosphate rock access and energy efficiency. The vendor base stratifies across three tiers: integrated miners with captive rock supply, regional chemical specialists with formulation expertise, and trading houses sourcing from multiple production origins. Two strategic archetypes dominate—vertically integrated Chinese producers controlling upstream phosphate rock and European specialists commanding kosher-halal certification premiums. Capacity expansion in spray-dried agglomeration and backward integration into phosphate mining represent the primary competitive moves.
Among China-based integrated producers, Xingfa Chemicals Group and Chengxing Industrial Group exemplify the cost-leadership archetype through upstream control of Guizhou phosphate deposits. ICL Phosphate Specialty occupies a position within the certification-premium tier, representing producers that differentiate through religious dietary compliance for Middle Eastern and North African markets. Budenheim anchors the European pharmaceutical-grade segment, sitting within the quality-specialist archetype serving nutraceutical formulators with dedicated facility assets.
| Leading Market Players |
|---|
| Xingfa Chemicals Group |
| Chengxing Industrial Group |
| Hawkins Inc. |
| Choice Chemicals Ltd. |
| Mianyang Aostar |
| ICL Phosphate Specialty |
| Blue Sword Chemical |
| Shijiazhuang Lemandou |
| Budenheim |
| Others |
Value Network & Pricing Analysis
ICP-MS analytical chemistry talent concentration in Guizhou and Yunnan provinces feeds directly into cost differentials between pharmaceutical-grade and commodity powder tiers. Labor scarcity for heavy metal and fluoride testing expertise in Western markets widens the premium spread that certified producers command over standard-grade competitors.
Pricing Analysis
Bundled certification-and-testing services separate premium pricing from unbundled commodity transactions. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels anchors contract structures, with kosher-halal certification and dual-use facility qualification driving the top-tier premium. Cost compression in standard powder grades is intensifying because Chinese integrated producers leverage captive phosphate rock mining. Feed-grade blenders exhibit the highest price sensitivity, while pharmaceutical compounders tolerate premium positioning for guaranteed purity floors.
Supply Chain Analysis
Single-source vulnerability sits with phosphate rock concentration in China's Guizhou and Yunnan mining clusters. Supply draws from Chinese phosphate deposits, Moroccan rock imports for European processors, and residual US domestic mining in Florida and Idaho. Raw material dependencies include phosphoric acid, potassium hydroxide, and specialized ceramic filtration media. Tariff exposure on Chinese phosphate derivatives threatens margin stability for Western formulators. Distribution runs through Rotterdam and Hamburg logistics hubs for European nutraceutical markets, with direct rail links serving Midwestern US dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade monopotassium phosphate functions as a stable compounder, with mineral fortification mandates in clinical nutrition and infant formula providing durable demand baselines regardless of cyclical food processing volatility.
For Market Incumbents: Deepen backward integration into phosphate rock mining or secure long-term offtake agreements with Guizhou-based suppliers to defend against citrate substitution in clean-label bakery segments. Expand spray-dried agglomeration capacity in European logistics hubs to capture granular grade premiums from Dutch and Italian co-manufacturers retrofitting pneumatic conveying lines. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade certified material and standard food-grade powder offers entry space for mid-tier producers. Target Indian nutraceutical contract manufacturers in Maharashtra and Gujarat seeking FSSAI-aligned mineral inputs with shorter qualification timelines than established European suppliers. Lead with digital procurement platforms that compress distributor layers for mid-volume pharmaceutical compounders. For Investors and Strategic Acquirers: Nutraceutical contract manufacturers are the most active acquirer in this space, consolidating supplier relationships around dual-certified producers capable of serving both food and pharmaceutical grades. The acquisition target archetype combines captive phosphate rock access with existing kosher-halal certification infrastructure. Watch EFSA acceptable daily intake evaluation outcomes as the signal for reformulation-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive Guizhou deposit access secures cost leadership against energy price volatility. |
| Spray-Dried Agglomeration Capacity Expansion | Engineered particle densities capture premiums from automated European bakery systems. |
| Kosher-Halal Dual Certification Investment | Religious dietary compliance unlocks Middle Eastern and North African import channels. |
| Long-Term Offtake Agreements with Pharmaceutical Compounders | Multi-year purity floors displace spot market exposure in German and Dutch nutraceutical clusters. |
| Digital Procurement Platform Development | Direct-to-formulator e-commerce compresses distributor margins for mid-tier buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged phosphate plant managers, procurement leads at dairy and bakery processors, distribution channel partners in Rotterdam and Hamburg, and technical R&D directors at nutraceutical compounders. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, GB 25560 regulatory submissions to SAMR, and EFSA food additive safety dossiers. Bottom-up capacity modeling and top-down demand segmentation were triangulated against reported producer utilization rates.
Historical reference periods anchored volume and value trajectories across the projection horizon. The analytical framework modeled segmentation across physical form, application tier, end-user scale, and distribution channel structure. CAGRs were derived from fitted growth curves calibrated to phosphate rock cost pass-through elasticities and substitution dynamics with citrate alternatives. Forecast inputs included EFSA acceptable daily intake revision timelines, FSSAI mineral fortification mandate implementation pace, and spray-drying technology adoption rates in European co-manufacturing.
The model assumes a particular technology adoption path; alternative pathways for spray-dried agglomeration would alter the outlook if pneumatic conveying retrofit rates in industrial bakeries lag projected timelines. Forecasts reflect assumptions about regulatory stability in Chinese export quotas and REACH compliance friction for new market entrants. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Grade Calcium Carbonate Market