
 Food Grade Silica Market | 2026-2036
Food Grade Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Silica Market Analysis
Asian precipitated silica producers is broadening output dedicated to food-contact specifications. Evonik Industries AG leverages its synthetic amorphous silica expertise to dominate high-purity grades for sensitive applications. Tata Chemicals Limited anchors regional supply through integrated soda ash-to-silica manufacturing in Gujarat. Huber Engineered Materials competes on US-based production with FDA-compliant certification pathways.
Food grade silica denotes synthetic amorphous silicon dioxide meeting purity thresholds above 96 percent SiO₂ with controlled particle size distribution, manufactured via precipitation or thermal processes for use as an anti-caking agent, carrier, or flow aid in ingestible products. Powder formulations lead volume due to ease of dispersion in dry seasoning and salt applications, while colloidal grades command margin pools in premium beverage clarification and nutraceutical encapsulation. Gel formats sustain demand in moisture-sensitive confectionery packaging where adsorption kinetics outperform mineral alternatives.
FDA food additive regulations under 21 CFR 172.480 govern silicon dioxide identity and purity thresholds for US market access, while EFSA evaluations under the EU reauthorization process for E 551 reshape specification requirements for imported material. BIS certification requirements in India and evolving GB standards under SAMR in China create divergent compliance pathways that fragment supplier qualification costs. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location and certification investment.
Market Dynamics
Clean-label formulation mandates from nutraceutical brands are compressing specification tolerances for silicon dioxide carriers, forcing precipitated silica producers to recalibrate purity thresholds and particle engineering protocols faster than process equipment depreciation cycles allow.
Growth Catalysts
- EFSA Reauthorization Protocol:The EU's updated E 551 evaluation is accelerating R&D investment in synthetic amorphous silica with sub-micron particle control, as manufacturers pre-empt stricter migration limits for ingestible applications.
- Nutraceutical Encapsulation Demand:Soft-gel and tablet manufacturers in North America are specifying colloidal silica for flow-aid applications in probiotic and omega-3 formulations, creating premium-grade volume pull.
- China Capacity Expansion:Precipitated silica output from Jiangsu and Shandong provinces is scaling dedicated food-contact lines, reducing import dependency for domestic seasoning and salt processors.
Market Restraints
- Soda Ash Input Volatility:Synthetic amorphous silica production depends on sodium carbonate pricing, and energy-intensive Solvay process economics in Europe are transmitting cost spikes to precipitated silica contract structures.
- Supplier Concentration Risk:High-purity thermal silica capacity clusters among a limited set of German and US specialty chemical producers, creating qualification bottlenecks for new food-grade entrants.
- Cellulose Substitution Threat:Microcrystalline cellulose and rice hull-derived silicon dioxide are capturing share in organic-certified seasoning applications where synthetic carrier labeling creates consumer friction.
Strategic Opportunities
- India BIS Certification Gap:Domestic precipitated silica producers in Gujarat and Maharashtra are underinvested in IS 15316 compliance infrastructure, creating first-mover advantage for integrated soda ash-to-silica operators.
- Plant-Based Protein Clarification:Oat milk and pea protein beverage manufacturers are trialing colloidal silica for haze reduction and shelf-life extension, opening beverage-grade specification development.
- SAMR GB Standard Harmonization:China's evolving national food additive standards under SAMR are converging toward CODEX Alimentarius parameters, simplifying dual-certification pathways for exporters.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Particle size distribution characterization and heavy metals testing at ppb thresholds require specialized spectroscopy expertise that outpaces vocational training output in emerging production regions.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA 21 CFR 172.480, EFSA E 551, and BIS IS 15316 qualification cycles extend commercialization timelines by 18-24 months for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Silica Market |
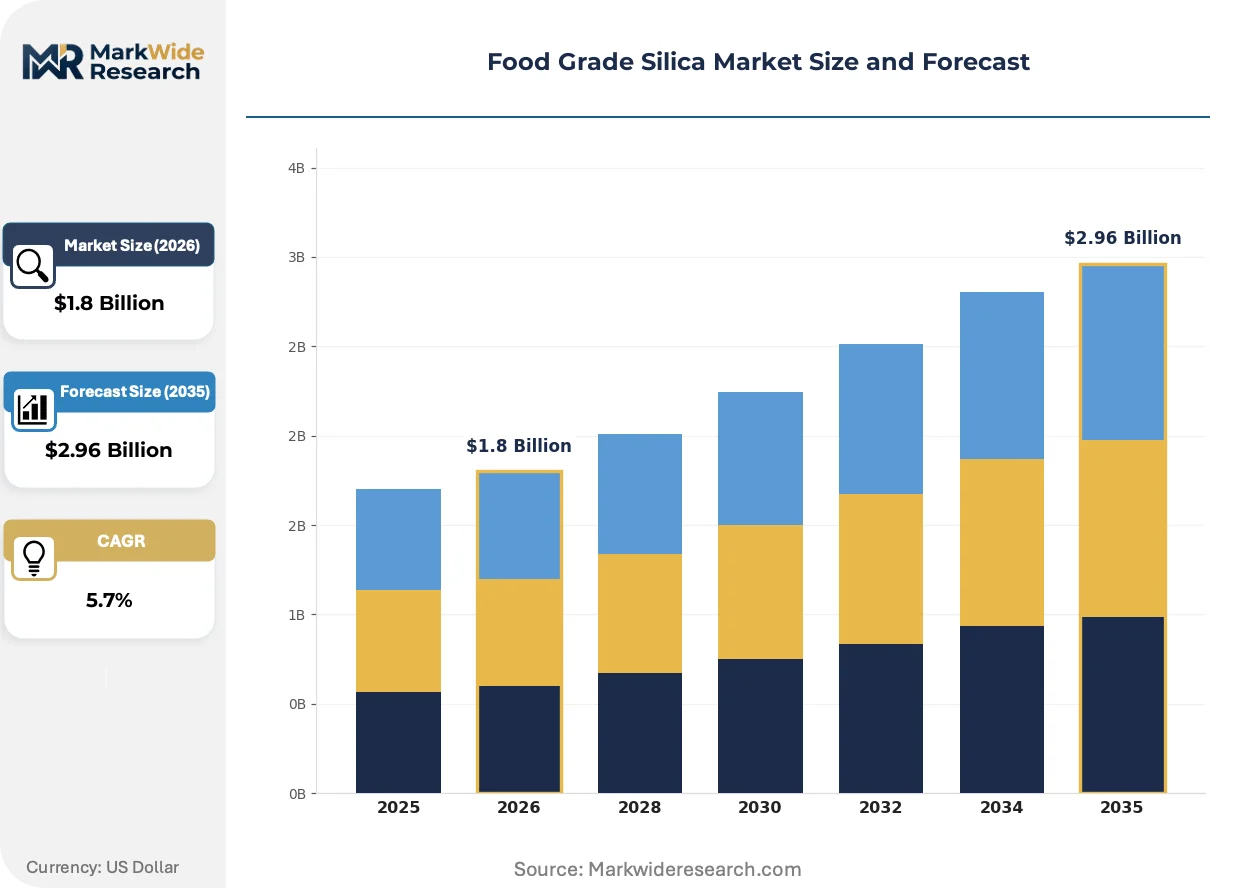
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Gel, Colloidal Application: Food Additive, Anti-Caking Agent, Flow Agent, Absorbent End User: Food & Beverage Manufacturers, Nutraceuticals, Confectionery, Dairy Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | Huber Engineered Materials, Tata Chemicals Limited, Evonik Industries AG, Madhu Silica Pvt. Ltd., Quechen Silicon Chemical Co., Ltd., Solvay S.A., W. R. Grace & Co., Tokuyama Corporation, Imerys S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Silica Market Emerging Trajectories
Continuous precipitation reactor designs and membrane filtration integration are compressing batch-to-batch variability in synthetic amorphous silica, enabling real-time specification adherence that static reactor configurations cannot match.
Membrane-assisted precipitation technology is rewriting the economics of high-purity silica production. Nutraceutical contract manufacturers in Switzerland and Germany are adopting these systems to reduce heavy metals content below 10 ppm without secondary acid washing. The structural consequence is a compression in premium-grade pricing power for legacy thermal process operators.
REACH Annex XVII amendments on nanomaterial registration are forcing precipitated silica producers to distinguish colloidal dispersions from nanoparticle classifications. The industrial consequence is a documentation burden that favors integrated producers with in-house toxicology testing capabilities. Food-contact applications in the EU are responding by consolidating supplier bases toward REACH-registered entities with established safety data packages.
Direct-procurement platforms are disintermediating traditional chemical distributors for standard-grade powder silica. Mid-sized seasoning blenders in the US Midwest are sourcing through B2B marketplaces that bypass regional distributor markups, compressing channel economics. This pattern is most visible in salt and dry seasoning applications where specification standardization reduces technical service requirements.
Food Grade Silica Market Segmentation
Segmentation in food grade silica reveals how purity thresholds and particle engineering requirements diverge across end-use specifications. Buyers select grades based on migration limits, dispersibility needs, and certification burdens rather than commodity pricing alone.
Product Type:
Buyers differentiate primarily by dispersion kinetics and moisture sensitivity requirements in their production lines.
- Powder:Synthetic amorphous silicon dioxide with controlled particle size distribution below 10 microns enables rapid dispersion in dry seasoning and salt applications. Seasoning blenders in India and China specify this grade for bulk anti-caking where cost efficiency outweighs premium certification needs.
- Colloidal:Sub-micron particle suspensions in aqueous or alcoholic carriers command specification premiums for beverage clarification and soft-gel encapsulation. Nutraceutical contract manufacturers in Germany and Switzerland are qualifying these grades for probiotic formulations where haze control determines shelf-life extension.
- Granular:Coarse agglomerates above 100 microns serve desiccant applications in moisture-sensitive confectionery packaging where adsorption capacity trumps dispersion speed.
- Gel:Rigid mesoporous structures with defined pore diameters target specialized moisture scavenging in premium chocolate and dried fruit applications.
Powder leads volumes today; colloidal is gaining share fastest.
Application:
Specification intensity escalates with direct ingestible contact and regulatory scrutiny depth.
- Anti-Caking Agent:Silicon dioxide prevents agglomeration in hygroscopic powders through surface adsorption of moisture films. Salt processors across Gujarat and Rajasthan specify food-grade precipitated silica to maintain flowability in tropical storage conditions where humidity exceeds 70 percent seasonally.
- Flow Agent:Colloidal grades reduce interparticle friction in tablet compression and capsule filling operations. Omega-3 and probiotic manufacturers in North America are driving volume as soft-gel specifications tighten around particle size consistency.
- Food Additive:Direct incorporation into ingestible matrices as E 551 or FDA 21 CFR 172.480 compliant carriers requires sub-10 ppm heavy metals certification that thermal process operators struggle to achieve.
- Absorbent:Mesoporous silica scavenges moisture and volatile compounds in packaging headspace applications for confectionery and dried goods.
Anti-caking agent anchors current demand; flow agent applications are expanding most quickly.
End User:
Certification burden and technical service requirements separate commodity buyers from specification-intensive accounts.
- Nutraceuticals:Soft-gel, tablet, and encapsulation manufacturers demand colloidal silica with batch-to-batch particle distribution consistency below 5 percent coefficient of variation. EFSA reauthorization protocols for E 551 are compressing supplier qualification timelines to 12-18 months for new entrants.
- Food & Beverage Manufacturers:Seasoning, salt, and dry mix processors consume standard-grade powder silica where FDA or FSSAI compliance suffices without REACH registration burdens. These buyers prioritize supply security and freight economics over technical service intensity.
- Confectionery:Chocolate and sugar confectionery producers specify gel and granular formats for moisture control in packaging where adsorption kinetics outperform mineral alternatives.
- Dairy:Powdered milk and infant formula applications require the highest purity thresholds with allergen-free certification and sub-ppb heavy metals testing that only integrated thermal process operators can reliably deliver.
Food and beverage manufacturers dominate volume; nutraceuticals show the steepest expansion trajectory.
Packaging Type:
Handling economics and contamination risk determine format selection across supply chain tiers.
- Bulk Containers:Flexible intermediate bulk containers and silo truck deliveries serve high-volume salt and seasoning processors where annual offtake exceeds 500 metric tons. These buyers negotiate direct procurement contracts that bypass distributor markups.
- Bags:25-kilogram multi-wall paper sacks remain standard for mid-tier nutraceutical and confectionery manufacturers with moderate volume requirements and warehouse constraints.
- Drums:Fiber and steel drums protect hygroscopic colloidal grades from moisture ingress during ocean freight from European and US specialty producers to Asian formulators.
- Sachets:Single-use desiccant packets integrate silica gel into retail packaging for consumer-facing confectionery and dried fruit applications.
Bulk containers capture the largest volume share; sachet formats are climbing the fastest as retail packaging specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting precipitated silica investment toward jurisdictions where purity certification costs less than in Western Europe. Manufacturers are relocating thermal process capacity to exploit gaps between EFSA reauthorization timelines and emerging market compliance infrastructure.
China
Domestic seasoning and salt processors in Jiangsu and Shandong provinces are absorbing expanded precipitated silica output from newly commissioned food-contact lines. SAMR's evolving GB standards are converging toward CODEX Alimentarius parameters, reducing dual-certification burdens for exporters targeting Southeast Asian markets. Qingdao and Yantai chemical clusters are scaling dedicated anti-caking agent production for domestic dairy powder applications.
Germany
Nutraceutical contract manufacturers in Bavaria and Baden-Württemberg are qualifying colloidal silica grades for probiotic encapsulation under tightening EFSA E 551 migration limits. REACH Annex XVII nanomaterial registration requirements are consolidating supplier bases toward integrated producers with established safety data packages. Frankfurt-Rhine-Main specialty chemical corridors are deploying membrane-assisted precipitation systems to compress heavy metals content below 10 ppm.
India
Gujarat-based salt processors across Kutch and Rajkot districts specify standard-grade powder silica for tropical humidity conditions exceeding 70 percent seasonally. BIS IS 15316 certification infrastructure remains underdeveloped among domestic precipitated silica producers, creating qualification bottlenecks for new entrants. Maharashtra's integrated soda ash-to-silica operators in Thane and Raigad are capturing first-mover advantage in compliance investment.
United States
Midwestern seasoning blenders in Illinois and Iowa are sourcing powder silica through direct-procurement platforms that bypass traditional distributor markups. FDA 21 CFR 172.480 compliance suffices for standard anti-caking applications without REACH registration burdens. Gulf Coast petrochemical corridors are evaluating backward integration into synthetic amorphous silica to secure captive sodium carbonate supply chains.
Brazil
São Paulo-state food manufacturers are importing colloidal grades for beverage clarification applications where domestic precipitated silica capacity lacks sub-micron particle control. ANVISA alignment with CODEX standards is simplifying import qualification pathways for European and US specialty producers. Campinas chemical parks are attracting toll-manufacturing investments for regional anti-caking agent formulation.
Food Grade Silica Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue colloidal and gel specialization to escape commodity pricing pressure. The vendor base stratifies across three tiers: integrated multinational chemical conglomerates with captive raw material positions, regional precipitated silica specialists serving salt and seasoning processors, and niche thermal process operators targeting nutraceutical purity thresholds. Competitive dynamics center on backward integration into soda ash supply and membrane filtration technology licensing rather than direct price confrontation.
Among German-based specialty chemical operators, Evonik Industries AG exemplifies the high-purity synthetic amorphous silica archetype with established REACH registration portfolios. Tata Chemicals Limited anchors regional supply positioning through integrated manufacturing infrastructure in Gujarat. Huber Engineered Materials represents US-based production with FDA-compliant certification pathways serving domestic seasoning and salt processors.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| Tata Chemicals Limited |
| Evonik Industries AG |
| Madhu Silica Pvt. Ltd. |
| Quechen Silicon Chemical Co., Ltd. |
| Solvay S.A. |
| W. R. Grace & Co. |
| Tokuyama Corporation |
| Imerys S.A. |
| Others |
Supply Flow & Price Mechanics
Membrane-assisted precipitation technology is compressing production economics for high-purity grades while simultaneously concentrating supply among integrated operators with capital to license filtration systems. This dual effect reshapes margin distribution across the value chain, rewarding backward-integrated producers with captive sodium carbonate supply while squeezing toll-manufacturing margins.
Pricing Analysis
Distributor markups of 15-25 percent on standard-grade powder silica are eroding as Midwestern seasoning blenders adopt direct-procurement platforms. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered colloidal grades from FDA-compliant powders and uncertified industrial material. Cost compression in standard powder tiers is intensifying because Chinese capacity additions outpace specification differentiation. Salt processors in Gujarat exhibit highest price sensitivity; nutraceutical encapsulation houses in Bavaria show least.
Supply Chain Analysis
Single-source vulnerability sits with German thermal process operators for sub-10 ppm heavy metals material. Geographic concentration centers on China, India, and Germany for precipitated and thermal silica output. Production draws from sodium carbonate via Solvay process, membrane filtration systems, and acid-washing infrastructure. Regulatory restriction risk looms from REACH Annex XVII nanomaterial documentation burdens. Distribution runs through chemical distributors for small-batch colloidal grades and direct silo-truck delivery for high-volume salt processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food grade silica market functions as a stable compounder anchored by irreversible clean-label formulation mandates across nutraceutical and beverage applications.
For Market Incumbents: To counter cellulose substitution in organic-certified seasoning applications, deepen REACH-registered safety data packages for EFSA E 551 reauthorization defense and expand membrane filtration capacity in Gujarat to capture BIS certification first-mover rents. Certification investment in IS 15316 compliance infrastructure represents the critical lever for India market position. For New Entrants and Emerging Players: SAMR GB standard harmonization toward CODEX Alimentarius parameters in China opens a window for export-oriented precipitated silica facilities with dual-certification pathways. Target underqualified domestic producers in Maharashtra lacking integrated soda ash positions. Plant-based protein clarification for oat milk and pea protein beverage manufacturers offers the most penetrable application wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among regional precipitated silica specialists with untapped food-contact line potential and proximity to soda ash feedstock. Long-term viability over a 5-10 year horizon rests on regulatory compliance infrastructure rather than commodity volume positioning. Monitor EFSA E 551 migration limit announcements as the decisive inflection signal for premium-grade pricing power.| Strategic Initiative | Industry Significance |
|---|---|
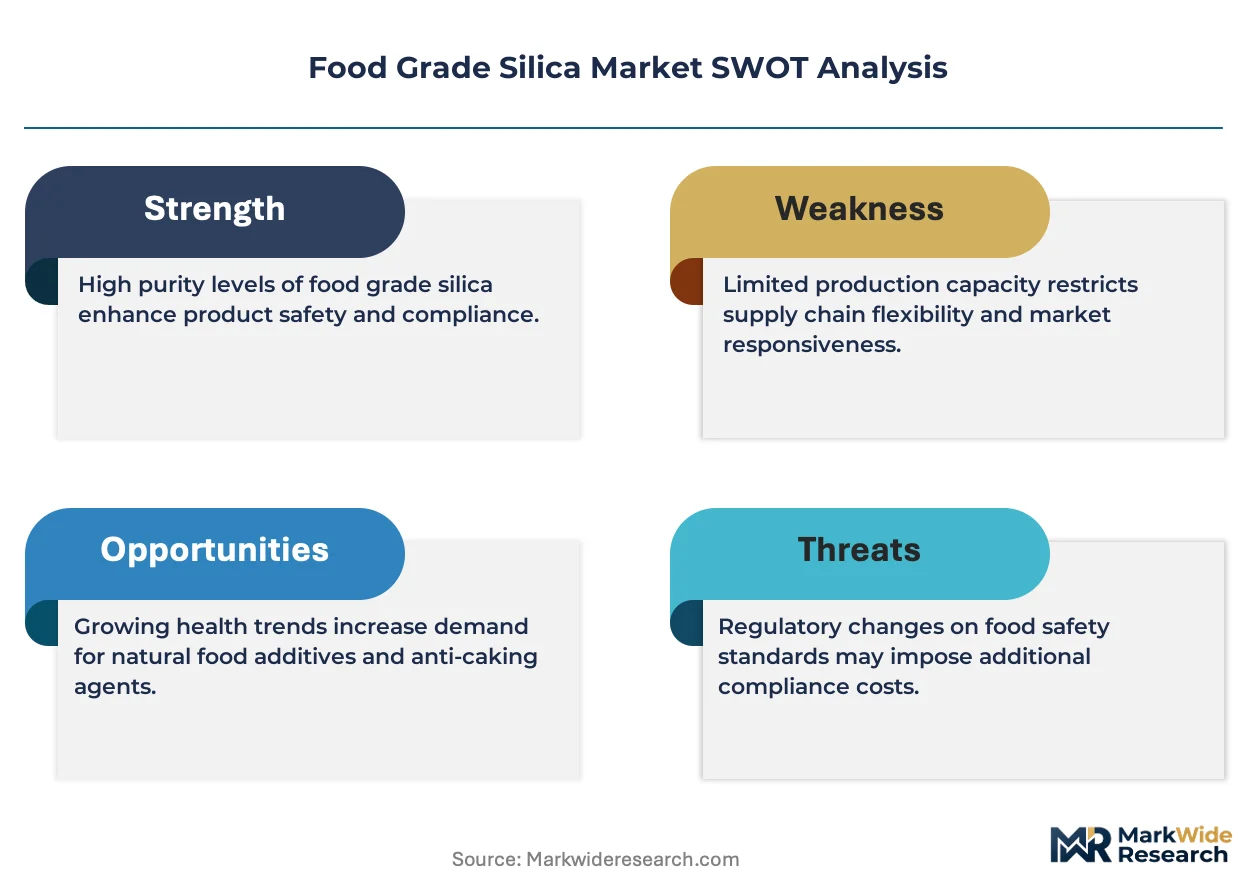
| Backward Integration into Soda Ash | Captive sodium carbonate supply secures margin stability against Solvay process energy cost volatility in Europe. |
| Membrane Filtration Licensing | Membrane-assisted precipitation enables sub-10 ppm heavy metals output without secondary acid washing. |
| BIS IS 15316 Certification Investment | Compliance infrastructure in Gujarat and Maharashtra captures qualification bottleneck rents from underinvested domestic competitors. |
| Direct-Procurement Platform Adoption | B2B marketplace channel bypasses distributor markups for Midwestern seasoning blenders with standardized specifications. |
| Colloidal Grade Capacity Expansion | Sub-micron particle control serves nutraceutical encapsulation demand from probiotic and omega-3 manufacturers in North America. |
Methodological Framework
Multiple input streams — technical discussions with precipitated silica plant managers, procurement leads at seasoning and nutraceutical manufacturers, distribution channel partners, and regulatory affairs directors — were reconciled against customs data, BIS certification registries, SEC 10-K filings, and EFSA reauthorization documentation. Bottom-up capacity modeling and top-down demand estimation were triangulated to validate volume outputs.
Historical shipment patterns were cross-referenced against panel input from industry participants to anchor growth trajectories. Segmentation dimensions included product type tier, application intensity, end-user certification burden, and regional regulatory cluster. CAGRs were derived from supply-demand balance modeling incorporating capacity commissioning timelines and specification migration trends across the projection horizon.
Revisions become necessary when EFSA E 551 reauthorization timelines shift, SAMR GB standard convergence stalls, or cellulose substitution rates in organic applications accelerate beyond current trajectories. Forecasts reflect documented assumptions about regulatory compliance costs and membrane technology diffusion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Isoflavones Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Food Grade Activated Carbon Market