
 Natural Antioxidants Market | 2026-2036
Natural Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Antioxidants Market Intelligence
Clean extraction technology is tilting procurement standards toward solvent-free and supercritical CO2 processes that preserve bioactive integrity. BASF SE anchors its position through backward integration into rosemary and tocopherol supply chains, while DSM differentiates via fermentation-derived antioxidant platforms. Kalsec Inc. specializes in spice and herb extract portfolios that target premium clean-label segments.
Natural antioxidants comprise bioactive compounds—primarily polyphenols, carotenoids, and flavonoids—extracted from botanical matrices to inhibit lipid peroxidation and oxidative rancidity in finished goods, typically measured by ORAC values or DPPH radical scavenging capacity. Their primary commercial purpose centers on replacing synthetic preservatives like BHT and BHA in oxidation-sensitive formulations. Polyphenols from green tea and grape seed command the deepest margin pools due to concentrated efficacy and supply scarcity, while carotenoids sustain volume leadership through feed and food coloring co-demand. Flavonoid applications in dietary supplements represent the fastest-expanding channel as direct-to-consumer brands prioritize single-ingredient transparency.
Regulators including EFSA, FDA, and EMA enforce divergent safety dossier requirements for novel extract submissions, with EFSA's novel food catalog creating bottlenecks that favor established suppliers with existing approvals. REACH and FDA GRAS self-affirmation pathways diverge sufficiently to require dual-track regulatory strategy for cross-Atlantic commercialization. Stakeholders must monitor emerging genome-edited crop antioxidant sources, as gene-edited botanicals threaten to outpace existing regulatory classification frameworks.
Market Dynamics
Clean-label procurement mandates from packaged food manufacturers are restructuring supplier qualification criteria, favoring botanical extract houses with solvent-free extraction certifications and batch-level traceability systems over commodity chemical traders.
Growth Catalysts
- EU Green Deal additive thresholds:REACH compliance deadlines are redirecting formulation budgets toward rosemary-derived and tocopherol-based alternatives as permissible synthetic antioxidant limits tighten across continental Europe.
- Supercritical CO2 extraction maturation:Equipment cost curves have flattened sufficiently to enable mid-scale processors to deploy solvent-free systems that preserve polyphenol integrity for premium clean-label segments.
- Direct-to-consumer supplement channel expansion:Single-ingredient transparency requirements from digital-native brands are accelerating flavonoid procurement from grape seed and green tea extract suppliers.
Market Restraints
- Raw material supply concentration:Rosemary cultivation clusters in Morocco and Spain create weather-dependent input volatility that compresses margin predictability for tocopherol and carnosic acid producers.
- EFSA novel food bottlenecks:The novel food catalog approval timeline stretches 18-24 months, favoring incumbent suppliers with existing dossiers and freezing smaller extract houses out of new product launches.
- Synthetic preservative cost floor:BHT and BHA maintain 60-70% cost advantages over botanical equivalents, limiting displacement velocity in price-sensitive commodity food categories.
Strategic Opportunities
- Fermentation-derived antioxidant platforms:Microbial production of carotenoids and polyphenols bypasses agricultural yield constraints and enables year-round supply continuity for oxidation-sensitive formulations.
- CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements are creating audit-ready traceability premiums for extract houses with farm-to-fork documentation systems.
- Personalized nutrition subscription models:Direct-to-consumer brands are unbundling antioxidant formulations into single-compound SKUs that command ingredient-level transparency premiums from bioactive suppliers.
Industry Challenges
- Dual-track regulatory dossier costs:EFSA novel food and FDA GRAS self-affirmation pathways require non-overlapping toxicology studies that strain R&D budgets for cross-Atlantic commercialization.
- Genome-edited crop classification gaps:Gene-edited botanicals with enhanced polyphenol yields are outpacing existing regulatory frameworks, creating approval uncertainty for CRISPR-derived antioxidant sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Antioxidants Market |
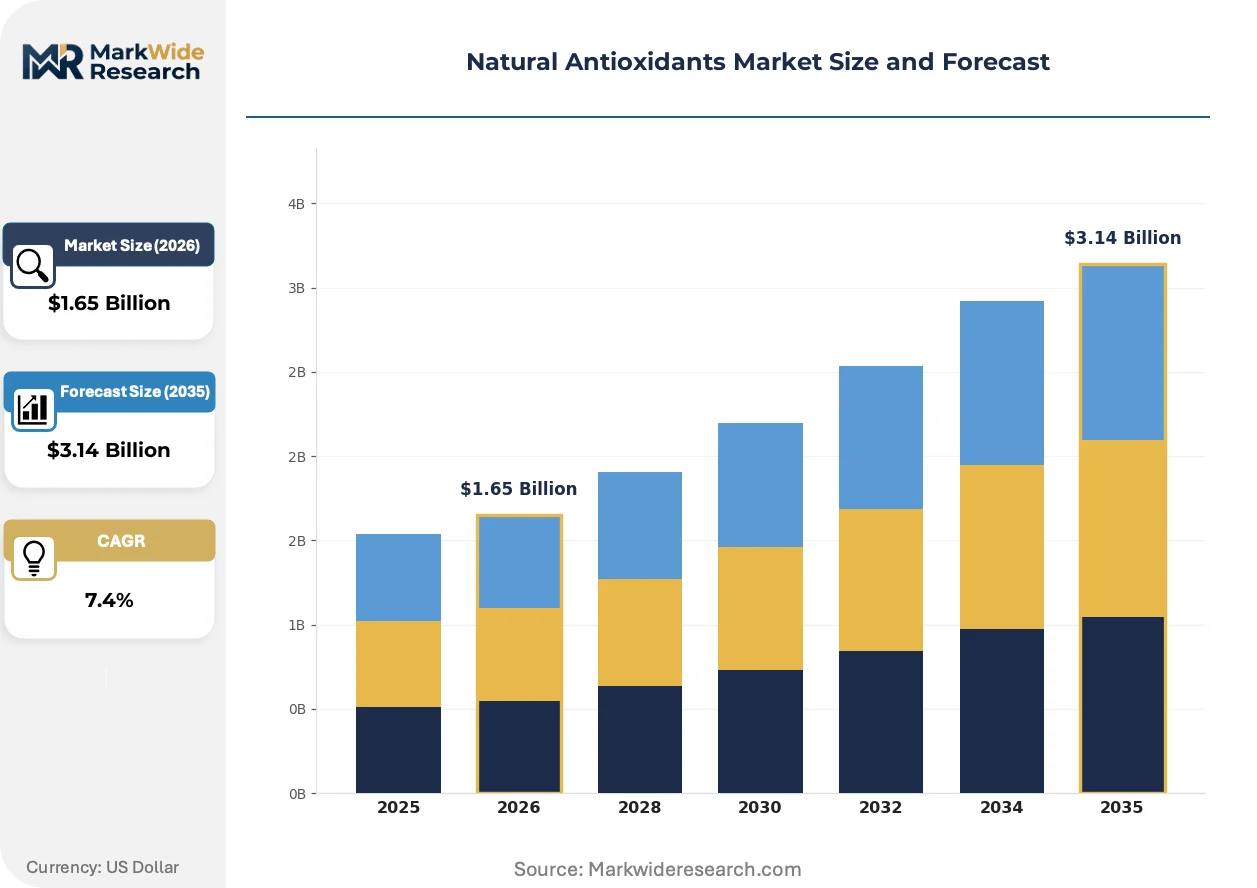
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.14 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavonoids, Carotenoids, Polyphenols, Vitamin C Application: Food & Beverage, Cosmetics, Dietary Supplements, Pharmaceuticals Source: Fruits, Vegetables, Herbs, Grains Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Archer Daniels Midland Company, BASF SE, DSM, Camlin Fine Sciences Ltd., DuPont, Prinova Group LLC, Eastman Chemical Company, Naturex, Kalsec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Antioxidants Market Strategic Shifts & Innovations
Extraction technology convergence with precision fermentation is collapsing traditional boundaries between agricultural and biomanufactured antioxidant supply chains, while regulatory disclosure mandates are rewiring procurement transparency standards.
Supercritical CO2 extraction is collapsing the cost-performance gap between solvent-based and clean-label antioxidant production. Mid-scale processors in Germany and Italy are deploying these systems to serve continental packaged meat and bakery manufacturers seeking EFSA-compliant shelf-life extension. The technology is collapsing batch-to-batch variability that previously limited botanical extract adoption in oxidation-sensitive frying oils.
REACH authorization requirements for synthetic antioxidants are compressing permissible use thresholds across EU member states. Food and beverage manufacturers face reformulation deadlines that favor suppliers with pre-approved botanical dossiers. The regulation most acutely affects margarine and edible oil processors in Germany, where ingredient procurement teams are accelerating rosemary extract qualification timelines.
Subscription-based supplement distribution is fragmenting bulk antioxidant procurement into small-lot, high-frequency orders. Direct-to-consumer brands in the United States are bypassing traditional ingredient distributors to contract directly with extract houses for single-compound transparency. This pattern concentrates in California and New York metro areas where digital-native wellness brands cluster.
Natural Antioxidants Market Segmentation
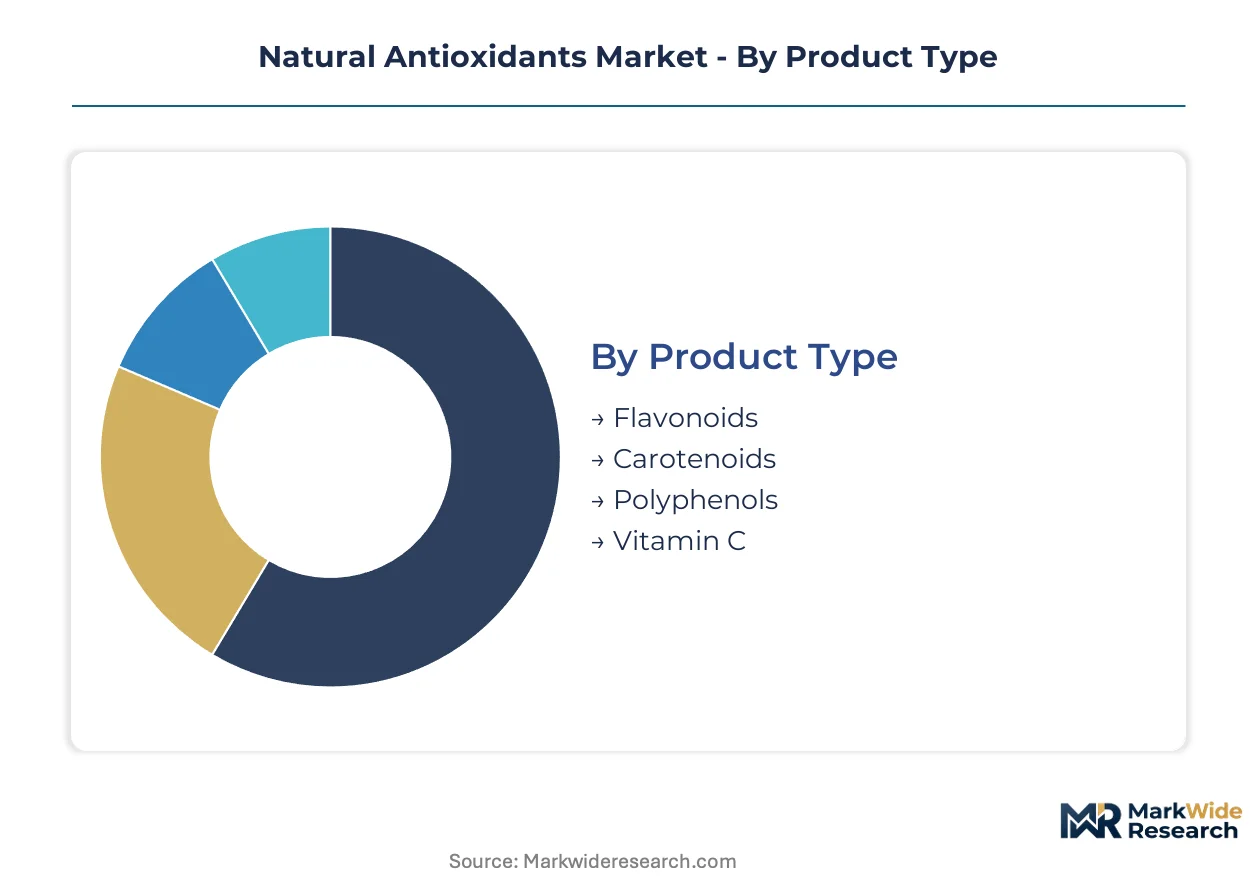
Natural antioxidants span diverse molecular classes with divergent extraction economics and regulatory pathways. Segmentation reveals where formulation budgets concentrate and which supply chains command premium positioning.
Product Type:
Mature tocopherol platforms coexist with emerging fermentation-derived alternatives across the efficacy spectrum.
- Polyphenols:Concentrated bioactive compounds from green tea and grape seed matrices deliver superior ORAC values for premium oxidation control. Procurement from German and Italian extract houses is accelerating as EFSA-compliant clean-label mandates displace synthetic BHT in continental frying oils and margarine formulations.
- Carotenoids:Lipid-soluble pigments including beta-carotene and lutein serve dual functions as colorants and radical scavengers. Feed additive demand in Spain and poultry integration in France sustains volume leadership, though supply volatility from Moroccan cultivation clusters compresses margin predictability.
- Flavonoids:Grape seed and citrus-derived compounds target dietary supplement transparency requirements.
- Vitamin C:Ascorbic acid platforms anchor commodity food preservation with established GRAS status.
Polyphenols handle the majority of throughput; flavonoids are the fastest mover on share.
Application:
End-use concentration follows clean-label procurement intensity across formulation-sensitive categories.
- Food & Beverage:Oxidation-sensitive categories including edible oils, processed meats, and bakery formulations drive rosemary extract and tocopherol qualification. German packaged food manufacturers near Frankfurt and Hamburg are accelerating supplier audits for solvent-free extraction certifications ahead of REACH compliance deadlines.
- Dietary Supplements:Single-ingredient transparency requirements from California and New York direct-to-consumer brands are fragmenting bulk procurement into small-lot, high-frequency orders. Grape seed and green tea extracts command ingredient-level premiums from digital-native wellness companies.
- Cosmetics:Topical stability applications favor lipophilic carotenoid platforms for photoprotection claims.
- Pharmaceuticals:Excipient-grade antioxidants require EMA-compliant dossier submissions for parenteral formulations.
Food & Beverage captures the dominant formulation spend; Dietary Supplements is climbing the fastest on procurement frequency.
Source:
Botanical origin determines extraction methodology and regulatory classification complexity.
- Herbs:Rosemary and oregano matrices yield carnosic acid and rosmarinic acid through supercritical CO2 processing. Moroccan and Spanish cultivation clusters supply Frankfurt-area processors serving continental meat and bakery manufacturers.
- Fruits:Grape seed and berry pomace streams provide concentrated proanthocyanidins for supplement and cosmetic applications.
- Vegetables:Tomato and carrot-derived carotenoids leverage existing food processing waste streams.
- Grains:Oat and rice bran ferulic acid platforms remain niche due to lower bioavailability metrics.
Herbs dominate extraction throughput; fruits are gaining share fastest on upcycling economics.
Distribution Channel:
Channel selection reflects order scale and transparency documentation requirements.
- Direct Sales:Large-scale food manufacturers in Germany and supplement brands in California bypass distributors for batch-level traceability. Contract relationships with extract houses enable CSRD-compliant supply chain disclosure and farm-to-fork documentation.
- Distributors:Mid-scale processors across Italy and Spain rely on ingredient traders for fragmented raw material aggregation.
- Online:Small-lot procurement portals serve research institutions and startup formulation labs.
- Retail:Consumer-packaged finished goods move through conventional grocery and pharmacy networks.
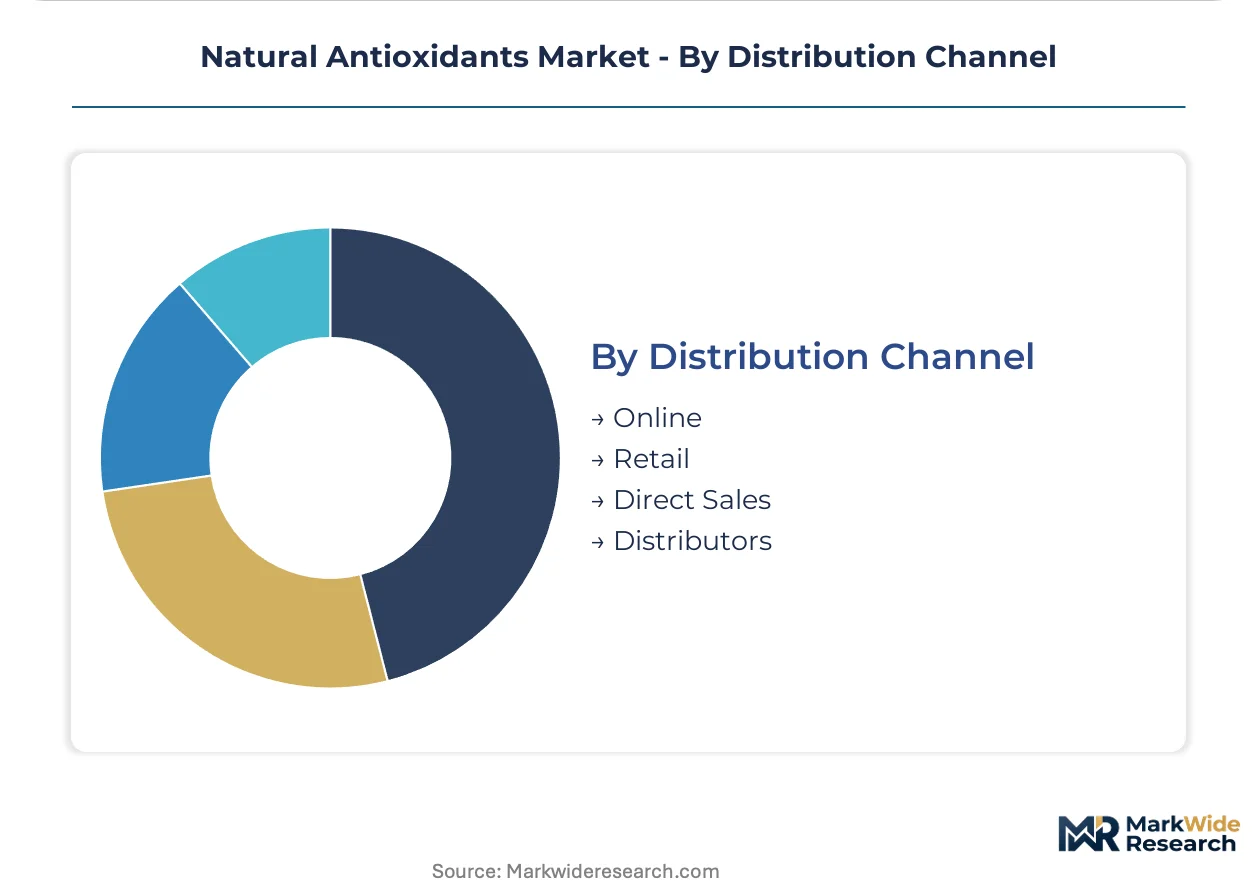
Direct Sales manages the largest contract values; Online is expanding most quickly on order frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish rosemary extract exports supply German food processors confronting REACH compliance deadlines, while Moroccan cultivation clusters feed tocopherol production lines across continental Europe.
Germany
Frankfurt and Hamburg ingredient processors serve continental packaged meat and bakery manufacturers accelerating clean-label reformulation. EFSA novel food catalog requirements compress approval timelines for new botanical submissions. The Rhine-Main cluster concentrates supercritical CO2 extraction capacity for rosemary-derived carnosic acid serving margarine and edible oil applications.
Spain
Moroccan rosemary imports and domestic cultivation sustain tocopherol and carotenoid production for feed and food colorant markets. REACH authorization thresholds for synthetic antioxidants tighten permissible use limits across Iberian Peninsula formulation facilities. Barcelona-area extract houses deploy solvent-free processing systems to capture premium clean-label procurement from French and Italian buyers.
United States
California and New York metro direct-to-consumer supplement brands fragment bulk procurement into small-lot, high-frequency orders for grape seed and green tea extracts. FDA GRAS self-affirmation pathways enable faster market entry compared to EFSA timelines. Los Angeles and San Francisco Bay Area digital-native wellness companies contract directly with extract houses for single-ingredient transparency documentation.
China
Domestic green tea polyphenol production serves both export markets and local food preservation demand. SAMR food additive standards and GB compliance requirements structure permissible extract concentrations in finished goods. Yangtze River Delta processing hubs concentrate botanical extraction capacity serving domestic bakery and frying oil manufacturers.
India
Spice-derived antioxidant extraction from cardamom and turmeric matrices targets export supplement and cosmetic markets. FSSAI food safety standards govern permissible botanical additive thresholds in domestic packaged food formulations. Gujarat and Maharashtra processing clusters supply standardized curcuminoid extracts for North American and European dietary supplement distributors.
Natural Antioxidants Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers. Specialty chemical conglomerates with backward integration into agricultural supply chains occupy the upper tier, while mid-scale botanical extract houses and regional fermentation platforms populate the middle and lower tiers. Dominant competitive moves include capacity expansion in supercritical CO2 processing infrastructure and strategic partnerships between extract houses and direct-to-consumer supplement brands for transparent supply chain documentation.
Within the integrated chemical conglomerate tier, BASF SE and DSM exemplify divergent sourcing strategies—one through captive rosemary and tocopherol cultivation, the other through microbial production platforms. Kalsec Inc. occupies a specialist position representing the mid-scale botanical extract archetype focused on spice and herb matrices. These three anchors illustrate how procurement standards are tilting toward solvent-free extraction certifications and batch-level traceability systems that commodity traders cannot readily replicate.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| DSM |
| Camlin Fine Sciences Ltd. |
| DuPont |
| Prinova Group LLC |
| Eastman Chemical Company |
| Naturex |
| Kalsec Inc. |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp barge freight corridors transmit agricultural commodity cost volatility directly into rosemary extract and tocopherol pricing tiers, amplifying margin compression for processors lacking Moroccan cultivation partnerships while enabling solvent-free certification premiums for German extract houses serving REACH-compliant buyers.
Pricing Analysis
Solvent-based extraction platforms, supercritical CO2 systems, and emerging fermentation-derived alternatives stratify across three performance tiers. Premium-mid-economy pricing differentiation separates EFSA novel food dossier holders from commodity traders, with certification grade and volume scale as primary drivers. Pricing pressure stems from synthetic preservative cost floors that limit displacement velocity in commodity frying oils. Commodity food manufacturers exhibit highest price sensitivity; direct-to-consumer supplement brands absorb premium tiers for transparency documentation.
Supply Chain Analysis
Rosemary feedstock cultivation clusters in Morocco and Spain, with German and Italian processors commanding downstream extraction capacity. Carnosic acid and rosmarinic acid inputs draw from Mediterranean agricultural zones, while tocopherol production rests on soybean and sunflower oil refining byproduct streams. Single-source vulnerability concentrates in Moroccan weather-dependent harvests that disrupt continental European supply continuity. Distribution runs through direct sales contracts for large-scale food manufacturers and fragmented distributor networks for mid-scale Italian and Spanish processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction maturation is collapsing cost-performance gaps and accelerating clean-label displacement, positioning the market for sustained disruption as REACH compliance deadlines compress synthetic antioxidant permissible thresholds.
For Market Incumbents: Entrench solvent-free extraction certifications through backward integration into Moroccan rosemary cultivation partnerships, insulating margin predictability from weather-driven input volatility. Accelerate EFSA novel food dossier maintenance to freeze smaller extract houses out of new product launches as approval timelines extend.
For New Entrants and Emerging Players: Build out fermentation-derived antioxidant platforms that bypass agricultural yield constraints and enable year-round supply continuity for oxidation-sensitive formulations. Target California direct-to-consumer supplement brands with single-compound transparency documentation and small-lot, high-frequency order fulfillment capabilities.
For Investors and Strategic Acquirers: Mid-scale botanical extract houses with existing supercritical CO2 infrastructure and CSRD-compliant traceability systems represent priority acquisition targets. Long-term viability hinges on regulatory disclosure mandate compliance; monitor EFSA novel food catalog approval velocity as inflection indicator for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Moroccan rosemary partnerships secure feedstock continuity for Frankfurt-area processors facing REACH deadlines. |
| Supercritical CO2 Capacity Expansion | German extract houses deploy solvent-free systems to capture EFSA-compliant clean-label premiums from margarine manufacturers. |
| Fermentation Platform Development | Microbial carotenoid production bypasses Spanish cultivation volatility and enables consistent supply for feed additive markets. |
| Novel Food Dossier Investment | EFSA catalog pre-approvals create competitive moats that freeze smaller extract houses out of new botanical launches. |
| Direct-to-Consumer Channel Partnerships | California wellness brands contract directly with extract houses for single-ingredient transparency documentation. |
Research Approach
Cross-validation between primary interviews with rosemary cultivation operators, supercritical CO2 equipment manufacturers, EFSA regulatory consultants, and packaged food procurement directors anchors the qualitative findings against secondary validation from REACH authorization databases, EFSA novel food catalog submissions, and EU customs trade flows. Bottom-up triangulation across extraction capacity installations and top-down reconciliation against formulation spend patterns structure the analytical framework.
Calibration against historical CAGRs from botanical extract markets and fermentation-derived ingredient platforms shapes the projection methodology across the analysis window. Segmentation dimensions span molecular class, application category, botanical source, and distribution channel, with regulatory approval velocity and clean-label procurement intensity as industry-specific forecast inputs. Growth trajectories derive from elasticity modeling against synthetic preservative displacement thresholds.
Stress conditions across Moroccan agricultural yield variance, EFSA approval timeline extensions, and REACH threshold tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding supercritical CO2 equipment cost curves and fermentation platform scale-up economics. Cross-checking against EU Green Deal implementation progress and CSRD disclosure mandate enforcement is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
China Food Hydrocolloids Market