
 Russia Car Loan Market | 2026-2036
Russia Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Car Loan Market Insights
Securitized auto loan pools is tilting competitive dynamics toward institutions with balance-sheet depth and distribution scale. Sberbank leverages its branch network across federal subjects to originate volume at low acquisition cost. VTB Bank anchors its position through state-linked corporate fleet programs and dealer floorplan financing. Gazprombank competes by bundling fuel-card incentives with vehicle finance products for commercial borrowers.
A car loan is a secured consumer credit instrument collateralized by the vehicle title, typically structured with fixed monthly payments over two to seven years and governed by central bank reserve requirements on retail lending. Its primary commercial purpose is to bridge the gap between household savings and vehicle acquisition cost, converting durable-goods expenditure into serviceable debt streams. New-car loans command tighter spreads but depend on OEM subsidy programs, while used-car financing carries wider margins and faster portfolio turnover. Fixed-rate products dominate origination volumes as borrowers seek payment certainty against policy-rate volatility.
The Central Bank of Russia shapes lender behavior through macroprudential caps on debt-to-income ratios and risk-weighted asset rules for auto portfolios. CBR reporting standards on non-performing loans force transparency in vintage performance, while consumer protection statutes govern early repayment penalties and disclosure formats. Fleet operators and multi-brand dealer groups should monitor regulatory shifts in loan-loss provisioning requirements and any relaxation of subsidized-rate programs for domestic vehicle assembly.
Market Dynamics
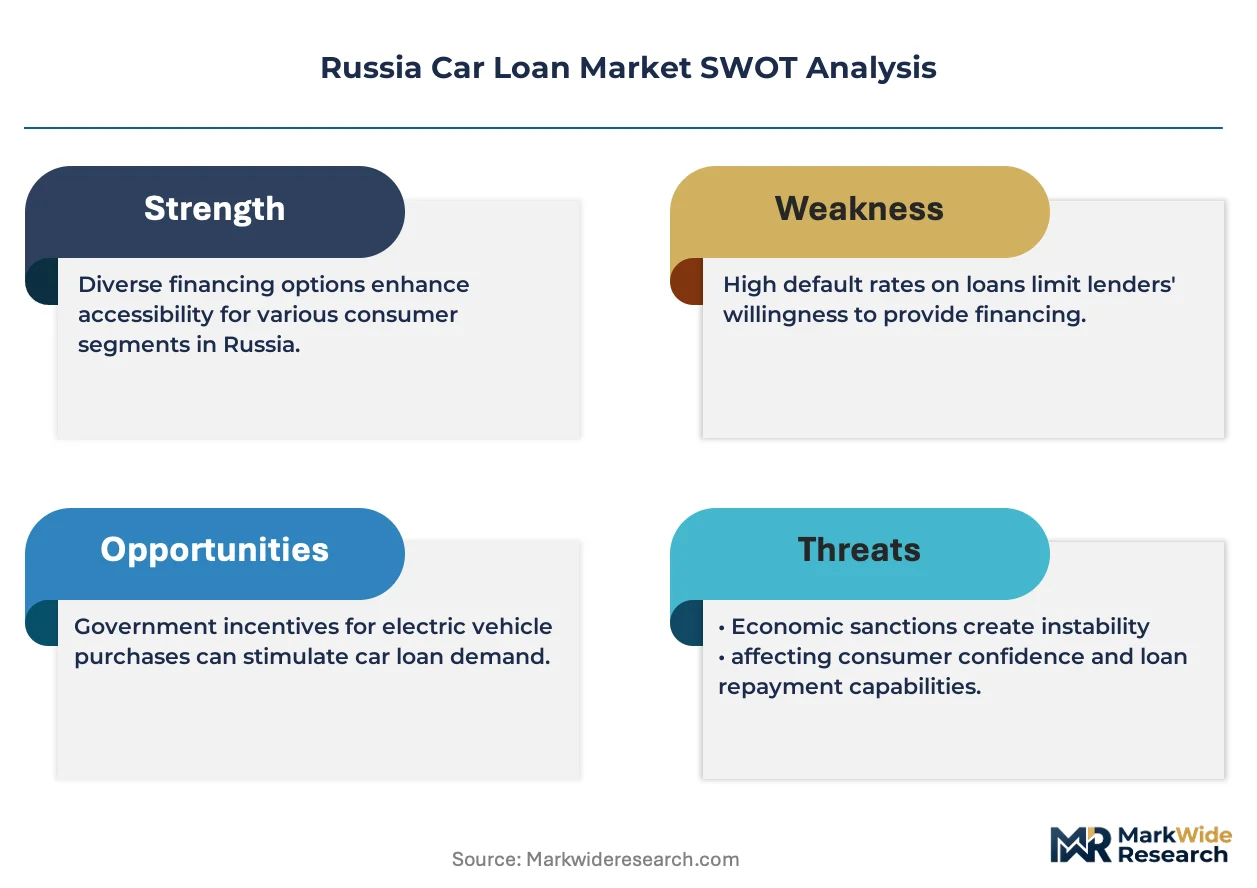
The Central Bank of Russia's macroprudential tightening on debt-to-income ratios and risk-weighted capital requirements is compressing lender margins while redistributing origination volume toward balance-sheet-heavy institutions with federal subject coverage.
Growth Catalysts
- Provincial First-Time Buyer Expansion:Demand from first-time vehicle purchasers in cities beyond Moscow and St. Petersburg is expanding the addressable borrower base. Regional bank branches in the Volga Federal District are capturing this inflow through localized credit scoring models.
- Used-Car Financing Margins:Wider spreads on pre-owned vehicle loans versus new-car products are attracting portfolio rebalancing by auto lenders. Faster turnover rates in used-car pools improve velocity metrics for originators.
- Central Bank Transparency Mandates:Mandatory CBR reporting standards on non-performing loan vintages are improving secondary market pricing for securitized auto pools. Institutional investors gain visibility into portfolio performance curves.
Market Restraints
- Policy Rate Volatility:Central Bank of Russia benchmark rate fluctuations compress net interest margins on fixed-rate auto products. Lenders face duration mismatch between floating-rate funding and fixed-rate receivables.
- Domestic Assembly Subsidy Uncertainty:State support programs for domestic vehicle production create dependency risk in new-car loan origination. Floorplan financing exposure concentrates on OEMs with subsidy-linked assembly operations.
- Collateral Depreciation Velocity:Rapid vehicle value erosion in the Russian secondary market elevates loan-to-value risk in secured auto portfolios. Recovery rates on defaulted loans trail European benchmarks.
Strategic Opportunities
- Embedded Insurance Bundling:Integration of compulsory motor third-party liability coverage with loan origination workflows captures ancillary revenue streams. Digital policy issuance at point of sale reduces friction in the borrower journey.
- Commercial Fleet Electrification:Corporate borrowers replacing diesel light-commercial vehicles with electric alternatives require structured asset finance products. Gazprombank's fuel-card infrastructure positions it for bundled charging-credit offerings.
- Securitization Pipeline Depth:Institutional demand for ruble-denominated structured credit is deepening primary issuance capacity for auto loan ABS. Originators with scale advantages gain funding cost separation from smaller competitors.
Industry Challenges
- Legacy Core System Integration:Regional banks with Soviet-era IT infrastructure face complexity in deploying real-time credit decisioning engines. API connectivity to dealer management systems requires middleware investment.
- Collections Workforce Scarcity:Specialized auto loan recovery agents with legal enforcement expertise are concentrated in Moscow. Provincial originators face talent gaps in field-based asset repossession operations.
- Cross-Border Sanctions Compliance:Restrictions on correspondent banking relationships complicate foreign-currency denominated fleet financing for multinational corporate borrowers. Documentation standards require continuous legal review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Car Loan Market |
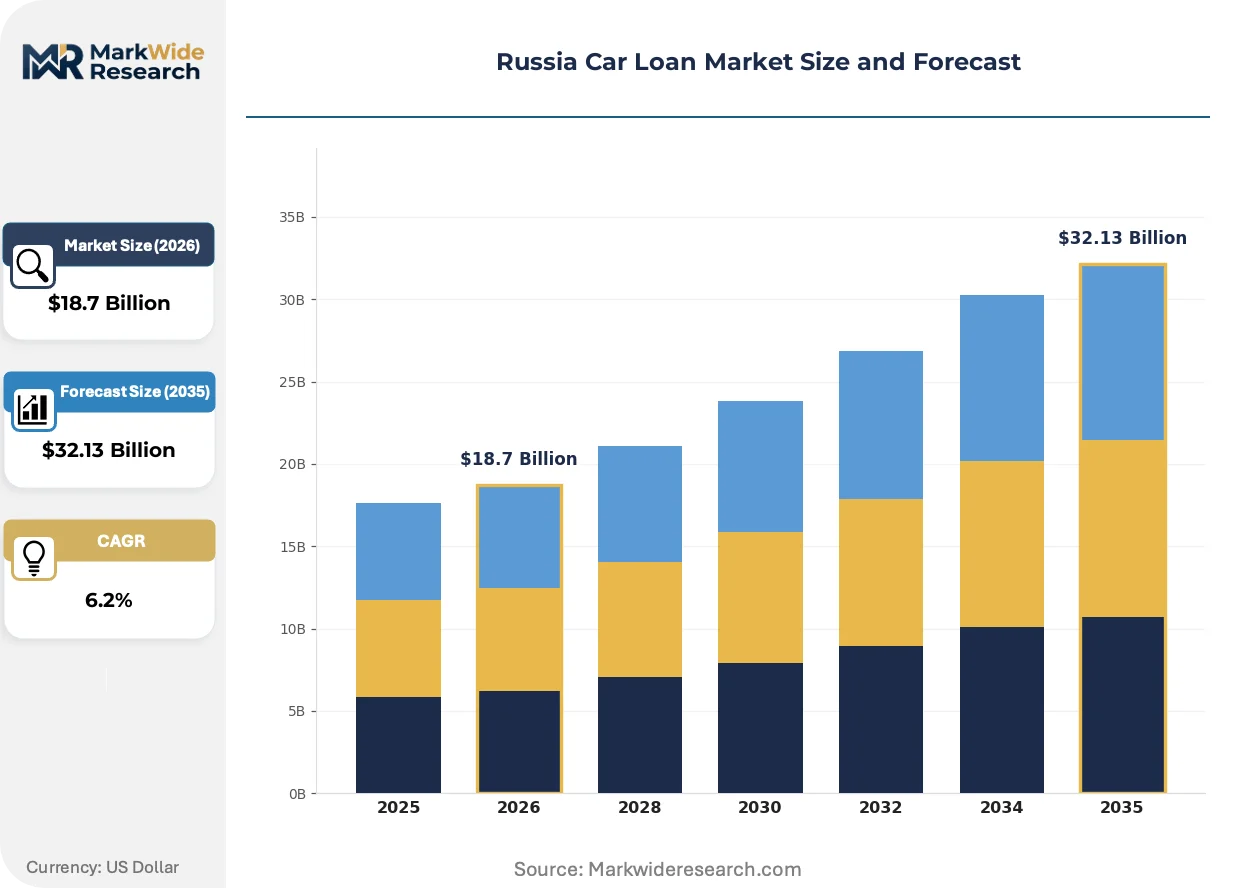
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Cars, Used Cars, Electric Vehicles, Luxury Vehicles Loan Term: Short-Term, Medium-Term, Long-Term, Flexible Term Interest Rate Type: Fixed Rate, Variable Rate, Discounted Rate, Promotional Rate Customer Type: Individual Borrowers, Corporate Clients, Fleet Operators, First-Time Buyers |
| Companies Covered | Sberbank, VTB Bank, Gazprombank, Unicredit Group, Alfa-Bank, Rosbank, Auto Finance Bank, Raiffeisenbank, Rosselkhozbank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Car Loan Market Trends and Innovations
Digital origination platforms and alternative data scoring are compressing decision timelines while regulatory disclosure mandates are reshaping secondary market liquidity for auto loan portfolios.
Machine learning models incorporating telematics-derived driving behavior and alternative bureau data are rendering obsolete traditional credit-scoring approaches reliant solely on income verification and collateral appraisal. Regional banks in the Ural Federal District are piloting these systems for thin-file borrowers. The structural consequence is expanded credit access for gig-economy workers previously excluded from prime auto financing tiers.
Central Bank of Russia directives on loan-loss provisioning granularity are forcing vintage-level disclosure of 90-plus-day delinquency curves. This transparency requirement is compressing information asymmetry between originators and ABS investors. Securitization sponsors must now maintain granular performance data infrastructure to access institutional capital.
Subscription-based vehicle access models are fragmenting traditional ownership patterns among urban professionals in Moscow and St. Petersburg. Fleet operators and multi-brand dealer groups are responding with residual-value-backed short-term finance products. This behavioral shift is most visible in the premium segment where lessees prioritize flexibility over equity accumulation.
Russia Car Loan Market Segmentation
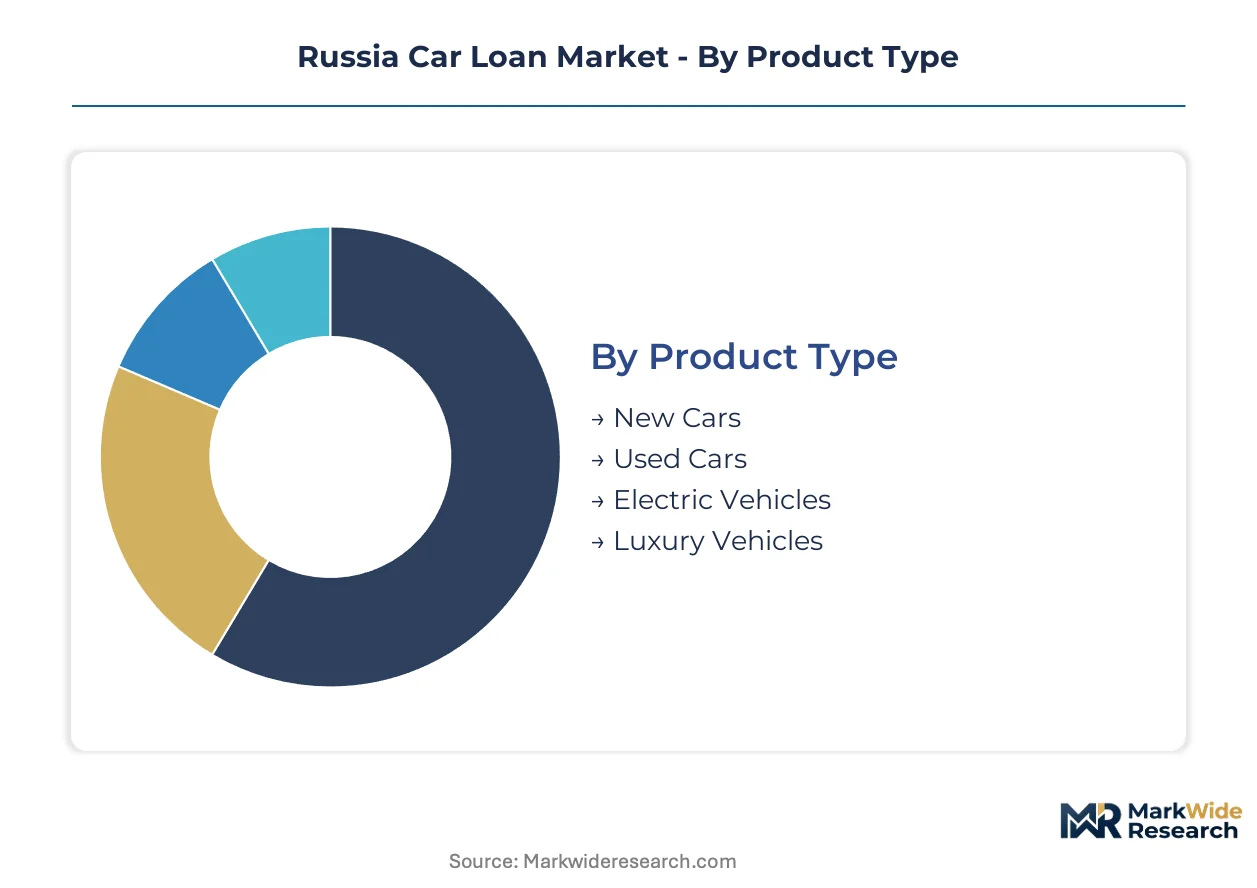
Portfolio turnover velocity varies dramatically across Russia's car loan segments, with used-car pools cycling faster than new-vehicle paper and short-term products repricing more frequently than long-dated obligations. Lenders optimize capital deployment by matching funding duration to segment-specific amortization curves.
Product Type:
Used-car financing turns over fastest as collateral ages accelerate payoff incentives, while electric vehicle loans carry extended durations due to higher principal amounts and residual value uncertainty.
- New Cars:Factory-backed subsidy programs compress borrower rates below risk-adjusted levels. Sberbank dominates origination in Moscow and St. Petersburg through OEM-captive partnerships. Central Bank reserve requirements treat new-car pools as lower-risk weighted assets.
- Used Cars:Wider spreads compensate for collateral depreciation velocity and information asymmetry in vehicle condition. Volga Federal District branches capture disproportionate volume from provincial first-time buyers seeking affordable transportation. Faster portfolio turnover improves lender velocity metrics.
- Electric Vehicles:Sparse charging infrastructure outside major metros constrains demand concentration. Domestic assembly incentives from the Ministry of Industry and Trade shape lender subsidy eligibility.
- Luxury Vehicles:Thin secondary market liquidity elevates recovery risk on defaulted collateral. Moscow-based private banking units handle bespoke structuring for high-net-worth borrowers.
Used Cars anchors the volume base while Electric Vehicles gains share at the steepest rate.
Loan Term:
Cost tier stratification separates mass-market borrowers seeking payment minimization from commercial fleets optimizing total cost of ownership through accelerated depreciation schedules.
- Short-Term:12-24 month structures minimize total interest expense for cash-flow-sensitive borrowers. Regional banks in the Siberian Federal District favor this product for seasonal income earners.
- Medium-Term:Three-to-five year tenors balance payment affordability with interest cost containment. This structure captures the median Russian household's debt service capacity.
- Long-Term:Six-to-seven year maturities stretch qualification ratios for entry-level new-car buyers. Extended duration amplifies duration mismatch risk for fixed-rate originators.
- Flexible Term:Seasonal payment schedules align with agricultural and construction sector cash flows. Ural Federal District pilots target SME fleet operators with harvest-linked repayment calendars.
Medium-Term structures carry the largest outstanding balance while Flexible Term products expand most quickly among non-standard employment categories.
Interest Rate Type:
Customer sophistication divides the market between payment-certainty seekers and rate-speculative borrowers willing to accept benchmark exposure for upfront savings.
- Fixed Rate:Payment certainty dominates borrower preference amid Central Bank policy volatility. Sberbank and VTB Bank compete on origination volume through rate-lock guarantees at application.
- Variable Rate:Floating structures indexed to CBR key rate offer lower initial carrying costs. Borrower uptake concentrates among financially sophisticated corporate fleet managers.
- Discounted Rate:OEM-subsidized programs penetrate new-car showrooms with below-market financing. Domestic assembler eligibility depends on localization thresholds monitored by the Ministry of Industry and Trade.
- Promotional Rate:Limited-duration teaser structures convert showroom traffic during model-year transitions. Dealer floorplan exposure concentrates risk in inventory-heavy balance sheets.
Fixed Rate products dominate origination flow while Discounted Rate structures climb the fastest as domestic assembly incentives expand.
Customer Type:
Application purpose separates household mobility expenditure from commercial asset deployment, with fleet scale determining lender servicing economics and covenant complexity.
- Individual Borrowers:Salary-backed installment structures constitute the retail banking core. Debt-to-income caps enforced by Central Bank macroprudential regulation constrain qualification ratios.
- Corporate Clients:Balance-sheet financing for executive vehicles and sales fleets requires structured asset-backed facilities. Gazprombank bundles fuel-card incentives with vehicle finance for commercial borrowers.
- Fleet Operators:Multi-unit acquisition programs demand residual value guarantees and maintenance bundling. Leasing structures compete with term loans for municipal and logistics contract vehicles.
- First-Time Buyers:Thin credit files and down payment constraints elevate loan-to-value ratios. Regional banks in the North Caucasus Federal District deploy alternative data scoring for gig-economy applicants.
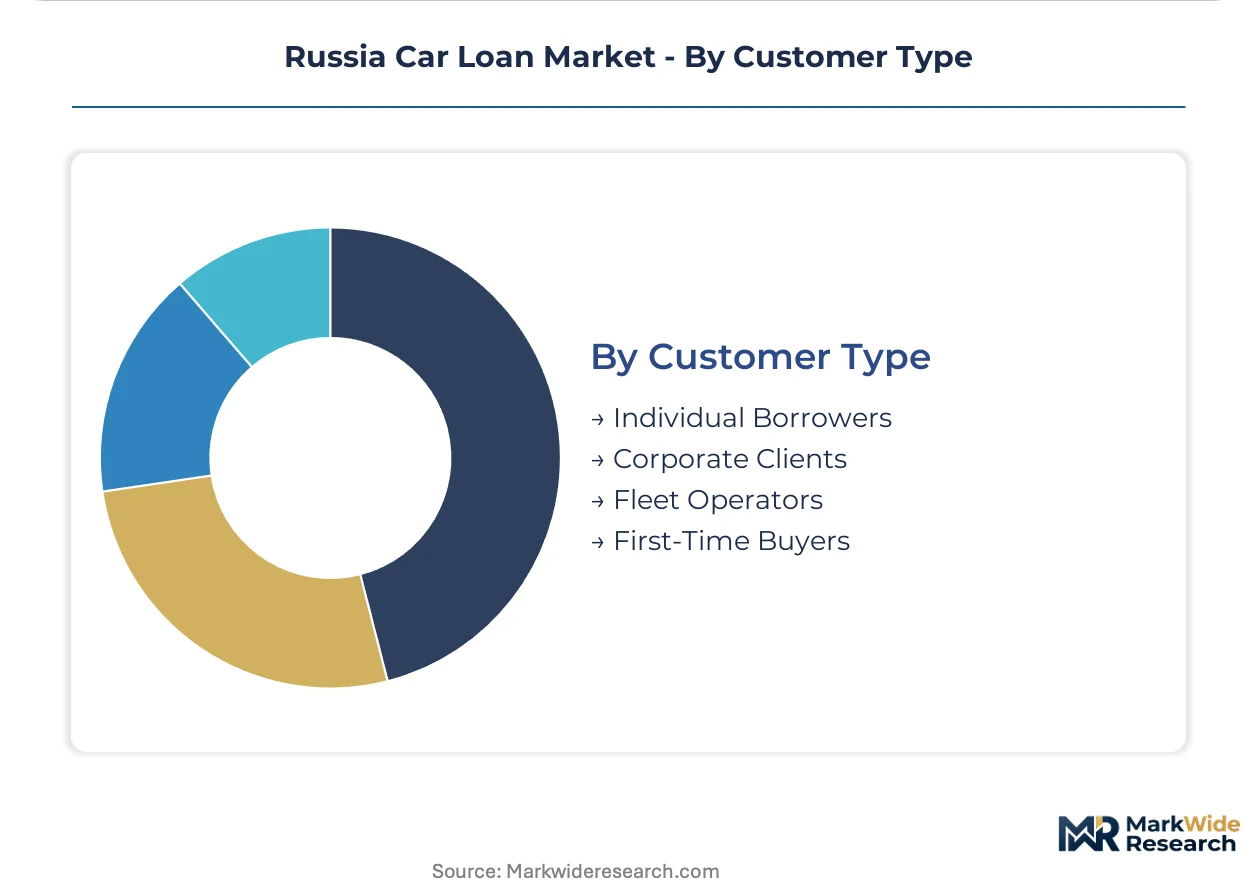
Individual Borrowers anchors the volume base while First-Time Buyers gains share at the steepest rate as provincial penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed subsidized-rate programs for domestic vehicle assembly are redistributing origination volume across Russia's federal districts. The Central Bank of Russia's macroprudential caps on debt-to-income ratios compress margins unevenly, favoring lenders with branch density in high-growth provincial markets.
Volga Federal District
First-time buyers in Kazan, Samara, and Nizhny Novgorod drive used-car financing demand. Regional banks deploy localized credit scoring for thin-file applicants in this corridor. The Ministry of Industry and Trade's assembly incentives for domestic OEMs concentrate dealer floorplan exposure in Tatarstan and Samara Oblast.
Central Federal District
Moscow-based fleet operators and executive vehicle programs anchor corporate origination volumes. The Central Bank of Russia's reporting standards on non-performing loan vintages force transparency from lenders headquartered in the capital. Premium segment leasing structures compete with term loans for municipal contract vehicles in the Moscow agglomeration.
Siberian Federal District
Seasonal income earners in Novosibirsk and Krasnoyarsk favor short-term 12-24 month structures. Regional originators pilot flexible repayment calendars aligned with agricultural and construction sector cash flows. The district's sparse charging infrastructure outside major metros constrains electric vehicle loan penetration.
Ural Federal District
Machine learning scoring models incorporating telematics data expand credit access for gig-economy workers in Yekaterinburg and Chelyabinsk. Alternative bureau data pilots target thin-file borrowers previously excluded from prime tiers. Mining sector fleet operators demand residual value guarantees on light-commercial vehicle replacements.
North Caucasus Federal District
Provincial first-time buyer penetration deepens in Grozny and Makhachkala with elevated loan-to-value ratios. Regional banks deploy alternative data scoring to qualify applicants with informal income documentation. Collateral depreciation velocity in the secondary market elevates recovery risk relative to European benchmarks.
Russia Car Loan Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market tilting toward balance-sheet-heavy institutions with federal subject coverage. State-linked banks leverage branch networks and corporate relationships to originate at scale, while smaller regional lenders compete on localized underwriting flexibility. Two strategic archetypes dominate: distribution-integrated universal banks with low acquisition costs, and fuel-infrastructure bundlers targeting commercial fleets. Competitive moves concentrate on securitization pipeline development and embedded insurance integration at point of sale.
Among Moscow-based universal banks, Sberbank occupies a position exemplifying distribution-scale advantage through federal subject branch density. VTB Bank anchors the state-linked corporate tier, representing lenders that bundle dealer floorplan financing with fleet programs. Gazprombank sits within the infrastructure-bundling archetype, positioned to integrate fuel-card incentives with commercial vehicle finance. These three entities collectively illustrate the market's polarization between channel control and product specialization.
| Leading Market Players |
|---|
| Sberbank |
| VTB Bank |
| Gazprombank |
| Unicredit Group |
| Alfa-Bank |
| Rosbank |
| Auto Finance Bank |
| Raiffeisenbank |
| Rosselkhozbank |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic vehicle assembly capacity across the Volga Federal District is compressing dealer floorplan margins while elevating acquisition costs for regional lenders. This utilization squeeze propagates through the value chain, forcing originators to absorb higher wholesale vehicle costs or pass through rate adjustments to provincial first-time buyers.
Pricing Analysis
Collateral depreciation velocity creates the primary spread between new-car and used-car financing tiers, with wider margins on pre-owned vehicles compensating for accelerated value erosion and information asymmetry in condition assessment. Sberbank and VTB Bank compete on origination volume through rate-lock guarantees, while regional banks price for risk using localized credit scoring. Pricing pressure stems from Central Bank macroprudential caps on debt-to-income ratios that compress net interest margins. First-time buyers in provincial cities exhibit highest price sensitivity, while corporate fleet managers prioritize total cost of ownership over rate minimization.
Supply Chain Analysis
Export control restrictions on semiconductor and advanced manufacturing technology flows from the European Union and United States are constraining domestic vehicle production inputs and extending assembly lead times. Russia's automotive supply chain draws from China for electric vehicle components, from domestic Tatarstan and Samara Oblast facilities for internal combustion assembly, and from Turkey for select Tier 1 parts. Single-source vulnerability concentrates in advanced driver-assistance systems and battery management controllers. Distribution runs through multi-brand dealer groups with floorplan financing exposure to state-linked universal banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's car loan market sits in early-cycle expansion as provincial first-time buyer penetration deepens beyond Moscow and St. Petersburg, with alternative data scoring unlocking credit access for thin-file borrowers previously excluded from prime tiers.
For Market Incumbents: Insulate securitization pipeline capacity against regulatory transparency mandates by investing in vintage-level performance data infrastructure before Central Bank disclosure requirements harden. Consolidate field-based collections capabilities in provincial markets where specialized auto loan recovery agents remain scarce, and acquire alternative data scoring licenses to defend origination share against fintech entrants targeting gig-economy segments.
For New Entrants and Emerging Players: The North Caucasus Federal District offers the most penetrable geography for thin-file auto lending, with elevated loan-to-value demand from provincial first-time buyers and limited incumbent presence in alternative data underwriting. Target commercial fleet electrification in the Ural Federal District, where mining sector operators seek residual value guarantees on light-commercial vehicle replacements. Lead with embedded insurance bundling at point of sale to capture ancillary revenue and reduce customer acquisition friction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because macroprudential tightening favors balance-sheet-heavy institutions with federal subject branch density over thinly capitalized regional competitors. Acquisition targets should display scale advantages in securitization infrastructure or fuel-infrastructure bundling capabilities for commercial fleets. The signal to watch is any relaxation of subsidized-rate programs for domestic vehicle assembly, which would reprice new-car loan origination volumes and shift competitive positioning toward used-car specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Data Scoring Deployment | Machine learning models incorporating telematics expand credit access for gig-economy workers in Yekaterinburg and Chelyabinsk. |
| Securitization Pipeline Development | Granular vintage-level disclosure infrastructure accesses institutional capital as Central Bank transparency mandates compress information asymmetry. |
| Embedded Insurance Integration | Digital policy issuance at point of sale captures ancillary revenue and reduces friction in the borrower journey for provincial first-time buyers. |
| Commercial Fleet Electrification Financing | Structured asset finance products for electric light-commercial vehicles leverage Gazprombank's fuel-card infrastructure for bundled charging-credit offerings. |
| Provincial Collections Capability Buildout | Field-based asset repossession operations in the North Caucasus Federal District address talent gaps concentrated in Moscow. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with auto lending executives, dealer floorplan managers, Central Bank regulatory affairs specialists, and provincial branch operations heads; and secondary validation through Central Bank of Russia macroprudential reporting, Ministry of Industry and Trade assembly incentive disclosures, and federal subject vehicle registration databases. Bottom-up origination volume triangulation against top-down central bank consumer credit aggregates calibrated market sizing.
Forecast inputs incorporated debt-to-income regulatory trajectory, domestic assembly subsidy durability, and provincial penetration rates across the projection horizon. Segmentation dimensions modeled include vehicle condition tier, loan term structure, interest rate fixation, and customer archetype. CAGRs derived from vintage-level amortization curve analysis and policy-rate sensitivity testing, with electric vehicle adoption curves and charging infrastructure buildout as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Central Bank benchmark rate trajectory, ruble volatility, or sanctions regime intensity would shift the trajectory. Material shifts in domestic vehicle assembly subsidy eligibility or loan-loss provisioning requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Premium Finance Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Mexico Home Equity Lending Market