
 Cash Advance Services Market | 2026-2036
Cash Advance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Advance Services Market Outlook
Platform fee revenue is tilting from traditional storefront lending toward digital disbursement channels. Square Inc. leverages its merchant ecosystem to embed cash advances directly at point-of-sale, reducing customer acquisition friction. PayPal Holdings Inc. sustains a global user base that feeds proprietary underwriting algorithms for instant advance decisions. SoFi Technologies Inc. anchors its positioning in the individual borrower segment through employment-verification-linked products.
Cash advance services constitute short-term liquidity instruments where providers disburse funds against anticipated income streams, typically employing automated repayment via bank account debits or future card receivables with factor rates rather than simple interest calculations. The primary commercial purpose centers on bridging temporal mismatches between expense obligations and revenue receipt for consumers and micro-enterprises excluded from conventional credit markets. Merchant cash advances attract disproportionate margin attention as small business working capital needs intensify, while payday loans retain volume dominance despite regulatory compression in multiple jurisdictions. Installment loans emerge as the fastest-growing structural category as borrowers seek amortization schedules over single-payment obligations.
The US Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure mandates that reshape product presentation and comparison standards for cash advance providers. State-level usury caps and licensing requirements across California, Texas, and New York create a fragmented compliance mosaic that elevates operational complexity for national platforms. The UK Financial Conduct Authority's cost cap framework and Australia's National Consumer Credit Protection Act demonstrate convergent regulatory trajectories toward borrower affordability tests. Stakeholders must monitor how real-time payroll data integration and earned wage access models redraw the boundary between regulated credit products and unregulated salary advances.
Market Dynamics
Automated payroll data integration is compressing underwriting timelines from days to minutes, forcing providers to rebuild risk engines around real-time employment verification rather than traditional credit scoring.
Growth Catalysts
- Truth in Lending Act enforcement:The US Consumer Financial Protection Bureau mandates standardized disclosure formats that reduce borrower confusion and accelerate platform comparison shopping.
- Gig economy workforce expansion:Platform workers with irregular income streams generate sustained demand for earned wage access products that bridge pay cycle gaps.
- Embedded finance APIs:Payment processors integrate cash advance origination directly into merchant dashboards, collapsing customer acquisition costs for small business lending.
Market Restraints
- State-level usury fragmentation:California, Texas, and New York maintain divergent rate caps and licensing requirements that prevent standardized national product rollouts.
- Bank partner concentration:Reliance on a limited pool of chartered institutions for compliance and funding creates single-point-of-failure risk in the sponsor bank model.
- ACH debit failure rates:Automated repayment mechanisms face elevated return rates from thin-file borrowers, eroding unit economics for high-frequency advance products.
Strategic Opportunities
- Employer-sponsored earned wage access:Regulatory frameworks in Australia and the United Kingdom create compliant pathways for salary-linked advances outside traditional credit licensing.
- Real-time payments infrastructure:The US FedNow network enables instant disbursement without card network rails, opening white-label advance distribution through community banks.
- Behavioral underwriting convergence:Cash flow analytics from open banking APIs merge with employment data to score previously unscorable borrower segments.
Industry Challenges
- Data engineering talent scarcity:Platforms compete for machine learning engineers capable of building real-time risk models that satisfy both speed and compliance requirements.
- Legacy core banking integration:Sponsor bank technology stacks impose latency constraints that conflict with consumer expectations for instant advance decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Advance Services Market |
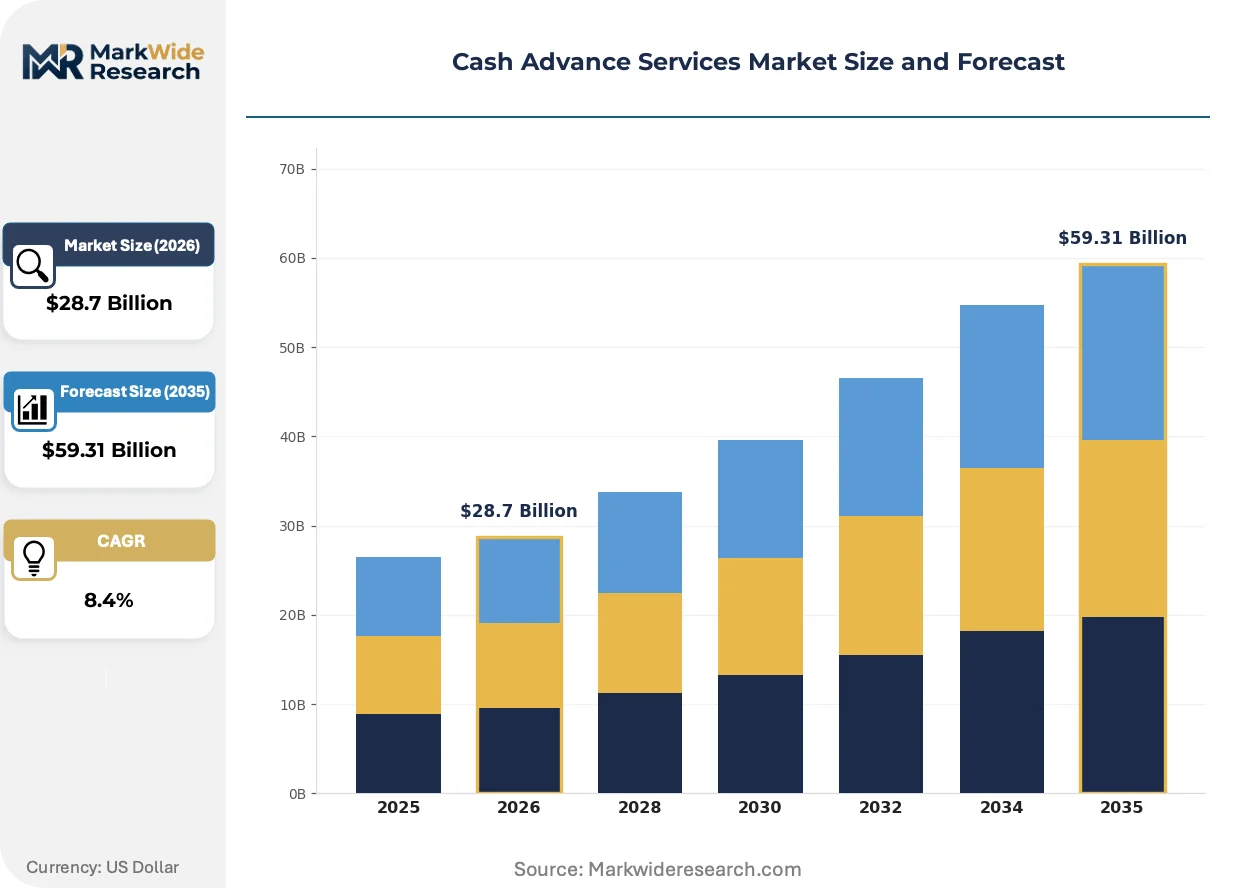
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payday Loans, Title Loans, Installment Loans, Merchant Cash Advances Customer Type: Individuals, Small Businesses, Corporations, Freelancers Interest Model: Fixed Rate, Variable Rate, APR, Deferred Payment Loan Purpose: Emergency Expenses, Business Investment, Debt Consolidation, Unexpected Bills |
| Companies Covered | Square Inc., Worldpay Inc., Wells Fargo & Co., ACE Cash Express Inc., Advance America Cash Advance Centers Inc., American Express Company, Stripe Inc., SoFi Technologies Inc., PayPal Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Advance Services Market Strategic Shifts
Real-time data infrastructure is collapsing the boundary between payroll systems and credit origination, enabling product designs that were technically impossible under batch-processing architectures.
Open banking protocols are digitizing cash flow underwriting by enabling direct access to transaction histories without credential sharing. Fintech platforms serving underbanked consumers deploy these APIs to bypass traditional credit bureaus entirely. The structural compression of verification steps is digitizing the path from application to funding from hours to seconds.
The UK Financial Conduct Authority's cost cap framework is forcing product redesigns that eliminate balloon-payment structures in favor of amortizing installment schedules. Lenders operating across multiple jurisdictions must maintain parallel compliance stacks. Small-sum credit providers in the United Kingdom are responding by capping total cost of credit at 0.8% per day and mandatory affordability assessments.
Borrower preference is gravitating toward transparent fee structures that displace opaque factor-rate pricing. Digital-native consumers comparison-shop across platforms using annualized cost metrics rather than flat fees. This behavioral shift is most pronounced among gig workers in urban United States markets where earned wage access apps compete directly with traditional payday products.
Cash Advance Services Market Segmentation
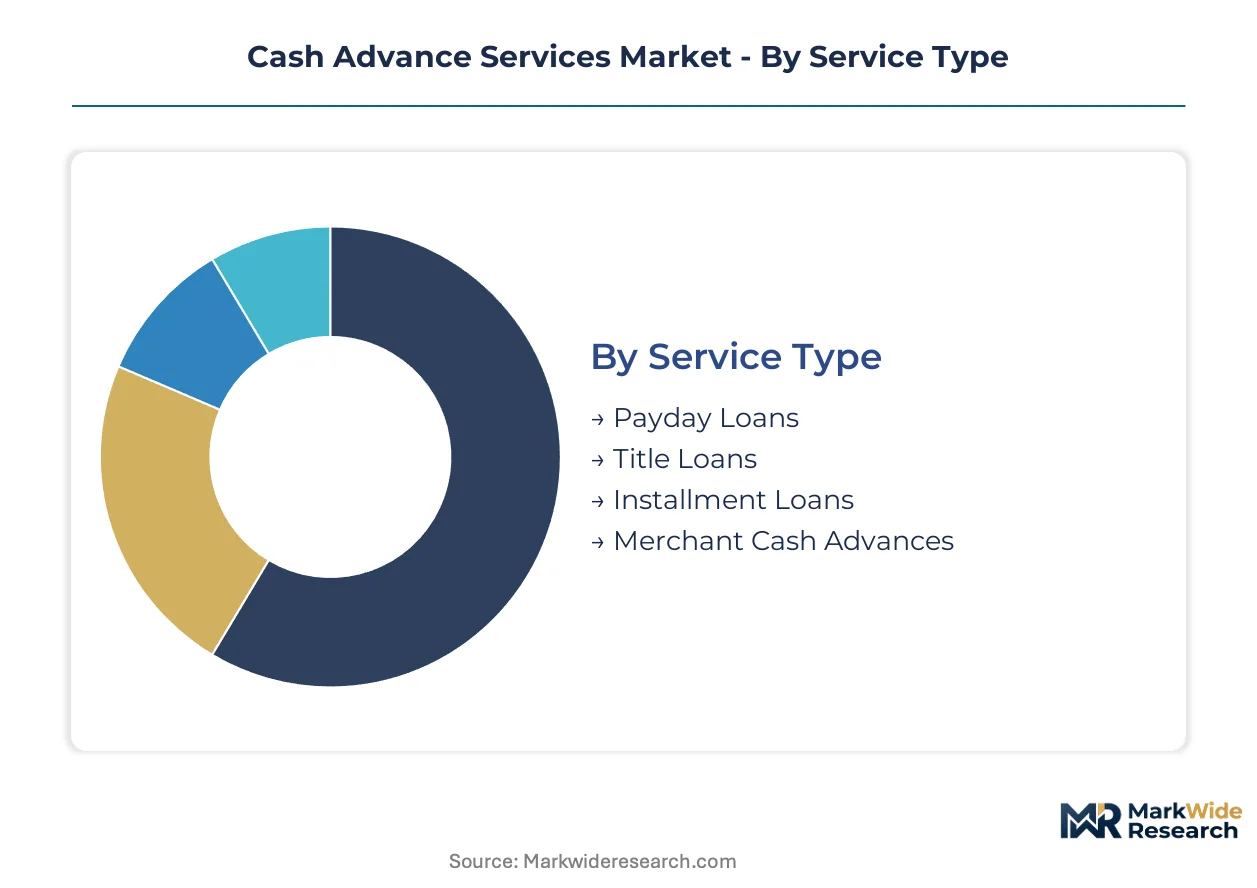
Cash advance providers tailor product architecture to distinct liquidity pressures and repayment capacities. Segmentation reveals how underwriting models, pricing mechanics, and distribution channels diverge across borrower circumstances and use cases.
Service Type:
Product design spans single-payment obligations to revenue-linked amortization structures, each calibrated to specific cash flow patterns and collateral availability.
- Payday Loans:Short-term unsecured advances against anticipated wages, typically repaid via single ACH debit on the borrower's next pay date. Demand concentrates among underbanked consumers in Texas and California, where state licensing frameworks permit higher factor rates than installment alternatives.
- Installment Loans:Amortizing credit products with scheduled payments over 3-24 months, displacing balloon-payment structures under UK Financial Conduct Authority cost-cap mandates. These products are expanding most quickly in urban United States markets where gig workers seek predictable repayment schedules.
- Title Loans:Secured advances collateralized by vehicle titles, carrying lower loss rates but geographic constraints from state-level repossession regulations.
- Merchant Cash Advances:Future receivables purchases repaid via daily card settlement splits, dominating small business working capital provision.
The dominant share belongs to Payday Loans, while Installment Loans are closing the gap fastest.
Customer Type:
Underwriting sophistication escalates with documentation depth, from thin-file consumers to payroll-integrated employees.
- Individuals:Consumer borrowers accessing advances through direct-to-consumer platforms or retail storefronts, segmented by credit bureau presence and banking history depth.
- Small Businesses:Micro-enterprises with seasonal revenue volatility, served through payment processor partnerships that embed advance origination in merchant dashboards.
- Freelancers:Platform workers with irregular income streams, driving earned wage access adoption through employment-verification APIs rather than traditional credit scoring.
- Corporations:Mid-market enterprises utilizing revolving credit facilities or supply chain finance, outside the core cash advance product perimeter.
Individual borrowers command the largest transaction volume, though Freelancers demonstrate the steepest expansion trajectory as gig economy participation broadens.
Interest Model:
Pricing transparency obligations under Truth in Lending Act enforcement are compressing factor-rate dominance toward standardized APR disclosure.
- Fixed Rate:Predetermined cost structures enabling certain repayment planning, prevalent in installment products targeting credit-building consumers.
- APR:Annualized percentage rate presentation mandated for comparison shopping, accelerating platform switching behavior among digitally native borrowers.
- Variable Rate:Cost structures tied to reference indices, rare in short-duration products but emerging in longer-term small business facilities.
- Deferred Payment:Grace-period structures accumulating fees during non-payment windows, facing regulatory scrutiny under affordability assessment requirements.
APR-based pricing is displacing opaque alternatives fastest, while Fixed Rate structures retain loyalty among risk-averse repeat borrowers.
Loan Purpose:
Use-case specificity determines advance size, duration, and channel selection, from emergency disbursement to strategic business investment.
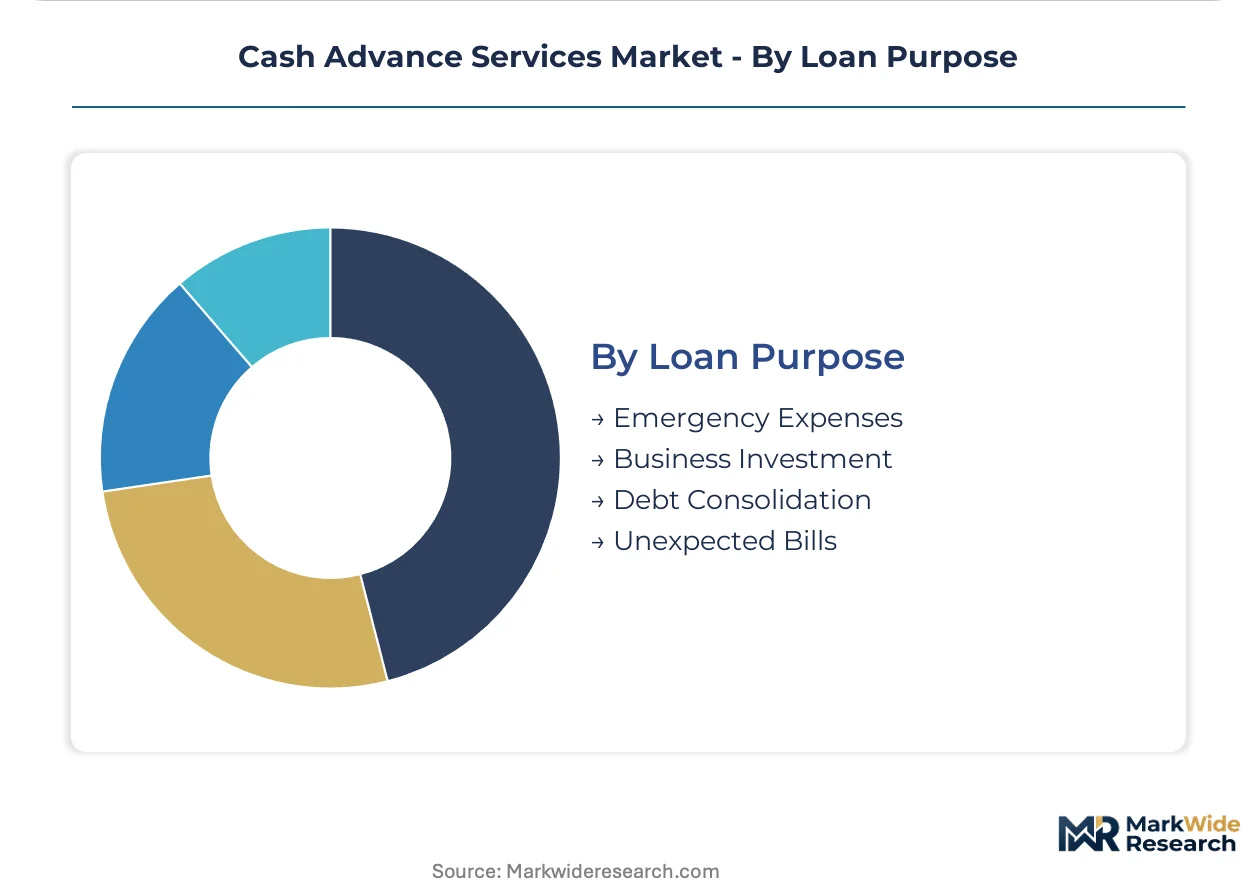
- Emergency Expenses:Medical or automotive liquidity crises demanding same-day funding, concentrated in markets with limited savings penetration.
- Unexpected Bills:Utility or rent obligations with strict due dates, driving demand for earned wage access products that bridge pay cycle gaps.
- Business Investment:Inventory or equipment purchases with anticipated revenue conversion, served through merchant cash advance products with revenue-linked repayment.
- Debt Consolidation:Refinancing of existing high-cost obligations into single amortizing schedules, requiring longer durations and stricter underwriting.
Emergency Expenses generate the highest transaction frequency, while Business Investment advances produce the largest average ticket sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies: gig workers in high-cost metros tolerate premium fees for speed, while rural borrowers prioritize absolute cost over disbursement velocity. The United States exhibits the widest elasticity spread between these extremes.
United States
Gig economy participation in California and Texas sustains demand for earned wage access products with instant disbursement. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure mandates that reshape product transparency nationwide. Miami-Dade and Atlanta clusters concentrate storefront payday lending, while San Francisco and New York City anchor platform-based digital advance origination.
United Kingdom
Platform workers in London and Manchester drive adoption of salary-linked advance products outside traditional credit licensing. The Financial Conduct Authority's cost cap framework mandates 0.8% daily interest ceilings and affordability assessments. The Southeast England corridor hosts fintech clusters developing open banking-enabled underwriting for thin-file borrowers.
Australia
Underbanked consumers in Sydney and Melbourne generate demand for short-term liquidity bridging pay cycle gaps. The National Consumer Credit Protection Act imposes responsible lending obligations and fee structure limitations. The Melbourne fintech precinct concentrates earned wage access providers integrating with real-time payroll systems.
Germany
Small business working capital gaps in Bavaria and North Rhine-Westphalia sustain merchant cash advance adoption through payment processor partnerships. BaFin supervision applies consumer credit directives to cross-border platform offerings. The Berlin startup ecosystem hosts embedded finance developers building advance origination APIs for merchant dashboards.
India
Gig platform workers in Maharashtra and Karnataka drive demand for instant salary advances against verified employment data. The Reserve Bank of India regulates digital lending through scale-based framework notifications and data localization requirements. The Mumbai-Pune corridor concentrates fintech platforms deploying alternative credit scoring for thin-file borrowers.
Cash Advance Services Market Competitive Environment
Capability concentration sits with fintech platforms possessing real-time underwriting infrastructure; scale advantage sits with incumbent payment processors commanding merchant ecosystem access. The market structure bifurcates between technology-native specialists and financial institution-backed generalists. Three archetypes dominate: merchant-embedded providers, direct-to-consumer platforms, and bank-sponsored hybrid models. Competitive moves center on payroll data API integrations and sponsor bank diversification to reduce concentration risk.
Within the payment processor tier, Square Inc. and Stripe Inc. occupy positions exemplifying merchant-ecosystem-embedded advance origination. PayPal Holdings Inc. anchors the global consumer-facing segment with cross-border infrastructure. SoFi Technologies Inc. represents the employment-verification-linked product archetype targeting individual borrowers. These three entities illustrate the strategic divergence between merchant-linked, consumer-direct, and salary-integrated distribution models.
| Leading Market Players |
|---|
| Square Inc. |
| Worldpay Inc. |
| Wells Fargo & Co. |
| ACE Cash Express Inc. |
| Advance America Cash Advance Centers Inc. |
| American Express Company |
| Stripe Inc. |
| SoFi Technologies Inc. |
| PayPal Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Mumbai-Pune corridor fintech clusters anchor algorithmic underwriting capacity that compresses origination costs and feeds downstream pricing power to platform-based providers. Factor-rate structures persist in Texas and California storefront lending, while APR-mandated transparency in United Kingdom and Australian markets forces fee compression through standardized disclosure.
Pricing Analysis
Origination fee revenue and daily interest accruals drive lifetime value in merchant cash advance products. Three-tier pricing structure across premium instant-disbursement, standard next-day, and economy ACH-settlement tiers segments borrower urgency. Price differentiation hinges on employment-verification depth and real-time payroll API integration quality. Pricing pressure stems from open banking proliferation that commoditizes thin-file underwriting. Gig workers in urban United States markets exhibit highest price sensitivity, while small businesses with seasonal volatility tolerate premium factor rates for revenue-linked repayment flexibility.
Supply Chain Analysis
Supplier-financing facilities from sponsor banks extend payment terms to cash advance platforms, embedding working capital risk in the funding layer. Underwriting technology development concentrates in United States, United Kingdom, and India. Risk engines draw from employment-verification APIs, open banking transaction feeds, and alternative credit scoring models. Single-source vulnerability sits with concentrated sponsor bank partnerships that face regulatory scrutiny. Distribution runs through payment processor dashboards, direct-to-consumer mobile applications, and employer-integrated earned wage access portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cash advance services market functions as a defensive-moat business where regulatory entrenchment and switching costs protect incumbent positions. Network effects from payroll data API integrations compound competitive advantage for established platforms.
For Market Incumbents: Pre-empt sponsor bank diversification to mitigate concentration risk from Truth in Lending Act enforcement actions. Deepen vertical integration into real-time payroll data infrastructure to lock out emerging API competitors. Defensive patenting around behavioral underwriting algorithms protects against fintech entrants with inferior data engineering depth.
For New Entrants and Emerging Players: Establish a beachhead in employer-sponsored earned wage access, the fastest-penetrating segment outside traditional credit licensing. White-label distribution through community banks leveraging FedNow instant payment rails offers lowest customer acquisition friction. Target thin-file freelancers in Maharashtra and Karnataka where alternative credit scoring gaps persist.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with embedded finance API capabilities and sponsor bank relationship depth. Long-term viability rests on regulatory compliance automation that scales across fragmented state-level usury frameworks. Acquisition target archetype: fintechs with real-time employment verification patents and Australian or United Kingdom regulatory licenses. Monitor ACH debit failure rate trends as inflection indicator for unit economics deterioration.
| Strategic Initiative | Industry Significance |
|---|---|
| Payroll API Integration | Employment-verification data feeds from ADP and Workday collapse underwriting timelines to seconds. |
| Sponsor Bank Diversification | Multiple chartered institution relationships mitigate single-point-of-failure risk from regulatory enforcement. |
| Earned Wage Access Licensing | Australian and United Kingdom frameworks enable salary-linked advances outside consumer credit regimes. |
| Real-Time Payments Infrastructure | FedNow network integration enables instant disbursement without card network interchange fees. |
| Open Banking Underwriting | Transaction history APIs from Plaid and Yodlee bypass traditional credit bureaus for thin-file scoring. |
Study Parameters
The analysis maps payday loans, installment loans, merchant cash advances, and earned wage access products, each validated through interviews with chief risk officers, sponsor bank compliance leads, payroll API product managers, and earned wage access platform executives. Primary fieldwork combined with secondary validation from Consumer Financial Protection Bureau enforcement actions, Financial Conduct Authority cost-cap filings, Reserve Bank of India digital lending notifications, and SEC 10-K disclosures from listed fintech platforms. Bottom-up transaction volume estimates triangulated against top-down addressable market sizing.
Assumptions held fixed include prevailing regulatory frameworks across United States state-level usury regimes, United Kingdom cost-cap parameters, and Australian responsible lending obligations; variables included gig economy participation rates, real-time payment infrastructure adoption, and open banking penetration. Segmentation dimensions modeled encompass service type, customer archetype, interest presentation model, and loan purpose across the projection horizon. CAGRs derived from historical growth pattern analysis applied to demographic and technology adoption curves. Forecast inputs incorporated automated repayment failure rate assumptions and payroll data API integration cost trajectories.
Sensitivities concentrate around Truth in Lending Act enforcement intensity, sponsor bank regulatory action, and real-time payments infrastructure adoption velocity. Forecasts reflect documented assumptions regarding gig economy workforce expansion and open banking regulatory enablement. Macroeconomic contraction elevating borrower default rates, state-level usury cap reduction, or FedNow network disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Refinancing Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Student Loan Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
North America Syndicated Loans Market