
 Syndicated Loans Market | 2026-2036
Syndicated Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Syndicated Loans Market Outlook
Market Context
ISO 9001 certification for loan servicing quality is collapsing as a meaningful differentiator among top arrangers. JPMorgan Chase & Co leverages its balance sheet depth to anchor marquee leveraged buyout mandates across North America. BNP Paribas SA competes through specialized energy transition financing desks in London and Paris. Deutsche Bank AG navigates regulatory capital constraints by concentrating on investment-grade corporate syndications.
Technical Definition and Segment Structure
A syndicated loan is a debt facility extended by a group of lenders—typically banks and institutional investors—structured under a single credit agreement with standardized covenants, pricing grids tied to credit ratings or benchmark rates, and an agent bank administering disbursements and compliance monitoring. Its primary commercial purpose is to aggregate sufficient capital for large-scale corporate borrowing while distributing credit exposure across multiple institutions. Term loan tranches dominate volume in acquisition financing for private equity sponsors, while revolving credit facilities generate recurring fee income for agent banks through undrawn commitment pricing. Infrastructure sector syndications are expanding fastest as governments prioritize energy transition and digital backbone projects.
Regulatory Framework and Outlook
Basel III endgame rules from the Basel Committee on Banking Supervision, SEC disclosure requirements for material loan participations, and EU CRD VI capital buffers collectively constrain bank risk-weighted asset deployment and reshape syndicate composition toward non-bank lenders. The European Banking Authority's leveraged lending guidelines further tighten underwriting discipline for cross-border deals. Stakeholders must monitor how central bank liquidity facilities and evolving prudential standards alter the economics of hold-versus-distribute strategies for underwriters.
Market Dynamics
Basel III endgame capital rules are compressing bank risk-weighted asset capacity, forcing underwriters toward distribute-first strategies and expanding non-bank institutional participation in primary syndicates.
Growth Catalysts
- Energy Transition Project Finance:Renewable energy installations in offshore wind and utility-scale solar are absorbing record syndicated credit volumes as sponsors seek long-tenor construction-to-term facilities.
- SEC Material Participation Disclosure:Enhanced transparency requirements for loan participations are deepening institutional investor confidence in secondary market liquidity.
- Corporate Refinancing Waves:Maturity walls from pandemic-era leveraged loans are generating sustained arranger fee pools as sponsors roll facilities into extended structures.
Market Restraints
- Basel III Risk-Weight Compression:Higher capital charges for unrated leveraged exposures are constraining European bank appetite for speculative-grade underwritings.
- Agent Bank Concentration:Top-tier arrangers control marquee mandate access, limiting mid-tier lenders to sub-participation economics in competitive auctions.
- Documentation Standardization:LMA and LSTA template rigidity slows covenant customization for complex infrastructure or transition finance structures.
Strategic Opportunities
- Private Credit Convergence:Direct lending funds are acquiring primary syndication skills, creating hybrid structures that blend bank distribution with hold-to-maturity capital.
- Transition Finance Taxonomies:EU Green Deal-aligned loan certification is opening dedicated investor pools for sustainability-linked pricing mechanisms.
- APAC Infrastructure Gaps:Southeast Asian digital backbone and power transmission projects are underserved by local bank capacity, inviting cross-border syndicate formation.
Industry Challenges
- Covenant-Lite Documentation:Erosion of financial maintenance terms complicates early warning detection and workout coordination across fragmented lender groups.
- ESG Data Verification:Sustainability-linked margin ratchets require third-party certification timelines that delay financial close on tight sponsor deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syndicated Loans Market |
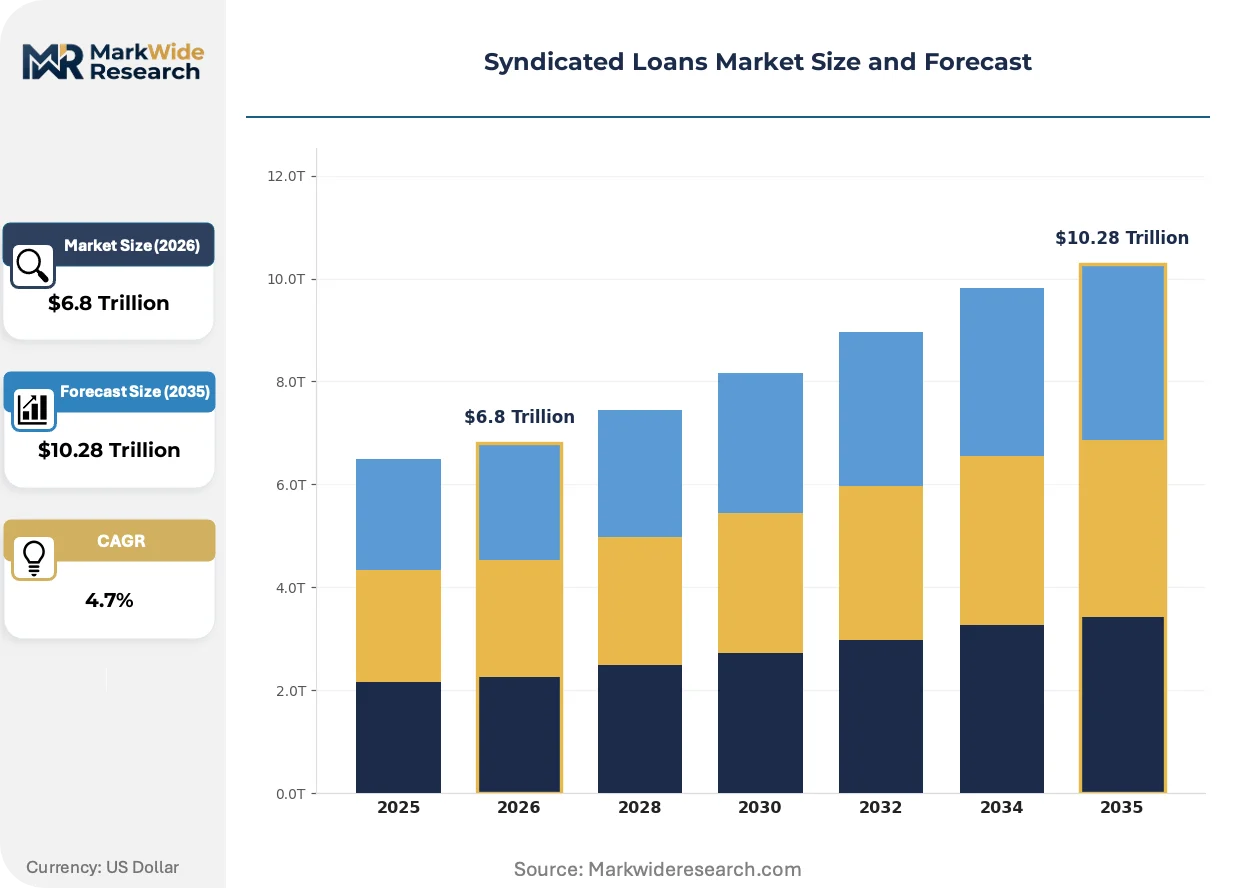
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $10.28 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Term Loan, Revolving Credit, Bridge Loan, Acquisition Financing Participant Role: Lender, Borrower, Agent Bank, Underwriter Industry Sector: Energy, Telecommunications, Real Estate, Infrastructure Transaction Structure: Sole Mandate, Club Deal, Syndication, Underwritten |
| Companies Covered | Banco Santander S.A, Mitsubishi UFJ Financial Group Inc., JPMorgan Chase & Co, ING Group N.V., Deutsche Bank AG, Bank of China, Barclays PLC, Sumitomo Mitsui Banking Corporation, BNP Paribas SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syndicated Loans Market Strategic Shifts
Digital workflow automation and regulatory taxonomy alignment are restructuring how syndicates form, price, and distribute risk across institutional channels.
Artificial intelligence-driven credit decisioning is bifurcating the arranger landscape. Large underwriters deploy machine-learning models for covenant surveillance and early default prediction. Mid-tier banks lack data science infrastructure to match these capabilities. The technology is compressing due-diligence timelines for investment-grade corporates while widening competitive gaps in leveraged finance.
EU CRD VI capital buffer implementation is tightening underwriting discipline for cross-border leveraged transactions. The framework mandates higher provisioning for originated exposures held beyond distribution windows. European arrangers are responding by shortening primary market periods and pre-placing institutional commitments before launch.
Sponsor procurement of financing packages is compressing arranger selection cycles. Private equity firms now run parallel processes across multiple underwriters, extracting fee compression and flex terms through competitive tension. This behavior is most visible in North American buyout mandates where sponsor consolidation has concentrated bargaining power among top ten financial sponsors.
Syndicated Loans Market Segmentation
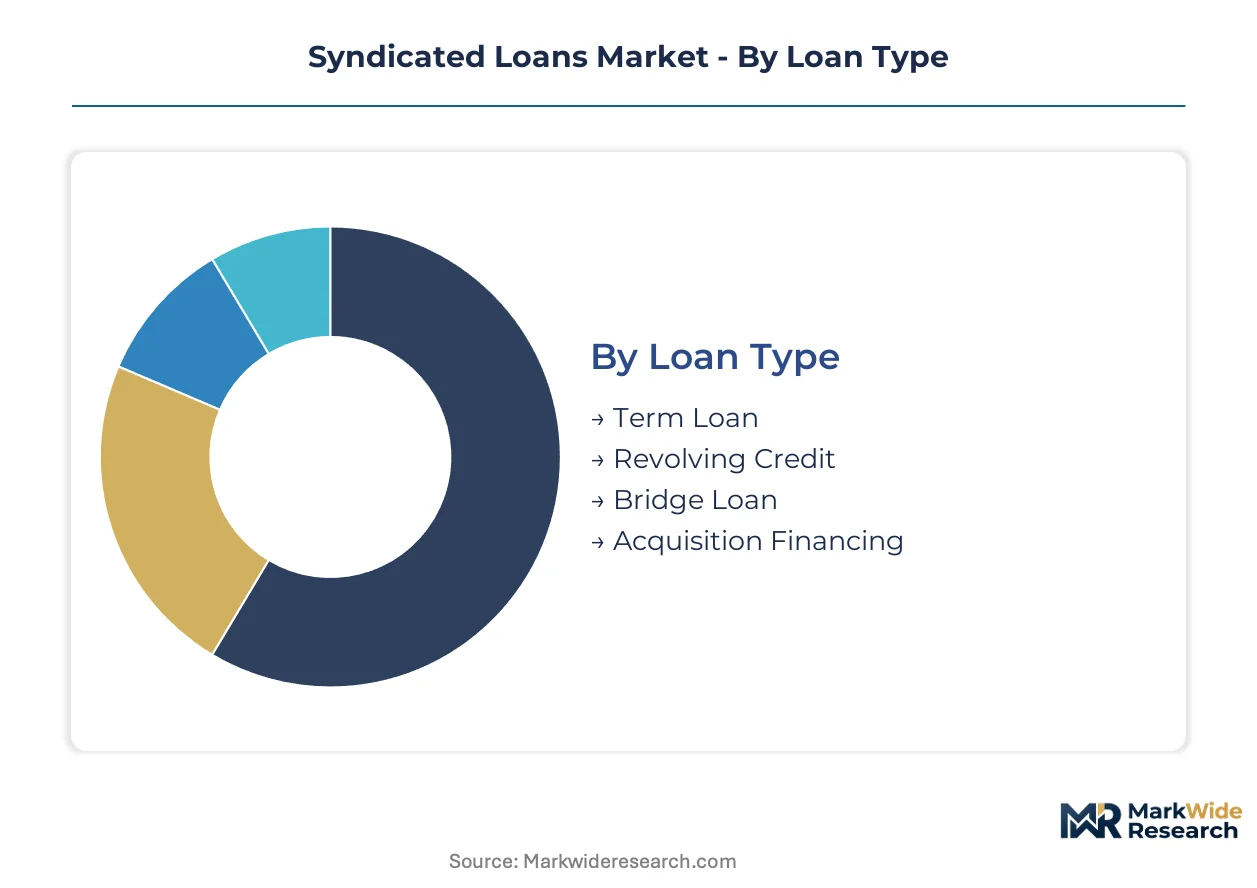
Syndicated loan structures fragment across multiple operational dimensions, each governing how capital aggregates, risk distributes, and fees accrue to arrangers. Understanding these segment boundaries clarifies where bank balance sheet constraints bite hardest and where non-bank capital can penetrate.
Loan Type:
Term loans flow through agent bank distribution networks to institutional investors, while revolving facilities concentrate on bank balance sheets due to undrawn commitment capital requirements. Bridge and acquisition structures demand hybrid channels blending underwriter risk absorption with pre-placed institutional commitments.
- Term Loan:Fixed-amortization or bullet-maturity tranches with pricing grids tied to credit ratings or leverage ratios. Sponsors in North American leveraged buyouts concentrate demand here as they seek covenant-lite structures for portfolio companies.
- Revolving Credit:Committed liquidity backstops generating recurring facility fees on undrawn amounts. Corporate treasurers in the United States prioritize these for working capital flexibility, though Basel III capital charges constrain bank appetite for unfunded commitments.
- Bridge Loan:Short-tenor interim financing pending permanent capital markets takeout. Investment-grade acquisition strategies in Europe absorb these structures where high-yield market windows dictate timing.
- Acquisition Financing:Purpose-built facilities backing M&A transactions with equity contribution requirements and MAC clauses. Sponsor procurement processes in competitive auctions drive fee compression here.
By volume, term loans lead. By growth pace, acquisition financing is climbing the fastest.
Participant Role:
Fee economics and risk exposure diverge sharply across participant roles, with underwriters capturing arrangement fees while lenders downstream earn spread income on funded exposure.
- Lender:Capital providers taking funded or unfunded exposures in primary syndication or secondary trading. Institutional investors including collateralized loan obligations and insurance companies in the United States dominate this tier.
- Borrower:Corporate, sovereign, or sponsor entities accessing aggregated credit capacity. Large-cap investment-grade corporates in Germany and France leverage this channel for multi-billion euro facilities.
- Agent Bank:Administrative agent administering disbursements, compliance monitoring, and inter-lender communications. JPMorgan Chase and BNP Paribas anchor this role in marquee mandates across their respective home markets.
- Underwriter:Arranger committing capital to distribute post-launch, absorbing market risk during syndication. European banks face EU CRD VI constraints that shorten their distribution windows.
Agent banks command premium economics. Underwriters face margin pressure from regulatory capital charges.
Industry Sector:
Sector concentration determines covenant architecture, with energy transition projects requiring completion guarantees and infrastructure mandates demanding availability-based repayment structures.
- Energy:Upstream reserve-based lending and offshore wind project finance with long-dated tenors. North Sea and Gulf of Mexico developments drive specialized syndicate formation around construction risk.
- Telecommunications:Spectrum acquisition and 5G rollout financing with regulatory milestone dependencies. Tower monetization strategies in India and Brazil absorb significant syndicated volume.
- Real Estate:Construction-to-permanent facilities backed by lease-up projections and sponsor guarantees. Commercial office exposure in central business districts faces repricing pressure.
- Infrastructure:Availability or demand-risk contracts with government counterparties. Southeast Asian power transmission and digital backbone projects attract cross-border syndicate participation.
Infrastructure commands the longest tenors. Energy transition sub-segments are expanding most quickly.
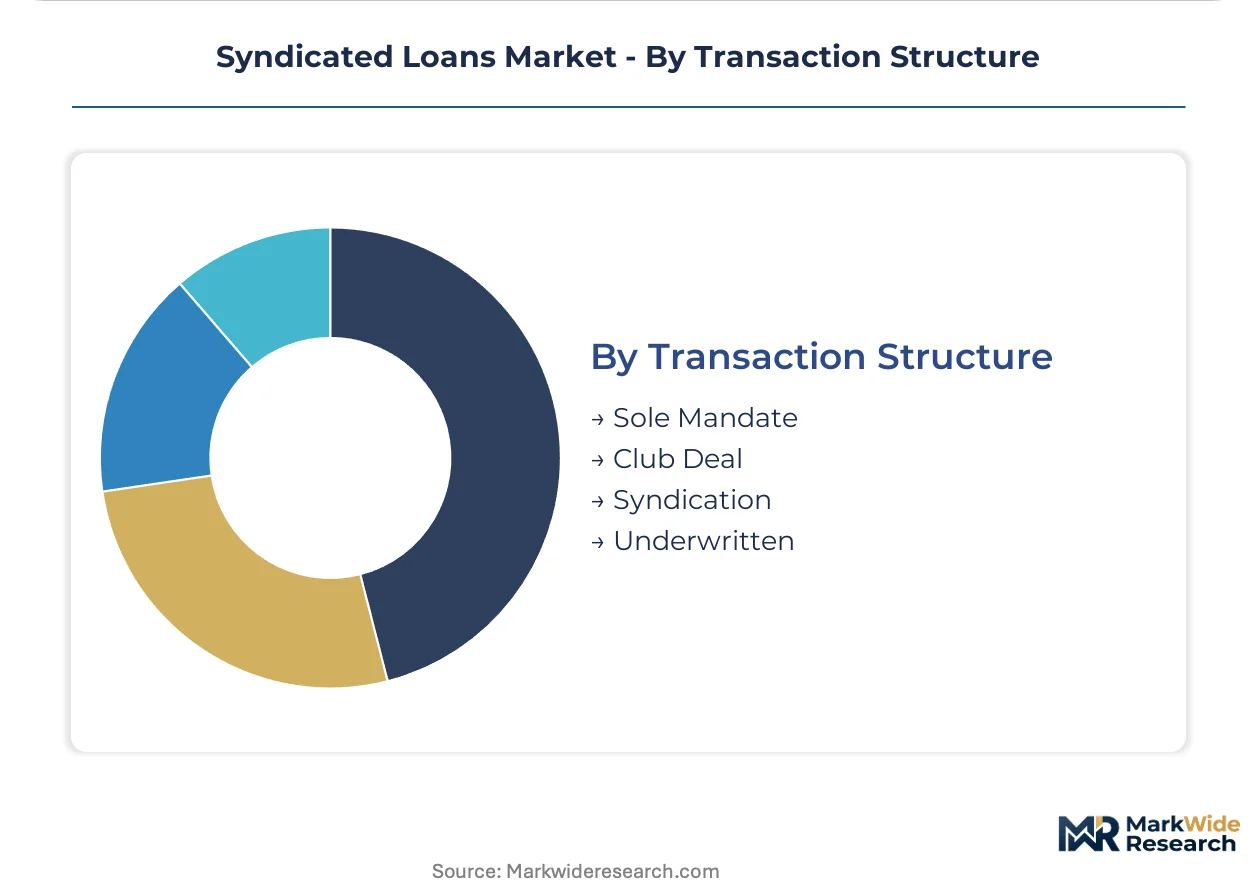
Transaction Structure:
Structural choice reflects borrower scale, relationship depth with lead arrangers, and urgency of funding timeline.
- Sole Mandate:Single underwriter bearing full distribution risk for relationship-intensive borrowers. German Mittelstand corporates favor this for confidentiality and speed.
- Club Deal:Pre-assembled lender group with limited or no general syndication. Mid-cap sponsors in the United Kingdom deploy this to avoid market disclosure.
- Syndication:Multi-stage process from underwritten launch to general syndication and final allocation. Standard for large-cap leveraged buyouts in North America.
- Underwritten:Firm commitment from arrangers regardless of subsequent placement success. Required for certain acquisition timelines where certainty of funds overrides pricing.
Syndication dominates headline volume. Club deals are gaining share fastest among privacy-sensitive borrowers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax credits and green energy incentives in the United States are accelerating renewable project finance mandates. Basel III implementation timelines diverge across jurisdictions, reshaping where banks can deploy underwriting capacity. Regulatory fragmentation is pushing sponsors toward jurisdictions with clearer capital treatment rules.
United States
Corporate refinancing waves from pandemic-era leveraged loans dominate arranger pipelines. SEC disclosure requirements for material loan participations deepen institutional investor confidence in secondary liquidity. New York-based financial sponsors concentrate buyout mandate procurement, extracting fee compression through competitive auction processes.
Germany
Mittelstand corporates favor sole-mandate structures for confidentiality and execution speed. EU CRD VI capital buffers constrain risk-weighted asset deployment for speculative-grade exposures. Frankfurt anchors investment-grade corporate syndication activity, with arrangers prioritizing relationship-intensive borrowers.
United Kingdom
Mid-cap sponsors deploy club deals to avoid market disclosure requirements. The European Banking Authority's leveraged lending guidelines tighten underwriting discipline for cross-border transactions. London-based energy transition financing desks specialize in offshore wind project syndications.
China
Infrastructure syndications for digital backbone and power transmission projects absorb significant domestic bank capacity. Dual carbon goals accelerate renewable energy installation financing through policy bank participation. Shanghai and Beijing clusters concentrate sovereign-backed project finance mandates.
Japan
Institutional investors including insurance companies and pension funds seek long-tenor project finance exposures. METI guidance on transition finance taxonomies aligns syndicated lending with national decarbonization targets. Tokyo-based megabanks anchor regional cross-border syndicate formation for Southeast Asian infrastructure gaps.
Syndicated Loans Market Competitive Environment
Player mix skews toward universal banks with balance sheet depth and specialized energy transition desks. The arranger landscape concentrates around institutions capable of absorbing distribution risk across multiple tranche structures. Three archetypes dominate: balance sheet-heavy North American money center banks, European universal banks with regulatory capital constraints, and Asia-Pacific policy-oriented lenders. Competitive positioning depends on shortening primary market periods and pre-placing institutional commitments before launch.
Within the balance sheet-driven tier, JPMorgan Chase & Co and BNP Paribas SA exemplify divergent strategies. JPMorgan Chase anchors marquee leveraged buyout mandates through depth of risk absorption capacity. BNP Paribas occupies a position concentrated on specialized energy transition financing desks in European financial centers. Deutsche Bank AG sits within the regulatory-constrained archetype, navigating capital adequacy requirements through investment-grade corporate syndication focus. Mitsubishi UFJ Financial Group Inc. represents the Asia-Pacific policy bank model, deploying long-tenor capital into regional infrastructure gaps.
| Leading Market Players |
|---|
| Banco Santander S.A |
| Mitsubishi UFJ Financial Group Inc. |
| JPMorgan Chase & Co |
| ING Group N.V. |
| Deutsche Bank AG |
| Bank of China |
| Barclays PLC |
| Sumitomo Mitsui Banking Corporation |
| BNP Paribas SA |
| Others |
Value Chain & Pricing Dynamics
Basel III capital adequacy requirements gate both arranger qualification and fee differentiation simultaneously. Banks with advanced internal ratings-based approaches command premium economics on leveraged mandates. Non-bank lenders without regulatory capital constraints undercut on spread but cannot match agent bank service depth.
Pricing Analysis
Certification level (agent bank ISO 9001 quality accreditation) creates the primary spread between top-tier and mid-market arrangers. Pricing stratifies across relationship-intensive sole mandates, competitive auction syndications, and club deal confidentiality premiums. Pricing pressure stems from sponsor procurement compression in North American buyout auctions. Mid-tier lenders exhibit highest price sensitivity as they compete for sub-participation economics.
Supply Chain Analysis
Just-in-time capital deployment dominates arranger behavior as Basel III endgame rules compress risk-weighted asset windows. Supply concentrates in the United States, United Kingdom, and Germany for marquee mandate origination. Raw material dependencies include institutional investor capital pools, CLO warehouse capacity, and insurance company balance sheet availability. Single-source vulnerability runs through top-tier agent bank concentration. Distribution runs through primary syndication to general syndication to secondary trading pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The syndicated loans market functions as a service-attach opportunity where agent bank administration fees and compliance monitoring revenue expand faster than arrangement fee pools.
For Market Incumbents: Compound defensive positioning by deepening balance sheet absorption capacity for underwritten risk and securing exclusive agent bank roles on renewable energy transition mandates. Private credit convergence threatens traditional syndication economics. Vertical integration into direct lending capabilities preserves margin. For New Entrants and Emerging Players: Lead with specialized energy transition financing expertise to penetrate the fastest-expanding infrastructure sub-segment. Southeast Asian digital backbone projects offer white-space access where local bank capacity falls short. Cross-border syndicate formation capabilities differentiate against established regional players. For Investors and Strategic Acquirers: EU CRD VI capital buffer implementation reshapes the acquisition landscape by forcing distressed divestitures of speculative-grade underwriting capabilities. Long-term viability centers on hybrid bank-direct lending platforms with taxonomy-aligned certification. Watch for central bank liquidity facility withdrawals as the inflection signal requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Agent Bank Role Consolidation | Captures recurring administration fees from multi-tranche mandates across JPMorgan and BNP Paribas relationships. |
| Energy Transition Desk Buildout | Opens dedicated investor pools for EU Green Deal-aligned project finance in offshore wind and utility-scale solar. |
| Direct Lending Capability Acquisition | Blends bank distribution infrastructure with private credit hold-to-maturity capital for sponsor flexibility. |
| Digital Workflow Automation | Compresses covenant surveillance timelines using machine-learning models for early default prediction. |
| APAC Cross-Border Syndicate Formation | Addresses infrastructure gaps in Southeast Asian power transmission through Tokyo-based megabank anchoring. |
Study Parameters
Cross-validation between arranger pipeline disclosures and institutional investor allocation data anchors the qualitative findings. Primary interviews with loan syndication heads, CLO portfolio managers, sponsor procurement officers, and regulatory capital directors combined with secondary validation from SEC material participation filings, LMA template documentation, Basel Committee regulatory texts, and syndicated loan league table data. Bottom-up tranche volume aggregation and top-down macro credit flow analysis triangulate market sizing.
Sensitivity analysis across regulatory implementation timelines tests forecast robustness. The analytical framework segments by loan type, participant role, industry sector, and transaction structure across the projection horizon. CAGRs derive from arranger fee pool trajectories and institutional capital deployment velocity. Renewable energy installation pipelines and corporate refinancing maturity walls serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Basel III endgame rules and EU CRD VI capital buffers; material policy shifts would require re-modeling. Specific risk factors include central bank liquidity facility withdrawals and sovereign credit rating migrations affecting risk-weighted asset calculations. Revision becomes warranted when sponsor leverage multiples or covenant-lite documentation prevalence cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
USA Home Loan Market