
 Online Payday Loans Market | 2026-2036
Online Payday Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Online Payday Loans Market Insights
Alternative credit scoring data is broadening the addressable borrower pool beyond traditional FICO thresholds. Earnin leverages real-time payroll connectivity to sustain zero-fee advance models against conventional interest structures. MoneyLion anchors its growth on integrated banking-plus-credit subscriptions that reduce customer acquisition costs. Dave competes through predictive overdraft alerts that convert users into short-term credit customers.
Online payday loans are short-term, high-cost credit instruments originated through digital platforms, typically featuring automated repayment schedules tied to borrower pay cycles with annual percentage rates often exceeding storefront lending equivalents. Their primary commercial purpose is providing liquidity bridge financing to consumers facing immediate cash shortfalls between income periods. Installment loan structures now lead product mix evolution as borrowers seek amortized repayment over single-payment balloons, while mobile applications represent the fastest-growing distribution channel due to biometric authentication and instant funding rails. Gig economy workers and freelancers constitute the most rapidly expanding customer type as irregular income patterns align with flexible draw schedules.
The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures and ability-to-repay assessments that shape product design and marketing practices across US-origin platforms. The UK's Financial Conduct Authority imposes rate caps and continuous payment authority restrictions that limit rollover sequences and mandate forbearance protocols. State-level usury ceilings and licensing requirements fragment operational compliance for interstate lenders. Stakeholders must monitor regulatory arbitrage between federal preemption doctrines and emerging state digital lending statutes to calibrate geographic expansion and product pricing architectures.
Market Dynamics
Platform-based employment is fragmenting income predictability across developed economies, forcing lenders to reconstruct underwriting models around real-time cash flow verification rather than static employment records. This structural shift is compressing traditional credit assessment timelines while expanding the addressable borrower base.
Growth Catalysts
- Real-time payroll APIs:Open banking infrastructure enables instantaneous income verification, reducing default risk and origination friction for gig economy borrowers.
- Financial Conduct Authority forbearance protocols:Mandatory repayment assistance requirements in the United Kingdom legitimize short-term credit as a regulated financial service.
- Biometric authentication rails:Mobile-native identity verification accelerates funding velocity and reduces synthetic fraud exposure.
Market Restraints
- State-level usury fragmentation:Interstate lenders face compliance multiplication as California, New York, and Illinois impose divergent rate ceilings and licensing requirements.
- Continuous payment authority restrictions:UK regulations limit automated debit sequences, constraining rollover revenue models.
- Banking-as-a-service concentration:Reliance on a narrow tier of sponsor banks creates operational vulnerability if de-risking pressures intensify.
Strategic Opportunities
- Earned wage access convergence:Integration of payroll advance functionality with employer HR platforms creates embedded distribution channels.
- Alternative data underwriting:Utility payment histories and rental records enable credit extension to thin-file borrowers excluded from FICO-centric models.
- Installment product migration:Amortized repayment structures attract borrowers seeking predictable obligations versus single-payment balloon pressure.
Industry Challenges
- Machine learning model governance:Fair lending scrutiny demands explainable algorithms for adverse action notices, complicating black-box credit scoring deployment.
- Legacy core system integration:Real-time funding requirements strain batch-oriented bank infrastructure, necessitating expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Payday Loans Market |
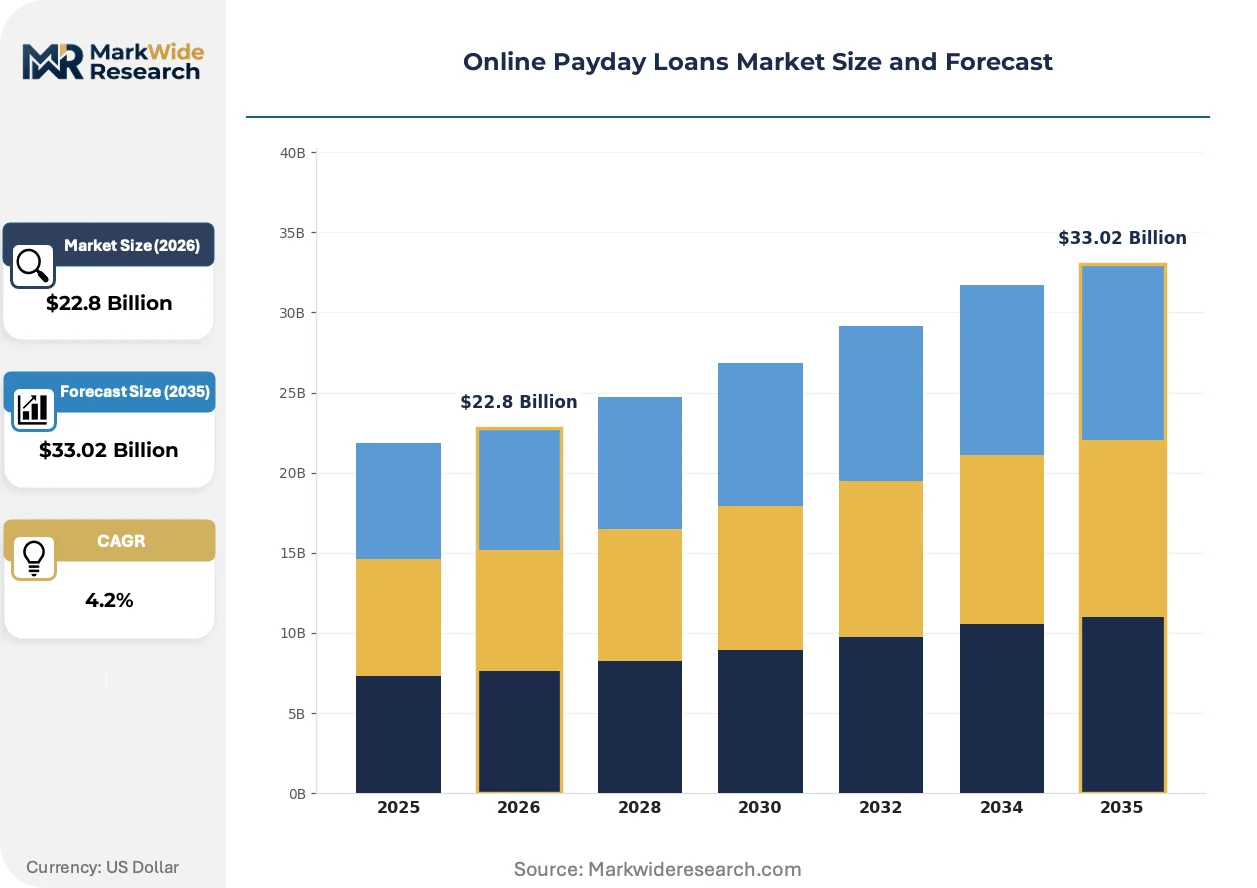
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $33.02 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Single Payment, Installment, Line of Credit, Title Loan, Cash Advance Purpose: Emergency Expenses, Medical Bills, Utility Payments, Rent Cover, Vehicle Repair Distribution Channel: Direct Lender Websites, Mobile Applications, Affiliate Platforms, Financial Aggregators, Social Media Customer Type: Self-Employed, Salaried Individuals, Students, Gig Economy Workers, Freelancers |
| Companies Covered | Wonga, Moneytree, Earnin, NetCredit, Klarna, MoneyLion, Dave, Check `n Go, ACE Cash Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Payday Loans Market Trends and Innovations
Digital lending infrastructure is bifurcating between vertically integrated balance-sheet lenders and API-first origination platforms, with capital-light models gaining traction among fintech entrants seeking regulatory arbitrage avoidance.
Embedded finance orchestration layers are modularizing the technology stack, separating underwriting engines from funding sources and servicing operations. Regional banks and credit unions adopt white-label origination modules to compete without proprietary development. This architecture is modularizing competitive moats, enabling smaller depositories to match national platforms on speed and user experience.
The Consumer Financial Protection Bureau's evolving ability-to-repay assessments tighten documentation requirements for covered loans, elevating compliance technology spend. Marketing disclosure protocols now mandate specific formatting for annual percentage rate presentations. US-origin platforms are responding by bifurcating product offerings between covered and exempt structures.
Gig workers increasingly demand draw schedules synchronized to platform payment cycles rather than traditional biweekly intervals. Earned wage access providers displace conventional payday structures by integrating directly with rideshare and delivery platforms. This behavioral pivot concentrates in North American and Western European metropolitan corridors where platform employment density is highest.
Online Payday Loans Market Segmentation
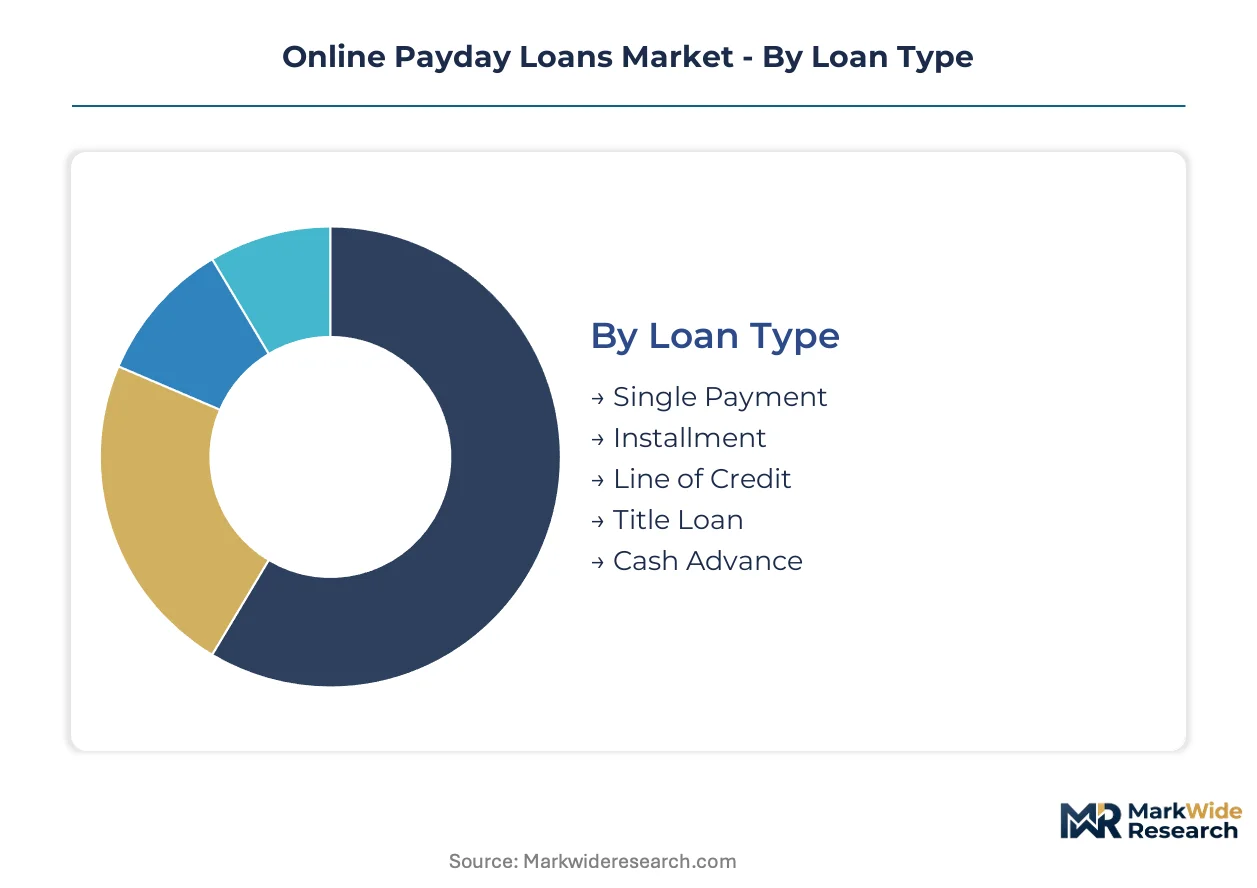
Segmentation in online payday lending reveals how product architecture, borrower circumstances, and channel economics intersect to determine risk pricing and origination costs. Each dimension carries distinct regulatory implications and technology requirements that shape competitive strategy.
Loan Type:
Single-payment balloons dominate transaction volume while installment structures command premium pricing through extended duration and lower default correlation.
- Single Payment:Lump-sum repayment structures tied to borrower pay cycles feature the highest APRs and shortest durations. Demand concentrates among subprime borrowers in Texas and Florida where state regulations permit fee structures that amortized products cannot replicate.
- Installment:Amortized repayment schedules spread obligations across multiple periods with embedded interest capitalization. California and Illinois borrowers increasingly select this format after state rate caps rendered single-payment economics unviable for lenders.
- Line of Credit:Revolving draw facilities with minimum payment requirements function as hybrid products bridging payday and credit card functionality.
- Title Loan:Vehicle-secured instruments with lien perfection requirements face geographic restriction to states permitting non-possessory collateral structures.
- Cash Advance:Employer-integrated or direct-deposit-linked advances with flat-fee pricing compete through regulatory exemption rather than interest rate competition.
Today's leader: Single Payment. Tomorrow's challenger: Installment.
Purpose:
Emergency liquidity needs drive origination velocity while recurring obligations like rent generate higher customer lifetime value through repeat borrowing patterns.
- Emergency Expenses:Unplanned financial shocks including family crises and sudden travel requirements generate the highest urgency-driven conversion rates. Gig economy workers in metropolitan corridors utilize these products most intensively due to income timing mismatches.
- Medical Bills:Healthcare cost exposure before insurance reimbursement or for uninsured populations creates demand for intermediate-duration credit. This segment faces increasing displacement from hospital-sponsored payment plans and HSA-linked advance products.
- Utility Payments:Disconnection avoidance motivates rapid funding acceptance with minimal rate shopping.
- Rent Cover:Housing stability threats produce the largest average ticket sizes and strongest repeat-borrowing propensity.
- Vehicle Repair:Transportation-dependent employment makes this purpose non-discretionary for commuters without transit alternatives.
Rent Cover generates the steepest expansion trajectory as housing cost burdens outpace wage growth in coastal metropolitan markets.
Distribution Channel:
Direct origination captures margin while affiliate and aggregator channels absorb customer acquisition costs through revenue-sharing arrangements.
- Direct Lender Websites:Proprietary traffic and organic search positioning enable rate optimization without intermediary commissions. Established platforms in the United Kingdom leverage Wonga's brand recognition residue to sustain direct channel economics.
- Mobile Applications:Native iOS and Android experiences with biometric onboarding and push notification engagement represent the fastest-climbing channel. Real-time funding rails and payroll API integration concentrate development investment here.
- Affiliate Platforms:Publisher-driven lead generation operates on cost-per-acquisition or revenue-share models with quality variance challenges.
- Financial Aggregators:Comparison shopping sites commoditize product differentiation and compress margins through rate transparency.
- Social Media:Meta and TikTok advertising faces increasing platform policy restrictions and regulatory scrutiny on targeting parameters.
Mobile Applications now anchor competitive positioning as funding velocity becomes the primary conversion driver.
Customer Type:
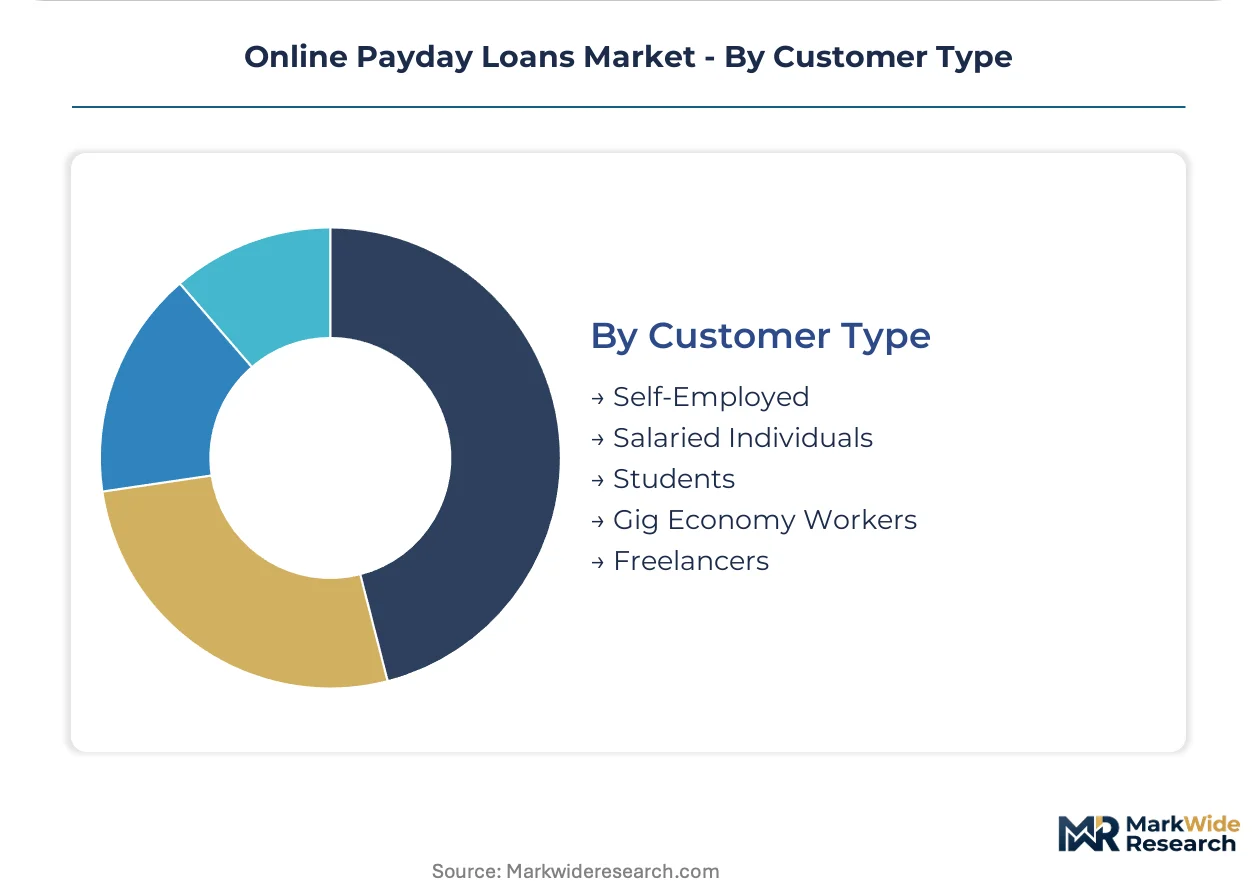
Salaried individuals offer income predictability for underwriting models while self-employed and gig workers require alternative data infrastructure and command risk-adjusted pricing premiums.
- Gig Economy Workers:Platform-based income from rideshare, delivery, and freelance marketplaces demands real-time cash flow verification replacing traditional employment records. Earned wage access providers target this segment with employer-integrated alternatives to conventional payday structures.
- Freelancers:Project-based revenue cycles with invoice payment lags create natural demand for receivables financing disguised as consumer credit.
- Self-Employed:Small business proprietors with irregular revenue streams face documentation challenges that increase origination friction.
- Salaried Individuals:W-2 employment verification enables the lowest-cost underwriting and broadest credit access.
- Students:Thin-file borrowers with limited credit history require educational expense-specific product structures and cosigner alternatives.
Gig Economy Workers are gaining share fastest as platform employment reshapes labor market composition across developed economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley fintech clusters anchor product innovation velocity for earned wage access and real-time payroll integration, while regulatory divergence between Westminster and Washington shapes operational compliance architectures.
United States
Gig economy density in Texas and Florida sustains single-payment balloon demand despite state-level rate cap fragmentation. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures and ability-to-repay assessments that compress origination timelines. California's Silicon Valley corridor concentrates venture-backed earned wage access development, with real-time payroll API integration emerging as the dominant technical standard.
United Kingdom
Wonga's legacy customer base continues migrating toward FCA-regulated fintech alternatives with mandatory forbearance protocols. The Financial Conduct Authority imposes rate caps and continuous payment authority restrictions that limit rollover revenue models. London's fintech cluster dominates European digital lending volume, with embedded finance partnerships displacing direct-to-consumer origination channels.
Germany
Thin-file borrower expansion drives alternative credit scoring adoption among platform-employed workers in Berlin and Hamburg. BaFin's consumer credit supervision requires standardized pre-contractual information disclosures. Munich's banking-as-a-service infrastructure providers enable white-label origination modules for regional depositories seeking digital lending capabilities.
Australia
ASIC's responsible lending obligations reshape product design toward amortized installment structures. Sydney and Melbourne concentrate neobank partnerships with earned wage access providers targeting healthcare and logistics platform workers. Real-time payment rail integration accelerates funding velocity for mobile-native applications.
Canada
Provincial rate cap variance between Ontario, British Columbia, and Alberta fragments operational compliance for interstate lenders. Toronto's fintech corridor develops employer-integrated payroll advance alternatives to conventional payday structures. FCAC disclosure requirements elevate compliance technology spend for US-origin platforms expanding northward.
Online Payday Loans Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities, with balance-sheet lenders and API-first origination platforms occupying distinct strategic tiers. Market structure fragments between vertically integrated incumbents and capital-light fintech entrants seeking regulatory arbitrage avoidance. Three archetypes dominate: earned wage access specialists, integrated banking-plus-credit subscription providers, and traditional payday lenders with digital migration investments. Competitive moves concentrate on embedded finance partnerships and real-time payroll API integration.
Within the earned wage access tier, Earnin and MoneyLion exemplify divergent monetization approaches—zero-fee advance models against integrated subscription architectures. Dave occupies a position bridging predictive overdraft alerts with short-term credit conversion. Wonga's regulatory history in the United Kingdom represents legacy direct-lender positioning now displaced by FCA-compliant alternatives. These three companies anchor distinct competitive vectors: payroll connectivity depth, banking ecosystem integration, and mobile-native user experience optimization.
| Leading Market Players |
|---|
| Wonga |
| Moneytree |
| Earnin |
| NetCredit |
| Klarna |
| MoneyLion |
| Dave |
| Check `n Go |
| ACE Cash Express |
| Others |
Pricing and Supply Chain Analysis
Gig economy workers concentrated in Texas and Florida metropolitan corridors drive demand for single-payment balloon structures with fee-based pricing models that amortized products cannot replicate under divergent state rate caps. This borrower concentration forces lenders to calibrate pricing architectures around geographic regulatory fragmentation rather than uniform national rate cards.
Pricing Analysis
Input-cost pass-through from banking-as-a-service sponsor bank fees and real-time payment rail charges shapes the dominant subscription-plus-transaction hybrid pricing model. Price differentiation hinges on employer-integrated payroll connectivity depth and biometric authentication speed tiers. Cost compression in the single-payment segment intensifies as California and Illinois rate caps render legacy fee structures unviable. Subprime borrowers in unregulated states exhibit the highest price inelasticity, while gig workers with earned wage access alternatives demonstrate acute sensitivity to flat-fee comparisons.
Supply Chain Analysis
Workforce availability constraints in Mumbai and Bangalore concentrate technology development for mobile-native origination platforms and alternative credit scoring engines. The supply chain draws from cloud infrastructure providers in the United States, biometric authentication vendors in Israel, and payroll API aggregators in the United Kingdom. Single-source vulnerability concentrates in the narrow tier of sponsor banks providing regulatory compliance coverage. Distribution runs through employer-embedded channels and direct-to-consumer mobile applications with revenue-share arrangements for affiliate lead generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in online payday lending rests on automation-driven origination cost reduction and the shift toward installment products that command extended-duration pricing premiums.
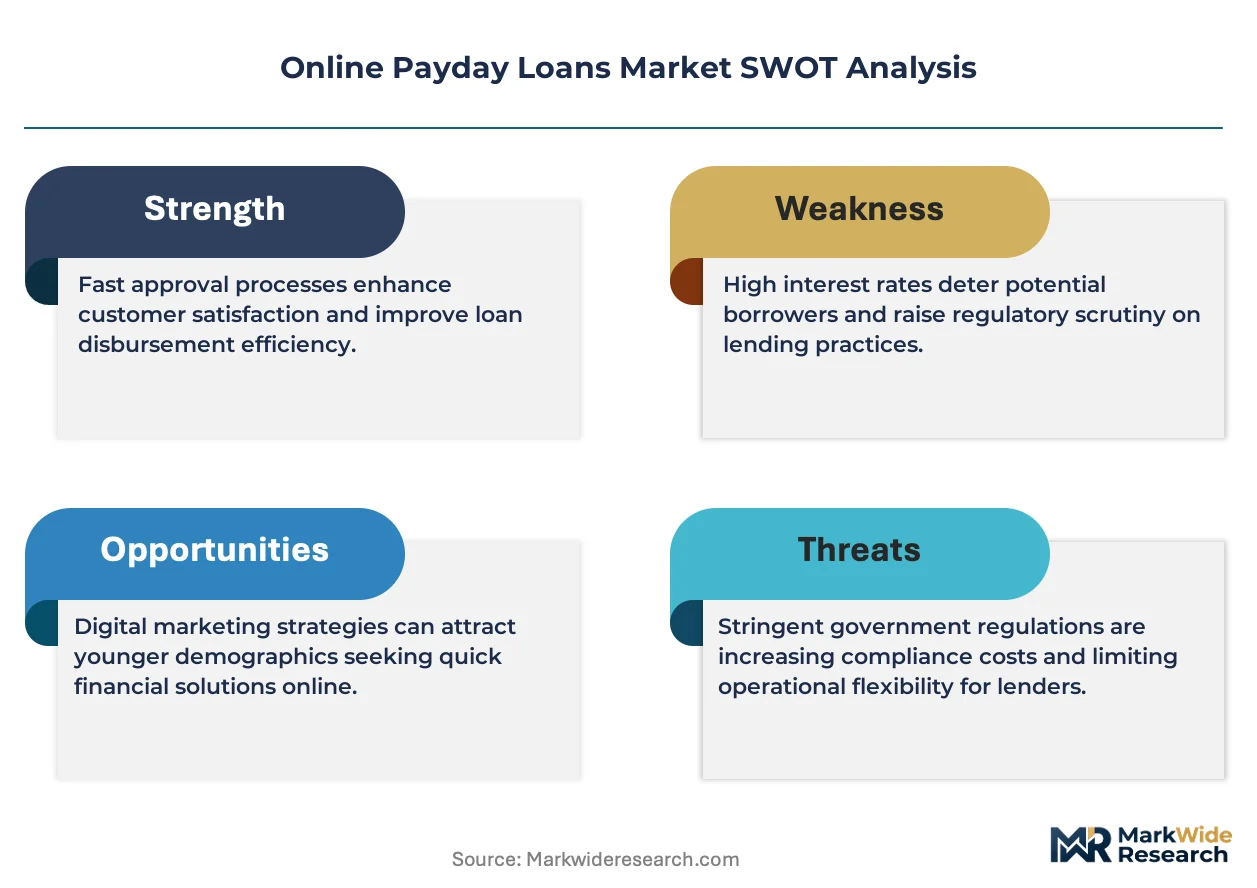
For Market Incumbents: Extend balance-sheet capacity into earned wage access partnerships before employer-integrated platforms displace conventional payday structures entirely. Acquire real-time payroll API capabilities to defend against fintech entrants with superior cash flow verification infrastructure. Deepen vertical integration into banking-as-a-service relationships to reduce sponsor bank concentration risk. For New Entrants and Emerging Players: The Consumer Financial Protection Bureau's evolving ability-to-repay assessments in the United States opens a window for compliance-technology specialists to capture share from legacy lenders with deficient documentation systems. Target thin-file gig economy borrowers in Texas and Florida where alternative data underwriting gaps persist. Pursue white-label origination modules for regional credit unions seeking digital lending capabilities without proprietary development. For Investors and Strategic Acquirers: Earned wage access specialists are the most active acquirer in this space, consolidating payroll connectivity assets ahead of embedded finance maturation. Long-term viability favors platforms with employer channel control and amortized product mix. Watch for inflection signals in state-level rate cap harmonization efforts that would compress arbitrage-dependent single-payment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Real-time Payroll API Integration | Earnin and MoneyLion compete through employer connectivity depth that reduces default risk. |
| Alternative Credit Scoring Deployment | Utility payment histories and rental records expand thin-file borrower access beyond FICO thresholds. |
| Installment Product Migration | Amortized repayment structures attract California and Illinois borrowers after state rate caps. |
| Biometric Authentication Investment | Mobile-native identity verification accelerates funding velocity and reduces synthetic fraud exposure. |
| Embedded Finance Partnership | Regional banks adopt white-label origination modules to match national platforms on user experience. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research draws from interviews with digital lending platform executives, regulatory compliance officers at sponsor banks, payroll API providers, and consumer finance attorneys. Secondary sources include Consumer Financial Protection Bureau enforcement actions, Financial Conduct Authority consultation papers, SEC filings for publicly traded fintech platforms, and open banking infrastructure documentation. Bottom-up origination volume estimates triangulate against top-down addressable market sizing.
Rate-of-change decomposition separates volume growth from pricing mix effects across the projection horizon. The analytical framework models segmentation by loan type, distribution channel, customer employment category, and geographic regulatory cluster. CAGRs derive from trend extrapolation of gig economy labor force participation, real-time payment rail adoption curves, and state-level legislative tracking databases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt state rate cap harmonization or sponsor bank de-risking cascades. Forecasts reflect assumptions about regulatory enforcement intensity and platform employment growth trajectories. Material deviation in Consumer Financial Protection Bureau rulemaking timelines or major sponsor bank withdrawal warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Brazil Car Loan Market