
 Working Capital Loan Market | 2026-2036
Working Capital Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Working Capital Loan Market Insights
The capital-intensity divergence between legacy banks and digital-native lenders is unwinding traditional underwriting economics. OnDeck leverages algorithmic risk scoring to serve borrowers outside conventional credit box parameters. Bank of America sustains its position through branch-integrated treasury management that bundles working capital with commercial deposits. Wells Fargo anchors its strategy in sector-specialized relationship banking for manufacturing and agricultural borrowers.
A working capital loan is a short-term debt instrument designed to finance operational expenditures—inventory purchases, payroll obligations, and accounts payable gaps—rather than fixed asset acquisition. These facilities typically carry maturities under twelve months, with interest calculated on drawn balances rather than full commitment amounts. Line of credit structures dominate the Loan Type dimension by volume, while invoice financing commands premium pricing due to its collateral-backed risk profile. The Borrower Profile segment shows Small Business and Medium Enterprise categories expanding fastest, as automated application programming interfaces reduce origination costs for sub-$250K exposures.
The Office of the Comptroller of the Currency supervises national bank lending standards, while the Consumer Financial Protection Bureau monitors fair lending disclosures in small-business credit products. State-level usury statutes create a patchwork compliance environment that shapes product design across interstate lenders. Stakeholders must monitor how open banking data-sharing frameworks and real-time payment infrastructure alter collateral verification and disbursement velocity.
Market Dynamics
Automated underwriting engines are compressing approval timelines from weeks to hours, fundamentally restructuring how lenders compete for commercial borrowers across the United States.
Growth Catalysts
- Real-time payment infrastructure:The FedNow Service enables instant disbursement and repayment cycles, reducing friction for inventory-heavy borrowers managing seasonal cash flow gaps.
- Small Business Administration 7(a) program:Federal loan guarantees expand credit access for sub-$5 million exposures, encouraging regional banks to extend working capital facilities to thinner-file applicants.
- Open banking frameworks:Plaid and Yodlee-powered data aggregation allows lenders to verify cash flow directly from business checking accounts, bypassing traditional tax return documentation.
Market Restraints
- State-level usury ceilings:Interest rate caps in Arkansas, Iowa, and other jurisdictions prevent national lenders from pricing risk-appropriately for subprime commercial borrowers.
- Deposit concentration at money-center banks:JPMorgan Chase and Bank of America capture disproportionate low-cost funding, squeezing net interest margins for regional competitors.
- Manual collateral verification:Accounts receivable auditing remains labor-intensive for invoice financing products, limiting scalability below $500 thousand ticket sizes.
Strategic Opportunities
- Embedded lending at point-of-sale:Shopify and Square integrate working capital offers directly into merchant dashboards, capturing borrowers at transaction origin.
- Supply chain finance digitization:Dynamic discounting platforms connect corporate buyers with their vendor bases, monetizing payables extension as a yield product.
- Community Development Financial Institution certification:CDFI designation unlocks below-market capital from the US Treasury, enabling mission-driven pricing in underserved metropolitan areas.
Industry Challenges
- Credit model explainability requirements:Fair lending examinations demand algorithmic decision documentation that many machine-learning underwriting stacks cannot produce.
- Core banking system integration:Legacy loan origination software at mid-tier banks resists API connectivity, delaying fintech partnership timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Working Capital Loan Market |
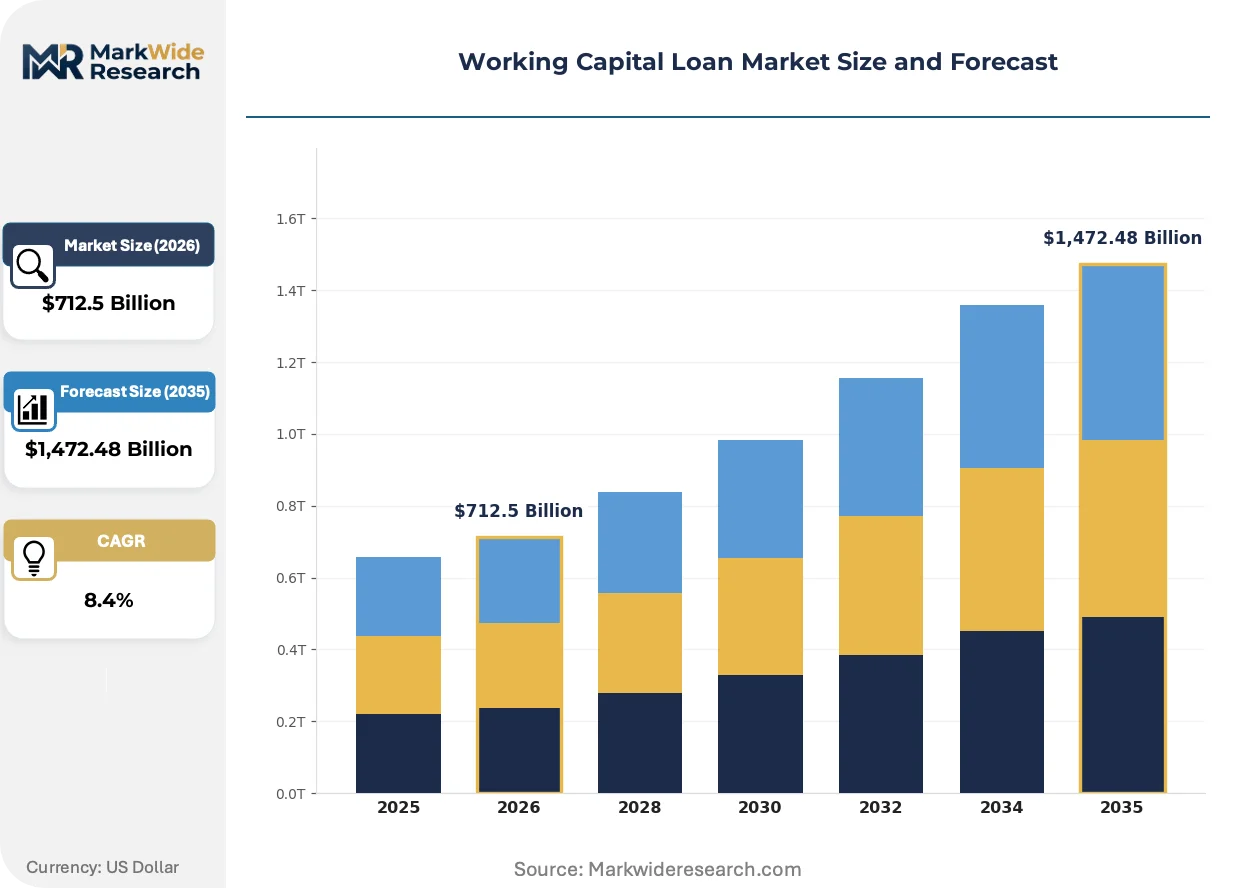
| Market Size in 2026 | $712.5 Billion |
| Market Size in 2035 | $1,472.48 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Short-Term Loan, Line of Credit, Invoice Financing, Equipment Financing Borrower Profile: Small Business, Medium Enterprise, Large Corporation, Start-Up Industry Vertical: Retail, Manufacturing, Service, Agriculture Loan Amount: Under $50K, $50K-$100K, $100K-$250K, Over $250K |
| Companies Covered | OnDeck, Bluevine, Bank of America, American Express, Fundbox, Chase, Fora Financial, Lendio, Wells Fargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Working Capital Loan Market Trends and Innovations
Digital-native lenders are forcing incumbent banks to rebuild their technology stacks around speed and user experience rather than relationship tenure.
Application programming interfaces for cash-flow underwriting are miniaturizing the data requirements for credit decisions. Sub-$250 thousand exposures now require only three months of bank transaction history rather than two years of financial statements. Manufacturing distributors and agricultural cooperatives are adopting these streamlined applications fastest.
The Consumer Financial Protection Bureau's small-business lending data collection rule under Section 1071 of the Dodd-Frank Act mandates demographic reporting for commercial credit applications. Lenders must rebuild origination workflows to capture race, ethnicity, and gender data without deterring completion. Community banks in the Southeast and Midwest are consolidating vendor relationships to meet compliance deadlines.
Buyer concentration among multi-location franchise operators is reshaping origination economics. National restaurant and auto service chains now centralize working capital procurement through preferred lender programs, displacing branch-relationship-driven decisions. This pattern concentrates volume with platforms offering standardized documentation and same-day funding guarantees.
Working Capital Loan Market Segmentation
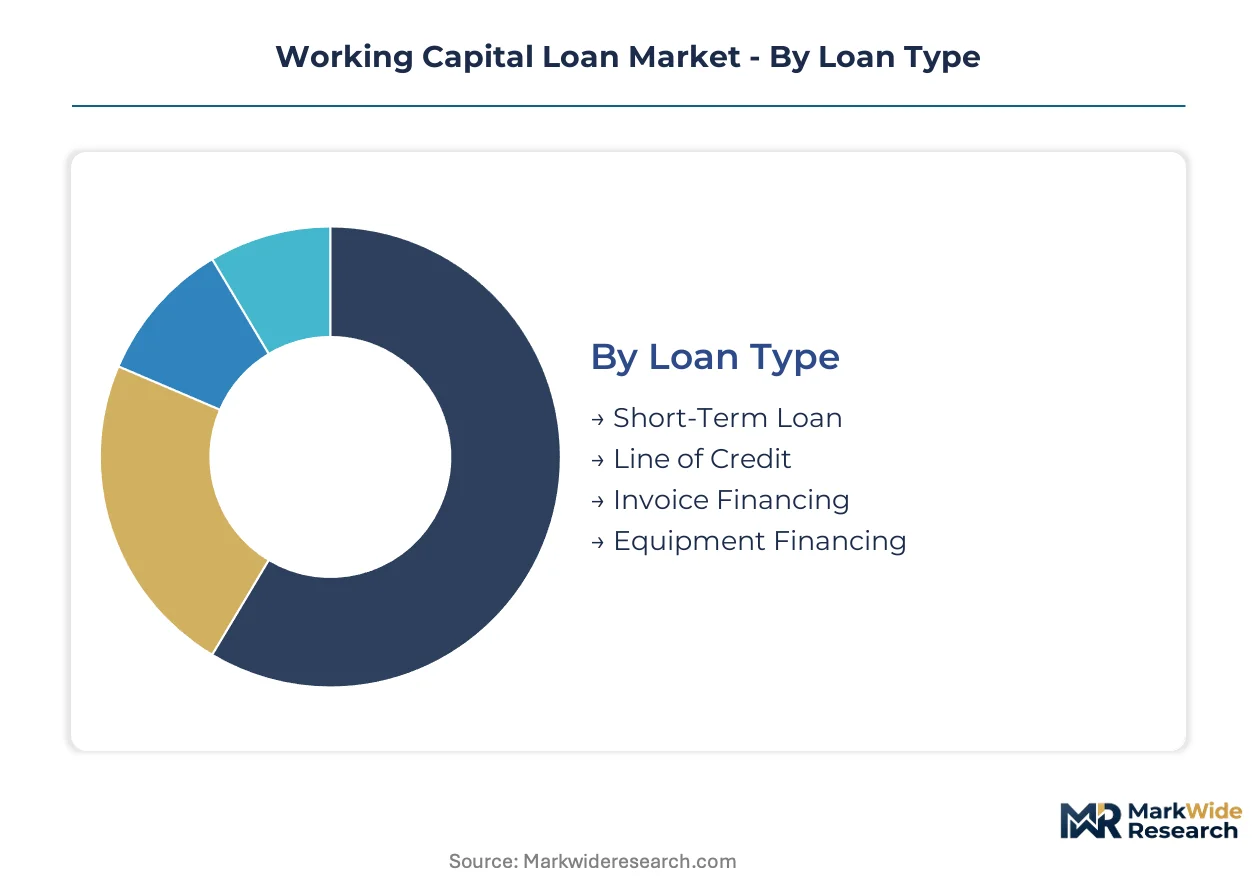
Working capital loan segmentation reveals how product structures, borrower scale, and industry risk profiles reshape lender economics. Understanding these dimensions exposes where automated underwriting delivers margin compression versus premium pricing power.
Loan Type:
Margin pools concentrate in collateral-backed products where risk-adjusted pricing sustains wider spreads than unsecured revolving facilities.
- Line of Credit:Revolving structures allow borrowers to draw, repay, and redraw within committed limits, with interest charged only on outstanding balances. Retail trade and manufacturing distributors across the United States favor this flexibility for seasonal inventory builds, though unused commitment fees erode lender yield during low-utilization periods.
- Invoice Financing:Accounts receivable serve as primary collateral, with advance rates typically tied to debtor credit quality. Agricultural cooperatives and manufacturing distributors adopt this structure fastest where payment terms stretch receivable cycles, but manual verification of invoice authenticity limits scalability below mid-ticket thresholds.
- Short-Term Loan:Fixed disbursement with bullet repayment suits discrete operational needs such as payroll coverage or single inventory purchases.
- Equipment Financing:Self-liquidating structures tied to specific asset acquisition fall outside pure working capital definitions but hybrid products blend characteristics.
The dominant share belongs to Line of Credit, while Invoice Financing is gaining share fastest through supply chain finance digitization.
Borrower Profile:
Automated origination has inverted traditional economics, making sub-$250K exposures profitable for digital-native lenders while relationship banking defends large-corporate share.
- Small Business:Sub-$5 million revenue borrowers with thinner credit files increasingly access capital through cash-flow underwriting powered by open banking data aggregation. Plaid-enabled verification of three months of transaction history now substitutes for two years of financial statements, compressing approval timelines from weeks to hours.
- Medium Enterprise:Revenue between $5 million and $100 million captures hybrid demand—sophisticated enough for treasury management bundles yet price-sensitive to fintech alternatives. Regional banks in the United States defend this segment through sector-specialized relationship managers who coordinate working capital with commercial deposit products.
- Large Corporation:Investment-grade borrowers with dedicated treasury functions negotiate committed credit facilities on relationship tenure rather than algorithmic speed.
- Start-Up:Pre-revenue or early-revenue ventures rely on personal guarantees or venture debt structures where traditional working capital products rarely apply.
Small Business commands volume leadership, though Medium Enterprise is climbing the fastest as automated platforms expand their ticket-size ceiling.
Industry Vertical:
Collateral liquidity and payment velocity determine sector-specific product mix and pricing tiers.
- Retail:Inventory-heavy operations with seasonal cash flow gaps drive revolving credit utilization. Multi-location franchise operators now centralize procurement through preferred lender programs, displacing branch-relationship decisions with standardized documentation requirements.
- Manufacturing:Extended production cycles and raw material financing needs favor invoice financing and supply chain finance structures where dynamic discounting platforms monetize payables extension.
- Service:Labor-cost-dominant operations with minimal physical collateral rely on unsecured lines where cash-flow underwriting and personal guarantees substitute for asset backing.
- Agriculture:Crop cycles and commodity price volatility create demand for harvest-season repayment structures, with Farm Service Agency guarantees supporting regional bank participation.
Retail holds the largest share, while Manufacturing is expanding most quickly through supply chain finance digitization connecting corporate buyers with vendor bases.
Loan Amount:
Ticket-size thresholds segment origination economics between automated platforms and relationship-managed facilities.
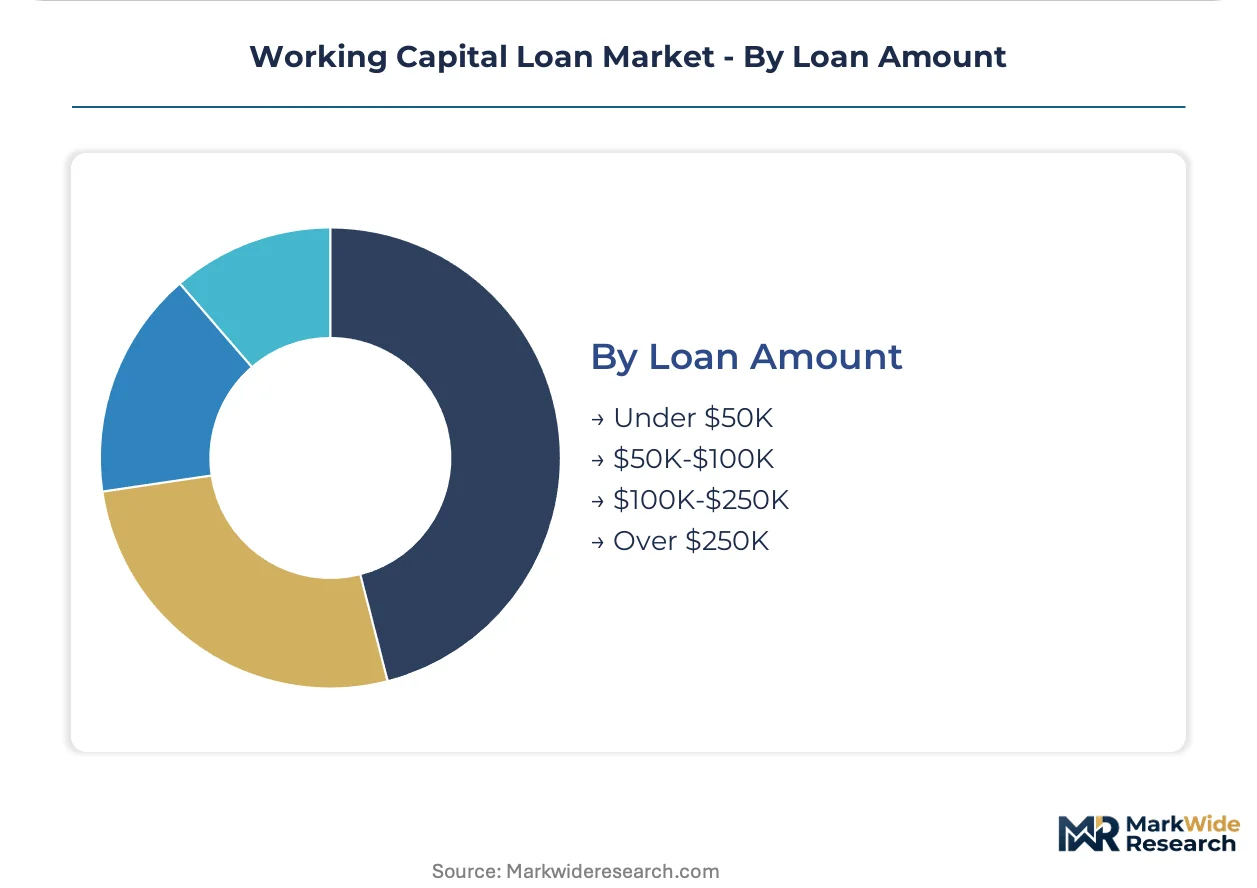
- $100K-$250K:The automation frontier where API-enabled underwriting achieves unit economics parity with larger exposures. Manufacturing distributors and agricultural cooperatives in the United States adopt these streamlined applications fastest, with three-month bank history replacing traditional documentation burdens.
- Over $250K:Relationship-managed facilities where sector specialization and treasury bundling sustain incumbent bank positioning. Bank of America and Wells Fargo anchor strategies here through branch-integrated commercial deposit products.
- Under $50K:Micro-exposures where embedded lending at point-of-sale—Shopify and Square merchant dashboards—captures borrowers at transaction origin with minimal friction.
- $50K-$100K:Mid-ticket zone where fintech speed competes with regional bank relationship tenure for established small businesses.
The $100K-$250K band dominates origination volume, while Under $50K is scaling fastest through embedded finance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where automated underwriting compresses spreads, while European jurisdictions sustain wider margins through stricter collateral requirements and longer regulatory approval cycles.
United States
Small Business Administration 7(a) guarantees expand credit access for sub-$5 million exposures, encouraging regional banks to extend facilities to thinner-file applicants. The Office of the Comptroller of the Currency supervises national bank lending standards alongside state-level usury statutes that create patchwork compliance. Multi-location franchise operators in Texas and Florida now centralize procurement through preferred lender programs, displacing branch-relationship decisions with standardized documentation.
United Kingdom
Open banking frameworks powered by Plaid and Yodlee competitors enable cash-flow verification directly from business accounts, bypassing traditional tax documentation. The Financial Conduct Authority monitors conduct in commercial lending while the Prudential Regulation Authority sets capital requirements for bank lenders. London-based fintech clusters and Manchester manufacturing distributors adopt streamlined applications fastest, with three-month bank history replacing two-year financial statement burdens.
Germany
Mittelstand manufacturers drive demand for supply chain finance structures where dynamic discounting platforms monetize payables extension. BaFin supervises lending conduct under the German Banking Act while EU-wide open banking regulations accelerate data-sharing standardization. Industrial clusters in Bavaria and Baden-Württemberg anchor invoice financing adoption, with automotive suppliers leveraging receivable-backed facilities to manage extended production cycles.
India
Non-banking financial companies capture working capital share from public sector banks through faster turnaround times and collateral-flexible products. The Reserve Bank of India regulates priority sector lending mandates that channel credit toward micro, small, and medium enterprises. Manufacturing distributors in Maharashtra and Gujarat adopt automated underwriting platforms fastest, while agricultural cooperatives in Punjab and Haryana rely on warehouse receipt financing for harvest-season liquidity.
Australia
Regional banks compete with digital lenders for small-business share as the Australian Prudential Regulation Authority tightens capital adequacy requirements. The Consumer Data Right mandates open banking participation, enabling cash-flow-based underwriting alternatives to traditional financial documentation. Sydney and Melbourne fintech clusters drive embedded lending adoption, while Queensland agricultural borrowers utilize Farm Management Deposit offsets against seasonal working capital facilities.
Working Capital Loan Market Competitive Landscape
Concentration sits with relationship-managed incumbents at the upper ticket threshold, while fragmentation dominates sub-$250K automation where digital-native lenders compress origination economics. Three archetypes define positioning: branch-integrated commercial banks bundling treasury management, algorithmic fintech platforms serving thin-file borrowers, and embedded finance operators capturing merchants at transaction origin. Dominant competitive moves include strategic partnerships between legacy cores and API-enabled underwriters, plus sector-specialized relationship banking investments in manufacturing and agriculture verticals.
Within the algorithmic underwriting tier, OnDeck and Bluevine exemplify speed-based positioning against incumbent documentation burdens. Bank of America anchors the relationship-managed archetype through branch-integrated treasury products. Wells Fargo occupies a sector-specialist position with dedicated manufacturing and agricultural banking units. These three represent divergent responses to the compression of approval timelines from weeks to hours.
| Leading Market Players |
|---|
| OnDeck |
| Bluevine |
| Bank of America |
| American Express |
| Fundbox |
| Chase |
| Fora Financial |
| Lendio |
| Wells Fargo |
| Others |
Pricing and Supply Chain Analysis
Automated underwriting engines replacing manual credit committees are simultaneously redrawing the geographic map of competitive supply and collapsing the customization premium that relationship banking once commanded. This substitution of algorithmic speed for branch-embedded judgment concentrates origination capacity in cloud-native platforms while compressing spreads on configured-to-order facilities.
Pricing Analysis
The customization-premium spread between relationship-managed revolving facilities and algorithmic originations has narrowed from triple-digit basis points to low-double-digit spreads as OnDeck and Bluevine standardize documentation. Price differentiation hinges on collateral verification intensity and treasury bundling depth, with invoice financing sustaining wider spreads than unsecured lines due to manual receivable auditing. Pricing pressure stems from embedded finance operators capturing micro-exposures at transaction origin with minimal acquisition cost. Small Business borrowers exhibit highest price sensitivity, while Medium Enterprise treasury functions prioritize speed and integration over rate minimization.
Supply Chain Analysis
Inventory-strategy preferences in working capital lending favor just-in-time capital deployment over strategic stockpiles of committed credit, compressing the value of undrawn revolver capacity. Geographic supply concentration centers on the United States, the United Kingdom, and Germany where open banking frameworks and real-time payment infrastructure enable fastest turnaround. Raw material dependencies include Plaid-enabled data aggregation, core banking system APIs, and cloud compute capacity for risk scoring engines. Single-source vulnerability in legacy core banking vendors creates integration bottlenecks for regional bank-fintech partnerships. Distribution runs through direct digital platforms, branch-integrated relationship managers, and embedded merchant dashboard integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
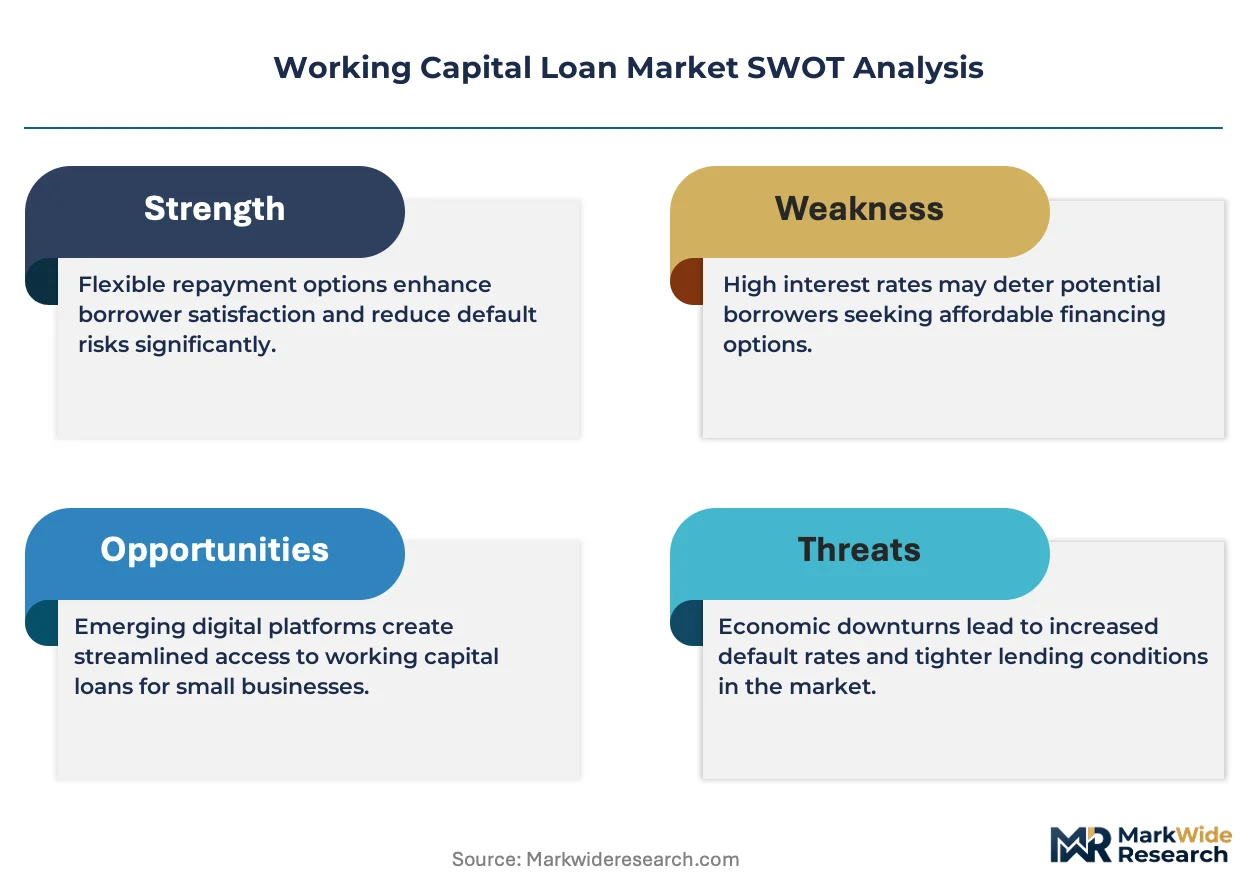
This market functions as a defensive-moat story anchored in regulatory entrenchment: the Small Business Administration 7(a) program and state-level usury compliance create barriers that pure algorithmic lenders cannot easily replicate without federal chartering or bank partnership structures.
For Market Incumbents: Consolidate sector-specialized relationship banking units in manufacturing and agriculture verticals where collateral expertise and Farm Service Agency guarantee programs sustain pricing power. Acquire API-enabled underwriting capabilities through strategic fintech partnerships rather than greenfield development, addressing the threat of deposit flight to digital-native competitors. Deepen integration between commercial deposit products and working capital facilities to elevate switching costs for Medium Enterprise treasury functions.
For New Entrants and Emerging Players: Embedded lending infrastructure gaps at point-of-sale platforms represent the most penetrable white-space, with Shopify and Square merchant dashboards demonstrating demand for transaction-origin capital access. Target agricultural cooperatives and manufacturing distributors in the United States where three-month bank history substitutes for traditional documentation burdens. Pursue white-label underwriting-as-a-service partnerships with regional banks stalled on core system modernization.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech lenders facing unit economics pressure as customer acquisition costs rise and funding costs normalize. Long-term viability favors platforms with diversified funding bases and CDFI designation unlocking below-market Treasury capital. Monitor open banking adoption velocity as the inflection signal: jurisdictions with mature data-sharing frameworks will see fastest algorithmic underwriting penetration and corresponding margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking API Integration | Enables regional banks to compress approval timelines from weeks to hours through fintech partnerships. |
| CDFI Certification Pursuit | Unlocks below-market capital from US Treasury for mission-driven pricing in underserved metropolitan areas. |
| Supply Chain Finance Digitization | Connects corporate buyers with vendor bases through dynamic discounting platforms monetizing payables extension. |
| Embedded Lending Partnership | Captures borrowers at transaction origin through Shopify and Square merchant dashboard integrations. |
| Sector-Specialized Relationship Unit | Defends Medium Enterprise share through manufacturing and agricultural banking expertise at Wells Fargo. |
Research Methodology
Operator-level perspectives from commercial lending officers, treasury management specialists, fintech product managers, and Small Business Administration guarantee administrators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from SEC 10-K filings, Federal Reserve call report data, and Consumer Financial Protection Bureau small-business lending disclosures. Bottom-up origination volume estimates triangulated against top-down addressable market calculations using banking sector asset composition data.
Sensitivity analysis across interest rate scenarios, open banking adoption curves, and regulatory enforcement intensity shaped the forecast framework. Segmentation dimensions modeled include loan type structure, borrower revenue scale, industry vertical risk profile, and geographic regulatory cluster. CAGRs were derived from trend extrapolation adjusted for structural shift impacts on origination velocity. Industry-specific inputs encompassed FedNow Service penetration rates and Section 1071 compliance cost estimates.
Underlying assumptions cover sustained small-business credit demand, stable federal guarantee program funding, and gradual core banking system modernization, with deviation risk concentrated in interest rate volatility and fair lending examination intensity. Revision becomes warranted when real-time payment infrastructure adoption crosses thresholds that fundamentally alter disbursement velocity competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
North America Mortgage/Loan Brokers Market