
 Global Revenue-Based Financing Market | 2026-2036
Global Revenue-Based Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Revenue-Based Financing Market Outlook
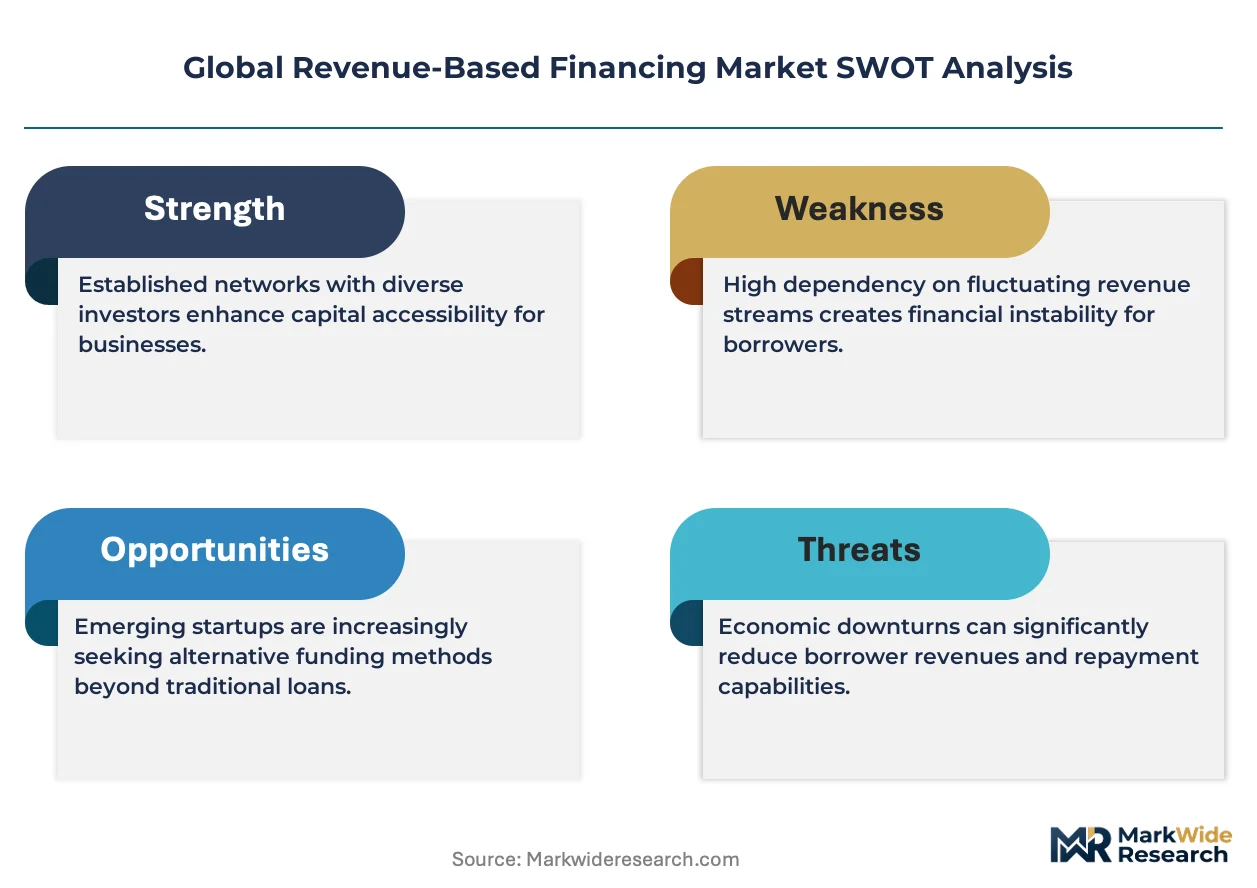
Subscription-based underwriting and recurring-revenue verification is restructuring how capital gets priced and deployed in founder-led businesses. Clearco leverages proprietary data integrations to automate investment decisions at scale, while Wayflyer anchors its operations in e-commerce cash-flow analytics. Pipe specializes in transforming recurring revenue streams into tradable assets, competing on liquidity velocity rather than traditional credit metrics.
Revenue-based financing denotes capital provision where repayment ties directly to borrower revenue performance, typically via fixed-percentage deductions from monthly receipts until a predetermined return multiple is achieved. The mechanism functions as a hybrid instrument—debt-like in structure but equity-like in risk-sharing—enabling companies with predictable recurring revenue to access growth capital without fixed amortization schedules or ownership dilution. Debt funding currently dominates transaction volume among established providers, though hybrid instruments are capturing attention from founders seeking balanced risk allocation. Seed-stage deployment remains the most contested investment stage as providers race to establish early relationships with high-velocity startups.
The SEC in the United States, the FCA in the United Kingdom, and the RBI in India each impose distinct disclosure and investor-protection frameworks that shape product design and cross-border capital flows. EU regulators under ESMA are scrutinizing revenue-based instruments for potential collective investment scheme classification, creating compliance uncertainty for platforms operating across member states. Stakeholders must monitor evolving securities-law interpretations and decide whether to structure products as regulated credit, unregulated commercial advances, or alternative investment vehicles.
Market Dynamics
Subscription revenue verification technology is compressing underwriting cycles from weeks to hours, forcing providers to rebuild their risk engines around real-time data pipelines rather than historical financial statements.
Growth Catalysts
- SaaS Recurring Revenue Models:Predictable monthly cash flows enable automated percentage-based repayment structures that align investor returns with borrower performance cycles.
- EU Alternative Investment Fund Managers Directive:Harmonized cross-border capital-raising frameworks are reducing compliance fragmentation for platforms operating across multiple member states.
- India's Startup India Seed Fund Scheme:Government-backed non-dilutive capital programs are normalizing revenue-linked repayment structures among early-stage technology ventures.
Market Restraints
- Data Integration Costs:API connections to payment processors, accounting systems, and banking platforms require substantial upfront technical investment before deployment scale becomes viable.
- UK FCA Disclosure Requirements:Evolving investor-protection frameworks around alternative finance products are extending product-approval timelines and legal review costs.
- Revenue Volatility in E-commerce:Seasonal demand swings and platform algorithm changes create repayment unpredictability that standard risk models struggle to price accurately.
Strategic Opportunities
- Brazil's Fintech Regulatory Sandbox:Central Bank of Brazil testing environments allow novel revenue-linked instruments to operate under temporary exemptions while compliance frameworks mature.
- Embedded Finance Distribution:Partnerships with vertical SaaS platforms enable capital offers at the point of spend, replacing traditional outbound sales with contextual underwriting triggers.
- AI-Enhanced Cash-Flow Forecasting:Machine learning models trained on sector-specific revenue patterns are converging with automated decision engines to expand addressable borrower segments.
Industry Challenges
- Underwriting Talent Scarcity:The intersection of data science, credit risk, and sector-specific operational expertise remains difficult to source at scale.
- Cross-Border Tax Complexity:Revenue-based repayments trigger divergent withholding tax treatments across jurisdictions, complicating fund structuring for international deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Revenue-Based Financing Market |
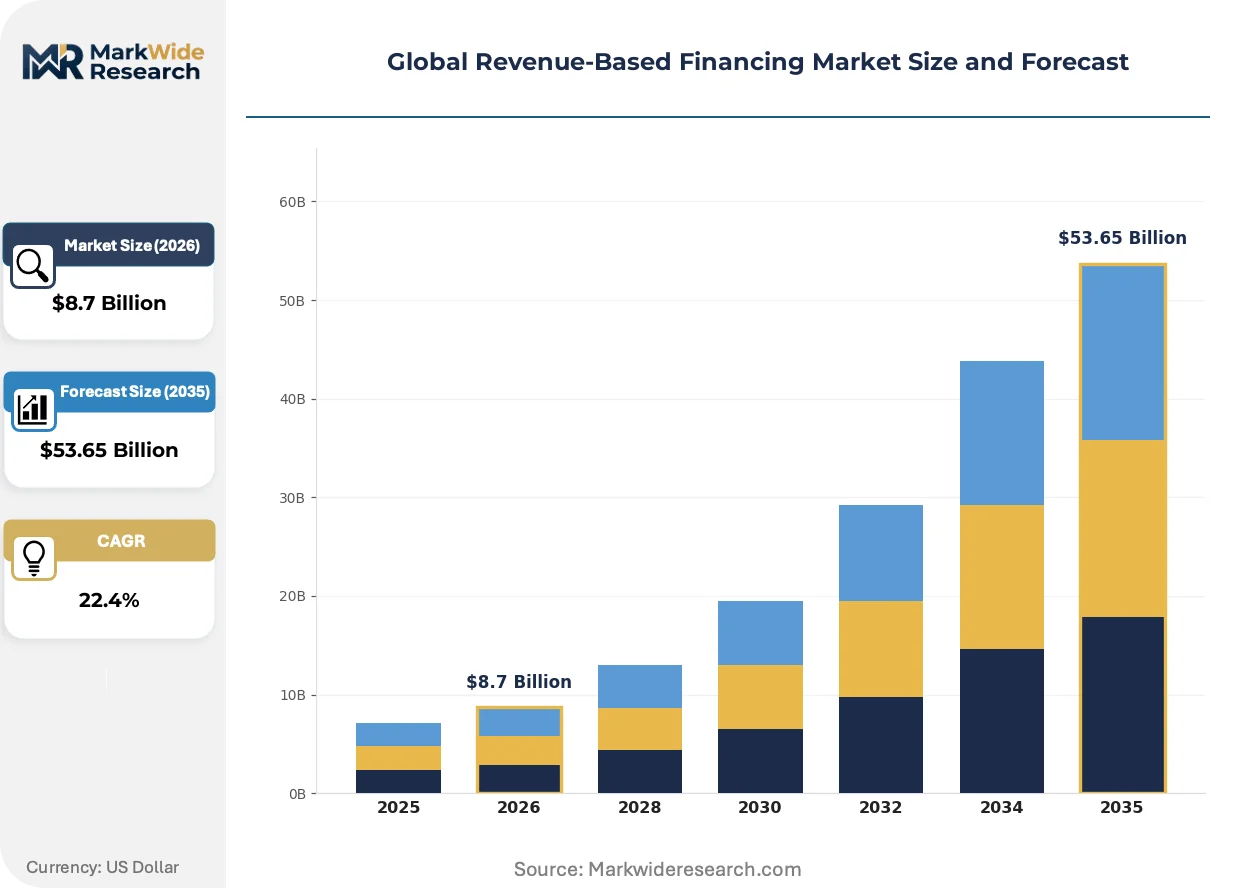
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Funding Type: Debt, Equity, Hybrid, Convertible Investment Stage: Seed, Series A, Series B, Growth Client Type: Startups, Small Businesses, Medium Enterprises, Large Corporations Payment Structure: Fixed Percentage, Revenue Threshold, Flexible Payments, Performance-Based |
| Companies Covered | Lighter Capital, Biz2Credit, Clearco, Silvr, Kapitus, Wayflyer, Pipe, Karmen, Capchase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Revenue-Based Financing Market Strategic Shifts
Real-time data infrastructure is eliminating information asymmetry between capital providers and recurring-revenue businesses, compressing the traditional due diligence timeline from weeks to minutes while expanding the pool of fundable ventures.
Application programming interfaces for financial data aggregation are converging with automated decision engines to enable instant capital deployment. E-commerce platforms and subscription software providers now connect banking, payment processor, and accounting system data through standardized pipelines. This convergence is compressing the cost structure of small-ticket underwriting, allowing providers to profitably serve borrowers previously excluded by minimum deal-size thresholds.
ESMA's scrutiny of revenue-based instruments for potential collective investment scheme classification is forcing product redesign across European platforms. Providers face binary choices between regulated fund structures and unregulated commercial advance classifications. UK and Netherlands-based platforms are most affected, with several restructuring as regulated credit providers to maintain cross-border passporting rights.
Founder preference for non-dilutive capital is displacing traditional venture debt in seed-stage financing conversations. SaaS and direct-to-consumer brands in the United States and United Kingdom now evaluate revenue-based offers alongside term sheets from venture lenders. This behavioral shift is most visible in recurring-revenue verticals where predictable cash flows support transparent repayment mechanics.
Global Revenue-Based Financing Market Segmentation
Segmentation in revenue-based financing reveals how capital providers calibrate risk-return profiles across borrower maturity, funding instrument design, and cash-flow predictability. Understanding these divisions enables providers to match repayment structures with revenue volatility patterns and founder dilution preferences.
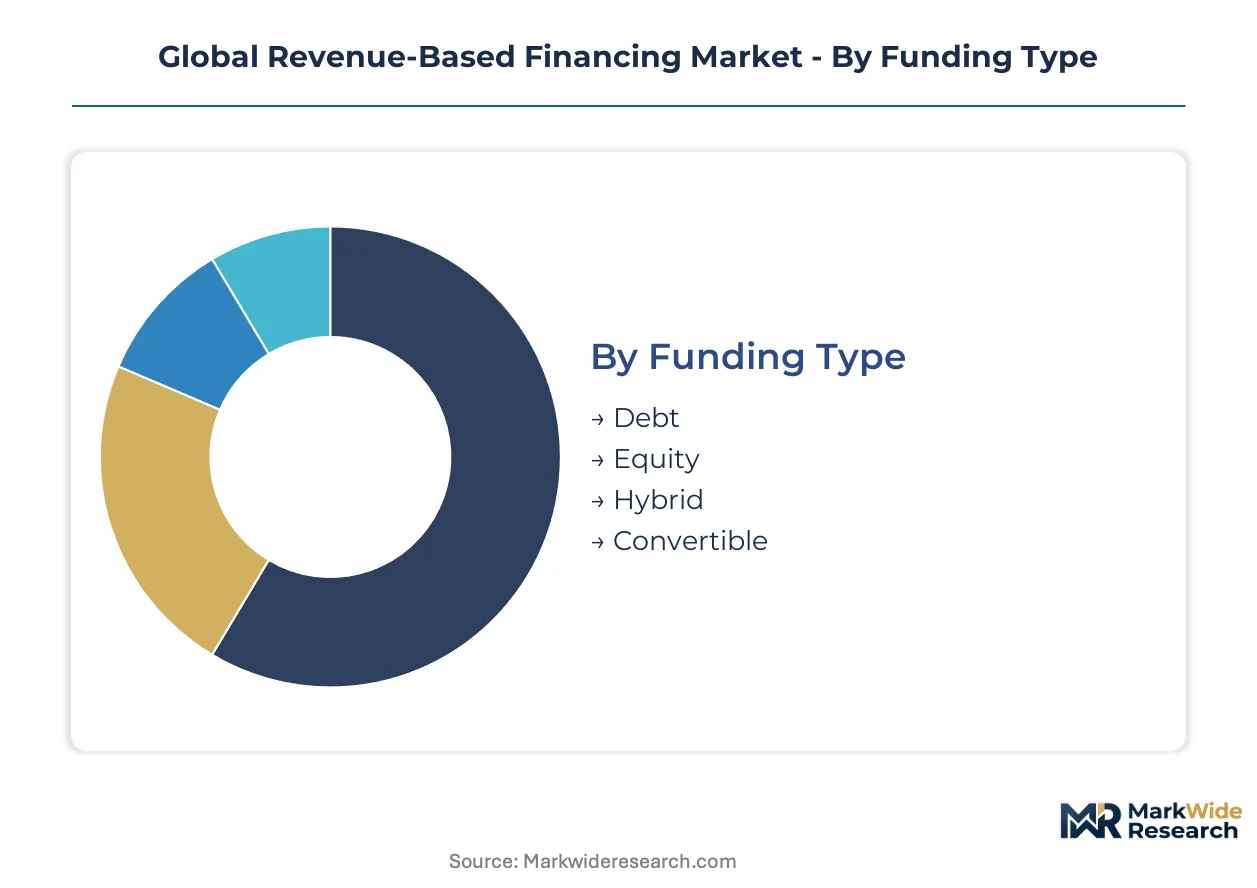
Funding Type:
Structural choice across this category ranges from standardized debt instruments to bespoke hybrid constructions that blend fixed obligations with contingent payouts.
- Debt:Fixed-return instruments with predetermined repayment multiples and no ownership conversion rights. Institutional investors in the United States and United Kingdom concentrate deployment here, drawn by collateral-like protections and predictable yield schedules.
- Hybrid:Instruments combining percentage-based revenue deductions with capped return floors and equity kickers. Demand concentrates among Series A SaaS ventures seeking balanced risk allocation between founders and capital providers.
- Equity:Direct ownership stakes with revenue-linked dividend preferences rather than fixed repayment obligations. Founders in India's startup clusters increasingly reject this structure to preserve cap table control.
- Convertible:Revenue-based advances that transform into equity upon predetermined valuation or revenue milestones. Early-stage platforms in Brazil's regulatory sandbox favor this flexibility for uncertain growth trajectories.
Most installed capacity flows through Debt. Expansion is steepest in Hybrid.
Investment Stage:
Deployment concentration across this category tracks founder sophistication and data availability for automated underwriting.
- Seed:Initial capital for pre-revenue or early-revenue ventures with minimal historical data. Providers in the United Kingdom compete aggressively here, using banking API integrations to underwrite on cash-flow velocity rather than audited financials.
- Series A:Scaling capital for ventures with 12-24 months of recurring revenue history. Automated decision engines in the United States process these applications fastest, leveraging Stripe and QuickBooks data pipelines.
- Series B:Growth financing for established recurring-revenue businesses seeking non-dilutive alternatives to venture debt. Indian fintech platforms report highest conversion rates at this stage as founders prioritize founder-friendly structures.
- Growth:Late-stage deployment for mature businesses with diversified revenue streams. European providers face ESMA classification uncertainty when structuring these larger tickets.
Series A commands the largest transaction volume. Seed-stage deployment is climbing the fastest as providers race to establish early borrower relationships.
Client Type:
Service intensity varies sharply across this category, from automated small-ticket processing to bespoke enterprise structuring.
- Startups:Venture-backed technology companies with predictable recurring revenue but limited operating history. SaaS and e-commerce platforms in the United States represent the core addressable population for automated underwriting.
- Small Businesses:Traditional Main Street operators with seasonal cash flows and minimal digital financial infrastructure. Higher data integration costs per dollar deployed constrain provider interest in this segment.
- Medium Enterprises:Established businesses with multi-year revenue track records and diversified customer bases. United Kingdom providers target this segment for cross-border expansion into EU markets.
- Large Corporations:Mature entities using revenue-linked structures for specific project financing or subsidiary capitalization. Transaction size attracts institutional fund participation but requires customized legal frameworks.
Startups absorb the majority of deployed capital. Medium Enterprises are gaining share fastest as providers build sector-specific underwriting models.
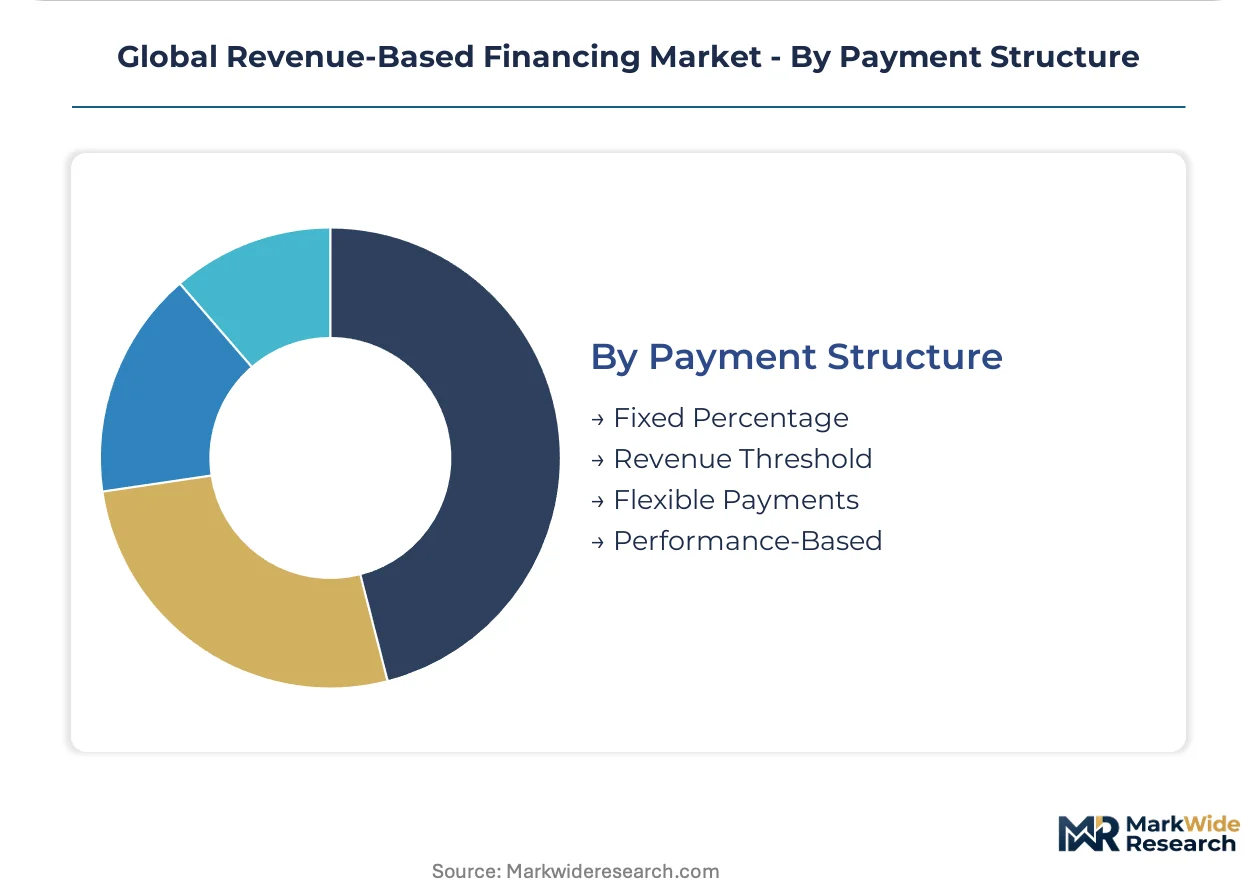
Payment Structure:
Flexibility gradients across this category determine borrower cash-flow strain during revenue downturns.
- Fixed Percentage:Unvarying revenue deductions regardless of monthly performance. Standard for SaaS borrowers with low seasonality in the United States and United Kingdom.
- Revenue Threshold:Payments activate only above predetermined monthly revenue floors. Protects e-commerce borrowers in India during post-festival demand slumps.
- Flexible Payments:Adjustable deduction rates based on trailing revenue trends. Requires real-time data infrastructure that only well-capitalized providers can maintain.
- Performance-Based:Tied to specific operational milestones or unit economics rather than raw revenue. Emerging structure for marketplace and platform businesses in Brazil's sandbox environment.
Fixed Percentage structures dominate current deployment. Revenue Threshold designs are expanding most quickly as providers compete for e-commerce borrowers with seasonal volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital providers exploit regulatory-arbitrage opportunities as compliance-cost differentials reshape cross-border deployment strategies. Founders in lower-cost jurisdictions access non-dilutive capital at compressed origination fees while platforms domicile fund structures in favorable regulatory environments.
United States
SaaS ventures in Austin and San Francisco drive transaction velocity through Stripe-integrated banking APIs. The SEC imposes disclosure frameworks for alternative finance products that shape term-sheet standardization. New York-based institutional funds anchor the largest deployment pools, channeling capital through automated decision engines into recurring-revenue borrowers.
United Kingdom
London fintech clusters concentrate provider headquarters seeking EU market access post-Brexit. The FCA's evolving investor-protection requirements extend product-approval timelines for revenue-linked instruments. Manchester and Edinburgh startup ecosystems generate seed-stage deal flow as banking API penetration enables cash-flow-based underwriting without audited financials.
India
Bangalore and Mumbai technology ventures normalize revenue-linked repayment through the Startup India Seed Fund Scheme. The RBI maintains distinct disclosure frameworks for alternative credit products that influence platform product design. Delhi-NCR SaaS founders increasingly reject equity dilution in favor of founder-friendly capital structures with percentage-based repayment mechanics.
Germany
Berlin and Munich startup ecosystems absorb capital from UK-based platforms seeking EU passporting rights. BaFin scrutiny of revenue-based instruments for potential collective investment classification creates compliance uncertainty. Hamburg fintech infrastructure providers build real-time data pipelines connecting accounting systems to automated underwriting engines.
Brazil
São Paulo e-commerce platforms test revenue-linked instruments within the Central Bank's regulatory sandbox. Temporary exemptions allow novel capital structures to operate while compliance frameworks mature. Rio de Janeiro fintech ventures deploy machine learning models trained on sector-specific revenue patterns to expand addressable borrower segments.
Global Revenue-Based Financing Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments in this founder-facing capital market. The provider base concentrates around automated underwriting platforms with proprietary data integrations and specialized e-commerce analytics shops with sector-specific risk models. Three archetypes dominate: API-first deployers compressing decision timelines to minutes, vertical specialists anchoring in SaaS or e-commerce cash-flow patterns, and hybrid structures blending percentage-based repayment with equity kickers. Competitive moves center on strategic partnerships with vertical SaaS platforms and AI-enhanced cash-flow forecasting capabilities that expand addressable segments.
Within the API-first deployer tier, Clearco and Pipe exemplify divergent approaches to automated capital deployment. Clearco occupies a position anchored in proprietary data integrations that enable investment decisions at institutional scale without human underwriting intervention. Pipe sits within the liquidity-velocity archetype, transforming recurring revenue streams into tradable assets and competing on transaction speed rather than traditional credit metrics. Wayflyer represents the vertical-specialist category, grounding operations in e-commerce cash-flow analytics with particular depth in platform-dependent revenue verification.
| Leading Market Players |
|---|
| Lighter Capital |
| Biz2Credit |
| Clearco |
| Silvr |
| Kapitus |
| Wayflyer |
| Pipe |
| Karmen |
| Capchase |
| Others |
Value Chain & Pricing Dynamics
API integration costs for banking, payment processor, and accounting system connections flow from upstream technical infrastructure through origination fee tiers downstream, compressing margins for small-ticket underwriters while concentrating pricing power with platforms achieving deployment scale.
Pricing Analysis
Direct-to-borrower origination fees dominate revenue-based financing pricing structures, bypassing intermediary markups entirely. Price differentiation rests on data infrastructure maturity and automated decision velocity, with API-first platforms commanding premium positioning against manual-underwriting shops. Pricing pressure stems from seed-stage provider competition racing to establish early borrower relationships. E-commerce borrowers with seasonal volatility exhibit highest price sensitivity, while Series A SaaS ventures with predictable recurring revenue demonstrate lowest sensitivity to fee compression.
Supply Chain Analysis
Freight and logistics costs are negligible in revenue-based financing's digital capital delivery model, though data pipeline latency between banking systems and underwriting engines creates operational friction. Capital provision concentrates in the United States, United Kingdom, and India, with fund structures domiciling in favorable regulatory jurisdictions. The supply chain draws from institutional LP commitments, banking API providers, and payment processor integrations. Single-source vulnerability in proprietary data partnerships poses structural risk. Distribution runs through direct platform interfaces and embedded finance partnerships with vertical SaaS providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Revenue-based financing operates as a geographic-arbitrage play where platforms domicile fund structures in the United Kingdom to exploit FCA regulatory clarity while deploying capital into India's higher-yielding, less-saturated borrower base.
For Market Incumbents: Hedge against hybrid instrument competition by deepening proprietary data moats through exclusive banking API partnerships. Incumbents should consolidate seed-stage market share through automated underwriting velocity before emerging vertical specialists capture sector-specific borrower relationships. Regulatory arbitrage from ESMA classification uncertainty threatens cross-border European operations; securing BaFin credit provider licensing preserves passporting rights. For New Entrants and Emerging Players: Enter via Brazil's Central Bank regulatory sandbox where temporary exemptions allow novel revenue-linked structures to operate while compliance frameworks mature. Small businesses with seasonal cash flows and minimal digital infrastructure represent the most penetrable white-space segment underserved by automated platforms. A go-to-market angle anchored in sector-specific cash-flow forecasting for Main Street operators bypasses incumbent API integration advantages. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specialist platforms with proprietary sector-specific risk models because borrower acquisition costs collapse when underwriting engines achieve scale within narrow industry verticals. Long-term viability hinges on regulatory clarity across EU member states and sustained founder preference for non-dilutive capital. Acquisition targets should demonstrate real-time data infrastructure and automated decision capabilities. The signal to watch is ESMA's final classification ruling on revenue-based instruments as collective investment schemes or regulated credit products.| Strategic Initiative | Industry Significance |
|---|---|
| Banking API Partnership Expansion | Exclusive data integrations with Stripe and QuickBooks compress underwriting cycles from weeks to minutes. |
| Regulatory Sandbox Entry | Brazil's Central Bank testing environment allows novel instruments to operate under temporary compliance exemptions. |
| Vertical SaaS Embedded Finance | Capital offers at point-of-spend replace outbound sales with contextual underwriting triggers for e-commerce borrowers. |
| AI-Enhanced Cash-Flow Forecasting | Machine learning models trained on sector-specific revenue patterns expand addressable borrower segments beyond recurring-revenue ventures. |
| Cross-Border Fund Restructuring | UK credit provider licensing preserves EU passporting rights amid ESMA classification uncertainty. |
Study Parameters
Multiple input streams — primary interviews with revenue-based financing platform executives, fund managers, and SaaS founders; secondary validation through SEC filings, FCA regulatory disclosures, and RBI alternative finance frameworks; and proprietary transaction databases — were reconciled through bottom-up and top-down triangulation. Stakeholder roles interviewed include chief investment officers at RBF platforms, venture debt underwriters, fintech regulatory counsel, and Series A SaaS CFOs evaluating financing alternatives. Secondary sources encompassed EU regulatory consultation papers, Indian Startup India program documentation, and Brazilian Central Bank sandbox participant disclosures.
Data-stream reconciliation across funding type, investment stage, client type, and payment structure segmentation enabled analytical framework construction across the projection horizon. Modeled dimensions included debt-hybrid-equity instrument classification, seed-through-growth stage deployment concentration, and fixed-flexible payment mechanics. CAGRs were derived from historical transaction velocity analysis and forward-looking deployment capacity assessments. Industry-specific forecast inputs incorporated API penetration rates in target borrower segments and evolving securities-law interpretations across US, UK, and EU jurisdictions.
Inputs from banking API providers and platform transaction disclosures were available through the study window; gaps in privately held borrower performance data introduce uncertainty bands around default rate assumptions and repayment velocity projections. Forecasts reflect documented assumptions regarding founder preference stability for non-dilutive capital and sustained regulatory tolerance for revenue-linked instruments. A model refresh is warranted upon material change in ESMA classification rulings or significant shifts in central bank sandbox policy frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Latin America Motorcycle Loan Market