
 North America Mortgage/Loan Brokers Market | 2026-2036
North America Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mortgage/Loan Brokers Market Analytics
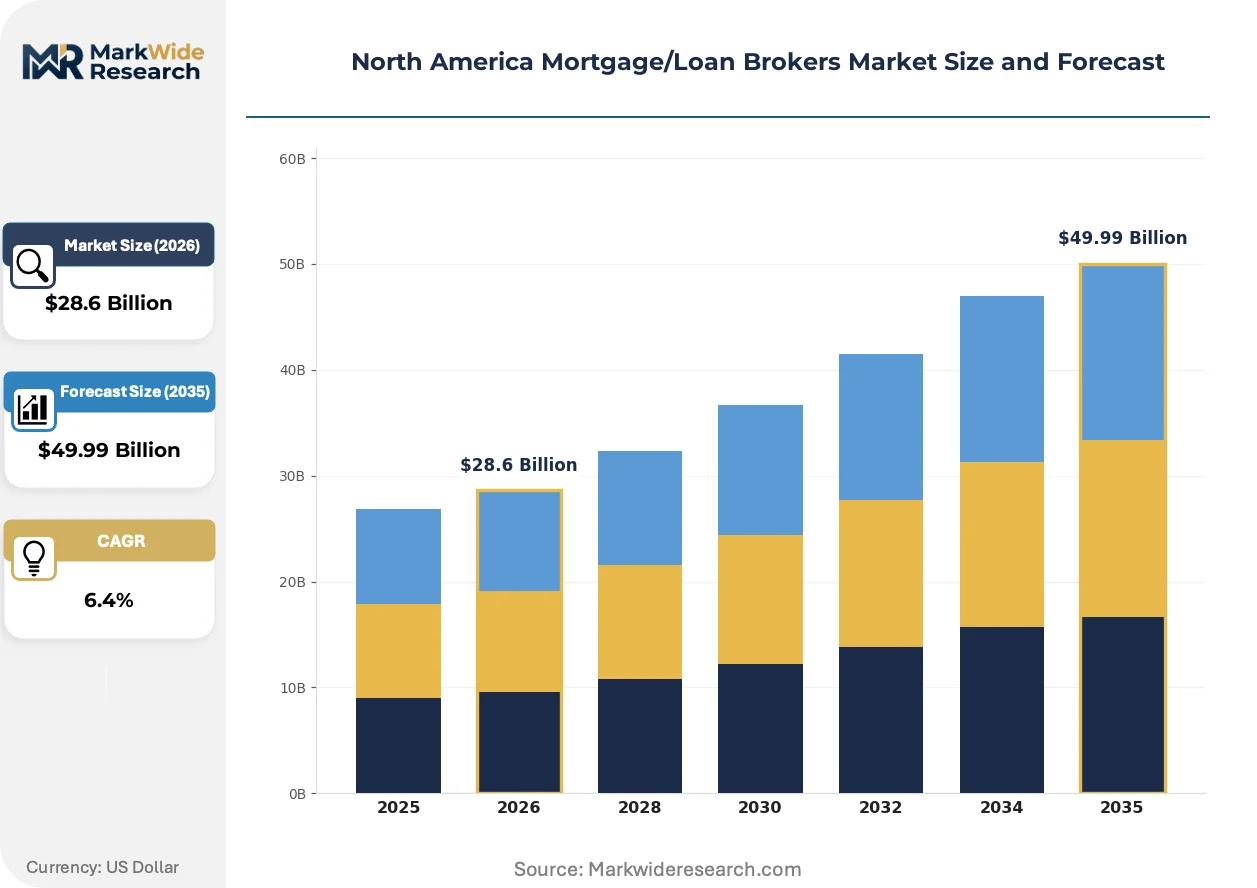
The Consumer Financial Protection Bureau's revised loan originator compensation rule is repositioning broker economics across the United States. Rocket Mortgage leverages its proprietary technology platform to sustain direct-to-consumer origination scale. United Wholesale Mortgage anchors the wholesale broker channel through its broker-centric technology and pricing infrastructure. CrossCountry Mortgage specializes in non-conventional loan products that compete aggressively in government-backed segments.
Mortgage and loan brokers function as intermediaries connecting borrowers with capital sources, earning compensation through origination fees and yield-spread premiums while managing documentation, rate shopping, and compliance verification. The broker channel processes conventional, FHA, VA, and jumbo loan products across fixed-rate and adjustable-rate structures, with loan amounts stratifying from sub-$150K entry-level financing to over-$500K high-balance jumbo transactions. Conventional loan services dominate transaction volume due to conforming limits and secondary market liquidity, while VA loan services exhibit structural growth tied to military population concentrations and specialized eligibility pathways. First-time home buyer clients represent the deepest client pool, though self-employed individuals present the fastest-growing specialized segment as alternative documentation products expand.
The CFPB enforces Truth-in-Lending and RESPA disclosure requirements that shape broker compensation transparency and referral fee prohibitions, while state-level banking regulators impose licensing, bonding, and continuing education mandates that vary across US jurisdictions and Canadian provinces. FHA and VA program guidelines from HUD and the Department of Veterans Affairs directly determine broker participation eligibility and product pricing for government-backed originations. Stakeholders must monitor pending CFPB broker fee disclosure reforms and corresponding state legislative responses that could recast competitive positioning between retail lenders and independent broker channels.
Market Dynamics
Digital underwriting platforms are compressing origination timelines and redistributing broker value from manual rate-shopping toward algorithmic loan matching and compliance automation.
Growth Catalysts
- Sun Belt Migration:Population inflows into Texas, Florida, and Arizona sustain elevated mortgage origination volumes as housing inventory turns faster than national averages.
- FHA Streamline Refinance Programs:Federal Housing Administration eligibility pathways expand broker participation in government-backed segments through reduced documentation requirements.
- Alternative Documentation Products:Bank-statement and asset-depletion loan structures unlock self-employed borrower segments previously excluded from conventional qualification frameworks.
Market Restraints
- Yield-Spread Premium Compression:CFPB compensation disclosure rules constrain broker revenue models by capping backend payments from lenders.
- Interest Rate Volatility:Federal Reserve policy uncertainty disrupts refinance pipeline predictability and locks borrower commitment timelines.
- Direct-to-Consumer Platforms:Proprietary lender technology stacks disintermediate broker relationships with creditworthy prime borrowers.
Strategic Opportunities
- Canadian Provincial Expansion:Ontario and British Columbia broker licensing frameworks present underpenetrated channels for US-originator technology transfer.
- VA Loan Specialization:Military population concentrations in San Antonio and Norfolk create concentrated demand for eligibility-navigation expertise.
- API-First Broker Networks:Embedded finance partnerships with real estate platforms and fintech marketplaces open non-traditional customer acquisition channels.
Industry Challenges
- Loan Officer Licensing Portability:State-by-state NMLS continuing education and bonding requirements fragment talent mobility across US jurisdictions.
- Legacy LOS Integration:Point-of-sale system upgrades demand capital allocation while maintaining compliance with TRID disclosure timing rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mortgage/Loan Brokers Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Conventional Loans, FHA Loans, VA Loans, Jumbo Loans Client Type: First-Time Home Buyers, Real Estate Investors, Refinancers, Self-Employed Individuals Loan Amount: Under $150K, $150K-$300K, $300K-$500K, Over $500K Interest Rate Type: Fixed Rate, Adjustable Rate, Interest-Only, Balloon Rate |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, CrossCountry Mortgage, Fairway Independent Mortgage, LoanDepot, Guaranteed Rate, CMG Mortgage, Movement Mortgage, Lendingtree, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mortgage/Loan Brokers Market Evolving Landscape
Automated valuation models and income verification APIs are collapsing the traditional information asymmetry that justified broker intermediation, forcing role redefinition around advisory rather than transactional functions.
Automated underwriting engines powered by direct-source asset and employment verification are consolidating broker workflow around exception handling rather than standard file processing. Mid-size brokerages with 50-200 loan officers adopt these platforms fastest as they seek parity with retail lender turn times. The technology is compressing headcount-per-loan metrics and shifting compensation structures toward flat fees rather than basis-point splits.
The Consumer Financial Protection Bureau's pending broker fee disclosure reforms are tightening compensation transparency requirements and restricting referral fee arrangements. Independent broker networks face margin pressure as retail lenders exploit regulatory clarity to poach originators. Wholesale channel participants in California and Texas markets are restructuring lender relationships to isolate yield-spread components from borrower-facing quotes.
First-time home buyers are gravitating toward digital-native mortgage marketplaces that aggregate lender offers through algorithmic matching rather than single-broker relationships. Sun Belt state borrowers under age 35 demonstrate highest platform adoption rates. This channel rotation favors brokerages with proprietary technology investments over traditional referral-dependent independents in Arizona and Florida metropolitan corridors.
North America Mortgage/Loan Brokers Market Segmentation
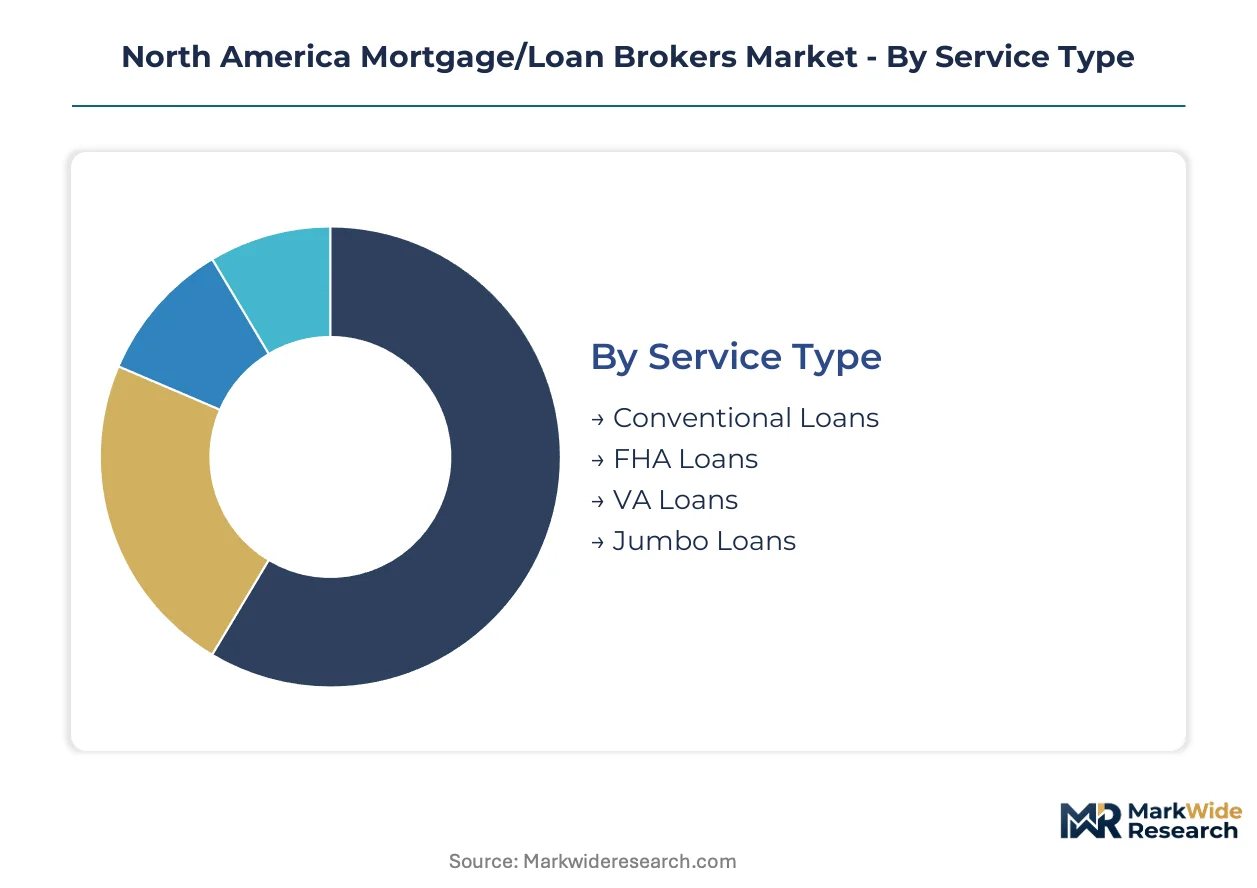
Broker revenue concentration varies sharply across loan structures and borrower profiles, with compensation models and compliance burdens shifting materially by segment. Understanding these divisions clarifies where technology investments and licensing specialization generate sustainable margin.
Service Type:
Borrower qualification complexity and secondary market liquidity determine where brokers can extract yield-spread premiums versus flat origination fees.
- Conventional Loans:Conforming balance limits and Fannie Mae/Freddie Mac standardized guidelines enable highest broker transaction velocity. Demand clusters in Sun Belt metropolitan areas where conforming limits accommodate median home prices without jumbo triggers.
- FHA Loans:Federal Housing Administration mortgage insurance pools expand first-time buyer access through reduced downpayment thresholds. Broker participation concentrates in markets with elevated renter-to-owner transition rates, particularly Texas and Florida urban corridors where HUD-approved counseling networks operate.
- VA Loans:Department of Veterans Affairs guaranty programs eliminate downpayment requirements for eligible service members. Military population density in San Antonio and Norfolk creates concentrated broker specialization demand.
- Jumbo Loans:Non-conforming balances above agency limits require portfolio lender relationships and expanded documentation. High-cost California and Northeast markets sustain this segment despite interest rate sensitivity.
Conventional Loans lead on scale; VA Loans lead on momentum.
Client Type:
Documentation burden and repeat transaction frequency shape broker customer acquisition economics across borrower cohorts.
- First-Time Home Buyers:Downpayment assistance program navigation and credit counseling coordination generate advisory-heavy engagements. Sun Belt state housing affordability initiatives expand this pool fastest.
- Real Estate Investors:Debt-service-coverage ratio products and portfolio underwriting require specialized lender relationships. Multi-property borrowers in Arizona and Florida metropolitan areas drive recurring origination volume.
- Refinancers:Rate-and-term or cash-out transactions spike during Federal Reserve easing cycles. Broker retention depends on rate-alert systems and automated pipeline management.
- Self-Employed Individuals:Bank-statement and asset-depletion qualification pathways unlock borrowers excluded from W-2-based underwriting. This cohort is expanding most quickly as gig economy participation rises.
First-Time Home Buyers anchor transaction volume; Self-Employed Individuals show steepest expansion trajectory.
Loan Amount:
Agency eligibility thresholds and jumbo cutoff points stratify broker compensation structures and lender panel requirements.
- Under $150K:Entry-level financing in rural and Rust Belt markets where conforming limits far exceed median prices. Limited broker engagement due to fixed-cost economics and direct-to-consumer platform competition.
- $150K-$300K:Core first-time buyer range dominating Sun Belt origination volume. Standardized documentation enables highest broker efficiency ratios.
- $300K-$500K:Move-up buyer segment requiring expanded debt-to-income analysis. High-balance conforming thresholds vary by county, demanding geographic pricing precision.
- Over $500K:Jumbo and super-jumbo territory requiring private banking relationships and portfolio lender access. Concentrated in California coastal and Northeast urban markets.
$150K-$300K dominates unit economics; Over $500K commands highest per-loan revenue.
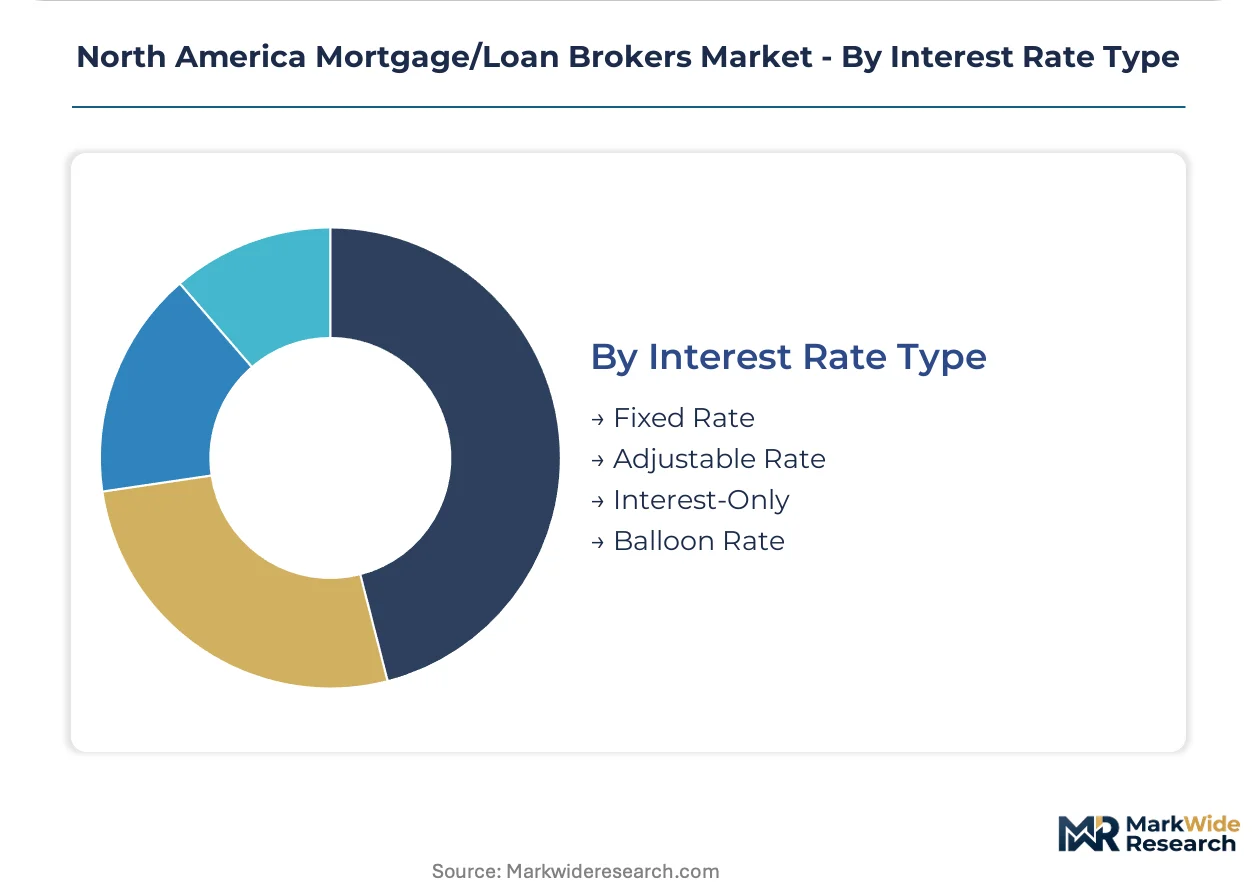
Interest Rate Type:
Borrower risk tolerance and holding-period expectations determine product mix and hedging requirements for broker operations.
- Fixed Rate:30-year and 15-year amortizing structures providing payment certainty. Dominates purchase originations across all client types in rising or uncertain rate environments.
- Adjustable Rate:Initial fixed periods followed by index-based adjustments appeal to short-term holders. ARM volume concentrates among refinancers and investors in Texas and Florida.
- Interest-Only:Reduced initial payments for cash-flow-focused borrowers, typically investors or high-net-worth individuals. Requires specialized investor guidelines and expanded disclosure compliance.
- Balloon Rate:Short-term structures with lump-sum maturity payments. Limited to commercial and niche residential applications with documented exit strategies.
Fixed Rate structures command absolute volume; Adjustable Rate products gain share fastest in investor-heavy markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed mortgage professionals concentrate in Sun Belt metropolitan corridors where housing inventory velocity sustains origination volume. Broker networks cluster around military installations and technology hubs that generate specialized borrower demand. Regulatory frameworks vary across state and provincial jurisdictions, shaping compensation structures and licensing portability.
United States
Sun Belt migration into Texas, Florida, and Arizona sustains elevated purchase origination activity as housing inventory turns faster than national averages. The Consumer Financial Protection Bureau enforces Truth-in-Lending and RESPA disclosure requirements that govern broker compensation transparency. Dallas-Fort Worth anchors wholesale broker network density, with independent operators processing conventional and government-backed products through digital underwriting platforms.
Canada
Provincial licensing frameworks in Ontario and British Columbia create structured entry points for broker participation in purchase and refinance markets. The Office of the Superintendent of Financial Institutions oversees mortgage insurer capital requirements that indirectly shape broker product availability. Greater Toronto's broker density reflects elevated transaction volumes in high-rise condominium financing, with originators specializing in first-time buyer downpayment assistance navigation.
Mexico
Mortgage broker penetration remains limited as Infonavit and commercial banks dominate residential lending through direct origination channels. The Comisión Nacional Bancaria y de Valores regulates non-bank financial intermediaries with lighter touch than US or Canadian counterparts. Mexico City metropolitan area shows emerging broker activity in upper-income segments where private banking relationships and dollar-denominated products attract cross-border financing expertise.
North America Mortgage/Loan Brokers Market Competitive Landscape
The competitive structure tilts toward technology-enabled wholesale lenders and direct-to-consumer platforms over traditional independent broker networks. Market concentration is moderate, with national-scale originators capturing disproportionate volume in government-backed and jumbo segments. Three archetypes dominate: proprietary technology platforms, wholesale broker-centric infrastructure providers, and non-conventional product specialists. Competitive moves center on API-first partner integrations and rate-alert automation systems that lock borrower relationships before application submission.
Within the wholesale channel, United Wholesale Mortgage anchors broker-centric technology and pricing infrastructure for independent originators across US markets. Rocket Mortgage occupies the direct-to-consumer platform tier, leveraging proprietary technology to sustain origination scale without traditional broker intermediation. CrossCountry Mortgage exemplifies the non-conventional specialist archetype, competing in government-backed segments through expanded documentation flexibility and military borrower eligibility expertise.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| CrossCountry Mortgage |
| Fairway Independent Mortgage |
| LoanDepot |
| Guaranteed Rate |
| CMG Mortgage |
| Movement Mortgage |
| Lendingtree |
| Others |
Value Network & Pricing Analysis
Commission-based compensation splits from flat-fee advisory services create divergent margin structures across broker tiers, with technology-enabled platforms capturing scale efficiencies that manual rate-shopping operations cannot match. This bifurcation concentrates supply chain investment in API-first underwriting infrastructure while legacy broker networks face sourcing pressure from direct-to-consumer platform competition.
Pricing Analysis
Bundled origination services versus unbundled advisory-only engagements define the pricing landscape. Transactional brokers earn through yield-spread premiums and origination fees tied to loan volume, while advisory-centric models charge flat fees for eligibility navigation and documentation support. Price differentiation hinges on technology integration depth and compliance automation sophistication. Pricing pressure intensifies as CFPB disclosure rules compress backend compensation from lenders. First-time home buyers exhibit highest price sensitivity; jumbo loan borrowers demonstrate lowest sensitivity due to complexity premium tolerance.
Supply Chain Analysis
Freight and logistics costs are negligible in this digital-service market, yet data infrastructure and cloud computing expenses function as analogous supply chain inputs. Technology vendors concentrate in the United States and Canada, with underwriting platform providers clustering in Texas, California, and Ontario financial technology corridors. Raw material dependencies include direct-source verification APIs, automated valuation model licenses, and loan origination system software. Supply chain risk centers on single-source vulnerability to proprietary lender technology stacks that disintermediate broker relationships. Distribution runs through wholesale lender networks, real estate platform partnerships, and direct-to-consumer digital marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as borrower demand shifts toward premium advisory specifications over transactional rate-shopping. Sophisticated eligibility navigation and compliance automation now command sustained fee premiums.
For Market Incumbents: Acquire proprietary underwriting technology assets to defend against direct-to-consumer platform disintermediation. Consolidate independent broker networks in Sun Belt metropolitan corridors where population inflows sustain origination volume. Channel control through API-first real estate platform partnerships offers defensive positioning against Rocket Mortgage and United Wholesale Mortgage scale advantages. For New Entrants and Emerging Players: Embedded finance partnerships with proptech marketplaces and digital real estate platforms offer the lowest customer acquisition cost route. Target self-employed borrower segments in Arizona and Florida where alternative documentation products remain underpenetrated. White-space concentration exists in Canadian provincial expansion, particularly Ontario and British Columbia licensing frameworks. Go-to-market leverage rests on military population concentrations for VA loan specialization. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size brokerages possessing 50-200 loan officer scale and technology parity with retail lenders. Long-term viability favors operations with proprietary platform investments over referral-dependent independents. Acquisition target archetype: technology-enabled wholesale channel participants with government-backed product expertise. Signal to watch: CFPB broker fee disclosure reform implementation as margin structure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedded finance partnerships with Zillow and Redfin collapse customer acquisition costs for originators. |
| VA Loan Specialization Buildout | Military population density in San Antonio and Norfolk creates defensible eligibility expertise moats. |
| Canadian Provincial Licensing Expansion | Ontario and British Columbia frameworks enable technology transfer from US-originator infrastructure. |
| Alternative Documentation Product Development | Bank-statement qualification pathways unlock self-employed segments excluded from conventional underwriting. |
| Wholesale Channel Consolidation | Independent broker network aggregation in Texas and Florida captures Sun Belt migration origination volume. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national jurisdiction. The research combines structured interviews with mortgage broker principals, wholesale lender relationship managers, and real estate platform partnership directors with secondary validation through NMLS licensing databases, CFPB regulatory filings, and HUD program participation records. Bottom-up transaction volume estimates triangulate against top-down mortgage origination market assessments.
Granularity-level modeling disaggregates the market across loan product type, client segment, loan amount tier, and interest rate structure, with additional dimensioning by state-level regulatory cluster and metropolitan statistical area origination velocity. CAGRs derive from regression analysis of historical origination patterns against population migration flows, interest rate scenario modeling, and housing affordability program expansion trajectories. Forecast inputs include Federal Reserve policy pathway assumptions and digital platform adoption curves across borrower age cohorts.
The model assumes a particular technology adoption path; alternative pathways for automated underwriting engine deployment would alter the outlook for broker headcount requirements and compensation structures. Forecasts reflect assumptions about CFPB regulatory trajectory and Sun Belt population migration persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Debt Financing Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Microfinance Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Car Finance Market