
 Used Car Financing Market | 2026-2036
Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Used Car Financing Market Outlook
US captive auto lenders is pivoting toward used vehicle portfolios as new car affordability constraints redirect consumer flow. Ally Financial leverages its digital servicing infrastructure to sustain margin efficiency across subprime and near-prime segments. Santander Consumer USA specializes in deep subprime underwriting, occupying a distinct risk-return tier that mainstream banks avoid. Capital One Auto Finance competes through data-driven pricing models that navigate credit spectrum segmentation with precision.
Used car financing denotes credit instruments collateralized by pre-owned vehicles, typically featuring loan-to-value ratios between 80% and 120% depending on borrower credit profile and vehicle age, with primary purpose of enabling vehicle acquisition without full upfront capital outlay. Secured loans dominate origination volume due to lower loss severity from collateral recovery, while dealer financing channels capture the fastest growth as point-of-sale digitization compresses approval timelines. Personal loans for used vehicle purchases concentrate margin pools in prime credit tiers where unsecured structures command higher interest spreads.
The US Consumer Financial Protection Bureau monitors auto lending for fair lending violations, while the Federal Reserve's interest rate posture directly shapes consumer payment affordability and originator funding costs. State usury laws and licensing requirements create fragmented compliance terrain that favors multi-state operators with dedicated regulatory infrastructure. Stakeholders must monitor real-time credit performance deterioration signals and benchmark their underwriting models against evolving regulatory expectations for algorithmic fairness.
Market Dynamics
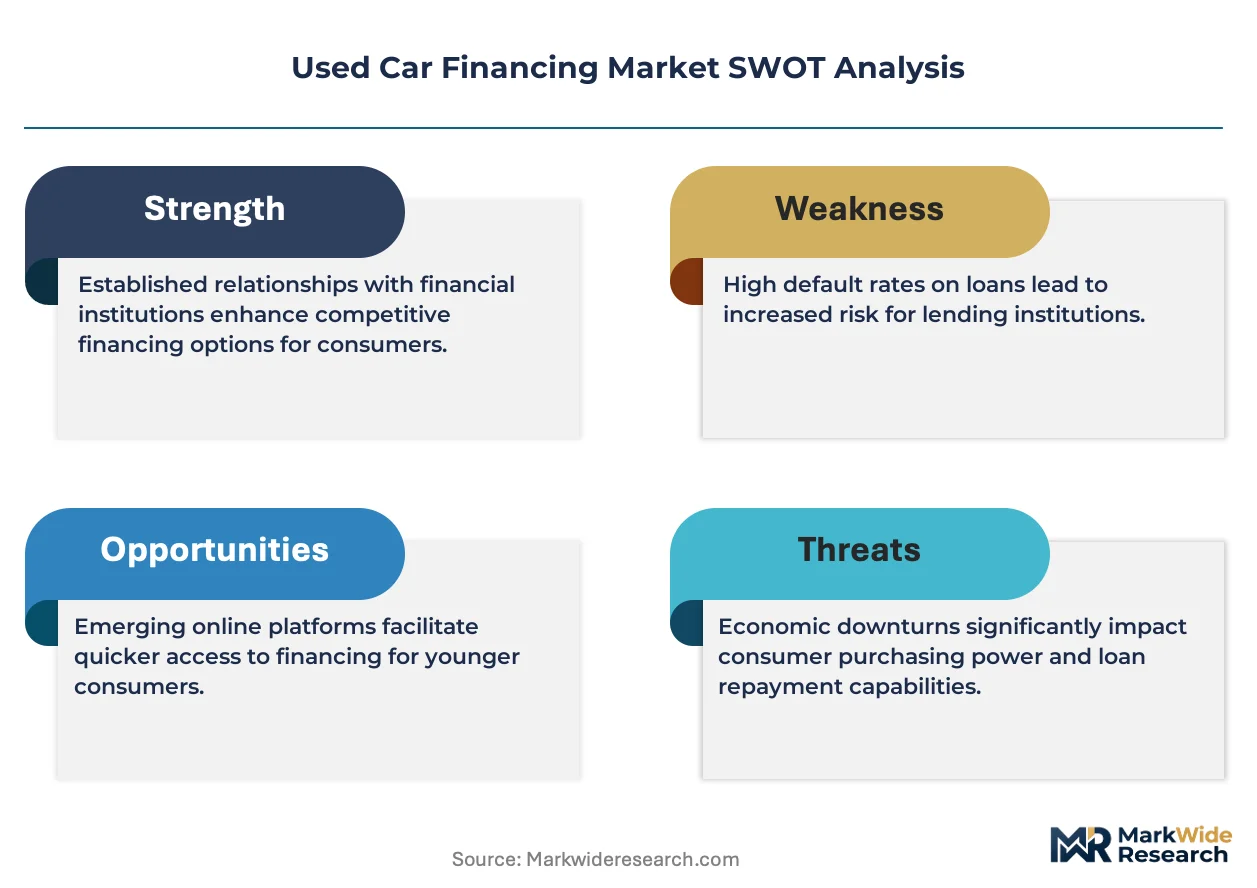
Digital underwriting platforms are compressing loan approval timelines from days to minutes, forcing traditional originators to rebuild their technology stacks or surrender market position to agile fintech entrants.
Growth Catalysts
- CFPB Fair Lending Oversight:Heightened scrutiny of dealer markup practices creates competitive opening for direct-to-consumer digital lenders with transparent pricing algorithms.
- Embedded Finance APIs:Dealer management system integrations enable instant credit decisions at point of sale, expanding subprime borrower access previously excluded by manual underwriting.
- Texas:Franchise dealer concentration in the Dallas-Fort Worth metroplex generates scale economies for captive finance companies operating dedicated regional servicing centers.
Market Restraints
- Wholesale Funding Volatility:Securitization markets for subprime auto ABS experience spread widening during Federal Reserve tightening cycles, squeezing originator margins.
- Collateral Depreciation Risk:Used vehicle wholesale values fluctuate with semiconductor-driven new car production gaps, creating loan-to-value mismatches in underwater portfolios.
- State Usury Fragmentation:Interest rate caps varying from California to Texas force multi-state operators to maintain parallel pricing infrastructures and compliance teams.
Strategic Opportunities
- Florida Subprime Penetration:Miami-Dade and Orlando metro areas show below-average digital lender presence relative to credit demand, offering first-mover positioning for algorithmic underwriting platforms.
- Buy-Here-Pay-Here Digitization:Independent dealers with captive financing operations lack integrated loan servicing technology, creating white-label software partnership potential.
- Infrastructure Investment and Jobs Act:Electric vehicle tax credit transferability provisions stimulate used EV financing demand as buyers seek to capture residual incentive value.
Industry Challenges
- Data Science Talent Scarcity:Machine learning engineers with credit risk modeling experience command premium compensation, constraining mid-tier originator model development velocity.
- Legacy Core System Integration:Mainframe-based loan origination systems from the 1990s resist API connectivity, forcing expensive middleware layers for digital channel deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Car Financing Market |
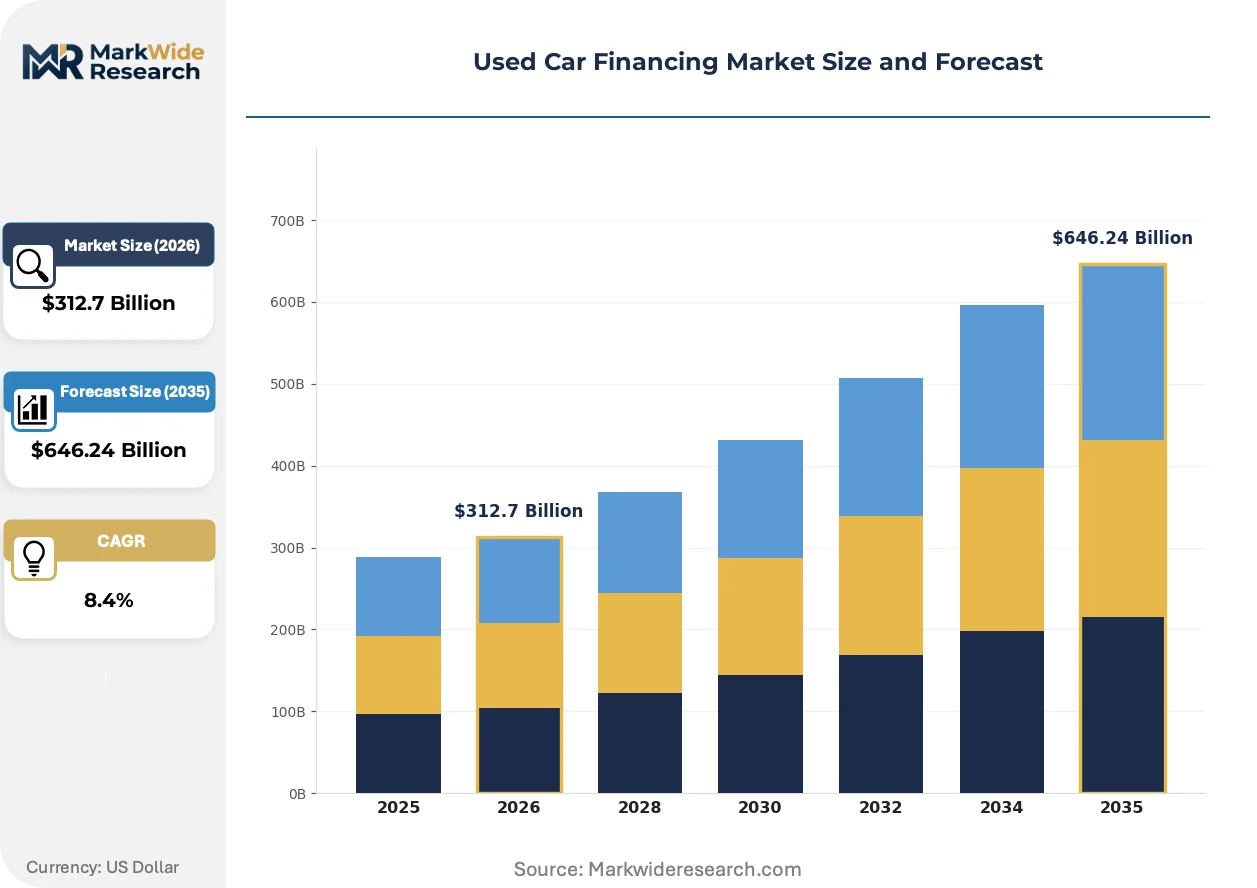
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Personal Loans, Dealer Financing Customer Type: Individual Buyers, Commercial Buyers, Fleet Operators, First-Time Buyers Credit Score: Excellent, Good, Fair, Poor Loan Term: Short-Term, Medium-Term, Long-Term, Flexible Terms |
| Companies Covered | Ally Financial, Capital One Auto Finance, Wells Fargo Auto Finance, Santander Consumer USA, Toyota Financial Services, Bank of America, Chase Auto Finance, GM Financial, Ford Motor Credit Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Car Financing Market Strategic Shifts
Artificial intelligence is restructuring competitive advantage around predictive accuracy rather than balance sheet scale, rewarding originators who can price risk at the individual loan level.
Machine learning credit models are consolidating underwriting decisions across formerly segmented risk tiers. Subprime specialists deploy gradient-boosted algorithms that parse alternative data signals including utility payment histories and gig economy income patterns. Ally Financial and Santander Consumer USA compete primarily on model precision rather than distribution reach.
The US Consumer Financial Protection Bureau's 2022 guidance on algorithmic fairness imposes adverse action notice requirements on AI-driven credit decisions. Lenders must now generate specific reasons for loan denials from black-box models, forcing investments in explainable AI tooling. Deep subprime originators face disproportionate compliance burden given higher denial rates in their target segments.
Subscription-based vehicle access models are fragmenting traditional ownership patterns. Younger borrowers in California and New York increasingly favor short-term used car leases with bundled maintenance over conventional installment loans. Lenders respond with residual-value-backed products that mirror captive lessor structures without manufacturer balance sheet support.
Used Car Financing Market Segmentation
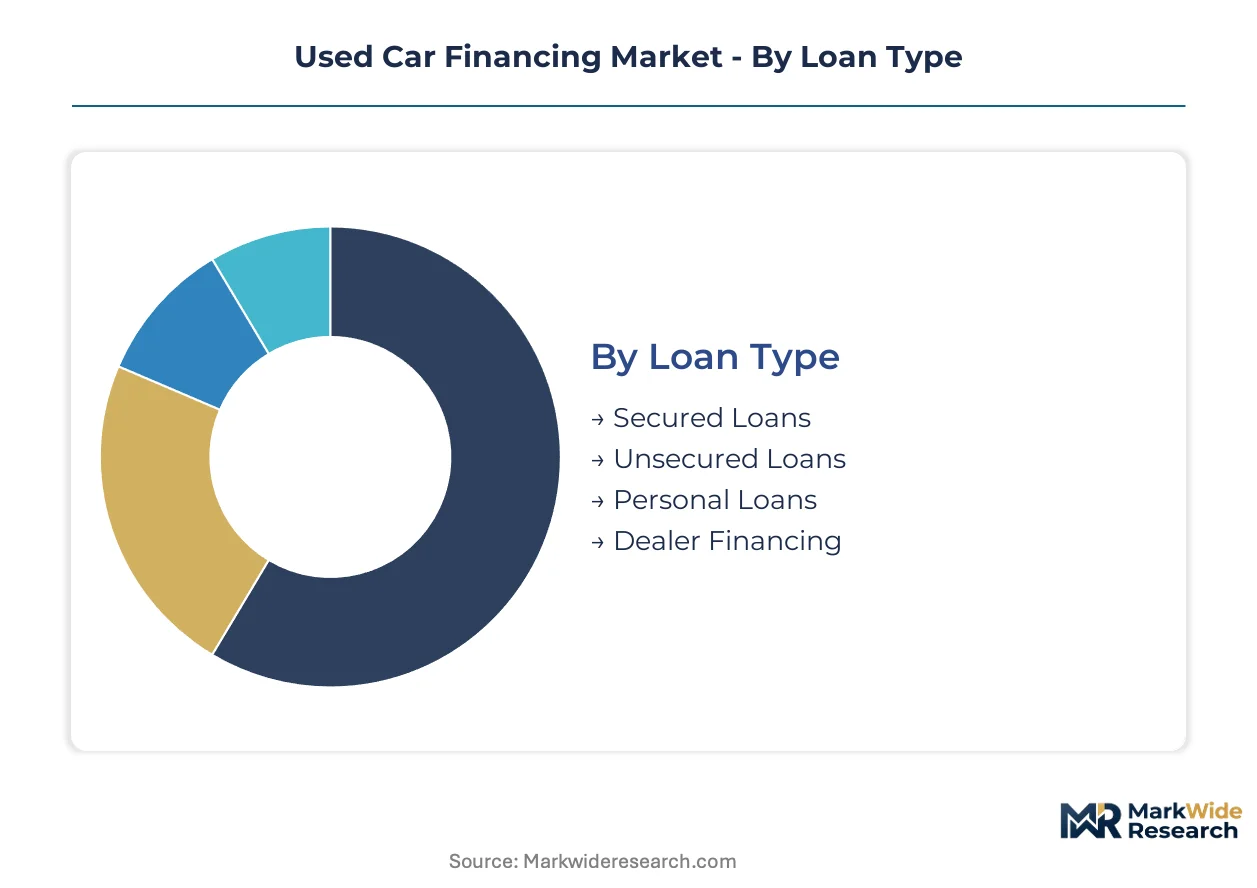
Used car financing segmentation determines capital allocation efficiency across originators with varying risk appetites. Loan structures, borrower profiles, and term configurations create distinct margin pools that reward specialized underwriting capabilities.
Loan Type:
Capital intensity peaks with dealer financing infrastructure, where captive lenders must fund floorplan credit alongside retail originations.
- Secured Loans:Collateralized by vehicle titles with perfected security interests, these instruments dominate originator balance sheets due to lower loss severity from repossession recovery. Demand concentrates among subprime borrowers in Texas and Florida, where state lien perfection laws favor rapid collateral liquidation.
- Dealer Financing:Point-of-sale credit decisions require integrated loan origination systems, dealer management software APIs, and real-time funding capabilities. Ally Financial and Santander Consumer USA compete primarily on approval speed rather than rate in this channel.
- Unsecured Loans:Absence of collateral demands higher interest spreads and stricter credit screening, limiting volume to prime-tier borrowers with established payment histories.
- Personal Loans:General-purpose credit structures allow vehicle acquisition without title liens, appealing to borrowers seeking simplified documentation.
Most installed capacity flows through Secured Loans. Expansion is steepest in Dealer Financing.
Customer Type:
Application patterns diverge sharply between individual consumption and revenue-generating fleet deployment.
- Individual Buyers:Retail borrowers seeking personal transportation represent the volume foundation, with subprime penetration expanding fastest among gig economy workers needing vehicle access for income generation. Digital underwriting platforms from Ally Financial and Capital One Auto Finance capture this flow through mobile-optimized application workflows.
- Fleet Operators:Commercial vehicle acquisition at scale demands customized amortization schedules aligned with depreciation tax treatment and residual value forecasting. Demand concentrates among last-mile delivery contractors in California and Texas metropolitan corridors.
- Commercial Buyers:Small business proprietors purchasing work vehicles require blended personal-commercial credit assessments that traditional scoring models handle poorly.
- First-Time Buyers:Thin-file applicants lacking established credit histories drive demand for alternative data integration in underwriting models.
Individual Buyers anchor current origination volumes. Fleet Operators are climbing the fastest as e-commerce logistics reshape vehicle demand.
Credit Score:
Risk-based pricing precision separates profitable originators from those suffering adverse selection.
- Poor:Deep subprime borrowers below 580 FICO scores require specialized servicing infrastructure for collections and loss mitigation. Santander Consumer USA maintains dedicated operations centers for this segment in Texas and Arizona.
- Fair:Near-prime borrowers between 580-669 scores represent the contested middle ground where machine learning models from Capital One Auto Finance and Ally Financial compete on pricing granularity.
- Excellent:Super-prime borrowers above 740 scores generate minimal loss rates but thin interest margins, forcing volume scale for profitability.
- Good:Prime-tier borrowers between 670-739 scores balance risk and return for diversified portfolios.
Fair credit tier absorbs the most underwriting technology investment. Poor credit tier is gaining share fastest as digital platforms broaden access.
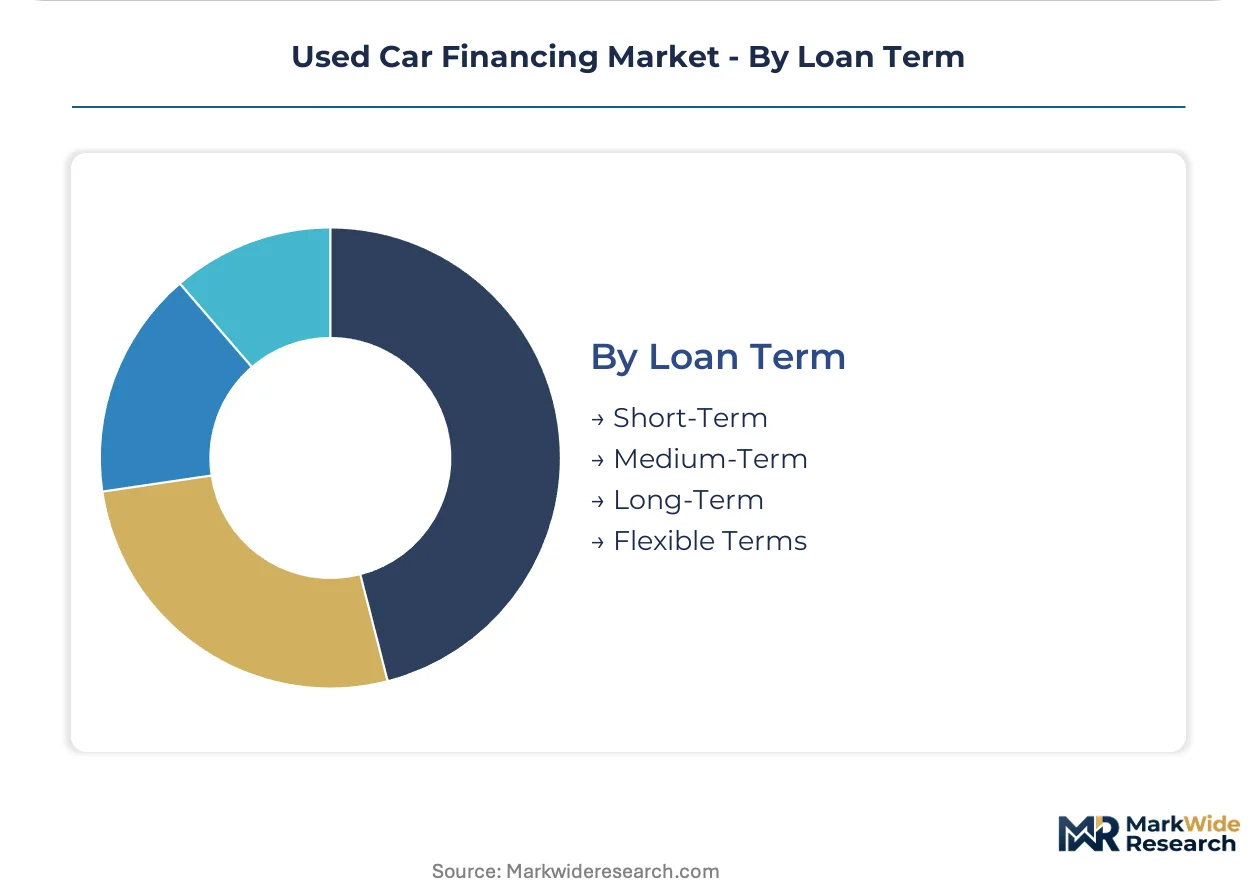
Loan Term:
Duration selection directly shapes loss severity curves and securitization pool performance.
- Long-Term:Extended amortization beyond 72 months reduces monthly payments but extends loss exposure windows and amplifies negative equity risk from accelerated depreciation. Demand concentrates among subprime borrowers in California seeking payment affordability.
- Medium-Term:48-60 month structures balance payment affordability with collateral value retention, dominating prime-tier originations.
- Short-Term:Compressed repayment schedules minimize interest revenue but reduce default probability, appealing to near-prime borrowers with liquidity buffers.
- Flexible Terms:Seasonal payment structures and skip-a-month provisions accommodate irregular income patterns among gig economy workers.
Medium-Term structures carry the most securitization volume. Long-Term originations are expanding most quickly as affordability constraints reshape borrower preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes origination geography as state-level usury caps and lien perfection laws create compliance cost differentials that favor multi-state operators clustering in permissive jurisdictions. The United States dominates absolute volume, though sub-regional specialization concentrates underwriting expertise in specific metropolitan corridors.
United States
Franchised dealer networks and captive finance companies generate dominant origination volumes across Texas, Florida, and California. The Consumer Financial Protection Bureau monitors auto lending for fair lending violations and algorithmic fairness compliance. Dallas-Fort Worth metroplex concentration enables Ally Financial and Santander Consumer USA to operate dedicated regional servicing centers with scale economies.
Canada
Thin-file immigrant populations and gig economy workers drive demand for alternative data underwriting platforms in Toronto and Vancouver metropolitan areas. The Financial Consumer Agency of Canada supervises lending practices through federal oversight harmonized with provincial consumer protection laws. Ontario's Greater Toronto Area anchors digital lender expansion as point-of-sale financing penetrates independent dealer channels.
United Kingdom
Personal contract purchase structures dominate used vehicle acquisition, with subprime penetration expanding among younger borrowers in Greater London and Birmingham. The Financial Conduct Authority regulates motor finance through consumer credit permissions and affordability assessment requirements. Manchester and Leeds financial services clusters host emerging fintech originators deploying open banking data for credit decisions.
Germany
Residual-value-backed used car leasing gains traction among price-sensitive consumers in Bavaria and North Rhine-Westphalia. BaFin supervises auto finance through banking license requirements and consumer credit directive implementation. Stuttgart's automotive finance ecosystem supports captive lender operations serving manufacturer-affiliated dealer networks.
Australia
Secured personal loan structures collateralized by used vehicles concentrate in Sydney and Melbourne metropolitan markets. ASIC regulates responsible lending obligations and broker remuneration practices. Queensland's Brisbane-Gold Coast corridor shows emerging subprime demand as digital platforms displace traditional credit union channels.
Used Car Financing Market Competitive Environment
United States originators anchor the volume tier; European and Asia-Pacific specialists hold differentiated positions in residual-value products and regulatory arbitrage structures. Market structure concentrates around captive finance subsidiaries, bank-owned auto divisions, and independent subprime specialists. Three archetypes dominate: balance-sheet-scale captives, data-driven direct lenders, and deep subprime servicing specialists. Competitive dynamics center on M&A consolidation of regional dealer platforms and strategic partnerships embedding finance APIs into dealer management systems.
Within the captive finance tier, Ally Financial and Santander Consumer USA exemplify divergent risk-return positioning. Ally Financial represents the technology-integrated multi-channel archetype with digital servicing infrastructure spanning prime through subprime segments. Santander Consumer USA occupies the specialized deep subprime position that mainstream banks avoid. Capital One Auto Finance anchors the data-driven direct lender archetype, competing through algorithmic pricing precision rather than distribution reach.
| Leading Market Players |
|---|
| Ally Financial |
| Capital One Auto Finance |
| Wells Fargo Auto Finance |
| Santander Consumer USA |
| Toyota Financial Services |
| Bank of America |
| Chase Auto Finance |
| GM Financial |
| Ford Motor Credit Company |
| Others |
Value Chain & Pricing Dynamics
Floorplan funding costs cascade through dealer financing markups as captive lenders price retail originations to recover wholesale capital expenses, with subprime borrowers in Texas and Florida absorbing the steepest rate spreads due to state-level usury permissiveness.
Pricing Analysis
Dealer markup layers dominate the pricing architecture, with point-of-sale finance managers negotiating discretionary rate add-ons that compress transparency for subprime borrowers. Rate differentiation hinges on FICO tier segmentation and vehicle age depreciation curves, with deep subprime originations commanding the widest spreads. Pricing pressure intensifies as digital direct-to-consumer platforms force disclosure of markup practices. Fleet operators exhibit the lowest price sensitivity due to tax-advantaged depreciation treatment, while gig economy individual buyers face acute affordability constraints.
Supply Chain Analysis
Machine learning engineering talent scarcity in Dallas-Fort Worth and Phoenix metro areas constrains model development velocity for regional originators competing against Ally Financial and Capital One Auto Finance. Securitization pipeline capacity concentrates among Wall Street dealer desks and rating agency analytical teams in New York. Funding draws from warehouse credit facilities, subprime auto ABS issuance, and bank syndicated term debt. Single-source vulnerability manifests in concentrated buyer demand for subprime auto ABS during Federal Reserve tightening cycles. Distribution runs through franchised dealer networks, independent buy-here-pay-here lots, and emerging direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Used car financing constitutes a late-cycle quality story as borrower migration toward certified pre-owned vehicles with extended warranty coverage shifts demand toward higher-collateral-quality originations.
For Market Incumbents: Deepen integration of alternative data signals into underwriting models to defend against fintech entrants exploiting embedded finance APIs at point of sale. Prioritize explainable AI tooling investments to preempt CFPB algorithmic fairness enforcement actions. Build captive servicing infrastructure in Texas and Florida to capture subprime scale economies. For New Entrants and Emerging Players: Algorithmic underwriting platforms offer a technology-first wedge into Miami-Dade and Orlando metro areas where digital lender penetration lags credit demand. Target independent buy-here-pay-here dealers lacking integrated loan servicing technology for white-label software partnerships. Pursue residual-value-backed product structures for used electric vehicle financing as tax credit transferability stimulates demand. For Investors and Strategic Acquirers: Consolidation pressure builds where subprime servicing specialists lack digital channel infrastructure to compete with multi-channel captives. Frame long-term viability around underwriting model precision rather than balance sheet scale. Target acquisition profiles emphasizing regional dealer platform networks with embedded floorplan relationships. Monitor securitization spread widening as an inflection signal for originator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Integration | Dealer management system partnerships from Ally Financial compress approval timelines to minutes. |
| Explainable AI Tooling Investment | Adverse action notice compliance from black-box models addresses CFPB algorithmic fairness guidance. |
| Subprime Servicing Center Expansion | Dedicated regional operations in Texas and Arizona capture scale economies for deep subprime collections. |
| Residual-Value Product Development | Used electric vehicle financing structures capture Infrastructure Investment and Jobs Act tax credit transferability. |
| Alternative Data Partnership | Utility payment and gig economy income signals broaden access for thin-file borrowers excluded by traditional scoring. |
Study Parameters
Multiple input streams — primary interviews with auto lending executives, regulatory affairs specialists, and dealer operations managers; secondary validation through CFPB enforcement action databases, Federal Reserve consumer credit reports, and securitization trustee filings — were reconciled through bottom-up origination volume modeling and top-down macroeconomic triangulation.
Data-stream reconciliation across loan type, credit score tier, customer segment, and regional origination cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from vintage loss curve analysis and funding cost trajectory modeling. Forecast inputs incorporated used vehicle wholesale value depreciation schedules and subprime auto ABS spread assumptions.
The model holds under stable Federal Reserve policy and steady used vehicle collateral values; deviation in wholesale funding volatility or semiconductor-driven new car production gaps would shift origination volume and loss severity projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Peer-To-Peer Lending Market