
 Global Commercial Loan Software Market | 2026-2036
Global Commercial Loan Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Loan Software Market Foresight
The commercial loan software landscape is consolidating around a sharp split between premium enterprise suites and lightweight cloud-native alternatives. FIS anchors the high end through its embedded position in tier-one bank cores, while nCino differentiates via its Salesforce-native architecture built for mid-market velocity. Finastra competes aggressively on open API interoperability, a capability that sustains its relevance across fragmented European banking infrastructure.
Commercial loan software encompasses platforms that automate the full credit lifecycle from origination through servicing, typically integrating risk engines with document workflows and regulatory reporting modules. Cloud-based deployment now leads new installations as banks shed on-premise maintenance burdens, though hybrid architectures retain stronghold status among institutions with strict data residency requirements. Loan origination applications command the deepest investment pools, while fraud detection solutions represent the fastest-expanding segment as synthetic identity schemes proliferate. Credit scoring modules sit at the margin core, where specialized vendors extract premium pricing for alternative-data integration.
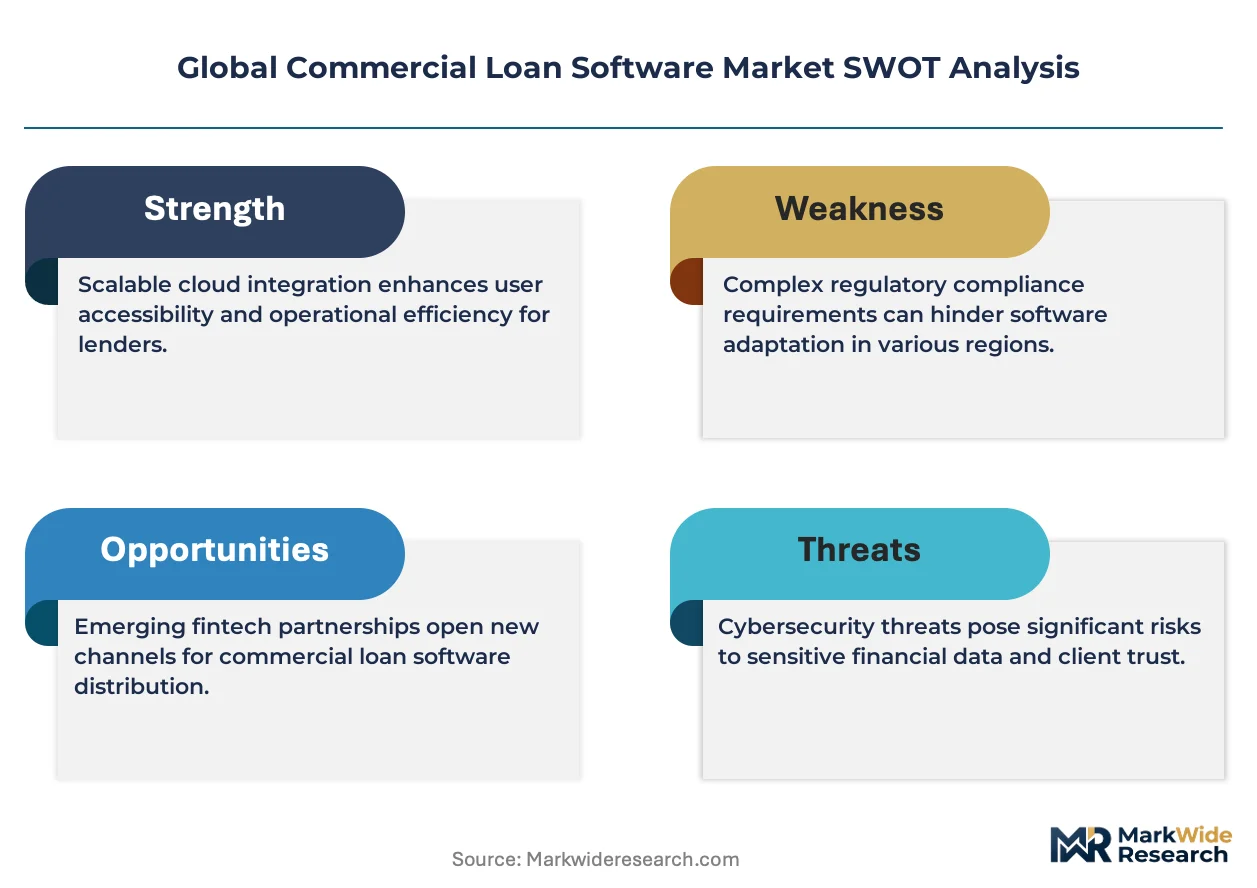
The US Office of the Comptroller of the Currency and the Federal Reserve jointly shape vendor requirements through cybersecurity resilience guidelines and third-party risk management mandates. In Europe, the Digital Operational Resilience Act and GDPR data-handling standards constrain how SaaS providers architect cross-border loan servicing platforms. Stakeholders must weigh the trade-off between vendor consolidation for operational simplicity and multi-provider strategies that limit systemic dependency on any single platform's roadmap.
Market Dynamics
The commercial loan software sector is compressing around a single structural force: the mandatory migration from on-premise legacy cores to API-orchestrated cloud architectures, driven by Basel III capital adequacy enforcement and open banking mandates across multiple jurisdictions.
Growth Catalysts
- Basel III Capital Requirements:Tier-one and regional banks in the United States face binding capital adequacy ratios that automated underwriting platforms solve through real-time risk-weighting calculations and dynamic provisioning models.
- Open Banking API Mandates:The European Union's PSD2 and subsequent open finance frameworks compel institutions to expose loan servicing data through standardized interfaces, creating procurement urgency for middleware-integrated software stacks.
- Synthetic Identity Fraud Proliferation:Document forgery and synthetic borrower profiles are forcing commercial lenders to deploy AI-powered identity verification modules as non-negotiable components of origination workflows.
Market Restraints
- Data Residency Compliance Costs:Strict localization requirements in Germany, France, and Switzerland block pure SaaS deployment for cross-border loan servicing, forcing hybrid architectures that double infrastructure expenditure.
- Core Banking Vendor Concentration:Three legacy core providers control the integration layer for over sixty percent of United States commercial banks, extracting premium fees for API access and roadmap prioritization.
- Alternative Credit Scoring Substitution:Fintech lenders bypass traditional loan origination software entirely by deploying proprietary machine-learning models trained on non-traditional data streams, eroding addressable market for conventional platforms.
Strategic Opportunities
- Underpenetrated Indian Commercial Banking:The Reserve Bank of India's phased implementation of scale-based regulation for non-banking financial companies creates a compliance-driven procurement window for automated credit monitoring systems.
- Embedded Finance Convergence:The intersection of banking-as-a-service platforms with commercial loan APIs enables software vendors to white-label origination engines for logistics marketplaces and supply chain finance networks.
- Digital Operational Resilience Act Tailwind:The European Union's DORA mandates operational resilience testing for critical ICT third-party providers, positioning certified loan software vendors as pre-qualified procurement options for supervised entities.
Industry Challenges
- Legacy Core Integration Complexity:Decades-old COBOL-based deposit systems at United States community banks resist real-time API connectivity, requiring expensive middleware layers that erode SaaS margin structures.
- Regulatory Certification Timelines:SOC 2 Type II and ISO 27001 audits for cloud-native platforms stretch twelve to eighteen months, delaying market entry for new entrants and freezing competitive dynamics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Loan Software Market |
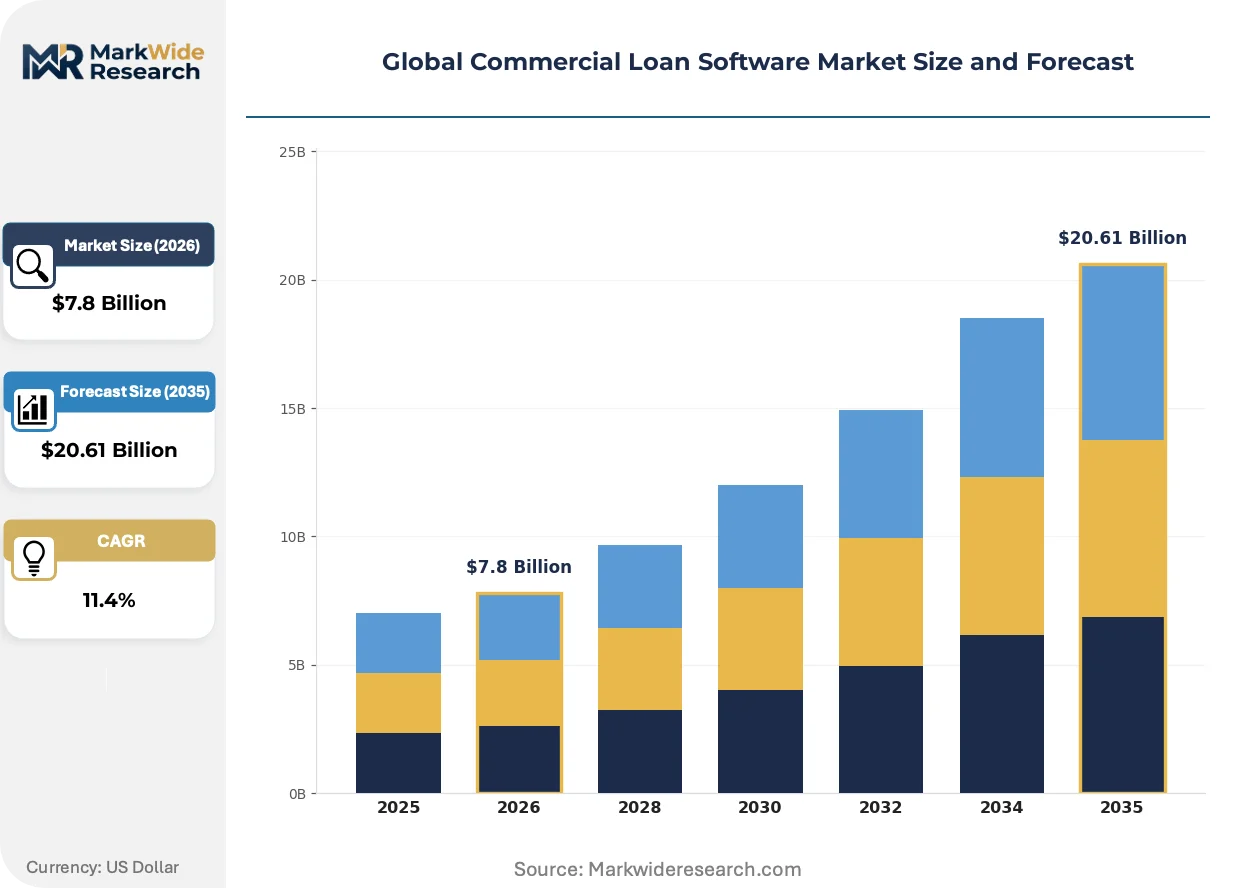
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Application: Risk Assessment, Loan Origination, Portfolio Management, Compliance Monitoring, Customer Onboarding End User: Commercial Banks, Credit Unions, FinTech Firms, Leasing Companies, Mortgage Lenders Solution Type: Loan Management, Credit Scoring, Document Management, Analytics & Reporting, Fraud Detection |
| Companies Covered | FIS, nCino, Finastra, Fiserv, ICE Mortgage Technology, Black Knight, Calyx Software, LoanPro, Linedata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Loan Software Market Shifts & Advancements
Artificial intelligence is penetrating every stage of the commercial credit lifecycle, compressing decision timelines from weeks to hours while simultaneously raising the bar for explainability and bias auditing across jurisdictions with divergent regulatory philosophies.
Embedded machine-learning risk engines are consolidating the competitive landscape for mid-market loan origination. United States regional banks and credit unions are adopting these tools at accelerated procurement cycles, displacing rules-based scoring modules that dominated the 2010s. The technology is consolidating vendor positions around platforms that can demonstrate regulatory-compliant model interpretability under the Federal Reserve's SR 11-7 guidance.
The European Union's Digital Operational Resilience Act is reshaping vendor qualification criteria for cross-border loan servicing. Institutions must now demonstrate end-to-end ICT risk management across their entire third-party ecosystem, including software providers. European commercial banks are responding by concentrating procurement on vendors with pre-certified DORA compliance frameworks, narrowing the competitive field.
Subscription pricing for loan origination modules is displacing perpetual license models in mid-market buyer segments. United States community banks and agricultural credit cooperatives are leading this transition, trading upfront capital expenditure for operational expenditure aligned to loan volume throughput. This shift is most visible in the agricultural lending vertical, where seasonal origination spikes favor elastic capacity models over fixed infrastructure investments.
Global Commercial Loan Software Market Segmentation
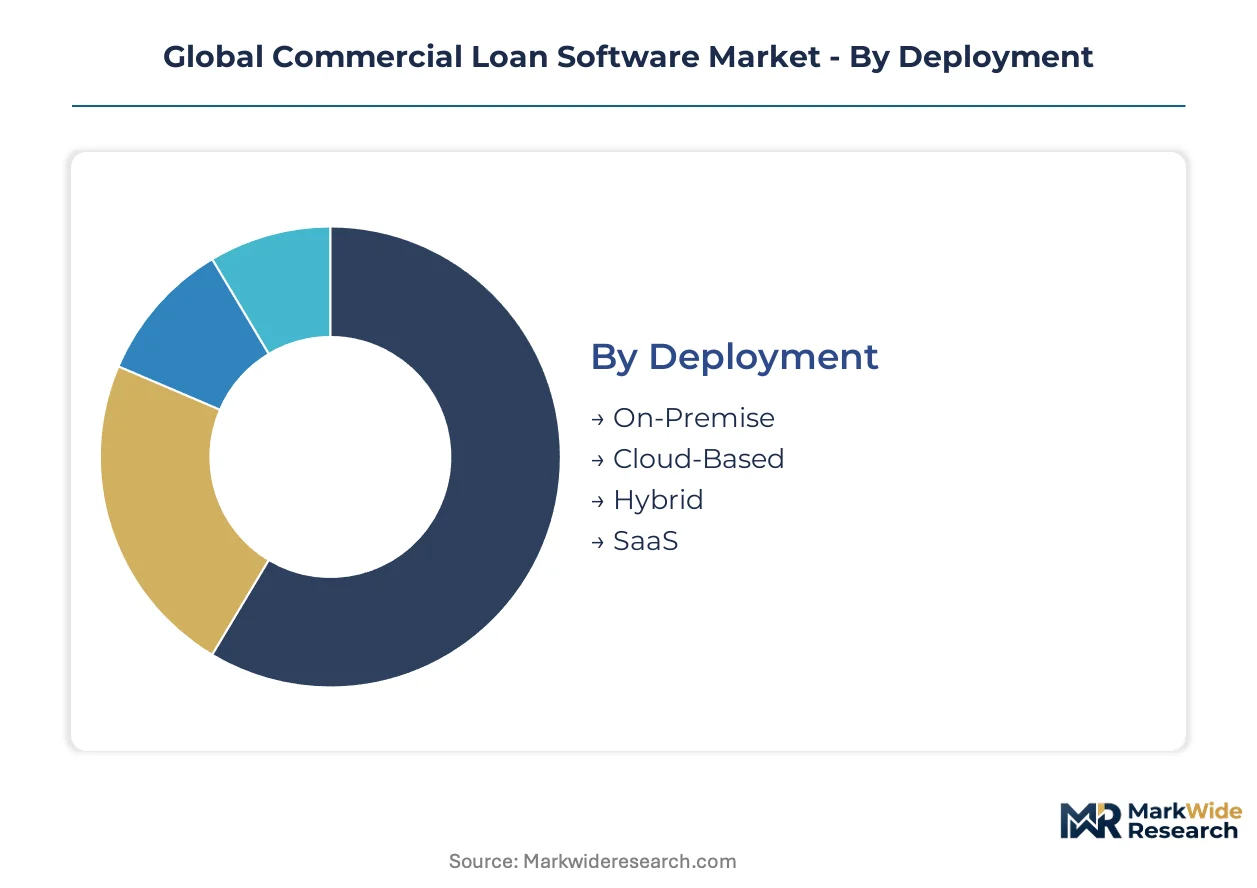
Commercial loan software procurement follows distinct patterns across deployment modes, functional applications, and institutional buyer profiles. Each segmentation axis reveals where capital concentrates and which integration architectures dominate vendor selection criteria.
Deployment:
Cloud-native platforms embed directly into bank cores through API layers, while on-premise installations persist where data sovereignty mandates block external hosting.
- On-Premise:Legacy installations running within bank-owned data centers maintain dominance among tier-one institutions with dedicated security operations centers. Demand concentrates in Germany and Switzerland, where federal banking supervisors enforce strict data localization for commercial credit records.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for seasonal origination spikes without capital infrastructure commitments. United States community banks and agricultural credit cooperatives drive procurement, trading upfront license fees for consumption-based operational expenditure aligned to loan throughput.
- Hybrid:Split architectures isolate sensitive risk calculations on-premise while pushing customer-facing workflows to cloud edge nodes. French and Italian regional banks favor this model to satisfy GDPR data residency requirements without sacrificing digital onboarding velocity.
- SaaS:Fully managed subscription platforms abstract all infrastructure maintenance, appealing to mid-market lenders without internal IT depth. Indian non-banking financial companies are accelerating adoption as the Reserve Bank of India's scale-based regulation tightens technology compliance thresholds.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Application:
Functional modules map to distinct stages of the credit lifecycle, with origination commanding the deepest investment pools and fraud detection gaining priority amid synthetic identity proliferation.
- Risk Assessment:Real-time scoring engines ingest alternative data streams for dynamic borrower evaluation. Tier-one United States banks embed these tools within automated underwriting platforms to satisfy Basel III capital adequacy calculations.
- Loan Origination:End-to-end workflow automation spanning application intake through documentation and approval routing. This segment captures the largest procurement budgets across North American regional banks modernizing legacy COBOL-based systems.
- Portfolio Management:Concentration tracking and covenant monitoring tools for existing commercial exposures. European banks under ECB supervision deploy these modules for stress testing and dynamic provisioning.
- Compliance Monitoring:Automated regulatory reporting and audit trail generation. German and French institutions prioritize these capabilities to satisfy Digital Operational Resilience Act documentation requirements.
- Customer Onboarding:Digital identity verification and KYC workflow orchestration. Synthetic identity fraud schemes are forcing United States lenders to upgrade these modules with AI-powered document authentication.
Procurement intensity clusters around Loan Origination; Compliance Monitoring is climbing the fastest as supervisory frameworks tighten.
End User:
Institutional buyer profiles determine integration complexity, with commercial banks demanding full-suite platforms and FinTech firms seeking lightweight API-first components.
- Commercial Banks:Full-service institutions requiring comprehensive origination-to-servicing platforms with core banking integration. United States regional banks represent the largest addressable pool, pressured by Office of the Comptroller of the Currency modernization mandates.
- Credit Unions:Member-owned cooperatives with leaner technology budgets favoring configurable SaaS solutions. Agricultural credit cooperatives in the United States Midwest drive seasonal demand spikes favoring elastic capacity models.
- FinTech Firms:Technology-native lenders deploying proprietary machine-learning models that bypass conventional origination software entirely. These players erode addressable market for traditional platforms through alternative-data credit scoring.
- Leasing Companies:Equipment finance specialists requiring asset-level tracking and residual value monitoring. European automotive leasing arms embed white-labeled origination engines through banking-as-a-service partnerships.
- Mortgage Lenders:Residential-focused originators with distinct documentation and secondary market integration requirements. United States mortgage banks prioritize GSE compliance modules for Fannie Mae and Freddie Mac delivery.
Commercial Banks anchor procurement volume; FinTech Firms are gaining share fastest through embedded finance convergence.
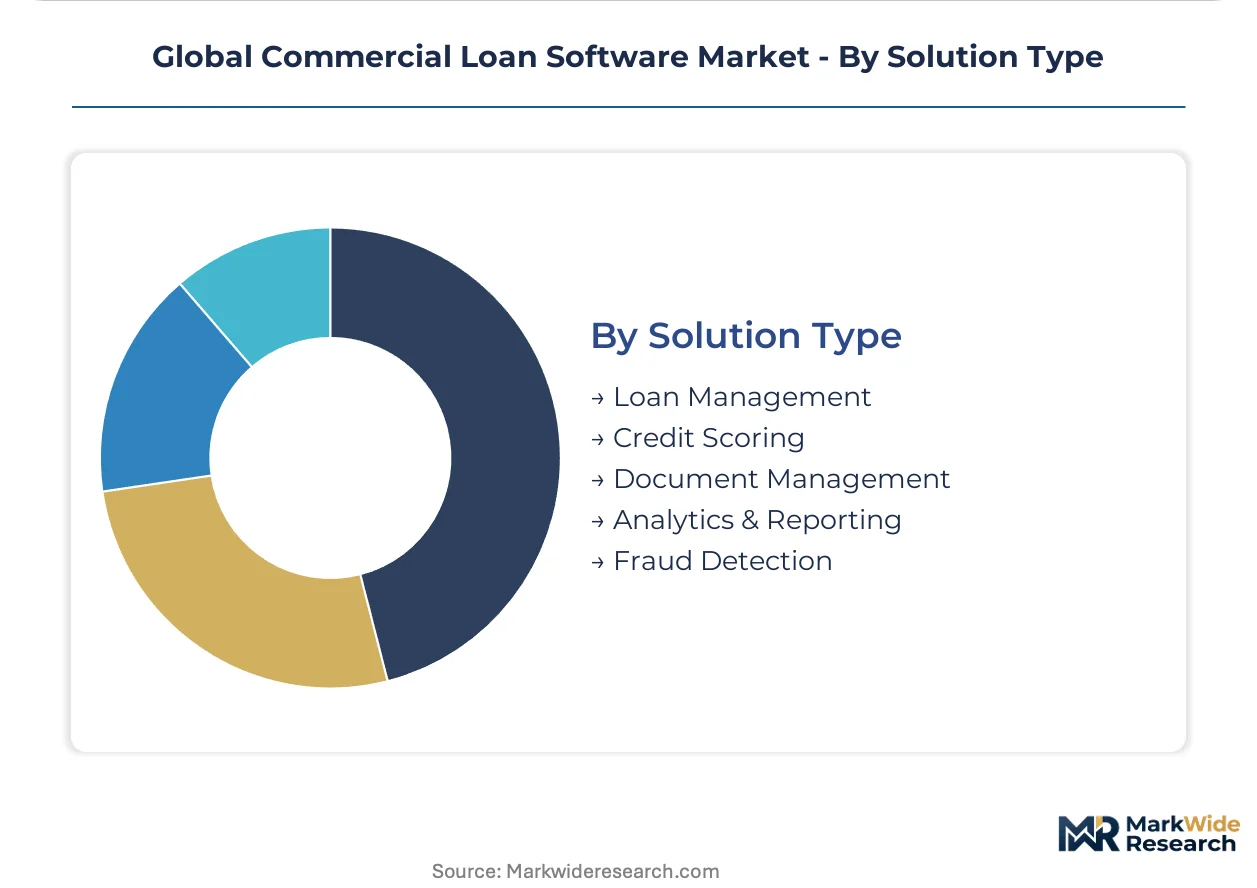
Solution Type:
Standalone point solutions compete against integrated suites, with specialized vendors extracting premium pricing for advanced analytics and alternative-data credit scoring.
- Loan Management:Core servicing platforms handling disbursement, repayment scheduling, and covenant tracking. United States community banks dominate installations, modernizing decades-old systems to enable real-time API connectivity.
- Credit Scoring:Statistical models for borrower default probability estimation. Specialized vendors command premium pricing for machine-learning engines trained on non-traditional data streams, displacing rules-based FICO-centric modules.
- Document Management:Digital vaulting and automated extraction for financial statement spreading and collateral verification. European banks under GDPR constraints favor these tools for audit-ready data lineage.
- Analytics & Reporting:Business intelligence layers for portfolio performance visualization and regulatory submission preparation. Basel III and DORA mandates are expanding mandatory reporting scope across jurisdictions.
- Fraud Detection:AI-powered identity verification and transaction anomaly detection. Synthetic identity schemes and document forgery are forcing commercial lenders to deploy these modules as non-negotiable origination components.
Revenue concentration sits with Loan Management; Fraud Detection shows the steepest expansion trajectory as identity threats multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors the global commercial loan software market through its concentration of tier-one bank headquarters and venture capital flows into fintech infrastructure. The metropolitan corridor generates disproportionate procurement volume for cloud-native origination platforms. Regulatory complexity across multiple jurisdictions drives cross-border vendor selection criteria.
United States
Regional banks in the Southeast and Midwest are accelerating automated underwriting adoption to satisfy Office of the Comptroller of the Currency modernization mandates. The Federal Reserve's SR 11-7 guidance on model risk management shapes vendor qualification requirements. Dallas and Atlanta host expanding technology operations for core banking modernization projects.
Germany
Sparkassen and cooperative banks drive demand for hybrid deployment models that satisfy federal data localization requirements. BaFin enforcement of GDPR data-handling standards constrains pure SaaS architectures for cross-border loan servicing. Frankfurt's financial district concentrates procurement decision-making for pan-European credit platforms.
United Kingdom
Challenger banks and building societies prioritize API-first origination stacks to compete with incumbent lenders. The Financial Conduct Authority's operational resilience expectations accelerate third-party vendor consolidation. London's fintech corridor hosts embedded finance partnerships linking loan software to banking-as-a-service infrastructure.
India
Non-banking financial companies in Mumbai and Bangalore are procuring automated credit monitoring systems ahead of Reserve Bank of India scale-based regulation deadlines. The central bank's phased compliance timeline creates concentrated procurement windows through 2026. Hyderabad's technology cluster supplies indigenous risk engine development for mid-market lenders.
Japan
Regional banks facing negative interest rate pressure are digitizing legacy commercial lending operations to reduce cost-to-income ratios. METI guidance on SME financing digitization shapes procurement priorities for origination workflow automation. Tokyo's financial district anchors vendor relationship management for megabank technology modernization.
Global Commercial Loan Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and regulatory certification breadth. The market structures around three tiers: legacy core-embedded suites commanding sustained renewal rates, Salesforce-native platforms capturing mid-market velocity, and API-first specialists extracting fees for interoperability layers. Consolidation pressure intensifies as Basel III and DORA compliance costs favor scaled vendors with pre-certified frameworks. Strategic moves concentrate on vertical capability acquisition and geographic regulatory certification.
Within the legacy-integrated tier, FIS and Fiserv occupy positions anchored to decades-old core banking relationships. nCino and Finastra exemplify the platform-native archetype, with the former representing Salesforce-ecosystem specialization and the latter occupying the open API interoperability niche. These three names surface repeatedly in procurement shortlists across North American and European commercial banking segments.
| Leading Market Players |
|---|
| FIS |
| nCino |
| Finastra |
| Fiserv |
| ICE Mortgage Technology |
| Black Knight |
| Calyx Software |
| LoanPro |
| Linedata |
| Others |
Supply & Pricing Matrix
Cloud infrastructure pricing indices from hyperscale providers cascade through commercial loan software supply chains, compressing margins for vendors tethered to fixed-cost data center operations while enabling elastic pricing tiers for API-native platforms serving mid-market banks.
Pricing Analysis
Outcome-based pricing tied to loan throughput volumes anchors vendor revenue models, with tiered SaaS subscriptions displacing perpetual licenses across United States community banks and agricultural credit cooperatives. Price differentiation separates Basel III-certified enterprise suites from lightweight cloud alternatives, with the former commanding premiums for real-time risk-weighting capabilities. Pricing pressure stems from alternative-data credit scoring fintechs bypassing traditional origination software entirely. Tier-one commercial banks exhibit lowest price sensitivity due to regulatory compliance mandates, while credit unions and non-banking financial companies negotiate aggressively on per-seat costs.
Supply Chain Analysis
Specialized compute hardware supply rests on Taiwan semiconductor foundries, United States hyperscale cloud operators, and German precision engineering firms for on-premise server deployments. Core dependencies include GPU accelerators for AI-powered fraud detection, encrypted storage arrays for GDPR-compliant data residency, and API gateway middleware from Salesforce and Microsoft ecosystems. Single-source vulnerability concentrates in Taiwan's advanced node fabrication for risk-engine training hardware. Distribution runs through direct enterprise sales teams for tier-one banks and channel partners serving mid-market regional institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Basel III compliance certification costs are forcing consolidation among sub-scale vendors unable to sustain eighteen-month SOC 2 Type II audit cycles, creating acquisition opportunities for scaled platforms with pre-certified frameworks.
For Market Incumbents: Deploy regulatory certification leverage by accelerating DORA pre-certification timelines for European expansion, insulating renewal rates against open-API specialists like Finastra. Acquire alternative-data scoring boutiques to neutralize fintech substitution threats in the mid-market. Deepen core banking integration moats through exclusive API access agreements with FIS and Fiserv legacy systems.
For New Entrants and Emerging Players: Banking-as-a-service API routes offer the lowest friction entry path, embedding white-labeled origination engines into logistics marketplaces and supply chain finance networks. Target Indian non-banking financial companies ahead of Reserve Bank of India scale-based regulation deadlines, where compliance-driven procurement windows concentrate through 2026. Lead with consumption-based pricing to displace fixed-license incumbents in agricultural credit cooperatives with seasonal origination spikes.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid-deployment specialists with German data localization capabilities and pre-existing BaFin relationships. Long-term viability hinges on vertical integration into AI risk engines rather than workflow automation alone. Monitor synthetic identity fraud incident rates as the inflection signal for fraud-detection module valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Salesforce-native architectures capture mid-market velocity through embedded CRM workflows. |
| Regulatory Certification Investment | DORA pre-certification narrows vendor shortlists for European commercial bank procurement. |
| Acquisition of Specialist Firm | Alternative-data scoring boutiques neutralize fintech substitution in credit decisioning. |
| Geographic Expansion | Indian non-banking financial companies present compliance-driven procurement concentration. |
| Strategic Partnership | Banking-as-a-service alliances embed origination engines in supply chain finance networks. |
Research Methodology
Multi-period observation of vendor procurement cycles, regulatory certification timelines, and cloud migration patterns anchored the trend analysis, supplemented by interviews with chief technology officers at regional banks, integration specialists at core banking vendors, compliance officers navigating Basel III implementation, and SaaS procurement leads at agricultural credit cooperatives. Secondary validation drew from SEC 10-K filings of publicly traded software vendors, European Banking Authority supervisory disclosures, Reserve Bank of India circulars on scale-based regulation, and hyperscaler capex disclosures revealing cloud infrastructure investment trajectories. Bottom-up segmentation modeling triangulated against top-down market sizing from banking technology expenditure surveys.
Segment-weighting across deployment modes, functional applications, and institutional buyer profiles structured the analytical framework, with loan origination and fraud detection modules receiving distinct growth coefficients. Deployment architecture splits—on-premise, cloud-native, hybrid, and SaaS—were modeled separately given divergent infrastructure cost structures. CAGRs were derived from trajectory fitting to observed procurement velocity across the projection horizon, incorporating regulatory deadline clustering and core banking modernization cycle phasing as industry-specific forecast inputs.
The model holds under sustained regulatory enforcement of Basel III capital adequacy and DORA operational resilience standards; deviation in central bank rate cycles or open banking mandate delays would shift procurement timing. Forecasts reflect these boundary assumptions without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Micro Lending Market