
 Canada Mortgage/Loan Brokers Market | 2026-2036
Canada Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Mortgage/Loan Brokers Market Analysis
First-time buyers is collapsing toward online and franchise broker channels as rate volatility compresses traditional bank loyalty. Ratehub.ca leverages proprietary rate-comparison engines to capture digitally native borrowers shopping across multiple lenders simultaneously. Dominion Lending Centres anchors its position through a coast-to-coast agent network that sustains face-to-face advisory in high-transaction markets. True North Mortgage differentiates via direct-lender relationships that compress origination spreads for rate-sensitive refinancers.
A mortgage or loan broker functions as an intermediary licensed to arrange financing between borrowers and lenders, operating under provincial regulatory frameworks that mandate errors-and-omissions insurance and continuing education credits. The broker's core commercial purpose is to reduce search costs and improve rate discovery for borrowers while generating origination fees or lender-paid commissions. Franchise and independent broker types currently occupy the largest share of transaction flow, though online broker platforms represent the fastest-growing channel as automated underwriting APIs shrink decision timelines. Fixed-rate products dominate loan type volumes during periods of policy-rate uncertainty, while home equity lines concentrate margin pools among self-employed client segments seeking flexible draw structures.
OSFI's Guideline B-20 mortgage underwriting standards and provincial regulator licensing regimes through FSRA Ontario and BCFSA directly shape broker market access, capital reserve expectations, and disclosure obligations for borrower-lender fee structures. The Financial Consumer Agency of Canada reinforces fair-lending oversight that brokers must navigate in advertising and compensation transparency. Stakeholders should monitor how open-banking implementation timelines alter data-sharing protocols between brokers and fintech-enabled lenders.
Market Dynamics
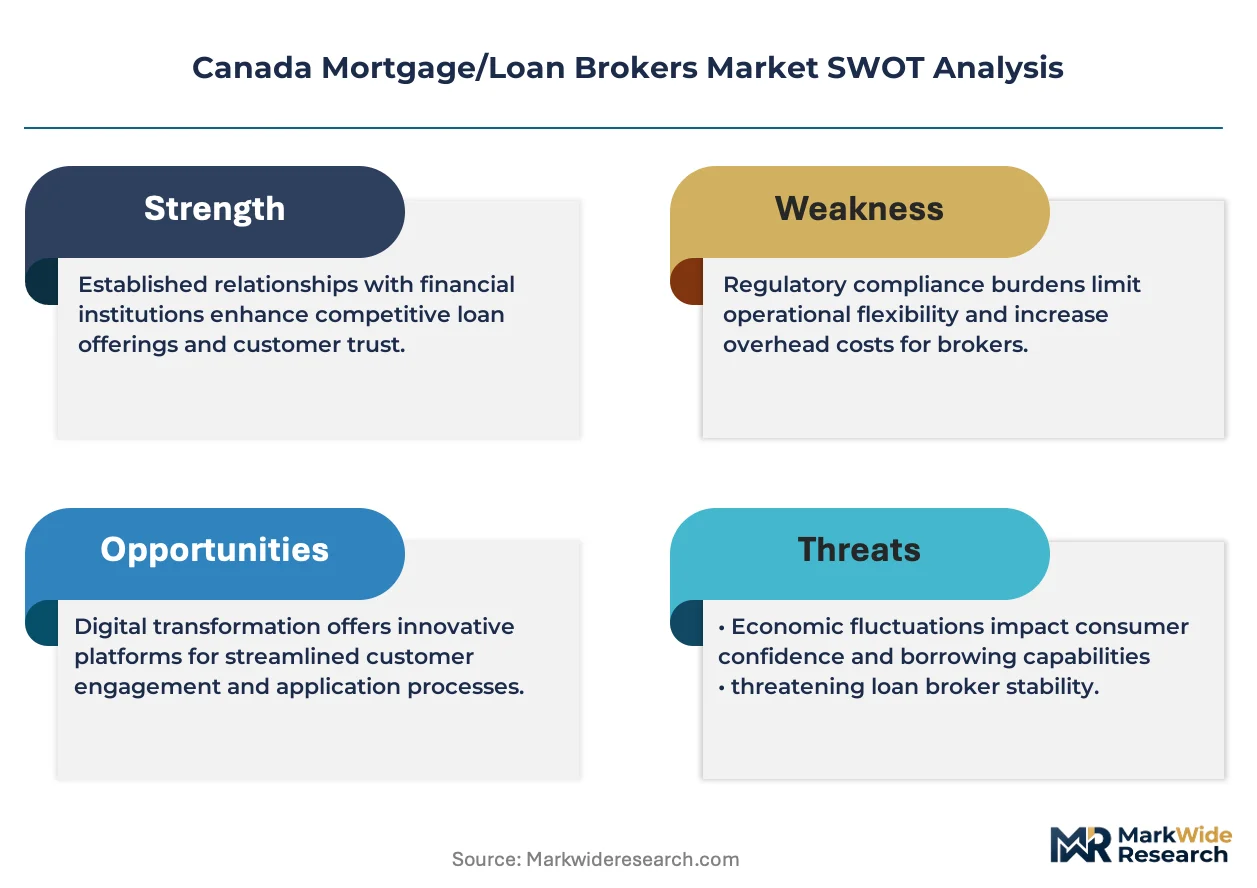
The Bank of Canada's interest rate regime is compressing refinancing volumes while accelerating first-time buyer migration toward digital rate-comparison platforms. This monetary policy pressure is fragmenting traditional bank loyalty and elevating broker-assisted shopping for competitive mortgage terms.
Growth Catalysts
- OSFI Guideline B-20:Stricter mortgage underwriting standards are expanding broker relevance as borrowers seek guidance navigating qualification complexity across multiple lenders.
- Automated Underwriting APIs:Real-time decision engines are shrinking origination timelines and attracting digitally native borrowers to online broker channels.
- Ontario's Greater Toronto Area:Severe housing affordability stress concentrates demand for broker-assisted rate discovery among stretched household budgets.
Market Restraints
- Interest Rate Volatility:Unpredictable Bank of Canada policy movements are destabilizing refinancing pipelines and compressing broker commission predictability.
- FSRA Licensing Burden:Ontario's continuing education mandates and errors-and-omissions insurance requirements raise fixed operating costs for smaller independent brokers.
- Direct-Lender Disintermediation:Monoline lenders building proprietary digital origination platforms threaten to bypass broker intermediation entirely.
Strategic Opportunities
- Open Banking Implementation:Pending data-sharing protocols between brokers and fintech-enabled lenders promise streamlined income verification and faster approvals.
- Self-Employed HELOC Segments:Flexible home equity draw structures remain underpenetrated by traditional banks, creating margin pool capture for specialized brokers.
- British Columbia Lower Mainland:Persistent affordability stress in Vancouver's orbit sustains broker demand for alternative lender placement.
Industry Challenges
- API Integration Complexity:Legacy broker back-office systems require costly reconfiguration to connect with modern lender decision engines.
- Compensation Disclosure Compliance:FCAC fair-lending oversight demands granular fee transparency that conflicts with legacy commission opacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Mortgage/Loan Brokers Market |
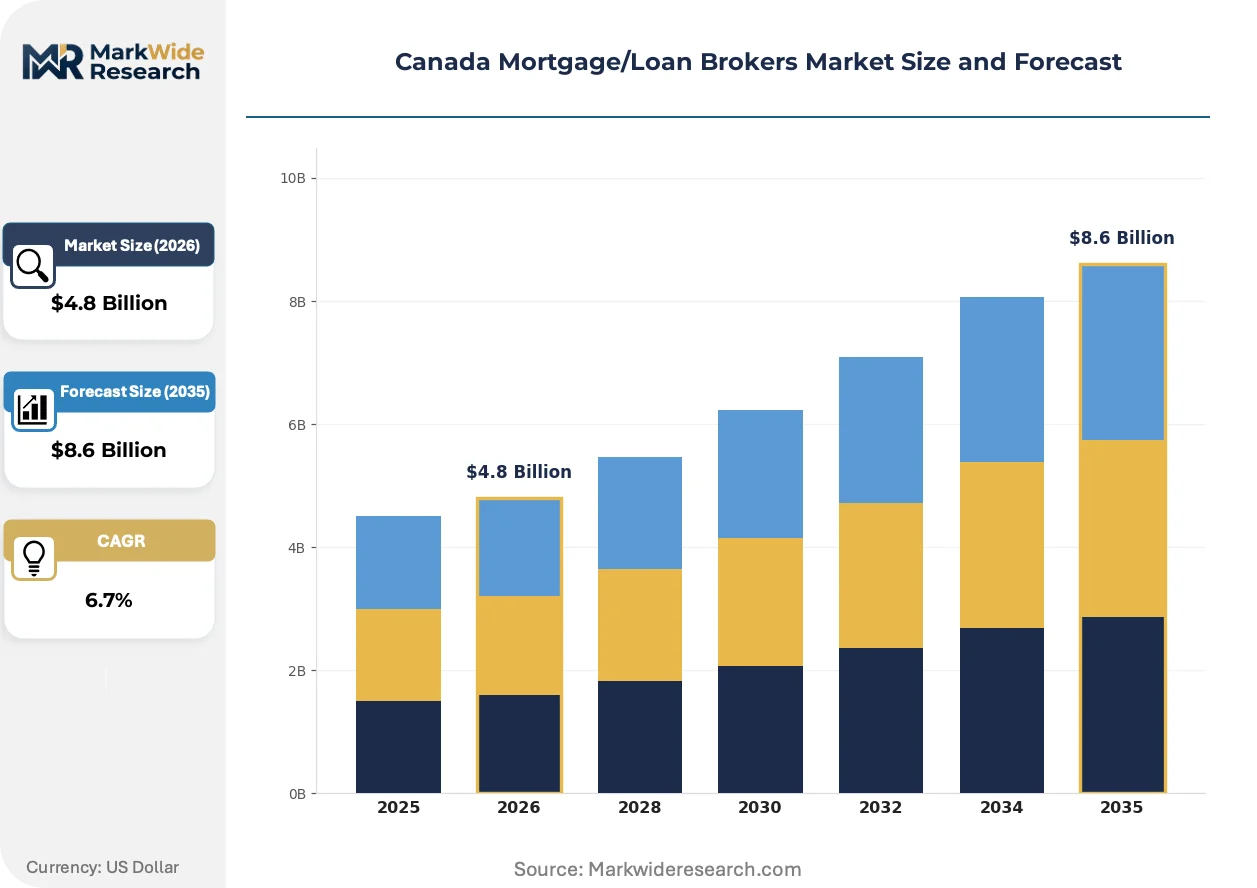
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Broker Type: Independent, Franchise, Bank-owned, Online Loan Type: Fixed-rate, Variable-rate, Home Equity Line, FHA Client Type: First-time Buyers, Investors, Refinancers, Self-employed Product Offering: Mortgage, Personal Loan, Commercial Mortgage, Line of Credit |
| Companies Covered | Ratehub.ca, Verico Financial, Dominion Lending Centres, True North Mortgage, Invis Mortgage Intelligence, Mortgage Alliance Company of Canada, Centum Financial Group, nesto Inc., TMG The Mortgage Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Mortgage/Loan Brokers Market Emerging Trajectories
Digital origination infrastructure is supplanting branch-based mortgage sales across Canadian broker channels. Rate-comparison engines and automated underwriting are compressing decision timelines while reshaping borrower expectations for instant pre-approval.
Application programming interfaces connecting broker platforms to lender decision engines are supplanting manual document submission and phone-based rate shopping. First-time buyers in Ontario and British Columbia are adopting these tools fastest, compressing the traditional 48-hour pre-approval window to under 15 minutes. This acceleration is eroding bank branch foot traffic and elevating digital-native broker brands.
FSRA Ontario and BCFSA are tightening advertising disclosure requirements for borrower-lender fee structures. Brokers must now display total cost of borrowing comparisons across all marketing channels. The regulatory friction falls heaviest on franchise networks with distributed agent bases struggling to standardize compliance across hundreds of individual practitioners.
Rate-sensitive refinancers are compressing their lender switching cycles from multi-year relationships to transaction-by-transaction shopping. Digital broker platforms capture this behavior through alert systems triggering borrower contact when rate spreads exceed threshold levels. This pattern concentrates in the Greater Toronto Area where household leverage ratios amplify basis-point sensitivity.
Canada Mortgage/Loan Brokers Market Segmentation
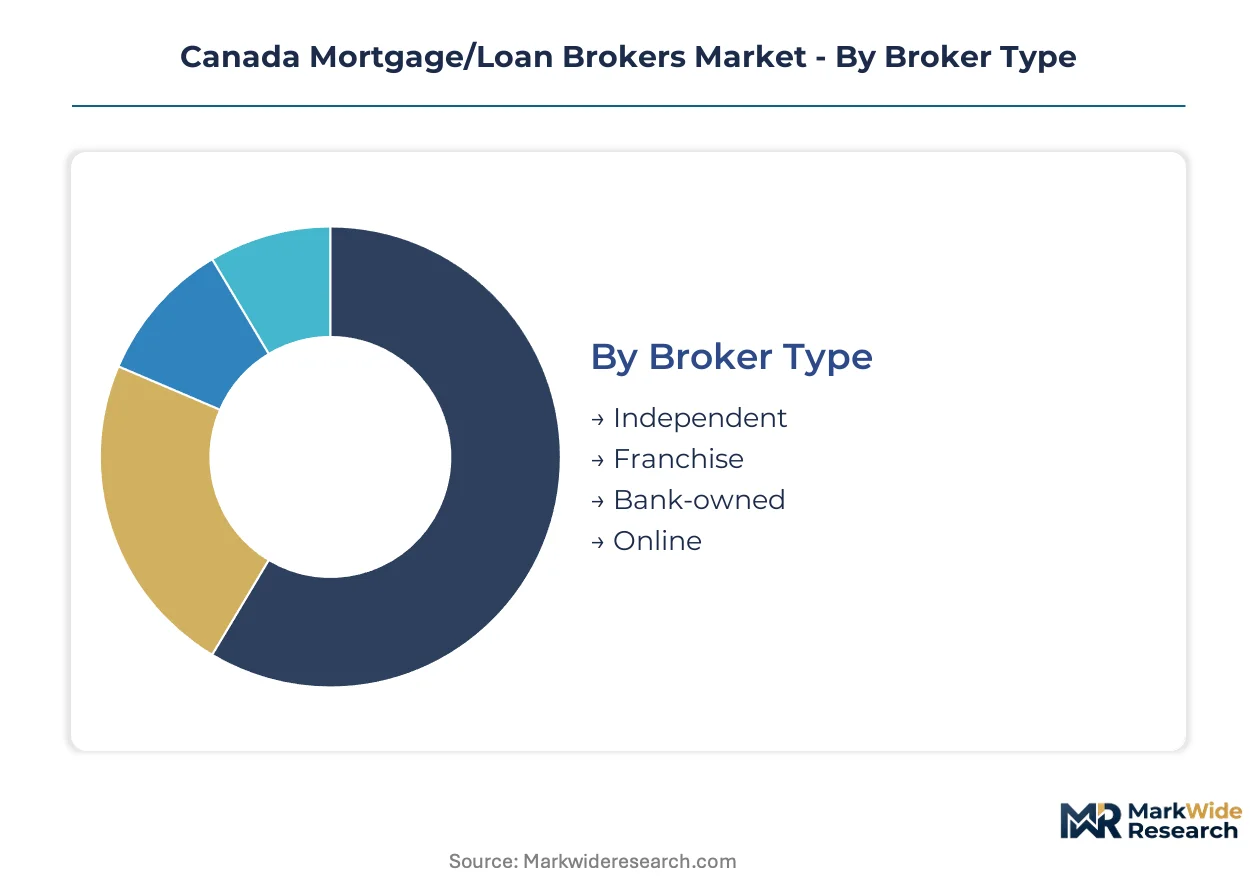
Segmentation reveals how broker business models, loan structures, and client profiles concentrate revenue across distinct operational footprints. Channel strategy varies sharply by segment, with digital platforms capturing rate-sensitive shoppers while franchise networks retain face-to-face advisory relationships.
Broker Type:
Channel economics diverge sharply across these four models, with commission structures and customer acquisition costs determining viable scale thresholds.
- Independent:Solo practitioners or small partnerships operating under personal brand with lower overhead but limited lender panel access. Demand clusters in secondary Ontario markets and Atlantic Canada where relationship-based referral networks sustain volume without national marketing spend.
- Franchise:Agent networks operating under centralized brands like Dominion Lending Centres or Mortgage Alliance with shared compliance infrastructure and pooled marketing. These dominate transaction flow in Greater Toronto Area and Lower Mainland corridors where scale economies justify franchise fees.
- Bank-owned:Captive broker channels tied to single lender balance sheets, offering product exclusivity in exchange for restricted rate shopping. Concentrated among refinancers seeking streamlined documentation through existing banking relationships.
- Online:Digital-native platforms leveraging API-connected rate engines and automated pre-approval workflows. Expanding most quickly among first-time buyers in urban Ontario and British Columbia where mobile-first shopping behaviors predominate.
Franchise networks dominate installed base. Online is where expansion concentrates.
Loan Type:
Product mix shifts with Bank of Canada policy cycles, with fixed-rate preference spiking during rate volatility periods.
- Fixed-rate:Principal-and-interest loans with locked rates over 1-5 year terms, insulating borrowers from policy-rate movements. Demand surges among risk-averse first-time buyers in high-leverage markets like Toronto and Vancouver when rate uncertainty peaks.
- Variable-rate:Floating-rate products tied to prime rate with conversion options, attracting borrowers betting on rate decline trajectories. Concentrates among sophisticated investors and refinancers with liquidity cushions to absorb payment shock.
- Home Equity Line:Secured revolving credit secured against residential property, offering flexible draw structures. Self-employed borrowers in British Columbia and Ontario leverage these for working capital smoothing.
- FHA:Government-backed mortgages with elevated default insurance and lower down payment thresholds, channeling marginal buyers toward alternative lenders outside big-six bank criteria.
Fixed-rate products anchor volume during uncertainty. Home Equity Lines generate premium margin capture.
Client Type:
Broker value proposition intensifies where qualification complexity or rate sensitivity exceeds borrower self-service capacity.
- First-time Buyers:Entry-level purchasers navigating down payment requirements, stress-test qualification, and lender comparison for the first time. Digital broker platforms capture this segment fastest in Ontario and British Columbia urban cores.
- Investors:Multiple-property owners seeking portfolio leverage optimization and rental income qualification strategies. Franchise brokers with specialized advisory capabilities retain this high-repeat segment.
- Refinancers:Existing homeowners pursuing rate reduction, term restructuring, or equity extraction. Rate volatility compresses this pipeline unpredictably, with digital alert systems capturing transaction-by-transaction shoppers.
- Self-employed:Non-salaried borrowers with variable income documentation requiring alternative lender placement. Specialized brokers extract premium commissions for navigating stated-income products outside bank standard criteria.
First-time buyers drive new customer acquisition. Self-employed borrowers yield highest per-transaction economics.
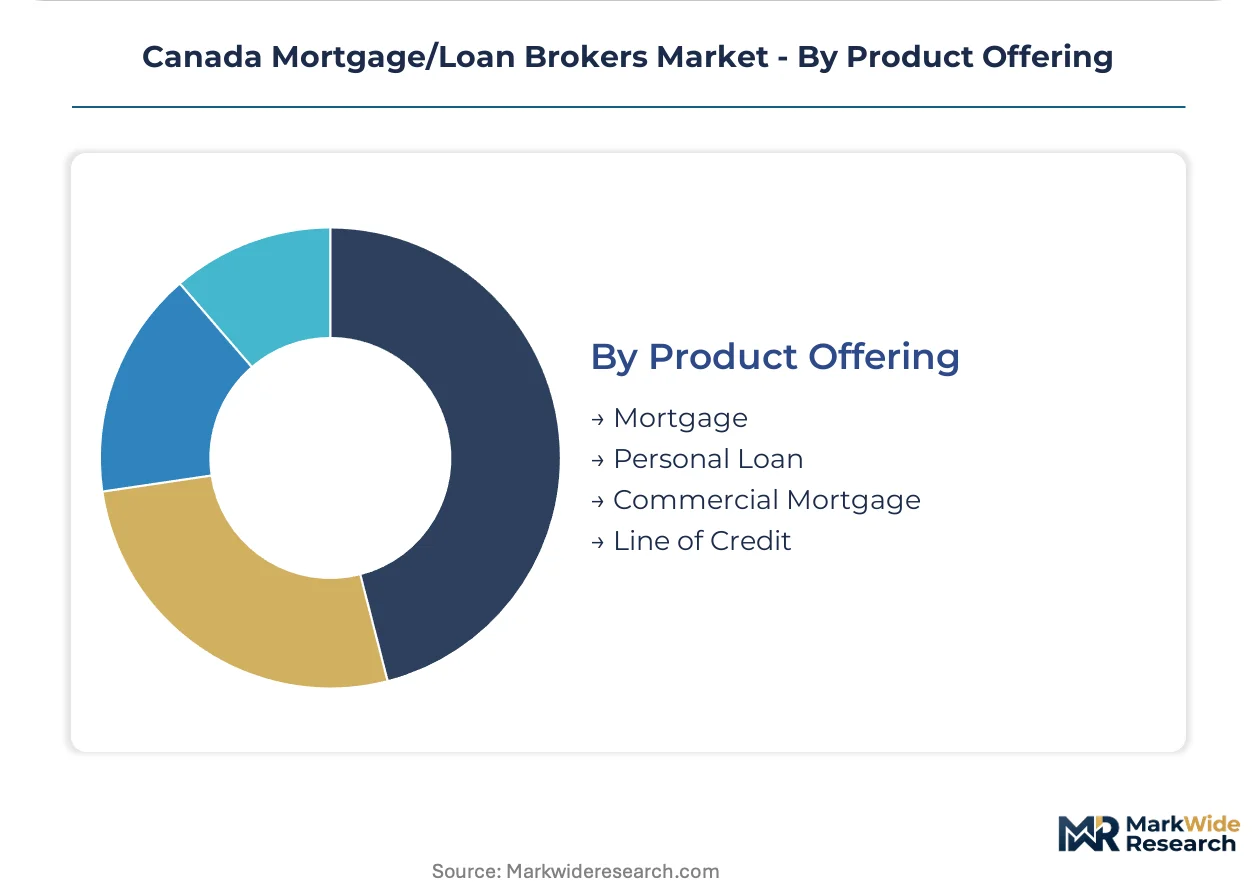
Product Offering:
Revenue per transaction escalates with product complexity, from standardized residential mortgages to structured commercial facilities.
- Mortgage:Residential purchase or refinance loans secured against owner-occupied or rental property, generating the baseline commission pool across all broker channels.
- Personal Loan:Unsecured or secured consumer credit for non-real estate purposes, typically cross-sold to existing mortgage clients.
- Commercial Mortgage:Income-producing property financing with elevated documentation requirements and extended timelines, commanding premium broker fees.
- Line of Credit:Revolving secured or unsecured facilities, often bundled with mortgage products for household liquidity management.
Residential mortgages dominate transaction counts. Commercial mortgages concentrate margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway corridor and CP/CN rail networks stitch together mortgage demand across provincial boundaries, with urban density along these arteries concentrating broker activity.
Ontario
The Greater Toronto Area generates the heaviest broker-assisted transaction volume as stress-test qualification complexity pushes buyers toward multi-lender shopping. FSRA Ontario mandates continuing education credits and errors-and-omissions coverage that elevate operating costs for independent practitioners. Ottawa-Gatineau corridor activity concentrates in franchise networks serving federal public sector employees with predictable income documentation.
British Columbia
Vancouver's Lower Mainland sustains premium commission pools where alternative lender placement dominates for non-conforming borrowers. BCFSA advertising disclosure rules require total-cost-of-borrowing comparisons across all marketing channels. Victoria and Kelowna sub-markets show accelerating digital platform adoption among tech-sector employees.
Alberta
Calgary-Edmonton corridor activity fluctuates with energy sector employment cycles that compress conventional bank qualification rates. Alberta Securities Commission oversight extends to mortgage investment corporation referrals that brokers coordinate. Fort McMurray and Grande Prairie sub-regions depend on specialized brokers navigating stated-income products for contract workers.
Quebec
Montreal's island market shows lower broker penetration than Ontario or British Columbia due to caisse populaire dominance in mortgage origination. Autorité des marchés financiers licensing requirements create distinct compliance architecture from English-Canada frameworks. Quebec City and Gatineau broker activity concentrates in franchise networks with bilingual advisory capacity.
Atlantic Canada
Halifax anchors regional broker volume as interprovincial migration from Ontario drives purchase demand. Nova Scotia's provincial regulator maintains reciprocity agreements that ease Ontario-licensed broker entry. Moncton and St. John's sub-markets sustain independent practitioners through relationship-based referral networks without national marketing spend.
Canada Mortgage/Loan Brokers Market Vendor Landscape
Listed leaders compete with private specialists across channel strategy, with public entities emphasizing technology infrastructure and private operators prioritizing agent network density. The market structures around three tiers: national franchise aggregators, digital-native platforms, and regional independents. Strategic archetypes include rate-comparison engines, coast-to-coast agent networks, and direct-lender relationship builders. Competitive moves concentrate on API integration investments and regulatory compliance automation.
Within the digital platform tier, Ratehub.ca and nesto Inc. exemplify automated underwriting adoption that compresses pre-approval timelines. Dominion Lending Centres anchors the franchise-network archetype through coast-to-coast agent density. True North Mortgage occupies a position emphasizing direct-lender relationships that narrow origination spreads for refinancers.
| Leading Market Players |
|---|
| Ratehub.ca |
| Verico Financial |
| Dominion Lending Centres |
| True North Mortgage |
| Invis Mortgage Intelligence |
| Mortgage Alliance Company of Canada |
| Centum Financial Group |
| nesto Inc. |
| TMG The Mortgage Group |
| Others |
Supply Flow & Price Mechanics
API-driven automated underwriting is displacing manual origination workflows, simultaneously redrawing broker platform economics and compressing commission spreads across Ontario and British Columbia corridors. This substitution concentrates pricing power with digital-native aggregators while fragmenting margin pools for legacy franchise networks dependent on face-to-face advisory.
Pricing Analysis
Volume-discount tiering structures dominate broker compensation, with lender-paid commissions scaling downward as origination volumes rise. Price differentiation hinges on borrower credit tier and loan-to-value ratio, with alternative lender placement commanding premium spreads. Pricing pressure intensifies as monoline lenders build proprietary digital channels that bypass broker intermediation. First-time buyers in Greater Toronto Area exhibit highest basis-point sensitivity, while self-employed refinancers tolerate elevated rates for flexible qualification.
Supply Chain Analysis
Inventory compression in lender decision engines has collapsed pre-approval timelines from 48 hours to under 15 minutes. Geographic supply concentration centers on Canada, with secondary dependencies on US-based credit bureau data and UK-sourced underwriting software. Raw material dependencies include proprietary rate-comparison algorithms, automated valuation models, and regulatory compliance APIs. Single-source vulnerability concentrates in cloud infrastructure providers hosting broker platform operations. Distribution runs through digital-native aggregators, franchise agent networks, and bank-owned captive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open banking implementation represents a high-growth disruption vector, with pending data-sharing protocols poised to reshape borrower verification economics and lender-broker data flows across Canadian mortgage origination.
For Market Incumbents: Secure API integration partnerships with fintech-enabled lenders before open banking protocols harden competitive moats. Defensive consolidation of compliance automation capabilities offsets FSRA and BCFSA disclosure burdens that disproportionately strain distributed franchise agent bases. Direct-lender relationship depth with monoline originators provides counterweight against disintermediation threats from proprietary digital platforms. For New Entrants and Emerging Players: Anchor in self-employed borrower segments where stated-income complexity sustains premium commission capture outside big-six bank standard criteria. White-space availability concentrates in commercial mortgage advisory and HELOC bundling for British Columbia tech-sector employees. Go-to-market positioning through mobile-first rate alert systems captures transaction-by-transaction refinancers in high-leverage Toronto and Vancouver corridors. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native platforms with automated underwriting infrastructure and scalable API architectures. Long-term viability over the coming decade hinges on regulatory technology investments that compress compliance costs per transaction. Acquisition target archetype emphasizes online broker platforms with proven lender panel diversification. Signal to monitor: open banking implementation timelines altering data-sharing economics between aggregators and fintech lenders.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Investment | Connects broker platforms to lender decision engines, collapsing origination timelines below 15 minutes. |
| Compliance Automation Deployment | Standardizes FSRA and BCFSA disclosure requirements across distributed franchise agent networks. |
| Direct-Lender Relationship Expansion | Narrows origination spreads for rate-sensitive refinancers through monoline originator partnerships. |
| Self-Employed Segment Specialization | Captures premium commissions for stated-income placement outside conventional bank criteria. |
| Open Banking Readiness Program | Positions platforms to leverage pending data-sharing protocols for streamlined income verification. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, lender origination disclosures, and provincial broker licensing databases. Primary interviews engaged mortgage brokerage principals, FSRA compliance officers, fintech platform engineers, and alternative lender underwriting heads. Secondary validation drew from Bank of Canada monetary policy reports, OSFI Guideline B-20 documentation, and Financial Consumer Agency of Canada fair-lending guidance. Bottom-up transaction volume estimates triangulate against top-down market sizing from aggregated lender commission disclosures.
Segmentation dimensions modeled span broker type, loan structure, client profile, and product complexity across the projection horizon. Broker channel analysis disaggregates franchise networks, independent practitioners, bank-owned captives, and digital-native platforms. Loan type segmentation captures fixed-rate, variable-rate, home equity line, and government-backed products. CAGRs derive from regression analysis of origination volume trends against interest rate regime shifts and housing affordability stress indicators. Forecast inputs incorporate Bank of Canada policy trajectory assumptions and open banking implementation pacing.
Decision-makers should treat outputs as directional under stable regulatory architecture and gradual open banking adoption; material acceleration or delay would warrant model refresh. Specific risks include interest rate volatility compressing refinancing pipelines, direct-lender disintermediation accelerating, and provincial licensing burdens escalating fixed costs for smaller independents. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Factoring Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Global Mortgage Lender Market