
 Corporate Lending Market | 2026-2036
Corporate Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Lending Market Outlook
Multi-source origination is hardening as the dominant credit sourcing pattern across corporate lending, replacing single-bank relationships with syndicated and platform-distributed structures. Kiavi leverages technology leadership in real estate-secured lending to sustain its position in asset-backed corporate credit. LendingClub competes through direct digital origination, while LQD Business Finance specializes in middle-market cash-flow loans with streamlined underwriting protocols.
Corporate lending encompasses the provision of debt capital to business entities through structured credit facilities governed by covenants, collateral requirements, and pricing benchmarks tied to reference rates such as SOFR or EURIBOR. Term loans anchor the product mix for capital-intensive manufacturing borrowers, while revolving credit facilities dominate working capital management across technology and healthcare verticals. Syndicated loans attract the largest transaction volumes among multinational firms seeking billion-dollar commitments, though bridge loans command premium pricing for acquisition financing timelines.
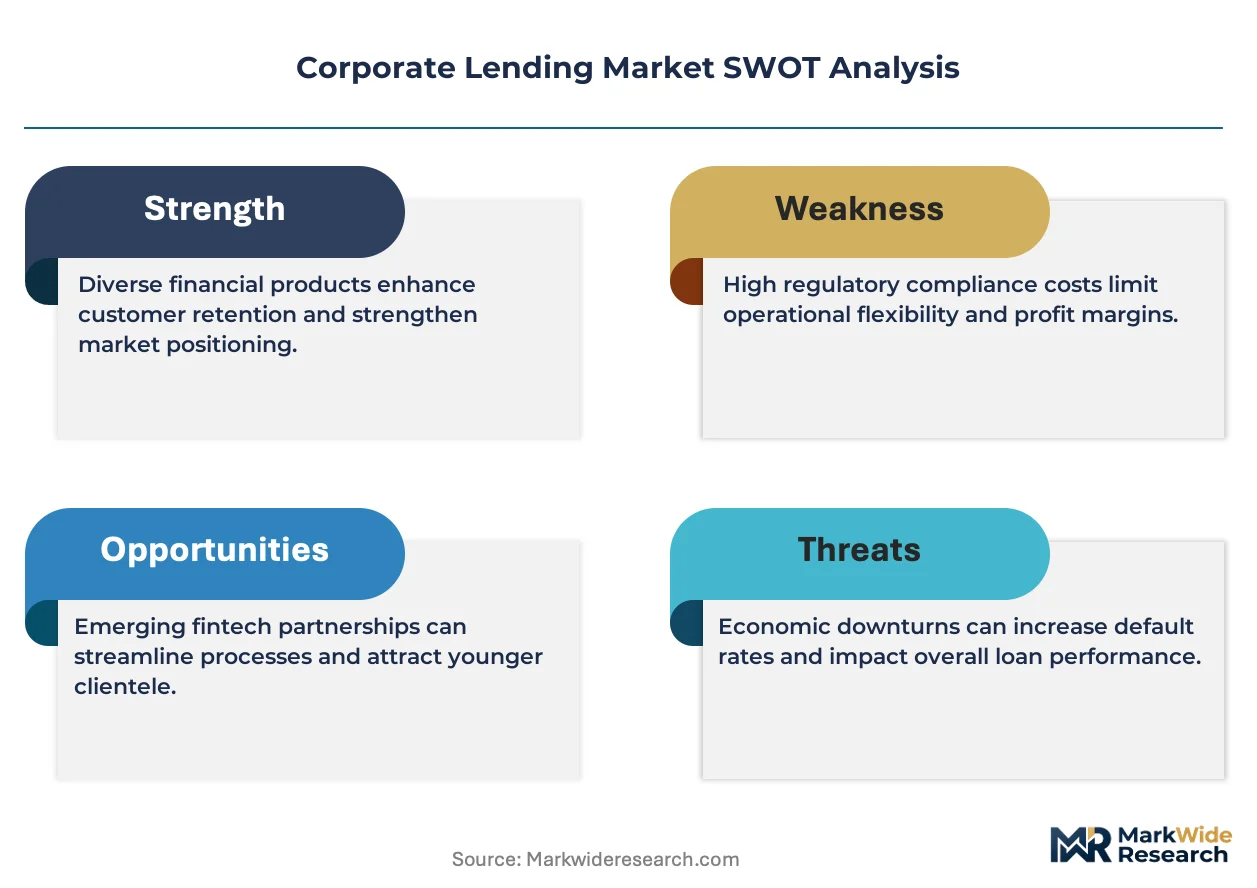
The Federal Reserve, SEC, and OCC collectively shape U.S. corporate lending through reserve requirements, disclosure mandates, and safety-and-soundness examinations that constrain bank balance sheet capacity. Basel III endgame proposals from U.S. regulators would increase risk-weighted asset charges for large corporate exposures, redirecting certain borrower segments toward non-bank lenders. Stakeholders must monitor how regulatory capital treatment evolves for fintech-originated loans held by institutional investors.
Market Dynamics
Basel III endgame capital requirements are compressing bank balance sheet capacity and redirecting corporate borrowers toward non-bank credit channels. Technology-enabled origination platforms now intermediate a growing share of middle-market exposure.
Growth Catalysts
- Basel III Risk-Weight Adjustments:Higher capital charges on large corporate exposures are pushing regional banks to syndicate more aggressively, creating volume for institutional investors and private credit funds.
- SOFR Transition Completion:The shift from LIBOR to SOFR-based pricing has standardized hedging instruments and reduced basis risk for floating-rate borrowers across manufacturing and technology verticals.
- API-Enabled Credit Distribution:Embedded finance partnerships allow lending platforms to originate through accounting software and ERP systems, reducing customer acquisition costs for working capital products.
Market Restraints
- Deposit Beta Compression:Regional banks face margin pressure as funding costs adjust faster than asset repricing, constraining their ability to compete on rate for investment-grade borrowers.
- Collateral Valuation Volatility:Commercial real estate price uncertainty is tightening loan-to-value requirements and extending due diligence timelines for asset-backed facilities.
- Regulatory Fragmentation:Divergent treatment of fintech-originated loans across state banking supervisors creates compliance overhead for digital lenders seeking nationwide scale.
Strategic Opportunities
- Climate-Linked Facility Structures:Sustainability-linked loan pricing tied to emissions targets attracts ESG-mandated capital from European institutional investors seeking yield with impact metrics.
- Revenue-Based Financing Expansion:SaaS borrowers with recurring revenue streams access non-dilutive capital through instruments that amortize as a percentage of monthly recurring revenue.
- Supply Chain Finance Integration:Reverse factoring programs embedded within procurement platforms allow corporate treasuries to optimize working capital while extending payment terms to suppliers.
Industry Challenges
- Underwriting Automation Risks:Machine learning credit models require continuous recalibration as macroeconomic conditions shift, demanding specialized data science talent scarce outside major metropolitan banking clusters.
- Covenant-Lite Documentation Standards:Erosion of financial maintenance covenants limits early warning signals for deteriorating credit quality, compressing response windows for workout specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Lending Market |
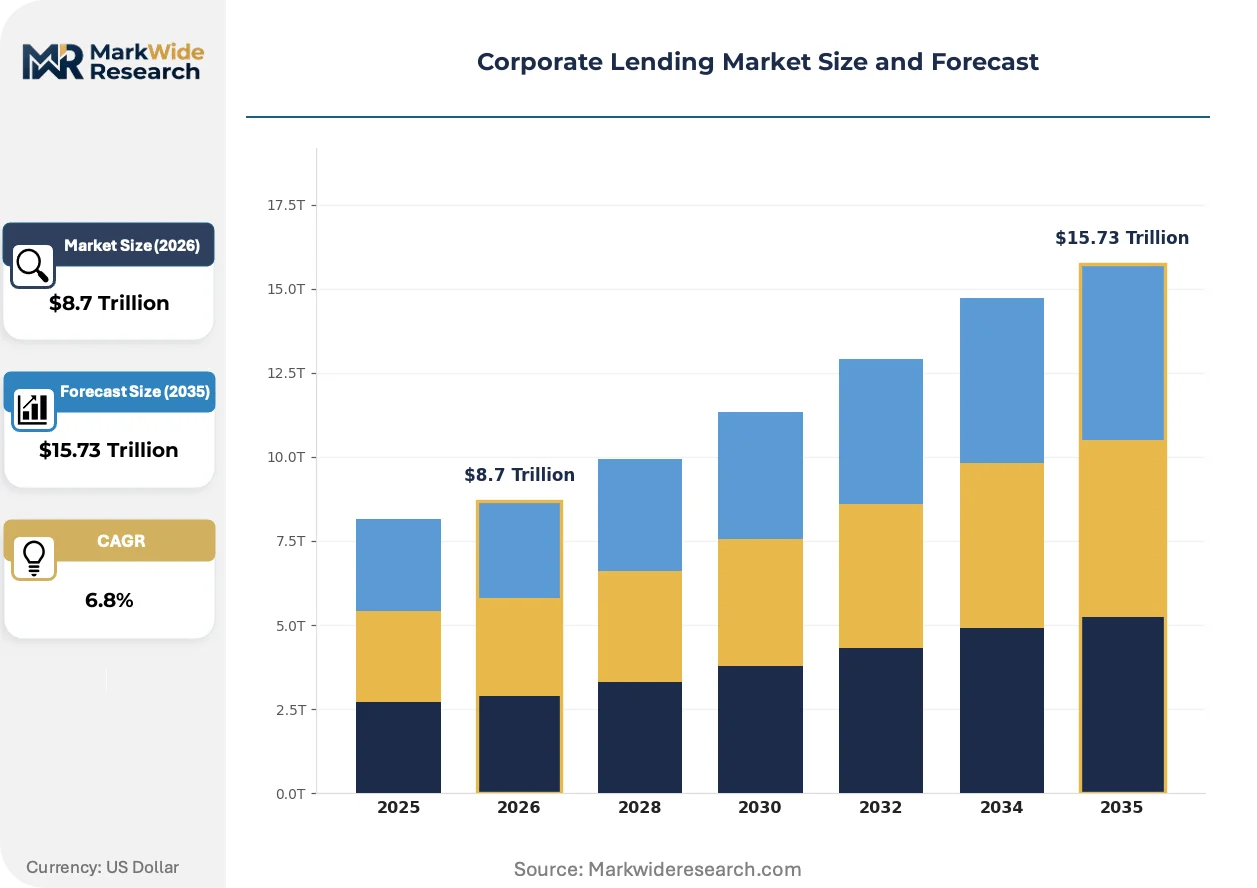
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $15.73 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Term Loan, Revolving Credit, Bridge Loan, Syndicated Loan Industry Vertical: Manufacturing, Technology, Healthcare, Real Estate Borrower Size: Small Enterprises, Mid-sized Companies, Large Corporations, Mulitnational Firms Interest Rate Type: Fixed Rate, Variable Rate, Discounted Rate, Non-Interest Capital |
| Companies Covered | Sivo, Paperstack, Kiavi, Erithmitic, Lama AI, LendingClub, LQD Business Finance, Ntropy, Alliant Credit Union, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Lending Market Strategic Shifts
Artificial intelligence is embedding into credit decisioning pipelines, compressing origination timelines while raising questions about model governance. Alternative data sources now supplement traditional financial statements for borrower assessment.
Machine learning-driven cash flow forecasting is expanding into middle-market underwriting, enabling lenders to analyze real-time transaction data from bank accounts and payment processors. Technology and healthcare borrowers with subscription revenue models are adopting these tools fastest. The technology is expanding into segments previously served only by asset-based lending, compressing the addressable market for traditional collateral-dependent structures.
The SEC's climate disclosure rules are mandating emissions reporting for large accelerated filers, forcing corporate treasuries to document sustainability metrics for loan pricing adjustments. Industrial borrowers in energy-intensive sectors face the steepest compliance costs. Facilities tied to verified emissions reductions now command tighter spreads in syndicated markets as institutional investors integrate transition risk into credit selection.
Direct origination through digital platforms is displacing traditional bank relationship managers for standardized working capital products. Middle-market finance teams now compare live rate quotes across multiple lenders simultaneously rather than negotiating sequentially. This behavior is most visible among technology sector borrowers in metropolitan corridors with dense fintech platform penetration.
Corporate Lending Market Segmentation
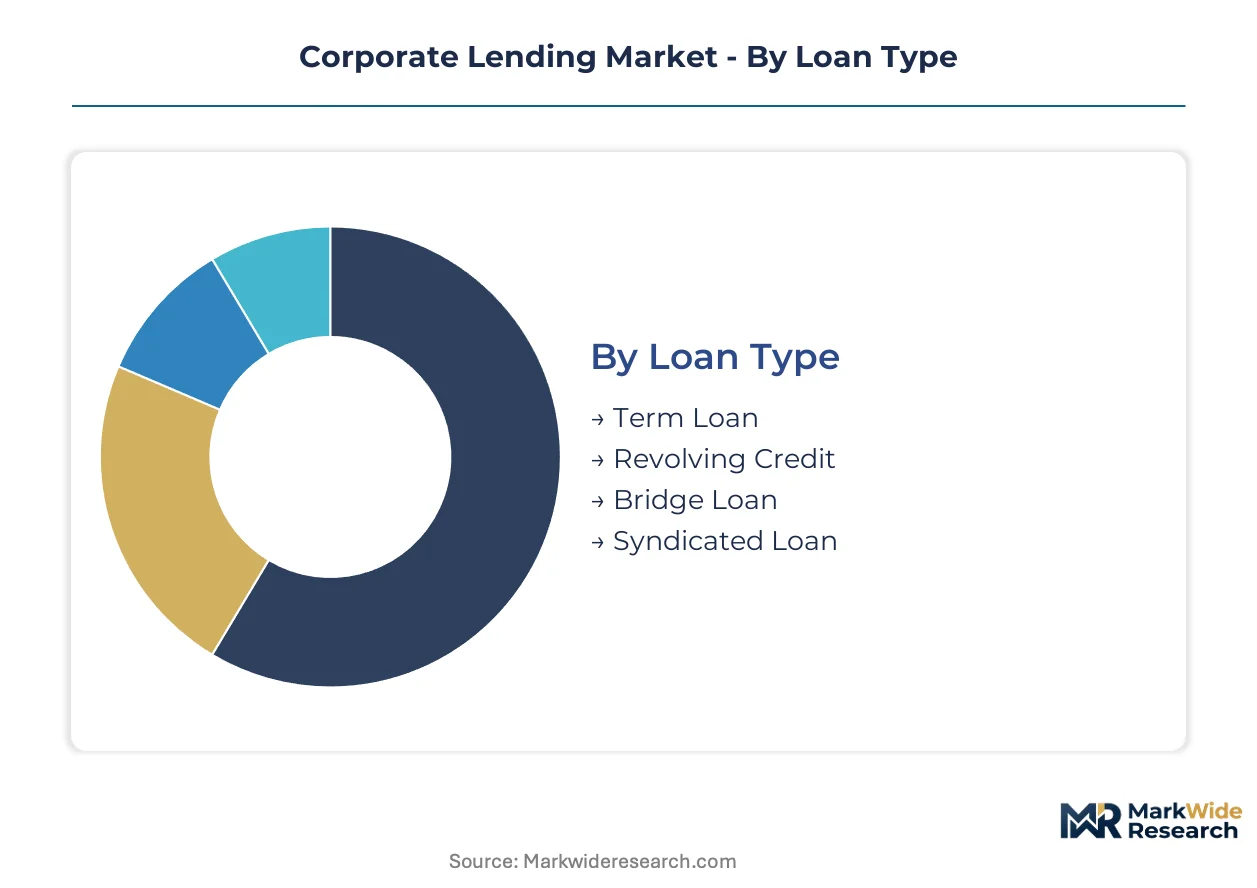
Corporate lending segmentation reveals how capital structures align with borrower risk profiles and funding timelines. Distinct product configurations serve working capital cycles, acquisition financing, and long-term capital deployment across enterprise scales.
Loan Type:
Standalone facilities dominate straightforward capital needs while embedded structures integrate with treasury management systems for automated drawdowns.
- Term Loan:Fixed-maturity amortizing facilities with scheduled principal repayments support capital-intensive manufacturing investments. Demand concentrates in the United States among industrial borrowers funding equipment modernization, constrained by Basel III risk-weight charges on longer-dated exposures.
- Revolving Credit:Committed liquidity lines with borrowing-base flexibility anchor working capital management. Technology sector adoption in Austin and San Francisco corridors drives volume as SaaS firms manage subscription revenue timing mismatches.
- Bridge Loan:Short-term acquisition financing with premium pricing fills transaction timeline gaps.
- Syndicated Loan:Multi-bank distributed commitments serve billion-dollar multinational funding requirements.
Revolving credit leads volumes today; syndicated loans are gaining share fastest.
Industry Vertical:
Cost-tier differentiation separates collateral-heavy from cash-flow-dependent underwriting approaches.
- Technology:Recurring revenue-based credit assessment replaces traditional asset coverage for software and platform companies. Borrowers in Seattle and Boston corridors access non-dilutive growth capital through API-enabled origination platforms.
- Manufacturing:Asset-backed structures with equipment and inventory collateral support cyclical production financing. Midwest industrial borrowers in Ohio and Michigan rely on regional bank relationships constrained by deposit beta compression.
- Healthcare:Receivables-based facilities align with insurance reimbursement timelines for provider networks.
- Real Estate:Property-secured lending with loan-to-value covenants faces valuation volatility headwinds.
Manufacturing leads volumes today; technology is climbing the fastest.
Borrower Size:
Volume concentration tracks with balance sheet complexity and covenant negotiation leverage.
- Mid-sized Companies:Revenue between $50 million and $1 billion drives the most competitive origination dynamics. These borrowers in Chicago and Dallas corridors compare live digital quotes against regional bank term sheets.
- Large Corporations:Investment-grade issuers with dedicated treasury functions access public bond markets and bilateral bank lines. German and Japanese industrial conglomerates anchor European and Asian syndicated loan volumes.
- Small Enterprises:Founder-guaranteed facilities with personal collateral requirements serve sub-$50 million revenue firms.
- Multinational Firms:Cross-border cash pooling and multi-currency revolving structures support global operations.
Large corporations lead volumes today; mid-sized companies show the steepest expansion trajectory.
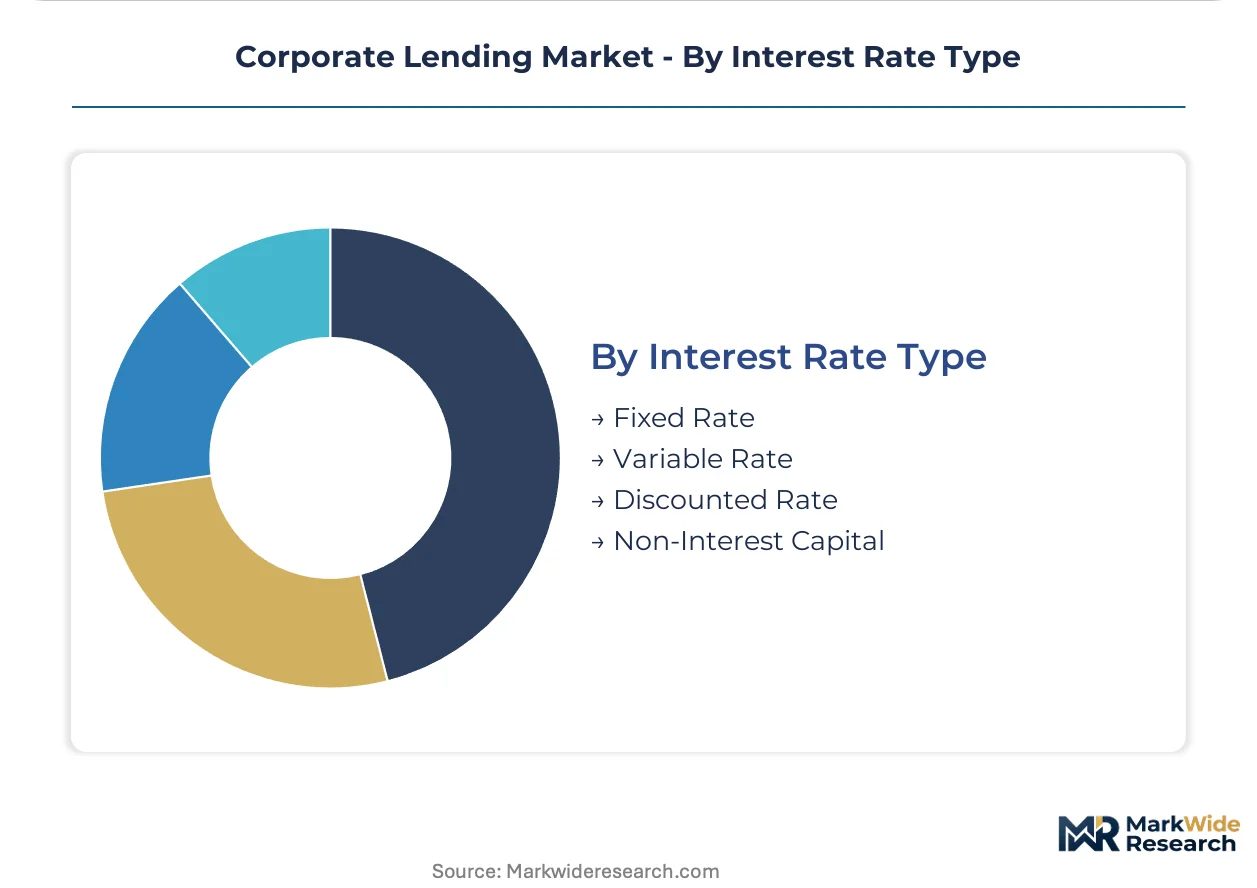
Interest Rate Type:
Margin structures reflect funding cost pass-through mechanisms and hedging instrument availability.
- Variable Rate:SOFR-based pricing with periodic resets dominates floating-rate exposure management. Adoption accelerated post-LIBOR transition among borrowers in London and New York seeking basis risk reduction.
- Fixed Rate:Locked-in coupons through maturity provide certainty for capital budgeting. German manufacturing borrowers favor fixed structures amid ECB rate uncertainty.
- Discounted Rate:Relationship-based pricing concessions reward multi-product banking clients.
- Non-Interest Capital:Convertible and revenue-based instruments offer equity-linked returns to alternative lenders.
Variable rate leads volumes today; fixed rate is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory capital arbitrage is redirecting corporate lending flows toward jurisdictions with lighter prudential requirements. Borrowers and lenders alike migrate where compliance costs compress returns least aggressively.
United States
Middle-market technology borrowers in Austin and San Francisco corridors drive revolving credit demand. The Federal Reserve, SEC, and OCC collectively constrain bank balance sheet capacity through reserve requirements and safety-and-soundness examinations. Regional banks in Chicago and Dallas face deposit beta compression, ceding share to fintech platforms.
Germany
Industrial conglomerates anchor European syndicated loan volumes with multi-billion-euro commitments. ECB rate uncertainty pushes manufacturing borrowers toward fixed-rate structures. Frankfurt-based treasury functions manage cross-border cash pooling for Mittelstand firms expanding into Eastern Europe.
United Kingdom
SOFR transition completion has standardized hedging instruments for London-based floating-rate borrowers. The Prudential Regulation Authority implements Basel III endgame proposals parallel to EU timelines. Canary Wharf financial institutions syndicate aggressively to distribute large corporate exposures.
China
State-owned enterprises access preferential credit through policy banks while private technology firms seek offshore funding. The People's Bank of China manages reserve requirement ratios to direct lending toward strategic sectors. Shenzhen and Hangzhou SaaS companies experiment with revenue-based financing structures.
India
Reserve Bank of India guidelines on priority sector lending redirect bank credit toward manufacturing and infrastructure. Mumbai and Bangalore technology borrowers access working capital through API-enabled distribution partnerships. Non-bank financial companies expand market share as Basel-equivalent rules constrain public sector bank capacity.
Corporate Lending Market Competitive Environment
Established lenders occupy the standard tier; emerging fintech entrants pursue digitally native origination and embedded distribution. The market structures around three tiers: universal banks with balance sheet scale, regional banks with relationship depth, and technology platforms with data-driven underwriting velocity. Competitive intensity concentrates in the middle-market segment where borrower acquisition costs determine economics. Dominant moves include strategic partnerships between banks and software platforms, plus vertical integration into loan servicing infrastructure.
Among technology-enabled originators, Kiavi and LendingClub exemplify the platform archetype with real-time credit decisioning capabilities. LQD Business Finance occupies a position within specialized middle-market cash-flow lending. These three entities represent contrasting approaches to borrower acquisition: Kiavi through asset-backed structures, LendingClub through direct digital channels, and LQD Business Finance through streamlined underwriting protocols for recurring revenue profiles.
| Leading Market Players |
|---|
| Sivo |
| Paperstack |
| Kiavi |
| Erithmitic |
| Lama AI |
| LendingClub |
| LQD Business Finance |
| Ntropy |
| Alliant Credit Union |
| Others |
Value Chain & Pricing Dynamics
Private-credit-rolled-up specialists dominate middle-market origination, compressing regional bank pricing power while concentrating supply chain control among vertically integrated platform lenders. Their balance sheet scale enables aggressive rate competition that forces traditional lenders into narrower credit tiers or riskier borrower segments.
Pricing Analysis
Distributor margin layers in syndicated lending have compressed as direct origination platforms eliminate intermediary fees. Pricing stratifies across investment-grade, leveraged, and sub-investment-grade tiers with spreads widening most sharply for borrowers below BBB- ratings. Cost compression in middle-market revolving facilities is intensifying because fintech platforms automate underwriting and reduce customer acquisition expenses. Technology sector borrowers with recurring revenue models show the least price sensitivity, while cyclical manufacturing firms negotiate most aggressively on basis points.
Supply Chain Analysis
Certification gating through Basel III risk-weight classifications determines which lenders can hold corporate exposures on balance sheet. Supply concentrates among United States, United Kingdom, and German financial institutions with access to deep deposit bases and institutional distribution networks. Raw material dependencies include SOFR-linked hedging instruments, credit default swap protection, and committed warehouse lines from investment banks. Single-source vulnerability runs through the tri-party repo market for intraday funding. Distribution runs through syndication desks, private placement agents, and direct digital platforms to corporate treasury functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States and European regulatory capital treatment creates margin opportunities for lenders willing to navigate divergent Basel III implementation timelines. The Federal Reserve's slower adoption of endgame rules versus the ECB's accelerated schedule produces measurable cost-of-capital spreads.
For Market Incumbents: To counter fintech platform disintermediation, universal banks should deepen API-enabled distribution partnerships with accounting software providers while consolidating regional bank relationships to capture middle-market origination volume. Channel control over embedded finance integrations represents the critical defensive lever.
For New Entrants and Emerging Players: ERP system integrators offer the most accessible partnership pathway for technology-enabled originators seeking rapid borrower acquisition. Revenue-based financing for SaaS companies in Austin and San Francisco corridors presents the most penetrable white-space segment. A direct-to-treasury digital origination model bypasses incumbent relationship manager networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional banks with compressed net interest margins and deteriorating deposit franchises. Long-term viability over the next decade hinges on successful technology transformation and balance sheet optimization. The signal to watch is sustained deposit outflows to money market funds as an inflection indicator for regional bank distress.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Origination Partnership | Embedded finance integrations with SAP and Oracle reduce customer acquisition costs for working capital products. |
| Climate-Linked Facility Launch | Sustainability-linked pricing attracts ESG-mandated capital from European institutional investors seeking yield. |
| Revenue-Based Financing Expansion | Non-dilutive capital structures for SaaS borrowers capture subscription economy growth without equity dilution. |
| Syndication Desk Consolidation | Scale advantages in distributing large corporate exposures improve risk-adjusted returns for lead arrangers. |
| Private Credit Fund Formation | Basel III capital arbitrage redirects institutional capital toward non-bank lending channels with lighter regulation. |
Study Parameters
Direct dialogue with chief credit officers, corporate treasury managers, fintech platform executives, and institutional fixed-income portfolio managers grounded the qualitative foundation. Primary insights were cross-referenced against secondary sources including Federal Reserve Senior Loan Officer Opinion Surveys, SEC corporate filings, Basel Committee regulatory texts, and syndicated loan pricing databases from LPC and Dealogic. Bottom-up and top-down triangulation validated volume estimates across loan type and borrower size segments.
Bottom-up modeling aggregated facility-level origination data by loan structure, industry vertical, and interest rate type across the projection horizon. Top-down analysis calibrated aggregate market size against banking system credit growth and non-bank financial intermediary expansion. Segmentation dimensions included loan type, industry vertical, borrower size, and interest rate structure. CAGRs were derived from regression analysis of historical credit growth against macroeconomic drivers including GDP expansion, capital expenditure cycles, and monetary policy stance.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory capital rule changes and interest rate volatility. Projections reflect assumptions about Basel III implementation timelines, fintech platform penetration rates, and corporate borrower preference shifts. A model refresh is warranted upon material change in Federal Reserve capital requirement proposals or sustained shifts in deposit beta behavior across regional banking systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Factoring Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Digital Lending Market