
 Russia AI in Fintech Market | 2026-2036
Russia AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Russia AI in Fintech Market Insights
Russia is reconfiguring its financial technology infrastructure through state-backed digital transformation programs. Sberbank leverages its SberCloud platform to anchor AI development across retail and corporate banking verticals. Tinkoff Bank sustains algorithmic innovation through its fully digital architecture, while VTB Bank competes with sovereign-entity procurement advantages in state-linked financial services.
Russia AI in Fintech comprises machine learning models, natural language processing engines, robotic process automation systems, and predictive analytics platforms deployed to automate credit scoring, detect transactional fraud, execute algorithmic trades, and power customer-facing chatbots. Machine learning dominates technology deployment due to its maturity in risk modeling, while robotic process automation captures expanding share as banks automate back-office compliance workflows. Fraud detection applications command premium investment priority following sanctions-related payment system fragmentation, and retail banks represent the deepest end-user segment due to massive customer bases requiring automated service delivery.
The Central Bank of Russia shapes AI deployment through digital rubble pilot requirements and financial stability mandates, while Federal Law No. 242-FZ on data localization constrains cloud architecture choices for foreign-origin AI tools. Compliance software solutions face escalating certification demands as regulators scrutinize algorithmic transparency in credit decisions. Stakeholders must monitor whether domestic chip and cloud capacity can support model training scale without Western hardware access.
Market Dynamics
The Central Bank of Russia's digital ruble pilot and Federal Law No. 242-FZ on data localization are compressing cloud architecture choices while forcing domestic AI infrastructure buildout across retail and corporate banking verticals.
Growth Catalysts
- Data Localization Mandates:Federal Law No. 242-FZ requires all personal data of Russian citizens to be stored on servers physically located within Russia, compelling banks to deploy domestic AI training clusters and cloud infrastructure rather than foreign-origin platforms.
- Retail Banking Automation:Massive customer bases at Sberbank and Tinkoff Bank are driving automated credit scoring deployment to reduce decision latency from days to minutes for consumer loan products.
- Algorithmic Trading Infrastructure:Moscow Exchange participants are expanding machine learning deployment for high-frequency execution strategies, creating demand for low-latency predictive analytics platforms.
Market Restraints
- Semiconductor Supply Concentration:Restricted access to advanced GPUs from NVIDIA and AMD suppliers in Taiwan and South Korea is constraining model training scale for Russian AI developers.
- Payment System Fragmentation:SWIFT exclusion and correspondent banking restrictions are fragmenting cross-border transaction data flows, degrading fraud detection model accuracy for international payments.
- Cloud Architecture Cost Inflation:Domestic cloud infrastructure buildout under data localization requirements carries 40-60% cost premiums versus foreign alternatives, compressing AI project ROI timelines.
Strategic Opportunities
- Corporate Banking Underpenetration:SME lending and trade finance segments remain underserved by AI automation, offering expansion space beyond saturated retail consumer markets.
- Federated Learning Deployment:Privacy-preserving machine learning techniques enable banks to train models across distributed datasets without centralizing sensitive transaction records, circumventing data sharing restrictions.
- Regulatory Sandboxes:Central Bank of Russia fintech sandbox programs allow controlled testing of AI-powered credit decisioning outside standard licensing requirements, accelerating product validation cycles.
Industry Challenges
- Machine Learning Engineering Talent Scarcity:Sanctions-related brain drain and restricted international mobility are depleting the specialized workforce for production-grade model deployment.
- Algorithmic Transparency Certification:Central Bank mandates for explainable credit decisions require extensive documentation and audit trails, extending compliance timelines for neural network-based scoring systems.
- Legacy Core Banking Integration:Soviet-era COBOL and mainframe infrastructure at regional banks creates friction for API-based AI service deployment, requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia AI in Fintech Market |
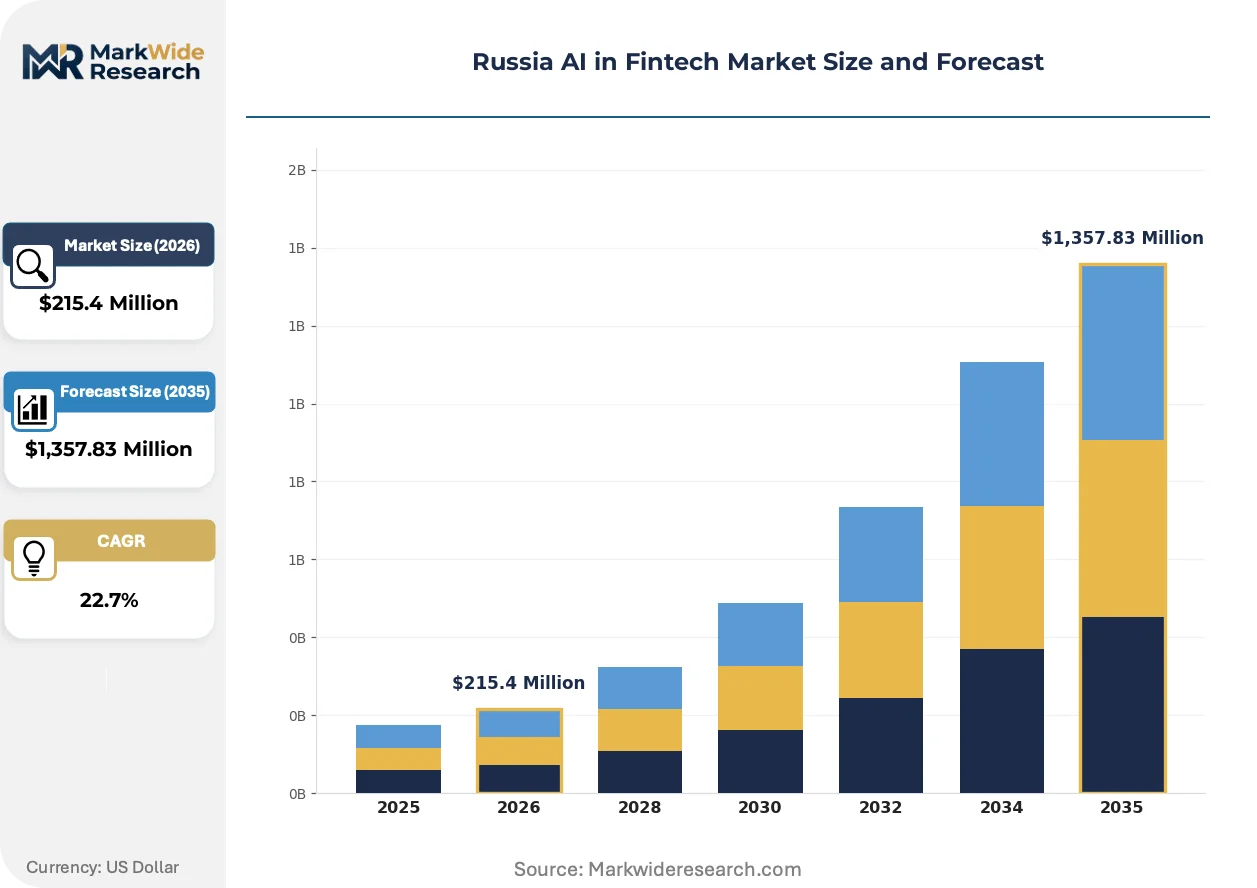
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,357.83 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Robotic Process Automation, Predictive Analytics Application: Credit Scoring, Fraud Detection, Algorithmic Trading, Customer Service End User: Retail Banks, Investment Firms, Payment Processors, Insurance Companies Solution: Chatbots, Analytics Platforms, Risk Management Tools, Compliance Software |
| Companies Covered | Sberbank, Tinkoff Bank, Yandex.Money, VTB Bank, Qiwi, Alfa-Bank, T-Bank, Otkritie Bank, Home Credit Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia AI in Fintech Market Trends and Innovations
Generative AI and large language models are penetrating customer service and compliance workflows, while regulatory pressure on algorithmic transparency is reshaping model architecture choices across Russian financial institutions.
Transformer-based natural language processing engines are rendering obsolete rule-based chatbot systems in retail banking customer service. Tinkoff Bank and Sberbank are deploying these models for intent classification and response generation across millions of monthly interactions. The technology is rendering obsolete first-generation scripted dialogue systems that required manual flowchart maintenance.
Federal Law No. 242-FZ enforcement is hardening data residency requirements for foreign AI service providers. Banks must now certify that model training, inference, and data storage occur exclusively on Russian territory. Retail payment processors and neobanks with cloud-native architectures are responding fastest, while legacy institutions face extended migration timelines.
Corporate treasury departments are unbundling AI procurement from bundled core banking contracts. Large enterprises now source fraud detection and cash flow forecasting algorithms through direct vendor relationships rather than bank-embedded services. This shift is most visible among commodity exporters in Moscow and St. Petersburg seeking customized risk models for sanctions-evasion payment routing.
Russia AI in Fintech Market Segmentation
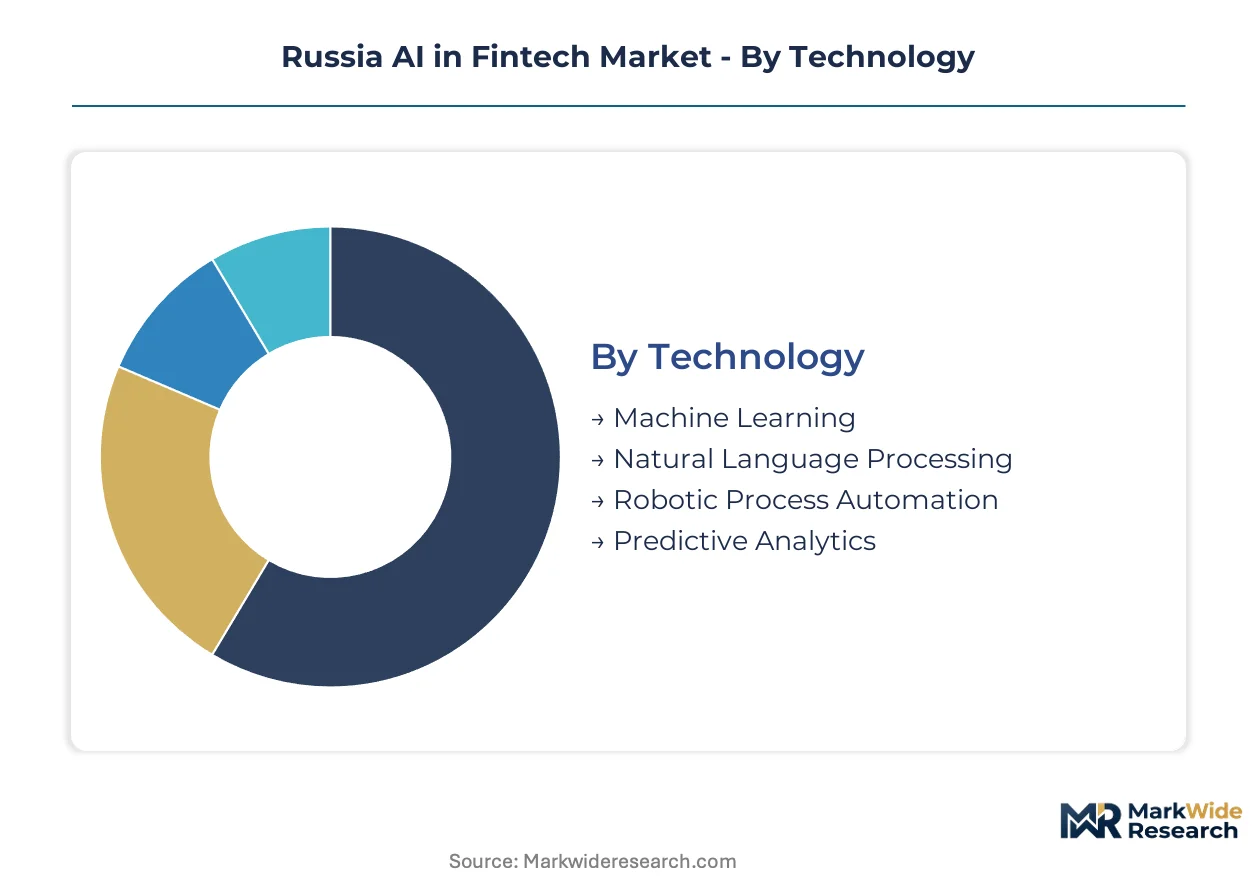
AI deployment patterns across Russian financial institutions vary sharply by technical maturity, regulatory exposure, and customer interaction intensity. Understanding these segment boundaries clarifies where infrastructure investments concentrate and where solution vendors face the steepest compliance barriers.
Technology:
Mature supervised learning techniques anchor production workloads, while generative architectures remain experimental across most institutions.
- Machine Learning:Supervised and ensemble methods dominate credit scoring and fraud detection pipelines. Sberbank and Tinkoff Bank operate the largest training clusters, constrained by GPU import restrictions that limit model complexity scaling.
- Natural Language Processing:Transformer-based intent classification and document parsing are displacing rule-based systems in customer service and compliance review workflows. Moscow-based neobanks deploy these fastest due to cloud-native architectures.
- Robotic Process Automation:Back-office task automation for KYC documentation and regulatory reporting. Regional banks with legacy core systems adopt this to defer expensive middleware replacement.
- Predictive Analytics:Time-series forecasting for liquidity management and macroeconomic scenario modeling. Central Bank stress-testing mandates drive procurement at systemically important institutions.
Machine Learning handles the majority of throughput; Natural Language Processing is expanding most quickly on share.
Application:
Regulatory pressure and customer volume shape which use cases receive capital allocation priority.
- Fraud Detection:Real-time transaction monitoring and sanctions-evasion pattern recognition. Payment system fragmentation degrades cross-border model accuracy, forcing domestic-only training data reliance.
- Credit Scoring:Automated consumer lending decisions from application to disbursement. Federal Law No. 242-FZ data localization requirements prevent cloud inference on foreign infrastructure.
- Algorithmic Trading:High-frequency execution strategies on Moscow Exchange equities and derivatives. Low-latency co-location at the exchange data center determines competitive positioning.
- Customer Service:Chatbot and voice assistant deployment for routine banking queries. Fully digital banks achieve higher containment rates than branch-network institutions.
Fraud Detection commands the largest absolute spend; Credit Scoring is gaining share fastest.
End User:
Customer base scale and regulatory classification determine AI procurement sophistication.
- Retail Banks:Mass-market lending and deposit institutions with millions of customers. Automated service delivery is mandatory given cost-to-serve constraints at this scale.
- Payment Processors:Transaction clearing and merchant acquiring specialists. Real-time fraud detection requirements drive the lowest latency inference demands.
- Investment Firms:Brokerage and asset management operations. Algorithmic execution and portfolio risk analytics dominate procurement.
- Insurance Companies:Life and property underwriters with emerging AI adoption. Claims automation and actuarial modeling lag banking sophistication by several years.
Retail Banks absorb the dominant share of sector investment; Payment Processors are climbing the fastest.
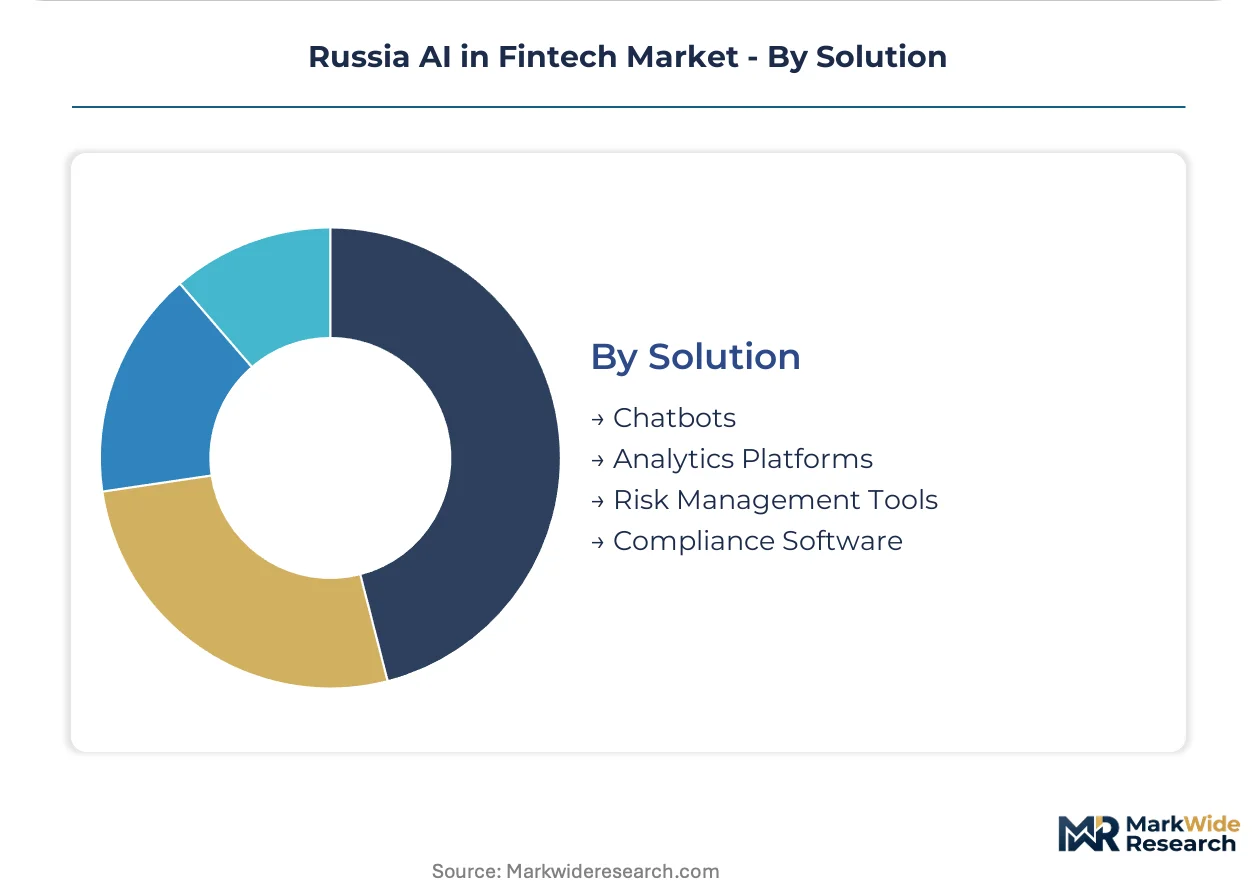
Solution:
Packaging format determines deployment friction and vendor relationship structure.
- Analytics Platforms:Integrated data visualization and model management environments. Corporate treasury departments increasingly source these outside bundled core banking contracts.
- Risk Management Tools:Credit, market, and operational risk quantification systems. Central Bank model validation requirements extend implementation timelines.
- Chatbots:Customer-facing conversational interfaces with escalating generative capabilities. First-generation scripted systems face rapid obsolescence.
- Compliance Software:Regulatory reporting and audit trail automation. Algorithmic transparency mandates intensify documentation burdens for neural network deployments.
Analytics Platforms represent the deepest installed base; Compliance Software shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Moscow-Kazan High-Speed Railway corridor anchors Russia's fintech AI concentration, linking the capital's development centers to Volga River industrial zones through dedicated fiber infrastructure that bypasses Western-dominated internet exchange points.
Moscow and Moscow Oblast
Sberbank's SberCloud platform and Tinkoff Bank's digital headquarters drive machine learning cluster demand. The Central Bank of Russia's regulatory sandbox operates from the capital, accelerating AI credit decisioning pilots. Skolkovo Innovation Center houses specialized engineering talent pools for neural network deployment.
Saint Petersburg
VTB Bank maintains algorithmic trading development facilities serving Moscow Exchange connectivity. The city's port infrastructure enables data center cooling systems for GPU-intensive training workloads. Local neobanks leverage the Baltic Sea cable landing stations for redundant domestic routing.
Kazan and Tatarstan Republic
Innopolis tech park anchors federated learning research for privacy-preserving banking models. Tatarstan's sovereign IT procurement preferences channel state-linked financial institution contracts toward regional developers. The city's university pipeline supplies machine learning engineering graduates to payment processors.
Novosibirsk and Siberian Federal District
Academic computing centers at Novosibirsk State University support AI model training for regional banks lacking capital-grade infrastructure. Domestic semiconductor assembly facilities under development aim to reduce GPU import dependence. Siberian payment networks deploy localized fraud detection to compensate for degraded cross-border data flows.
Yekaterinburg and Ural Federal District
Industrial banking relationships with metals and mining conglomerates drive specialized risk modeling demand. The Ural data center cluster serves as a geographic backup for Moscow-based AI inference workloads. Regional banks here face the steepest legacy core system integration challenges.
Russia AI in Fintech Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying algorithmic modules and training infrastructure. The vendor structure concentrates around state-linked banking groups with captive cloud capacity, while independent fintechs compete on narrow application specialization. Three archetypes dominate: sovereign-entity platforms with procurement preference, fully digital neobanks with cloud-native architectures, and payment processors with real-time inference requirements. Competitive positioning hardens through domestic infrastructure buildout and regulatory sandbox access rather than technology licensing.
Within the sovereign-entity tier, Sberbank anchors platform consolidation through vertical cloud integration, while VTB Bank occupies a position leveraging state procurement channels. Tinkoff Bank exemplifies the digital-native archetype with algorithmic innovation centered on customer-facing automation. These three structures represent the dominant competitive configurations shaping vendor relationships and talent acquisition patterns across the sector.
| Leading Market Players |
|---|
| Sberbank |
| Tinkoff Bank |
| Yandex.Money |
| VTB Bank |
| Qiwi |
| Alfa-Bank |
| T-Bank |
| Otkritie Bank |
| Home Credit Bank |
| Others |
Pricing and Supply Chain Analysis
The Moscow-Kazan High-Speed Railway corridor carries GPU server shipments from domestic assembly facilities to Sberbank and Tinkoff Bank data centers at freight premiums that compress margins for regional banks lacking volume procurement power. This logistics chokepoint concentrates pricing leverage among the three systemically important institutions with captive cloud infrastructure, while tier-three payment processors absorb 40-60% cost inflation for domestic AI training clusters versus pre-sanctions foreign alternatives.
Pricing Analysis
Volume-discount tiering separates sovereign-entity platforms with annual GPU procurement above ten thousand units from mid-tier neobanks purchasing hundreds of units quarterly and regional banks acquiring single-digit clusters through systems integrator markups. Certification under Central Bank of Russia algorithmic transparency mandates commands 15-25% price premiums for compliance software solutions. Cost compression in inference-as-a-service tiers is intensifying because SberCloud and VTB infrastructure are absorbing stranded domestic GPU capacity. Payment processors with real-time fraud detection requirements show lowest price sensitivity; regional agricultural credit cooperatives exhibit highest sensitivity to per-inference licensing fees.
Supply Chain Analysis
Tariff exposure between China and Russia dominates GPU import logistics, with customs processing delays at Zabaikalsk and Kraskino border crossings extending lead times for NVIDIA A100 and H100 alternatives sourced through parallel import channels. Domestic supply concentrates in China for advanced packaging, South Korea for HBM memory modules, and Taiwan for foundry capacity. Russian AI infrastructure draws from domestic semiconductor assembly at Mikron and Angstrem for legacy node inference chips, plus Chinese-origin training accelerators from Huawei and Biren Technology. Single-source vulnerability in high-bandwidth memory supply creates bottleneck risk for model scaling. Distribution runs through direct procurement relationships between banks and systems integrators, bypassing traditional IT distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Model training and inference operations represent the fastest-expanding recurring-revenue layer, with managed AI infrastructure services outpacing hardware procurement growth as banks outsource GPU cluster operations to SberCloud and VTB platform subsidiaries.
For Market Incumbents: Pre-empt talent attrition by locking machine learning engineering teams through equity participation in captive AI development subsidiaries. VTB Bank and Sberbank should accelerate backward integration into domestic GPU assembly partnerships with Mikron to reduce import dependency exposure. Central Bank algorithmic transparency mandates threaten neural network-based credit scoring margins; incumbents must invest in explainable AI architectures to defend compliance certification timelines.
For New Entrants and Emerging Players: Establish a beachhead in SME lending automation, where corporate banking segments remain underserved by incumbent AI deployment focused on retail consumer volumes. Federated learning solutions for privacy-preserving credit modeling offer the most penetrable entry angle, bypassing data localization barriers that constrain foreign-origin platform competitors. Partner with Innopolis tech park developers for regulatory sandbox access and engineering talent pipeline.
For Investors and Strategic Acquirers: Federal Law No. 242-FZ enforcement hardening in 2024-2025 reshapes the acquisition landscape toward domestic-cloud-native fintechs with certified data residency infrastructure. Long-term viability favors targets with Central Bank sandbox participation and established GPU supply relationships through Chinese parallel import channels. Watch for digital ruble pilot expansion signals as inflection indicator for payment processor AI infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Deployment | Innopolis research partnerships enable privacy-preserving model training without centralizing sensitive transaction data under Federal Law No. 242-FZ constraints. |
| Domestic GPU Assembly Partnership | Mikron and Angstrem alliances reduce import dependency for inference chip supply serving regional banks with limited procurement scale. |
| Regulatory Sandbox Participation | Central Bank fintech sandbox access accelerates AI credit decisioning validation cycles outside standard licensing requirements. |
| Algorithmic Transparency Certification | Explainable AI architecture investment defends against Central Bank model validation timeline extensions for neural network deployments. |
| Managed AI Infrastructure Service Launch | SberCloud and VTB platform subsidiaries capture recurring revenue from banks outsourcing GPU cluster operations and model training pipelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with machine learning engineering directors at Sberbank and Tinkoff Bank, Central Bank of Russia regulatory sandbox administrators, procurement leads at regional payment processors, and systems integrators supplying GPU infrastructure. Secondary validation drew from Central Bank of Russia fintech sandbox disclosures, Federal Law No. 242-FZ implementation guidance, Moscow Exchange algorithmic trading volume statistics, and customs import records for semiconductor equipment. Bottom-up segmentation modeling triangulated against top-down macroeconomic scenario analysis.
Calibration across the projection horizon anchored technology adoption curves to Central Bank digital ruble pilot phases and data localization enforcement timelines. Segmentation dimensions modeled include technology type, application use case, end-user institution category, and solution packaging format, cross-referenced with regional infrastructure maturity across Moscow, Saint Petersburg, Kazan, Novosibirsk, and Yekaterinburg clusters. CAGRs derived from logistic diffusion curves fitted to observed GPU procurement volumes and cloud infrastructure capex disclosures. Industry-specific forecast inputs incorporated sanctions-related payment system fragmentation effects on fraud detection model accuracy and domestic chip assembly capacity expansion schedules.
Stress conditions across GPU import restriction severity, engineering talent emigration rates, and Central Bank algorithmic transparency mandate enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding digital ruble adoption velocity and Chinese semiconductor export control evasion sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Micro-Investing Platform Market
FinTech
Latin America Fintech Market
FinTech
Financial Management Software Market
FinTech
Financial Cloud Market
FinTech
Germany Fintech Market
FinTech
Saudi Arabia Fintech Market
FinTech
Supply Chain Finance Market
FinTech
Robo-Advisory Software Market
FinTech
India AI in Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
North America Fintech Market
FinTech
Europe Embedded Finance Market
FinTech
Smart Finance Connectivity Market
FinTech
China AI in Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Decentralized Finance Technology Market