
 Canada Automotive Electric Actuators Market | 2026-2036
Canada Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Electric Actuators Market Outlook
Modular actuator packaging is repositioning how Tier-1 suppliers configure brake and steering subsystems for just-in-sequence delivery. Robert Bosch leverages integrated electromechanical modules to dominate power steering contracts with Detroit Three transplants. Continental anchors its position through brushless DC motor specialization for HVAC flap control in light trucks.
Canada automotive electric actuators are electromechanical devices converting electrical signals into precise mechanical motion, typically operating at 12-48V with torque outputs from 2-50 Nm for throttle, valve, and positional control in vehicle systems. Their primary purpose is replacing hydraulic and pneumatic mechanisms with programmable, feedback-capable motion control that reduces weight and enables software-defined vehicle architectures. Linear actuators lead the product mix due to widespread deployment in electronic brake boosters and gear selector mechanisms, while smart actuators with embedded position sensing represent the fastest-expanding category as automakers pursue predictive maintenance capabilities. The OEM channel captures the dominant value share, though aftermarket providers are gaining traction in actuator refurbishment for extended-duty commercial fleets.
Transport Canada enforces motor vehicle safety standards that mandate fail-safe actuator behavior in brake-by-wire and steer-by-wire prototypes, while Environment and Climate Change Canada emissions rules indirectly drive demand through powertrain electrification. Health Canada and PMRA oversee material compliance for lubricants and coatings used in actuator manufacturing, restricting certain substances in sealed motor housings. Stakeholders must monitor how proposed updates to Canadian Motor Vehicle Safety Standard 126 and provincial zero-emission vehicle mandates will reshape actuator specification requirements across the supply base.
Market Dynamics
Transport Canada's proposed updates to Motor Vehicle Safety Standard 126 are forcing Tier-1 suppliers to redesign brake-by-wire actuators with redundant fail-safe architectures before 2027 implementation deadlines.
Growth Catalysts
- Zero-Emission Vehicle Mandates:Provincial programs in Quebec and British Columbia require automakers to electrify powertrains, expanding demand for throttle-by-wire and electronic valve control actuators in hybrid architectures.
- Electronic Brake Boosters:The shift from vacuum-assisted to electromechanical braking in light trucks is absorbing linear actuator capacity at Windsor and Oshawa assembly plants.
- Great Lakes Corridor Concentration:Proximity to Detroit Three transplants and integrated cross-border supply chains position Ontario suppliers for just-in-sequence actuator delivery contracts.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium and dysprosium price volatility in brushless DC motors creates input cost instability for actuator manufacturers serving commercial vehicle segments.
- Single-Source Semiconductor Risk:MCU and gate driver concentration among Asian foundries exposes Canadian actuator suppliers to allocation constraints during automotive chip shortages.
- Steer-by-Wire Regulatory Friction:Transport Canada's conservative interpretation of fail-safe requirements delays approval timelines for fully electronic steering actuators versus hydraulic-electronic hybrid systems.
Strategic Opportunities
- Western Canada Commercial Fleets:Extended-duty mining and logging vehicles in Alberta and British Columbia present underpenetrated demand for predictive maintenance-enabled smart actuators with embedded position sensing.
- HVAC Flap Control Convergence:Integration of brushless DC actuators with cabin air quality sensors creates white space for multi-zone climate systems in electric pickup trucks.
- Refurbishment Channel Development:Direct-to-fleet actuator remanufacturing bypasses traditional aftermarket distribution, capturing margin from commercial operators seeking 15-year vehicle lifecycles.
Industry Challenges
- Embedded Systems Firmware Expertise:Shortage of automotive software engineers capable of developing ASIL-D compliant motor control algorithms constrains supplier R&D throughput.
- Cross-Border Certification Complexity:Dual compliance with Transport Canada CMVSS and US NHTSA FMVSS standards extends validation timelines for actuators deployed in integrated North American vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Electric Actuators Market |
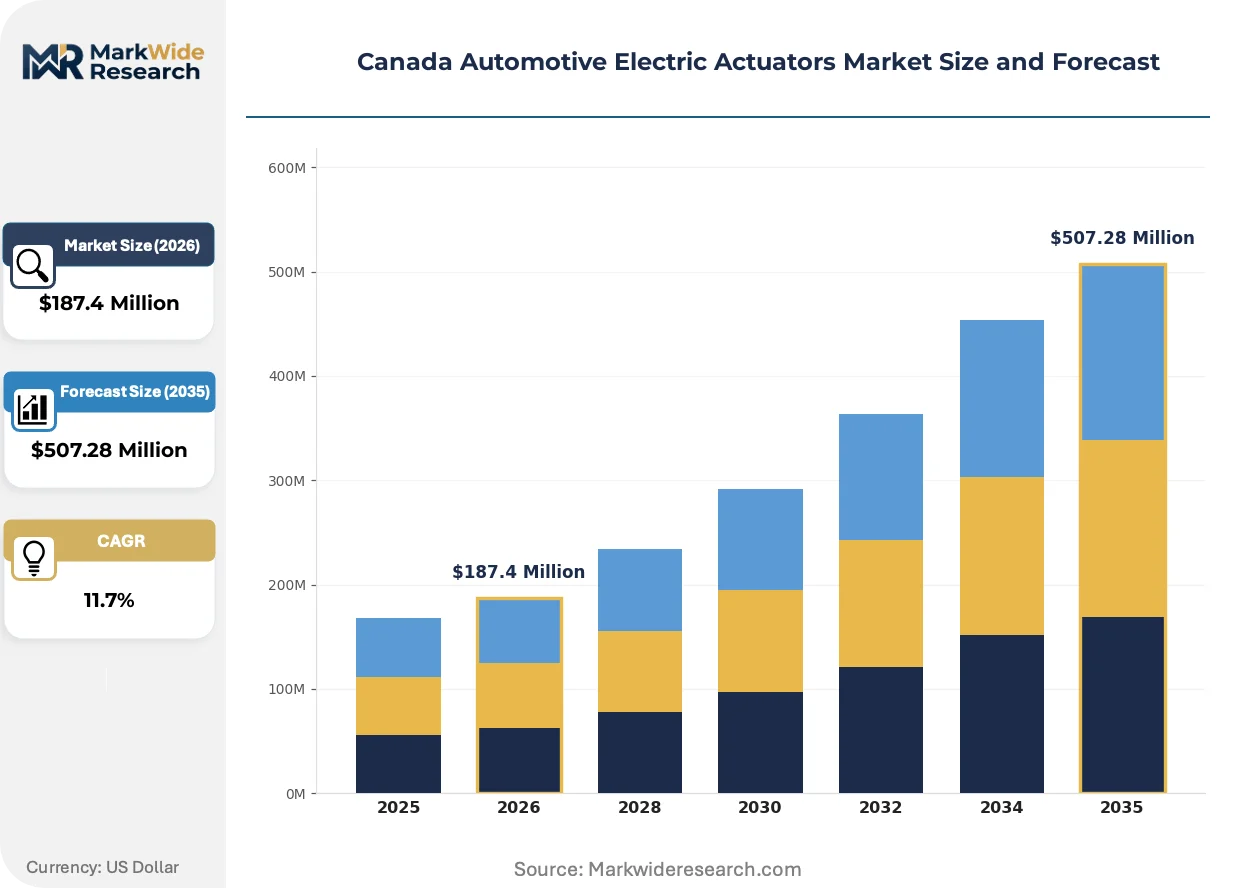
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Actuators, Linear Actuators, Electric Actuators, Smart Actuators Application: Power Steering, Brake Systems, HVAC Systems, Door Controls End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Brushless DC, Stepper Motors, Piezoelectric, Electromechanical |
| Companies Covered | Robert Bosch, Denso Corporation, Continental, Mitsubishi Electric, Aptiv PLC, Valeo, ZF Friedrichshafen, Johnson Electric, BorgWarner, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Electric Actuators Market Strategic Shifts
Software-defined vehicle architectures are collapsing mechanical-hydraulic subsystems into programmable electromechanical modules, compressing actuator specification cycles from 48 months to 24 months.
Integrated smart actuators with embedded Hall-effect position sensing and edge computing capability are absorbing diagnostic functions previously handled by separate ECUs. Tier-1 suppliers at Magna and Kautex facilities are adopting these modules for electronic parking brake and active grille shutter applications. This consolidation is absorbing discrete sensor supplier margins while enabling over-the-air calibration updates that reduce warranty claims.
Health Canada and PMRA restrictions on PFAS-based lubricants in sealed motor housings are forcing reformulation of bearing greases and gear oils. Actuator manufacturers must validate alternative chemistries under accelerated thermal cycling protocols before 2026 compliance deadlines. The brushless DC segment faces the steepest requalification burden due to permanent magnet rotor adhesion requirements.
Fleet procurement teams at Canada Post and municipal transit authorities are unbundling actuator replacement from full subsystem contracts, creating direct sourcing relationships with refurbishment specialists. This disintermediation compresses OEM aftermarket revenue while expanding third-party actuator remanufacturing capacity in Mississauga and Calgary service hubs.
Canada Automotive Electric Actuators Market Segmentation
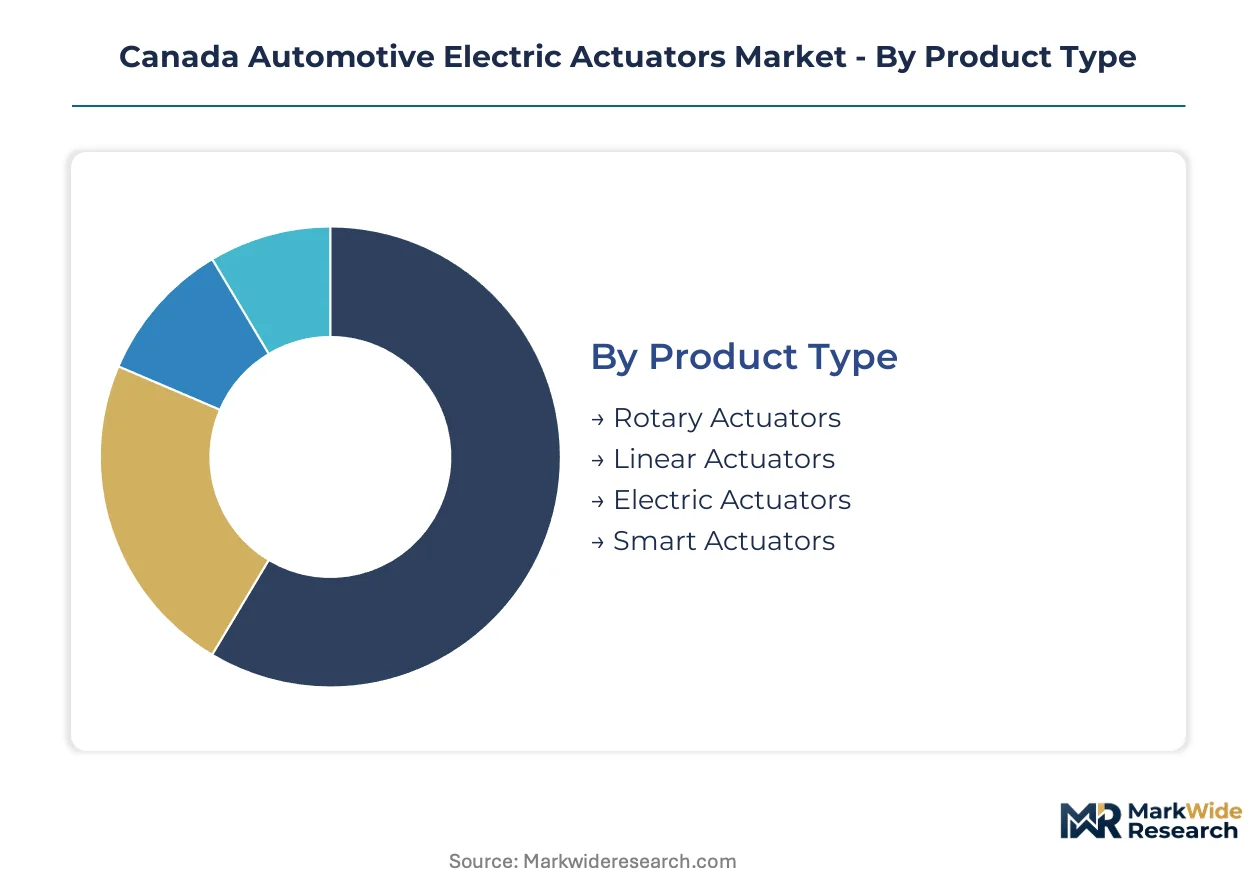
Segmentation reveals how certification requirements and supply chain positioning fragment revenue across actuator technologies. Each dimension carries distinct regulatory burdens and margin profiles that reshape supplier strategy.
Product Type:
Transport Canada CMVSS 126 mandates redundant fail-safe architectures for brake and steering actuators, imposing heavier validation burdens on electromechanical variants than on legacy hydraulic-electronic hybrids.
- Linear Actuators:Electromechanical devices converting rotary motor motion into precise linear displacement, typically deployed in electronic brake boosters and gear selector mechanisms. Demand concentrates at Windsor and Oshawa assembly plants serving Detroit Three light truck programs, driven by the shift from vacuum-assisted to electromechanical braking systems.
- Smart Actuators:Integrated modules embedding Hall-effect position sensing and edge computing capability for diagnostic functions. Western Canada mining and logging fleets in Alberta and British Columbia absorb capacity for predictive maintenance-enabled units, climbing fastest as fleet operators unbundle actuator replacement from full subsystem contracts.
- Rotary Actuators:Angular motion devices for throttle-by-wire and valve control applications in hybrid powertrains. Quebec zero-emission vehicle mandates expand deployment across electrified chassis architectures.
- Electric Actuators:General-purpose electromechanical units spanning 12-48V operating ranges for auxiliary vehicle functions. Aftermarket refurbishment channels in Mississauga and Calgary service hubs capture extended-duty commercial demand.
Linear actuators sit at the top of the volume ranking, with smart actuators climbing the fastest.
Application:
Cost tier differentiation separates mass-market brake and steering applications from premium HVAC and convenience systems, with the latter commanding higher per-unit margins.
- Brake Systems:Electronic brake boosters and brake-by-wire actuators requiring ASIL-D functional safety compliance. The Great Lakes automotive corridor spanning Windsor, Oshawa, and the Golden Horseshoe manufacturing belt concentrates production capacity for just-in-sequence delivery to Detroit Three transplants.
- HVAC Systems:Brushless DC flap control actuators integrated with cabin air quality sensors for multi-zone climate management. Electric pickup truck programs absorb expanding capacity as thermal management complexity rises with battery-electric architectures.
- Power Steering:Electric power steering actuators operating at torque outputs from 2-50 Nm. Ontario and Quebec assembly plants drive adoption across integrated cross-border supply chains.
- Door Controls:Compact electromechanical units for power sliding doors and liftgate mechanisms. Light truck platforms prioritize these actuators for premium trim differentiation.
Brake systems generate the steepest revenue concentration, while HVAC systems gain share fastest on electric vehicle thermal management expansion.
End User:
Customer type determines procurement modality, with OEMs demanding multi-year supply agreements and aftermarket providers pursuing spot-market refurbishment contracts.
- OEMs:Original equipment manufacturers specifying actuators for new vehicle programs with 48-month to 24-month compressed development cycles. Transport Canada motor vehicle safety standards and zero-emission vehicle mandates reshape specification requirements across the supply base.
- Tier-1 Suppliers:Integrated subsystem providers configuring brake and steering modules for just-in-sequence delivery. Robert Bosch and Continental anchor positions through electromechanical specialization and brushless DC motor expertise.
- Aftermarket Providers:Third-party remanufacturing specialists serving extended-duty commercial fleets. Direct sourcing relationships with Canada Post and municipal transit authorities bypass traditional distribution channels.
- Vehicle Assemblers:Final assembly operations in Windsor, Oshawa, and the Golden Horseshoe managing actuator integration into complete vehicle systems. Proximity to Detroit Three transplants positions these facilities for cross-border program participation.
OEMs command the dominant value position, with aftermarket providers expanding most quickly through fleet disintermediation.
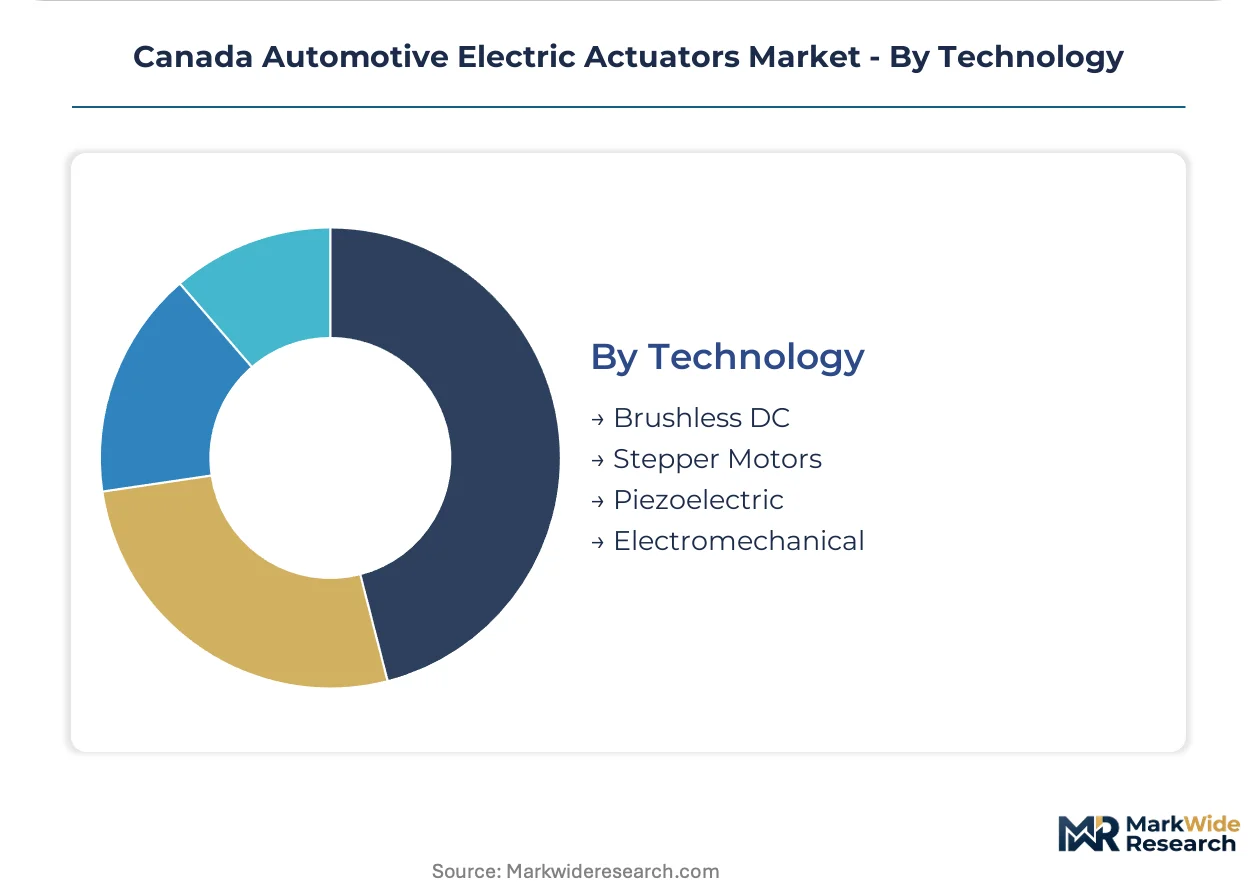
Technology:
Maturity curves separate established brushless DC architectures from emerging piezoelectric alternatives, with semiconductor content and rare earth magnet dependency driving input cost volatility.
- Brushless DC:Permanent magnet synchronous motors dominating power steering and HVAC applications. Health Canada and PMRA restrictions on PFAS-based lubricants force bearing grease reformulation before compliance deadlines.
- Electromechanical:Integrated motor-gearbox assemblies for linear and rotary motion control. Neodymium and dysprosium price volatility creates input cost instability for manufacturers serving commercial vehicle segments.
- Stepper Motors:Open-loop position control devices for low-torque auxiliary functions. Cost-sensitive applications in door controls and minor HVAC adjustments absorb capacity.
- Piezoelectric:Solid-state actuation using ceramic crystal deformation for ultra-precise positioning. Prototype steer-by-wire systems face Transport Canada regulatory friction on fail-safe approval timelines.
Brushless DC holds the volume lead, with electromechanical variants gaining fastest on electronic brake booster proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian automotive electric actuators industry traces its modern scale to post-NAFTA integration, when Ontario assembly plants adopted Detroit Three supply chain standards and cross-border component flows accelerated through the Great Lakes corridor.
Ontario
Electronic brake boosters and power steering actuators absorb the dominant production capacity, driven by Detroit Three light truck programs at Windsor and Oshawa facilities. Transport Canada CMVSS 126 mandates reshape specification requirements for redundant fail-safe architectures. The Golden Horseshoe manufacturing belt concentrates just-in-sequence actuator delivery contracts with integrated cross-border supply chains.
Quebec
Zero-emission vehicle mandates expand demand for throttle-by-wire and electronic valve control actuators across hybrid powertrain architectures. Provincial electrification programs accelerate chassis component electrification timelines. Assembly plants around Montreal anchor production for electrified vehicle platforms serving North American export markets.
Alberta
Extended-duty mining and logging fleets generate underpenetrated demand for predictive maintenance-enabled smart actuators with embedded position sensing. Commercial vehicle operators seek 15-year lifecycles through direct refurbishment relationships. Calgary service hubs develop remanufacturing capacity for brushless DC motor modules.
British Columbia
Provincial zero-emission vehicle mandates parallel Quebec's electrification trajectory, expanding actuator deployment in battery-electric commercial vehicles. Vancouver-area suppliers configure HVAC flap control systems for electric pickup thermal management. Cross-Pacific supply chain connections expose the region to semiconductor allocation constraints during automotive chip shortages.
Atlantic Canada
Smaller-scale assembly operations and Tier-2 supplier networks support regional commercial vehicle demand with limited actuator integration capacity. Federal industrial policy incentives attract battery-electric component investments. Halifax logistics corridors position the region for emerging Atlantic Canadian electric vehicle supply chain development.
Canada Automotive Electric Actuators Market Competitive Environment
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D compliant brake and steering actuators commanding pricing separation from auxiliary HVAC and door control units. The supplier base consolidates around integrated electromechanical module providers capable of 24-month development cycles versus legacy 48-month timelines. Three archetypes dominate: diversified global Tier-1s with power steering specialization, brushless DC motor specialists with HVAC expertise, and regional refurbishment operators capturing fleet disintermediation. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers securing just-in-sequence delivery contracts through proximity to Windsor and Oshawa assembly plants.
Within the diversified Tier-1 tier, Robert Bosch and Continental anchor positioning through integrated electromechanical module capabilities, while Denso Corporation represents the Japanese multinational archetype with established North American transplant relationships. These three exemplify how global scale combines with regional production presence to secure multi-year supply agreements with Detroit Three programs.
| Leading Market Players |
|---|
| Robert Bosch |
| Denso Corporation |
| Continental |
| Mitsubishi Electric |
| Aptiv PLC |
| Valeo |
| ZF Friedrichshafen |
| Johnson Electric |
| BorgWarner |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Ontario's Golden Horseshoe manufacturing belt anchor supply discipline through captive production of brushless DC motor subassemblies, translating upstream control into pricing power at Windsor and Oshawa assembly plants. Their integration insulates contract negotiations from rare earth magnet volatility while compressing margin leakage to commodity distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs actuator procurement, with ASIL-D functional safety certification and just-in-sequence delivery capability separating premium brake and steering contracts from auxiliary HVAC tiers. Price differentiation hinges on embedded position sensing density and Transport Canada CMVSS 126 validation burden. Cost compression in standard-tier linear actuators is intensifying because semiconductor allocation constraints force foundry premium payments. Fleet procurement teams at Canada Post exhibit the sharpest price sensitivity, while OEM platform engineers prioritize certification reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for electronic brake boosters and power steering modules, bypassing Tier-1 subsystem bundling to capture margin. Geographic supply concentration draws from China for neodymium and dysprosium permanent magnets, Taiwan for MCU and gate driver semiconductors, and Mexico for stamped metal housings. Raw material dependencies rest on rare earth magnet alloys, automotive-grade silicon wafers, and PFAS-free bearing greases. Single-source semiconductor vulnerability from Asian foundries exposes Canadian actuator suppliers to allocation rationing during automotive chip shortages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quebec's zero-emission vehicle mandates create a regulatory cost differential against Ontario's Detroit Three supply base, positioning Montreal-area suppliers for geographic arbitrage in electrified chassis component sourcing.
For Market Incumbents: Deepen backward integration into brushless DC motor winding operations to defend margin position against rare earth magnet price spikes. Secure redundant semiconductor sourcing from secondary foundries to mitigate single-source allocation risk. Prioritize ASIL-D certification investment ahead of Transport Canada CMVSS 126 implementation deadlines to lock in brake-by-wire contract renewals. For New Entrants and Emerging Players: Direct-to-fleet digital platforms bypass traditional aftermarket distribution, enabling predictive maintenance-enabled smart actuator sales to Alberta mining operators. Western Canada commercial vehicle refurbishment presents the most penetrable white space, with 15-year lifecycle demands unmet by incumbent OEM channels. Target embedded position sensing integration as the primary go-to-market differentiator against commodity linear actuator providers. For Investors and Strategic Acquirers: Tier-1 electromechanical module specialists with proven just-in-sequence delivery contracts are the most active acquirer in this space, consolidating brushless DC motor capabilities to compress development cycles. Long-term viability centers on software-defined vehicle architecture readiness and 24-month specification cycle execution. Watch Transport Canada steer-by-wire regulatory approval timelines as the critical inflection signal for fully electronic steering actuator market formation.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Backward Integration | Captive winding operations at Ontario facilities insulate margins from neodymium price volatility. |
| ASIL-D Certification Pre-Investment | Early validation ahead of Transport Canada CMVSS 126 deadlines secures brake-by-wire contract renewals. |
| Direct-to-Fleet Digital Channel Launch | Bypassing OEM aftermarket distribution captures margin from Alberta mining fleet refurbishment demand. |
| Secondary Foundry Semiconductor Sourcing | Redundant MCU supply from non-Taiwanese sources mitigates allocation risk during automotive chip shortages. |
| Embedded Position Sensing R&D Expansion | Hall-effect integration enables predictive maintenance capabilities for Western Canada extended-duty vehicles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors with secondary validation against vehicle production databases, IHS Markit registration data, Transport Canada CMVSS filings, and SEC disclosures from listed automotive component suppliers. Bottom-up actuator shipment estimates and top-down vehicle production projections were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic assembly volumes through post-chip-shortage recovery established baseline trajectory calibration across the projection horizon. Segmentation modeling captured product type, application, end user, and technology dimensions alongside vehicle class and propulsion architecture splits. CAGRs were derived from fitted growth curves incorporating zero-emission vehicle mandate penetration rates and electronic brake booster adoption timelines in light truck programs.
Regulatory implementation delays, rare earth export restrictions, and semiconductor allocation shocks are the dominant revision risks to forecast outputs. Forecasts reflect documented assumptions regarding Transport Canada rulemaking timelines and Detroit Three platform electrification commitments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
UK Automotive Eps Market