
 Automotive Sensor Cleaning System Market | 2026-2036
Automotive Sensor Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sensor Cleaning System Market Outlook
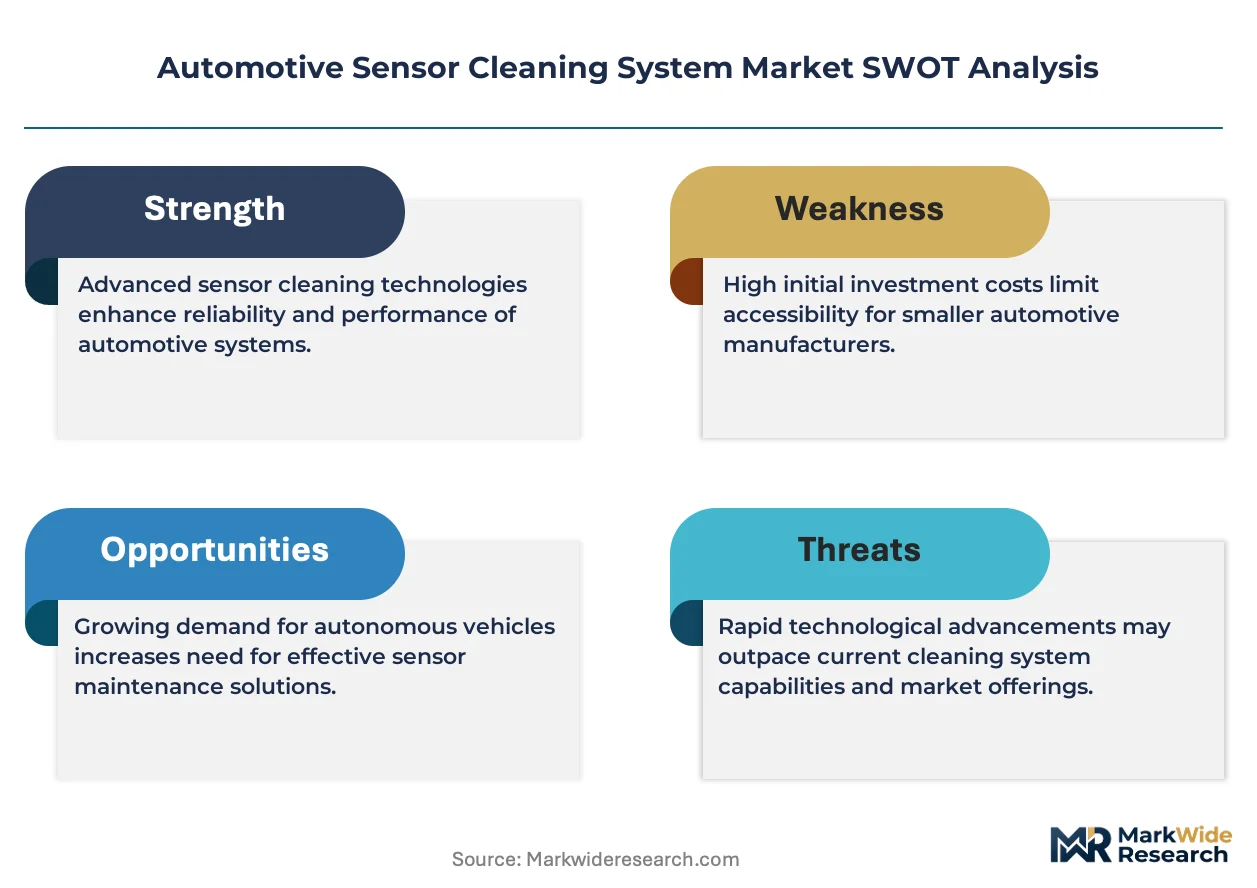
A capital-intensity divergence between full-system integrators and component suppliers is bifurcating competitive returns in the Automotive Sensor Cleaning System Market. Continental leverages captive electronics manufacturing to bundle cleaning hardware with sensor fusion stacks. Valeo sustains leadership in nozzle miniaturization through dedicated fluidics R&D centers in France. dlhBOWLES anchors North American supply with heated washer expertise migrated from legacy windshield platforms.
Automotive sensor cleaning systems combine precision fluid delivery, thermal management, and mechanical actuation to restore optical and acoustic sensor clarity under contamination events, operating across temperature ranges from minus forty to eighty-five degrees Celsius. Spray Systems dominate current OEM fitments due to proven compatibility with fused silica camera lenses and ultrasonic transducer housings. ADAS applications command the fastest expansion as lane-keeping and collision-avoidance suites proliferate across vehicle classes, concentrating margin pools in electrostatic and thermal technology tiers where integration complexity exceeds commodity mechanical alternatives.
FDA guidelines for automotive LiDAR eye-safety thresholds, EPA coolant toxicity restrictions on methanol-based washer fluids, and NHTSA automated driving system validation protocols collectively shape product architecture and material selection for sensor cleaning modules. The EU AI Act's forthcoming requirements for environmental robustness in automated decision systems will extend compliance obligations beyond traditional automotive homologation. Stakeholders must monitor divergence between regional chemical approval regimes and thermal efficiency standards to avoid platform fragmentation across export markets.
Market Dynamics
Level 2+ ADAS deployment timelines are compressing sensor cleaning module qualification cycles, forcing suppliers to synchronize fluidics engineering with camera-LiDAR fusion roadmaps.
Growth Catalysts
- EU Vehicle General Safety Regulation:Mandates for sensor performance under soiled conditions are accelerating compliance-driven design changes across German and French automotive clusters.
- Electrostatic cleaning technology:Eliminates fluid consumption in cold-climate operations, attracting OEM interest for electric vehicle platforms where thermal efficiency is prioritized.
- Stuttgart-Munich supplier corridor:Concentrated prototyping capabilities enable rapid iteration from validation to production for integrated cleaning-sensor modules.
Market Restraints
- Methanol-based washer fluid restrictions:EPA toxicity limitations on legacy chemistries are forcing reformulation investments that compress margins for fluid suppliers.
- Heated nozzle component concentration:North American supply for thermal management subsystems remains anchored to single-source foundry capacity, creating vulnerability.
- Lens coating incompatibility:Fused silica camera housings degrade under alkaline cleaning agents, constraining formulation flexibility for multi-sensor architectures.
Strategic Opportunities
- India PLI scheme for auto components:Localized manufacturing incentives are opening cost-competitive production bases for export-oriented cleaning module suppliers.
- Ultrasonic transducer cleaning:Untapped demand in parking-assist systems creates white space beyond camera-centric ADAS applications.
- AI Act environmental robustness requirements:Automated decision system mandates will extend compliance obligations to sensor hygiene validation protocols.
Industry Challenges
- Multi-physics simulation talent:Shortage of engineers fluent in coupled fluid-thermal-mechanical modeling delays virtual validation cycles.
- Homologation timeline compression:NHTSA automated driving system validation protocols require concurrent rather than sequential testing, straining certification bandwidth.
- Sensor fusion integration complexity:Cleaning system timing must synchronize with perception stack latency requirements, creating software-hardware co-design friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sensor Cleaning System Market |
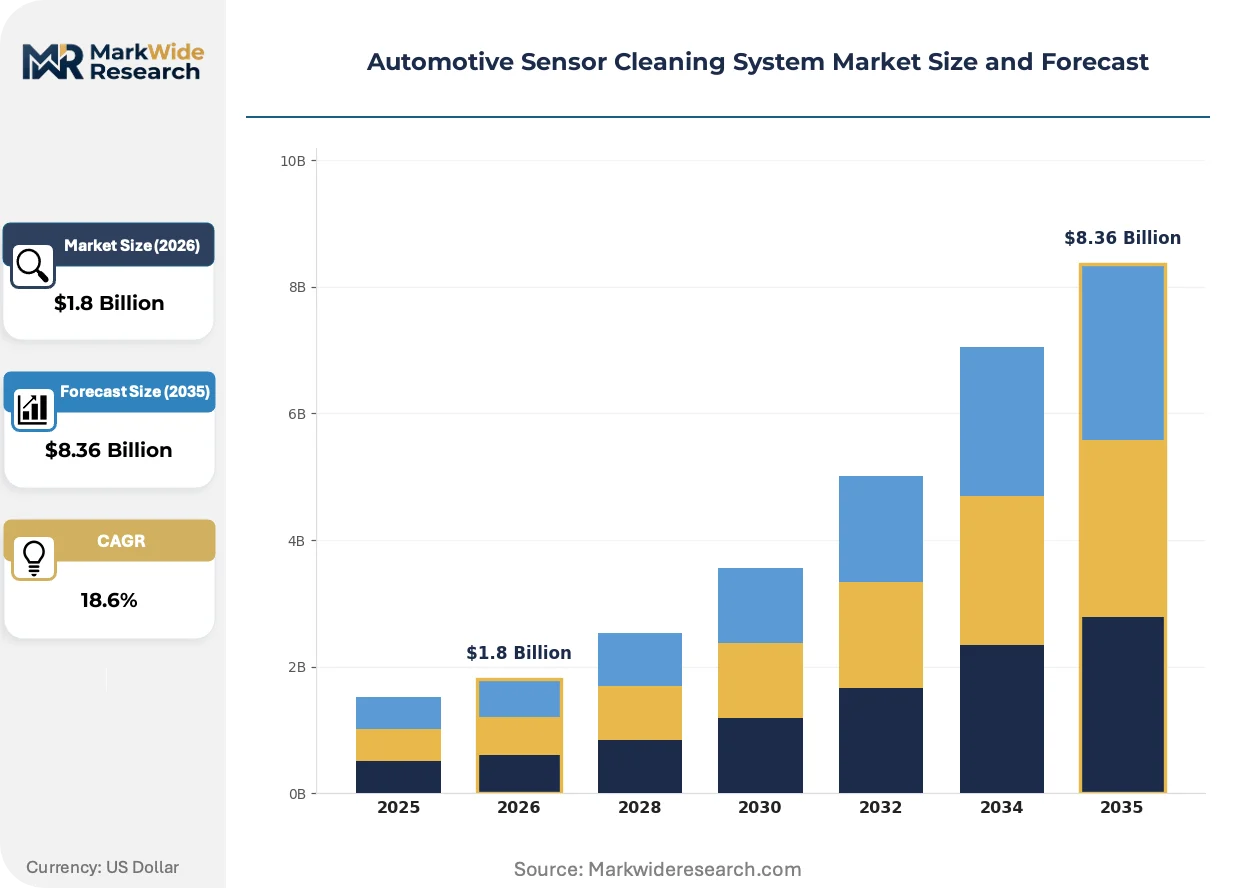
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Cleaners, Spray Systems, Wipe Solutions, Foam Cleaners Application: ADAS, Lane Keeping, Collision Avoidance, Parking Assistance End User: OEMs, Aftermarket Providers, Repair Shops, Fleet Operators Technology: Electrostatic, Thermal, Chemical, Mechanical |
| Companies Covered | Ficosa, Röchling Group, Continental, dlhBOWLES, Cebi Group, Vitesco Technologies, Kautex Textron, SEEVA Technologies, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sensor Cleaning System Market Strategic Shifts
Convergence between thermal management expertise and precision fluidics is redefining competitive capability requirements, with material selection and control algorithms emerging as primary differentiation vectors.
Electrostatic cleaning is supplanting spray-based architectures in premium electric vehicle programs. The technology uses ionized air streams to dislodge particulates without liquid residue, appealing to OEMs seeking to eliminate washer fluid reservoirs and pumps. Tier 1 suppliers with captive plasma generation expertise are capturing integration contracts that bundle cleaning with sensor fusion stacks.
REACH chemical authorization procedures are extending lead times for novel surfactant formulations. The ECHA evaluation framework now requires ecotoxicity dossiers for cleaning agents deployed in closed-loop vehicle systems. German automotive suppliers are responding by accelerating partnerships with specialty chemical firms holding existing substance registrations.
Fleet operators are unbundling sensor maintenance from traditional service packages. Commercial vehicle buyers now specify outcome-based contracts guaranteeing minimum detection ranges under defined contamination loads. This shift is most pronounced in German long-haul logistics, where downtime costs exceed hardware premiums for predictive cleaning system upgrades.
Automotive Sensor Cleaning System Market Segmentation
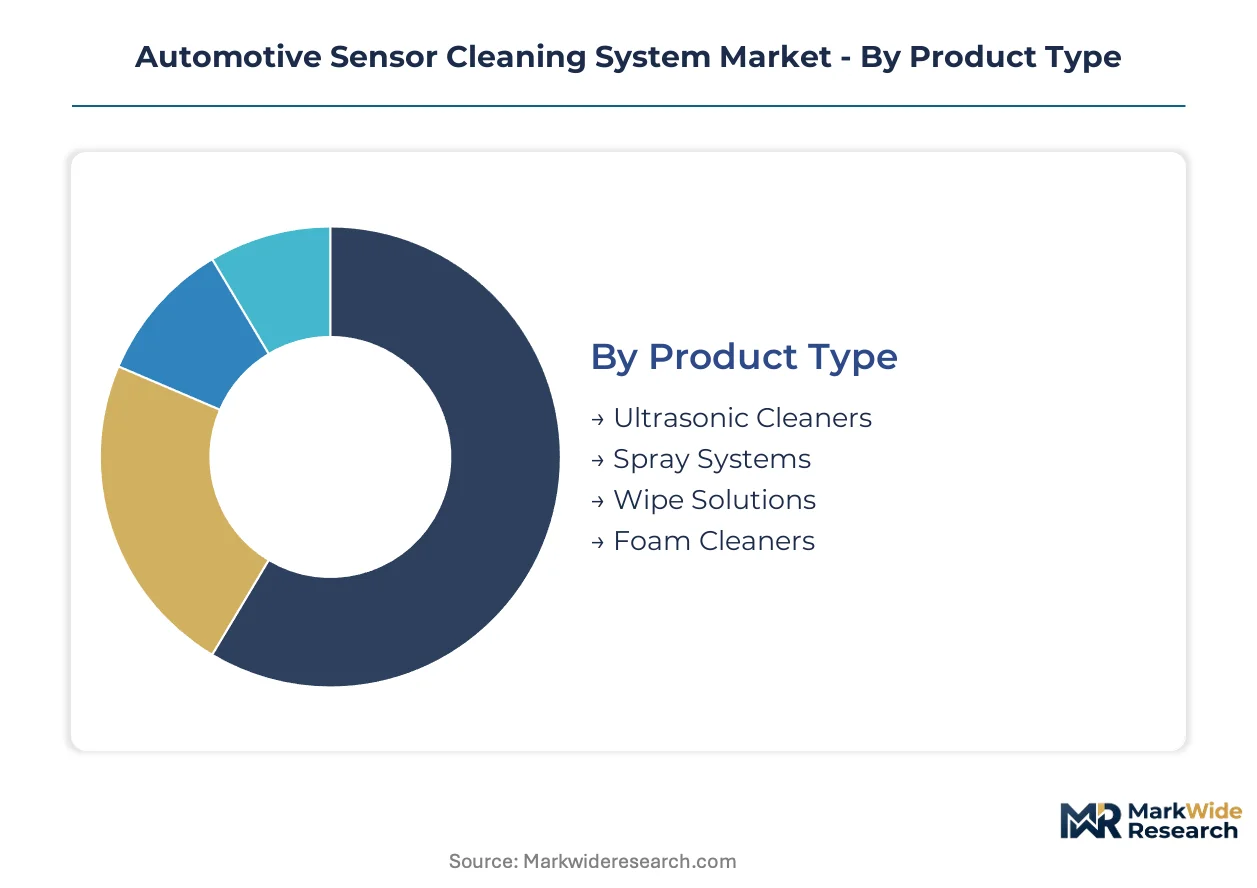
Segmentation in the Automotive Sensor Cleaning System Market reveals how cleaning architectures diverge across automation tiers and thermal requirements. Procurement patterns split between integrated OEM modules and distributed aftermarket servicing, with technology choices driven by climate exposure and sensor fusion complexity.
Product Type:
German and Japanese OEMs anchor domestic demand for precision-engineered systems, while export markets absorb higher volumes of standardized spray architectures.
- Spray Systems:Pressurized fluid delivery through micro-nozzles restores optical clarity across fused silica camera lenses and ultrasonic housings. Stuttgart-based Tier 1 suppliers dominate prototype-to-production cycles for integrated spray-LiDAR modules, driven by EU Vehicle General Safety Regulation compliance timelines.
- Ultrasonic Cleaners:High-frequency mechanical vibration dislodges particulates without liquid residue, enabling closed-loop operation in electric vehicle platforms. Japanese automotive clusters around Nagoya prioritize this technology for parking-assist sensor arrays where thermal efficiency constraints eliminate heated fluid alternatives.
- Wipe Solutions:Pre-moistened applicators serve aftermarket calibration procedures and repair shop sensor maintenance protocols.
- Foam Cleaners:Low-viscosity formulations target fleet operator mobile service units requiring rapid deployment without pressurized equipment.
Spray Systems command the established base. The steepest expansion runs through Ultrasonic Cleaners.
Application:
Cost tier stratification separates premium sensor fusion suites from single-function commodity installations across vehicle classes.
- ADAS:Multi-sensor architectures demand synchronized cleaning timing with perception stack latency requirements. Lane-keeping and collision-avoidance fusion stacks concentrate margin pools in electrostatic and thermal technology tiers where integration complexity exceeds mechanical alternatives.
- Collision Avoidance:Emergency braking systems require guaranteed detection range restoration under defined contamination loads, driving outcome-based procurement contracts in German long-haul logistics.
- Lane Keeping:Camera-centric installations favor spray-based architectures with proven compatibility across fused silica lens coatings.
- Parking Assistance:Ultrasonic transducer cleaning creates white space beyond camera-centric ADAS applications, with untapped demand in commercial vehicle proximity sensing.
ADAS captures the premium tier. Parking Assistance climbs the fastest from a smaller installed base.
End User:
Customer type determines integration depth, with OEMs specifying module-level contracts and fleet operators shifting toward performance-guaranteed service agreements.
- OEMs:Integrated cleaning-sensor module procurement bundles hardware with fusion stack roadmaps, compressing qualification cycles for Level 2+ ADAS deployment. Continental and Valeo anchor supply relationships through captive electronics manufacturing and dedicated fluidics R&D centers.
- Fleet Operators:Commercial vehicle buyers in North American and European logistics corridors now specify outcome-based contracts guaranteeing minimum detection ranges under defined contamination loads, prioritizing predictive cleaning system upgrades over hardware premiums.
- Aftermarket Providers:Distributed service networks address sensor degradation outside warranty periods, constrained by lens coating incompatibility with alkaline cleaning agents.
- Repair Shops:Calibration equipment investments limit participation to specialized facilities clustered around German automotive supplier corridors.
OEMs dominate volume concentration. Fleet Operators gain share fastest through service model innovation.
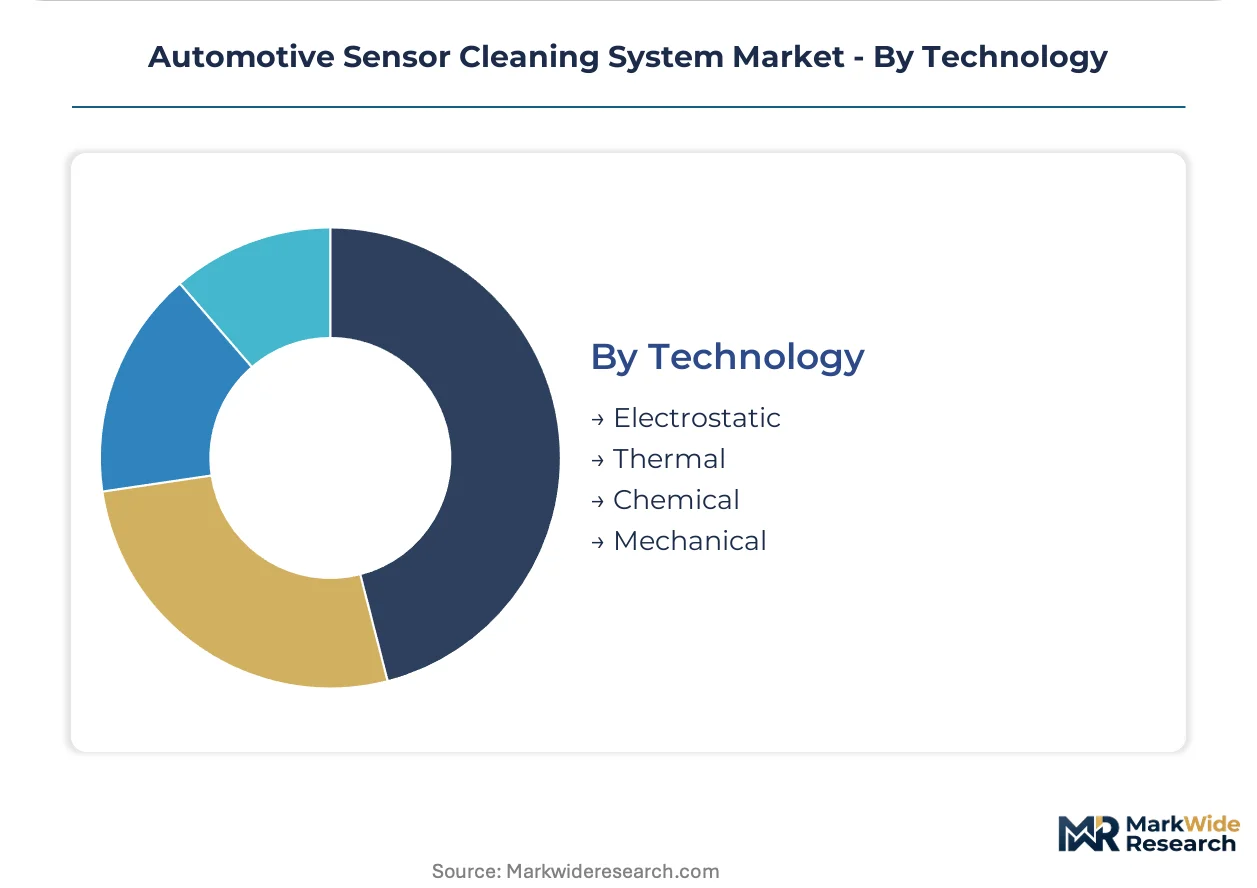
Technology:
Supply concentration in thermal management subsystems creates vulnerability for heated nozzle architectures, while electrostatic alternatives attract new entrants with plasma generation expertise.
- Electrostatic:Ionized air streams eliminate fluid consumption and washer fluid reservoirs, appealing to OEMs prioritizing thermal efficiency in electric vehicle platforms. Tier 1 suppliers with captive plasma generation expertise capture integration contracts bundling cleaning with sensor fusion stacks.
- Thermal:Heated nozzles and washer fluid circuits maintain operation across minus forty to eighty-five degrees Celsius ranges, with North American supply anchored to single-source foundry capacity for component subsystems.
- Chemical:Surfactant formulations face REACH authorization delays and EPA toxicity restrictions on methanol-based legacy chemistries, forcing reformulation investments.
- Mechanical:Physical actuation and wiper-based architectures serve cost-sensitive applications with lower automation tier requirements.
Thermal technology holds the installed base. Electrostatic systems expand most quickly in premium electric vehicle programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing premiums for integrated cleaning-sensor modules while Chinese suppliers compete on standardized spray architectures. This asymmetry reflects divergent regulatory stringency and automation tier concentration across automotive manufacturing clusters.
Germany
KBA homologation protocols and EU Vehicle General Safety Regulation mandates drive OEM procurement of validated cleaning systems for Level 2+ ADAS platforms. Stuttgart and Munich anchor prototype-to-production cycles, with Tier 1 suppliers compressing qualification timelines to synchronize with sensor fusion roadmaps. The supplier corridor concentrates fluidics engineering talent and captive electronics manufacturing.
United States
NHTSA automated driving system validation protocols force concurrent testing regimes that strain certification bandwidth for cleaning module suppliers. EPA toxicity restrictions on methanol-based washer fluids compel reformulation investments across fluid suppliers. Michigan and Ohio manufacturing clusters host heated nozzle component production, though single-source foundry capacity creates supply vulnerability.
China
MIIT new energy vehicle mandates prioritize thermal efficiency in sensor cleaning architectures for domestic electric vehicle platforms. Dual carbon goals accelerate electrostatic technology adoption to eliminate washer fluid reservoirs. Yangtze River Delta automotive clusters around Shanghai integrate cleaning modules with local LiDAR and camera supply chains.
Japan
METI industrial standards for automated driving systems emphasize environmental robustness validation for sensor hygiene protocols. Nagoya automotive clusters prioritize ultrasonic cleaning technology for parking-assist sensor arrays where thermal constraints eliminate heated fluid alternatives. Domestic OEMs specify closed-loop operation for electric vehicle platforms.
India
PLI scheme incentives for auto components attract localized manufacturing investment from export-oriented cleaning module suppliers. BIS certification requirements for automotive subsystems create compliance barriers that favor established Tier 1 relationships. Tamil Nadu and Maharashtra clusters develop cost-competitive production bases for spray system architectures.
Automotive Sensor Cleaning System Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with full-system integrators capturing premium margins through bundled sensor fusion stacks while component specialists compete on standardized architectures. The vendor base splits between captive electronics manufacturers with in-house fluidics capabilities and dedicated nozzle or thermal subsystem suppliers. Three archetypes dominate: integrated platform providers, precision fluidics specialists, and thermal management component suppliers. Strategic moves concentrate on M&A for sensor fusion integration and capacity expansion in heated nozzle foundries.
Among European-anchored integrated platform providers, Continental and Valeo occupy positions representing bundled electronics-fluidics capabilities, while dlhBOWLES exemplifies North American specialization migrated from legacy windshield platforms. These three names illustrate the geographic and capability bifurcation shaping procurement decisions across OEM and fleet operator segments.
| Leading Market Players |
|---|
| Ficosa |
| Röchling Group |
| Continental |
| dlhBOWLES |
| Cebi Group |
| Vitesco Technologies |
| Kautex Textron |
| SEEVA Technologies |
| Valeo |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts anchor procurement for heated nozzle subsystems and precision fluidics modules, locking in supply access for OEMs while compressing margin visibility for component suppliers facing EPA reformulation mandates and REACH authorization delays.
Pricing Analysis
Configured-to-order pricing for integrated cleaning-sensor modules commands substantial premiums over standardized spray architectures. Three-tier pricing structure across premium, standard, and economy levels separates electrostatic systems bundled with sensor fusion stacks from commodity mechanical alternatives. Cost compression in thermal management tiers is intensifying because single-source foundry concentration limits supplier leverage. Fleet operators exhibit the lowest price sensitivity due to outcome-based contracts prioritizing uptime guarantees.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and Japanese automotive clusters where qualification cycles compress delivery windows. Supply concentrates in Germany, China, and Mexico for precision nozzle manufacturing and heated washer component fabrication. Production draws from fused silica lens substrates, methanol-free surfactant formulations, and plasma generation equipment. Single-source foundry vulnerability for thermal subsystems creates structural risk. Distribution runs through Tier 1 integrators directly to OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Sensor Cleaning System Market sits at a regulatory-technology inflection where EU Vehicle General Safety Regulation mandates and Level 2+ ADAS deployment timelines are compressing competitive windows.
For Market Incumbents: Shield integrated platform positions by deepening backward integration into plasma generation capabilities before electrostatic technology displaces thermal architectures in premium electric vehicle programs. Accelerate capacity addition in Yangtze River Delta clusters to offset single-source heated nozzle vulnerability in North American supply chains. For New Entrants and Emerging Players: Lead with ultrasonic transducer cleaning specialization for parking-assist systems in commercial vehicle segments where camera-centric incumbents have limited penetration. Target India's PLI scheme incentives for cost-competitive spray system production serving export markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision fluidics specialists with captive electronics manufacturing. Long-term viability centers on suppliers capable of bundling cleaning hardware with sensor fusion validation protocols. Watch for divergence between regional chemical approval regimes as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces qualification cycles for Level 2+ ADAS cleaning modules across German OEM roadmaps. |
| Backward Integration into Fluidics | Captures margin pools from REACH-authorized surfactant formulations and nozzle miniaturization. |
| Software-Defined Vehicle Investment | Enables cleaning system timing synchronization with perception stack latency requirements. |
| Geographic Manufacturing Footprint | PLI scheme localization in Tamil Nadu creates cost-competitive export bases for spray architectures. |
| Charging Infrastructure Partnership | Extends electrostatic cleaning adoption through thermal efficiency alignment with electric vehicle platforms. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers; and secondary validation through vehicle production databases, IHS Markit registration data, EPA chemical filings, and ECHA substance dossiers. Bottom-up and top-down triangulation reconciled component-level cost builds with aggregate OEM procurement patterns.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs emerged from coupled fluid-thermal-mechanical adoption curves and sensor fusion integration timelines. Forecast inputs incorporated EU AI Act environmental robustness requirements and NHTSA validation protocol evolution.
The analysis sits within stated boundaries; outcomes outside sustained Level 2+ ADAS deployment acceleration or abrupt REACH chemical authorization delays would require recalibration. Forecasts reflect assumptions about thermal management technology persistence and electrostatic system cost curves. Revision becomes warranted when single-source foundry concentration for heated nozzles crosses supply disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Subframe Market
Automotive Components
Global Automotive Gears Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Glass Film Market