
 Hypertonic Drinks Market | 2026-2036
Hypertonic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertonic Drinks Market Analysis
The EU Green Deal is repositioning beverage formulation priorities across Europe, pushing manufacturers toward lower-sugar hypertonic profiles and biodegradable packaging matrices. PepsiCo leverages its North American bottling infrastructure to dominate shelf placement in mass retail channels. Red Bull GmbH differentiates through extreme-sports sponsorship density and pharmacy-grade electrolyte sourcing. Suntory Holdings Limited anchors Asian market penetration through convenience-store exclusivity agreements in Japan.
Hypertonic drinks contain dissolved solute concentrations exceeding plasma osmolality, typically formulated with glucose polymers at densities above 330 mOsm/L to accelerate intestinal water absorption during prolonged exertion. These beverages serve commercial purposes spanning athletic glycogen restoration, clinical rehydration for gastrointestinal patients, and occupational heat-stress management. Sports Drinks occupy the largest revenue pool due to established brand equity and stadium vending contracts, while Electrolyte Solutions represent the fastest-expanding category as medical practitioners prescribe hospital-grade formulations for post-surgical recovery. Nutritional Supplements concentrate margin capture through direct-to-consumer subscription models and personalized hydration profiling.
The FDA governs hypertonic drink labeling under food additive regulations, requiring quantitative electrolyte disclosure and prohibiting unsubstantiated performance claims. EFSA mandates novel food assessments for innovative carbohydrate blends entering European commerce, extending approval timelines for reformulated products. China's SAMR enforces GB standard compliance for osmolarity thresholds, restricting import access for non-conforming foreign brands. Stakeholders must monitor evolving sodium-content caps and front-of-pack warning systems as these regulatory instruments reshape permissible formulation architectures and channel access across key demand territories.
Market Dynamics
The EU F-Gas Regulation and packaging waste directives are compressing formulation freedom and forcing rapid retooling of bottling infrastructure toward recyclable formats and reduced carbon footprints.
Growth Catalysts
- Professional Sports Procurement:Elite football clubs and Olympic training centers in Germany are expanding procurement of hypertonic formulations for rapid glycogen replenishment, sustaining above-average per-capita consumption.
- EFSA Novel Food Pathways:The European Food Safety Authority's assessment framework for innovative carbohydrate blends is creating regulated entry channels for reformulated products with enhanced electrolyte density.
- Clinical Prescription Expansion:Hospital-grade electrolyte solutions are gaining traction as medical practitioners increasingly prescribe hypertonic formulations for post-surgical recovery and gastrointestinal patient rehydration.
Market Restraints
- Input Cost Volatility:Glucose polymer supply chains face pressure from agricultural commodity swings, directly compressing margins on formulations exceeding 330 mOsm/L density thresholds.
- Regulatory Friction:China's SAMR enforces GB standard compliance for osmolarity thresholds, restricting import access for non-conforming foreign brands and fragmenting international expansion.
- Substitution Pressure:Isotonic and hypotonic alternatives threaten volume in casual fitness segments where consumers prioritize palatability over maximum electrolyte delivery.
Strategic Opportunities
- Underpenetrated Occupational Segments:Heat-stress management applications in construction, mining, and agriculture remain underserved relative to athletic end-uses, offering white space for purpose-branded formulations.
- EU Green Deal Tailwinds:The European Green Deal's packaging mandates and lower-sugar priorities reward early movers deploying biodegradable matrices and reduced-glycemic carbohydrate sources.
- Direct-to-Consumer Subscriptions:Personalized hydration profiling through at-home electrolyte testing kits is opening recurring revenue streams outside traditional retail and stadium vending channels.
Industry Challenges
- Reformulation Timeline Compression:EFSA novel food assessments extend approval timelines, forcing R&D teams to parallel-track multiple carbohydrate blend candidates.
- Packaging Reconfiguration Costs:Recyclable bottle format transitions require capital-intensive retooling of filling lines and supply agreements with virgin plastic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertonic Drinks Market |
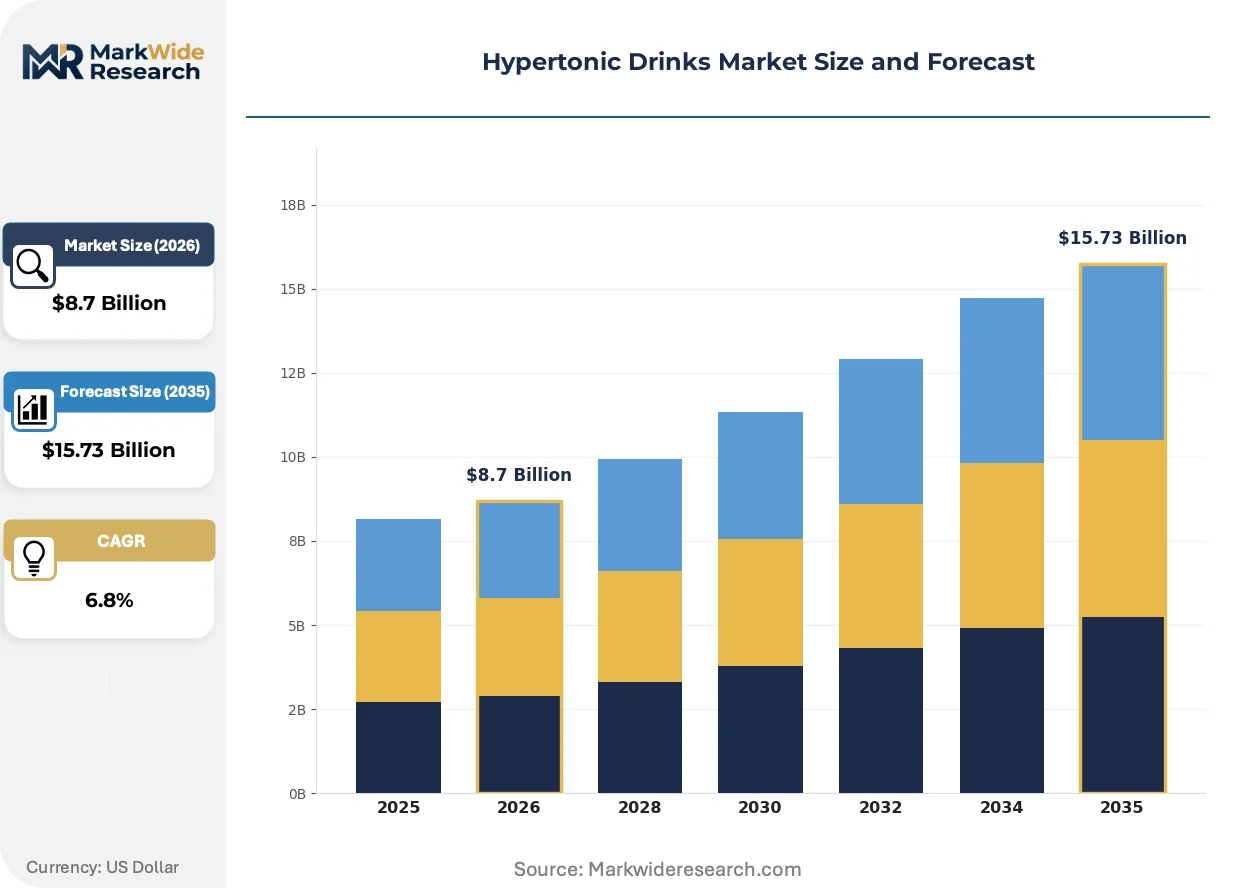
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Drinks, Energy Beverages, Electrolyte Solutions, Nutritional Supplements End User: Athletes, Fitness Enthusiasts, Casual Users, Medical Patients Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms Package Type: Bottles, Cans, Pouches, Powder Mixes |
| Companies Covered | PepsiCo, Monster Beverage Company, Red Bull GmbH, Coca-Cola Company, Nestle S.A., Abbott Nutrition Co., Lucozade Ribena Suntory, Suntory Holdings Limited, Britvic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertonic Drinks Market Emerging Trajectories
Formulation science and regulatory architecture are converging to reshape how hypertonic beverages are composed, certified, and delivered to end-users across athletic, clinical, and occupational settings.
Precision osmolarity tuning technology is modularizing production workflows. Manufacturers now deploy inline refractometry and automated batch correction to hit exact mOsm/L targets without manual intervention. Pharmaceutical-grade electrolyte sourcing teams at Red Bull GmbH and specialized compounders are adopting these systems to reduce batch-to-batch variance. The technology is modularizing quality assurance into discrete, swappable process units that smaller contract manufacturers can license rather than build.
REACH and the EU F-Gas Regulation are tightening scrutiny of synthetic cooling agents and propellants used in aerosolized delivery formats. Industrial consequence includes accelerated phase-out of hydrofluorocarbon-based packaging innovations and pivot toward mechanical pump systems. Sports drink segments targeting extreme-environment athletes are most affected, with German and Dutch formulators already submitting pre-registration dossettes for alternative pressurization methods.
Subscription-based replenishment models are displacing single-transaction retail purchases among endurance athletes and clinical dietitians. Direct-to-consumer platforms offering personalized electrolyte profiling are capturing share from pharmacy and stadium vending channels. This behavioral shift is most visible in Japan and South Korea, where convenience-store exclusivity agreements are being renegotiated to accommodate hybrid online-offline fulfillment.
Hypertonic Drinks Market Segmentation
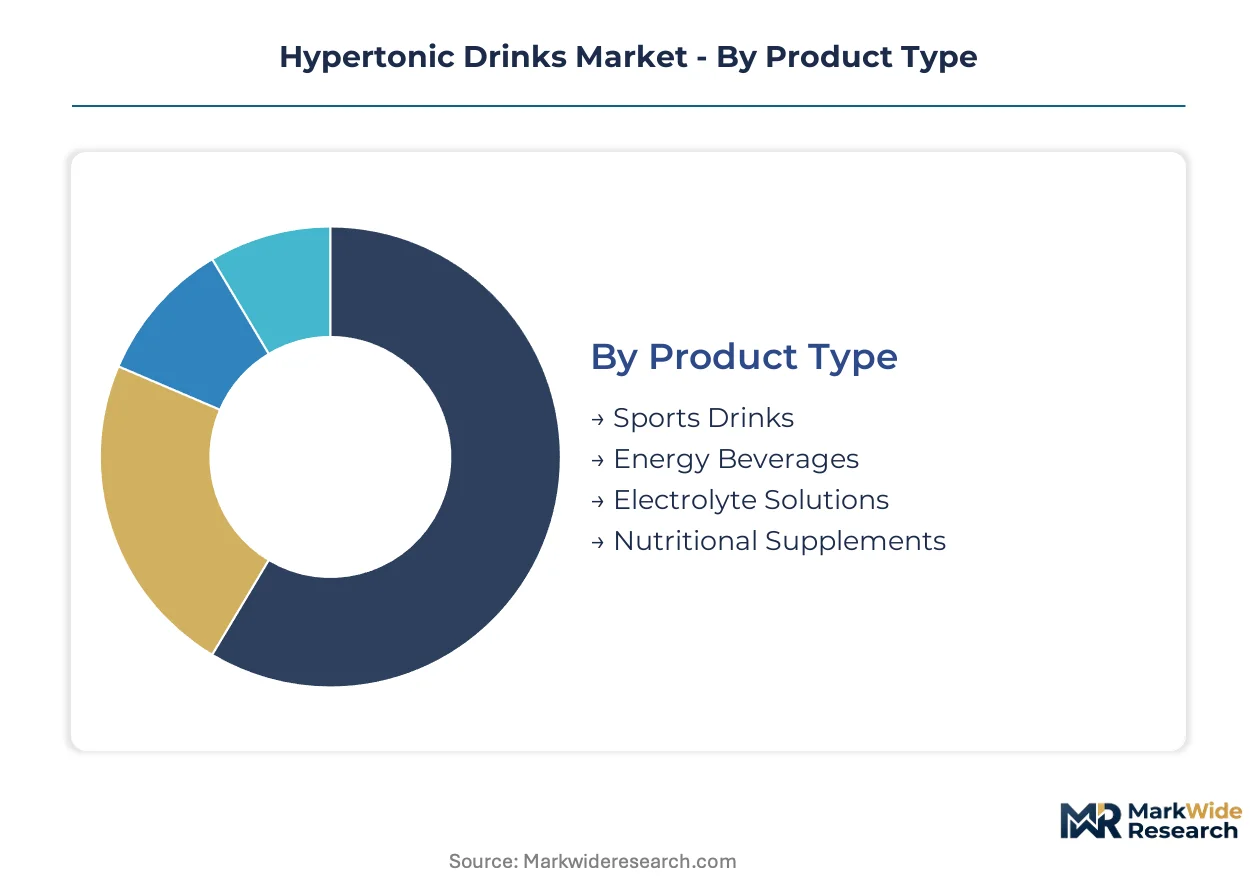
Hypertonic drinks serve divergent physiological needs across athletic performance, clinical recovery, and occupational safety. Segmentation reveals how formulation density, channel access, and packaging format determine margin capture and regulatory exposure.
Product Type:
Sports Drinks dominate volume through stadium vending contracts and mass retail shelf placement, while Electrolyte Solutions command premium pricing in controlled clinical channels.
- Sports Drinks:Formulated with glucose polymers at 330-400 mOsm/L for rapid glycogen replenishment during prolonged exertion. German football clubs and Olympic training centers sustain above-average procurement rates for high-osmolality recovery formulations.
- Electrolyte Solutions:Hospital-grade formulations with precise sodium-potassium ratios for post-surgical rehydration and gastrointestinal patient management. Medical practitioners in Japan and South Korea are expanding prescription volumes for controlled clinical recovery protocols.
- Energy Beverages:Caffeine-adjunct hypertonic blends targeting cognitive performance alongside physical exertion.
- Nutritional Supplements:Direct-to-consumer subscription models with personalized hydration profiling and at-home electrolyte testing integration.
Mature deployment sits with Sports Drinks. Newer deployment is concentrated in Electrolyte Solutions.
End User:
Professional procurement patterns diverge sharply from casual consumption, with institutional buyers prioritizing batch-certified osmolarity over palatability.
- Athletes:Elite competitors require glucose polymer densities exceeding 330 mOsm/L for intestinal water absorption optimization. Olympic training centers in Germany enforce strict procurement specifications for glycogen restoration protocols.
- Medical Patients:Post-surgical and gastrointestinal cases drive demand for pharmacy-grade electrolyte density with documented absorption kinetics. Hospital formularies in Japan are standardizing hypertonic prescriptions for controlled rehydration.
- Fitness Enthusiasts:Amateur endurance athletes balancing performance needs with taste accessibility.
- Casual Users:Heat-stress management in occupational settings with lower osmolarity tolerance thresholds.
Volume concentrates with Athletes. Margin expansion is accelerating fastest among Medical Patients.
Distribution Channel:
Channel selection determines regulatory scrutiny intensity, with pharmacy and clinical pathways requiring EFSA novel food documentation that mass retail bypasses.
- Supermarkets:Mass retail shelf placement rewards brand equity and bottling infrastructure scale. PepsiCo leverages North American distribution networks to secure dominant positioning in high-velocity grocery formats.
- Online Retail:Direct-to-consumer platforms enable personalized hydration profiling and subscription-based replenishment. Japanese and South Korean markets are renegotiating convenience-store exclusivity agreements to accommodate hybrid fulfillment models.
- Health Stores:Pharmacy-adjacent channels with trained staff capable of explaining osmolarity specifications to clinical dietitians.
- Gyms:Immediate post-workout consumption with vending-machine placement tied to equipment manufacturer partnerships.
Scale advantages cluster in Supermarkets. Subscription economics are displacing single-transaction models fastest in Online Retail.
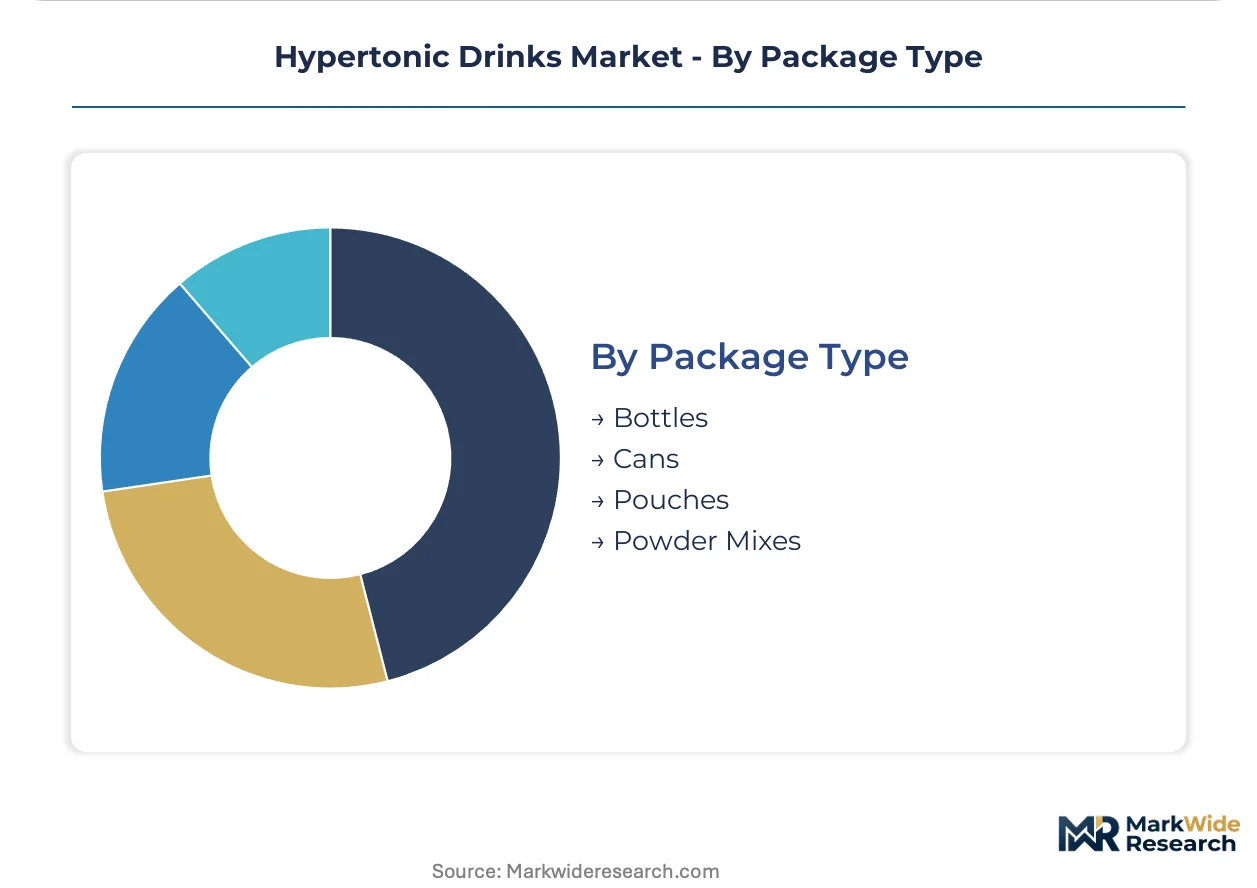
Package Type:
EU F-Gas Regulation and packaging waste directives are forcing rapid retooling toward recyclable formats, with carbon footprint now a procurement criterion for institutional buyers.
- Bottles:Recyclable PET formats are becoming mandatory for stadium vending contracts and Olympic training center procurement. German formulators are submitting pre-registration dossettes for alternative pressurization methods compliant with REACH.
- Powder Mixes:Reduced shipping weight and extended shelf life appeal to direct-to-consumer subscription models. Personalized hydration profiling platforms in Japan are integrating at-home electrolyte testing kits with powder sachet replenishment.
- Cans:Aluminum formats with mechanical pump systems replacing hydrofluorocarbon-based aerosolized delivery for extreme-environment athletes.
- Pouches:Flexible packaging for single-serve occupational heat-stress management in construction and mining sites.
Regulatory compliance investment is heaviest in Bottles. Format innovation is expanding most quickly in Powder Mixes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European hypertonic beverage procurement through its concentration of Olympic training centers and football club headquarters. German electrolyte-dense recovery formulations command premium shelf placement across mass retail and institutional channels. The Rhine-Main corridor's logistics infrastructure distributes high-osmolality products throughout Central Europe.
Germany
Bavarian Olympic training centers and North Rhine-Westphalian football clubs sustain above-average per-capita consumption of glycogen restoration beverages. EFSA novel food assessments for innovative carbohydrate blends extend approval timelines for reformulated products entering German commerce. Berlin-Brandenburg formulators submit pre-registration dossettes for alternative pressurization methods compliant with REACH and the EU F-Gas Regulation.
United States
Mass retail shelf placement rewards bottling infrastructure scale and stadium vending contract density. FDA food additive regulations govern hypertonic drink labeling and prohibit unsubstantiated performance claims. Greater Boston's sports nutrition clusters and Pacific Northwest endurance athlete communities drive direct-to-consumer subscription adoption for personalized hydration profiling.
Japan
Convenience-store exclusivity agreements anchor distribution for pharmacy-grade electrolyte formulations targeting clinical recovery protocols. METI oversees industrial standards for osmolarity measurement equipment deployed in manufacturing facilities. Tokyo-Osaka corridor hospitals standardize hypertonic prescriptions for post-surgical rehydration, expanding medical channel volumes.
China
SAMR enforces GB standard compliance for osmolarity thresholds, restricting import access for non-conforming foreign brands. Yangtze River Delta manufacturing clusters produce glucose polymers at scale for domestic formulation. Shanghai-based distributors navigate fragmented provincial regulations to secure pharmacy channel placement for hospital-grade electrolyte solutions.
South Korea
Seoul Capital Area endurance athletes displace single-transaction retail purchases through subscription-based replenishment platforms. MFDS regulates medical-grade electrolyte density claims for products targeting post-surgical recovery. Busan-Ulsan logistics hubs facilitate hybrid online-offline fulfillment models renegotiating traditional convenience-store exclusivity structures.
Hypertonic Drinks Market Vendor Landscape
The competitive structure tilts toward diversified beverage conglomerates with captive bottling infrastructure and mass retail shelf dominance. Strategic archetypes include scale-driven mass-market suppliers, premium-tier pharmacy-channel specialists, and direct-to-consumer subscription platforms. M&A activity concentrates on electrolyte solution manufacturers with hospital formulary relationships. Geographic expansion through convenience-store exclusivity renegotiation represents the second dominant competitive vector.
Among North American beverage conglomerates, PepsiCo and Monster Beverage Company exemplify scale-driven archetypes leveraging bottling infrastructure for stadium vending and mass retail penetration. Red Bull GmbH anchors the premium-tier specialist position through pharmacy-grade electrolyte sourcing density and extreme-sports sponsorship integration. These three entities collectively represent the structural poles around which mid-cap regional formulators and direct-to-consumer subscription platforms orbit.
| Leading Market Players |
|---|
| PepsiCo |
| Monster Beverage Company |
| Red Bull GmbH |
| Coca-Cola Company |
| Nestle S.A. |
| Abbott Nutrition Co. |
| Lucozade Ribena Suntory |
| Suntory Holdings Limited |
| Britvic Plc |
| Others |
Supply Flow & Price Mechanics
German Olympic training centers and Bundesliga football clubs now mandate batch-certified osmolarity documentation above 330 mOsm/L, forcing glucose polymer suppliers to invest in inline refractometry systems and pharmaceutical-grade electrolyte sourcing that compresses margins on standard-tier formulations.
Pricing Analysis
Value-based pricing anchors to glycogen replenishment throughput and post-surgical recovery outcomes. Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade electrolyte density from mass retail sports drinks and occupational heat-stress pouches. Cost compression in economy tiers is intensifying because agricultural commodity swings pressure glucose polymer input costs. Casual fitness enthusiasts exhibit highest price sensitivity, while German institutional buyers prioritize batch certification over per-unit cost.
Supply Chain Analysis
Regional distribution centers in the Rhine-Main corridor, Greater Boston, and Tokyo-Osaka anchor hub-and-spoke patterns for high-osmolality formulations. Manufacturing concentrates in Germany, Japan, and China. Formulation draws from glucose polymers, pharmaceutical-grade sodium-potassium compounds, and biodegradable packaging matrices. Single-source vulnerability persists in pharmaceutical-grade electrolyte sourcing. Distribution runs through hybrid online-offline fulfillment models renegotiating traditional convenience-store exclusivity structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision osmolarity tuning technology is displacing manual batch correction workflows, compressing reformulation timelines and rewarding early adopters with EFSA novel food pathway advantages.
For Market Incumbents: Acquire hospital formulary relationships and pharmacy-channel electrolyte solution manufacturers to defend against direct-to-consumer subscription platforms. Backward integration into glucose polymer production hedges agricultural commodity volatility. Certification investment in REACH-compliant pressurization methods protects German and Dutch market access. For New Entrants and Emerging Players: Occupational heat-stress management in construction and mining represents the most penetrable white space, with purpose-branded formulations commanding premium positioning. Direct-to-consumer platforms offering at-home electrolyte testing integration capture recurring revenue outside stadium vending channels. Subscription-based replenishment models displace single-transaction retail fastest in Japan and South Korea. For Investors and Strategic Acquirers: Re-rating potential sits with electrolyte solution manufacturers given clinical prescription expansion and hospital formulary standardization. Long-term viability favors targets with documented absorption kinetics and pharmacy-grade sourcing relationships. Watch EFSA novel food approval timelines as inflection indicators for reformulation pipeline value.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Osmolarity Technology Deployment | Inline refractometry systems reduce batch-to-batch variance for German Olympic procurement compliance. |
| Biodegradable Packaging Transition | EU F-Gas Regulation compliance secures stadium vending contracts and institutional buyer preference. |
| Direct-to-Consumer Subscription Launch | Personalized hydration profiling captures recurring revenue outside traditional retail channels in Japan. |
| Pharmacy-Grade Electrolyte Sourcing | Hospital formulary relationships command premium pricing in post-surgical recovery segments. |
| Occupational Segment Brand Extension | Heat-stress management formulations address underserved construction and mining demand. |
Methodological Framework
Multi-period observation of procurement specifications, EFSA novel food approval timelines, and convenience-store exclusivity renegotiations anchored the trend analysis, supplemented by interviews with sports nutrition formulators, clinical dietitians, hospital procurement managers, and glucose polymer supply specialists. Secondary validation drew from FDA food additive filings, EFSA novel food assessment databases, METI industrial standards documentation, and customs records for glucose polymer trade flows. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting across product type, end user archetype, distribution channel, and package format determined value allocation. CAGRs derived from exponential growth curve fitting across the projection horizon. Forecast inputs incorporated EFSA approval timeline distributions, agricultural commodity price indices, and institutional procurement contract renewal patterns.
Caveats apply where EFSA novel food assessment delays, glucose polymer supply disruptions, or front-of-pack warning system implementations could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market