
 United Arab Emirates Bottled Water Market | 2026-2036
United Arab Emirates Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Bottled Water Market Analytics
Multi-source procurement for raw water intake is rebalancing toward blended supply agreements that combine desalinated seawater with protected underground aquifers. Masafi Inc. anchors its competitive stance through exclusive access to mountainous spring sources in the northern emirates. Mai Dubai LLC leverages state-of-the-art bottling infrastructure near the Dubai-Al Ain road to sustain cost-efficient national distribution. Agthia Group PJSC dominates the broader beverage portfolio, extending its water brands through integrated retail and foodservice channels.
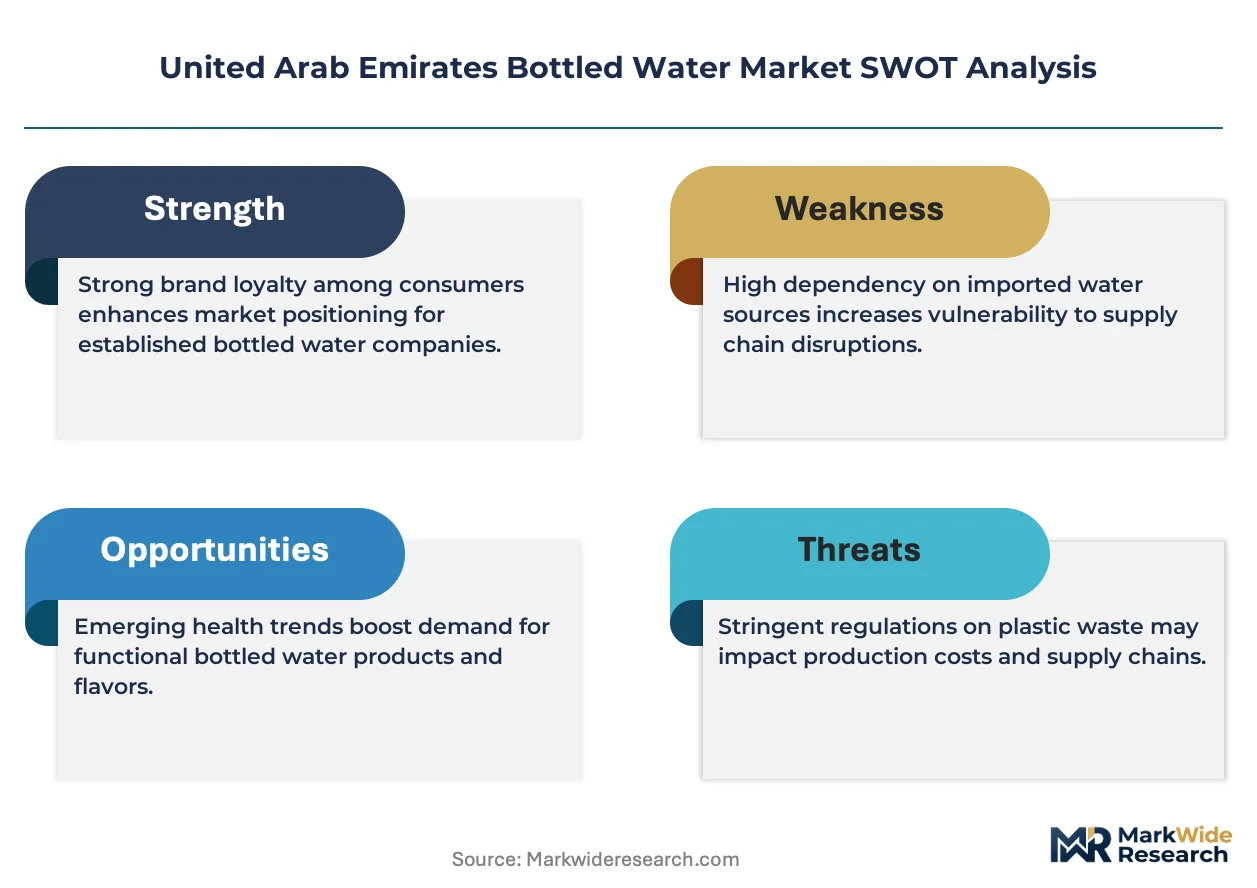
Bottled water in the UAE denotes potable water sealed in food-grade containers, typically treated through reverse osmosis, ultraviolet sterilization, or ozonation to achieve microbiological safety and mineral stability for human consumption. The product serves as a primary hydration source in a climate where ambient temperatures frequently exceed forty degrees Celsius and municipal tap water remains culturally distrusted for direct drinking. Purified water holds the largest volume position due to its lower production cost and universal compatibility with desalination feedstock, while mineral water commands premium shelf positioning and superior margins in hospitality settings. Plastic bottles retain overwhelming packaging dominance, though glass bottle adoption accelerates in hotel minibars and fine-dining establishments where aesthetic presentation drives purchasing decisions.
MOHAP enforces comprehensive food safety regulations governing bottled water labeling, source authentication, and maximum contaminant thresholds, compelling producers to maintain certified laboratory testing protocols. The Emirates Authority for Standardization and Metrology mandates compliance with UAE-specific bottled water standards that exceed baseline Gulf Cooperation Council requirements in certain microbiological parameters. ESMA's conformity assessment procedures shape market access timelines and compliance costs for both domestic manufacturers and import brands. Stakeholders must monitor evolving sustainability mandates around recycled plastic content and deposit-return schemes that could fundamentally alter packaging economics and channel profitability.
Market Dynamics
MOHAP's tightening food safety mandates are forcing producers to reconfigure laboratory testing protocols and source authentication systems, compressing operational timelines while elevating compliance costs across the value chain.
Growth Catalysts
- Hospitality sector expansion:Luxury hotels in Dubai and Abu Dhabi are extending premium water portfolios to differentiate guest experiences, creating sustained pull for mineral water variants with superior margin profiles.
- ESMA conformity assessment:The Emirates Authority for Standardization and Metrology's certification requirements exceed baseline Gulf Cooperation Council standards, filtering out marginal competitors and consolidating shelf access for compliant producers.
- Climate-driven consumption:Ambient temperatures exceeding forty degrees Celsius for extended periods elevate per-capita hydration requirements, embedding bottled water as a non-discretionary purchase category.
Market Restraints
- Feedstock concentration:Desalinated seawater from coastal plants dominates raw water intake, exposing producers to energy price volatility and infrastructure bottlenecks at intake facilities.
- Packaging material dependency:Virgin PET resin supply concentrates with regional petrochemical complexes, constraining cost flexibility for producers seeking recycled content transitions.
- Cultural tap water aversion:Persistent consumer distrust of municipal supply limits market education opportunities and reinforces single-use packaging dependence.
Strategic Opportunities
- Glass bottle hospitality channel:Fine-dining establishments and hotel minibars are accelerating aesthetic-driven packaging switches, opening margin expansion through presentation-premium capture.
- Deposit-return scheme preparation:Anticipated sustainability mandates around reverse logistics infrastructure offer first-mover advantage in circular packaging systems.
- Northern emirates spring positioning:Mountainous aquifer access in Ras Al Khaimah and Fujairah enables differentiated source storytelling against desalination-dependent competitors.
Industry Challenges
- Microbiological testing capacity:Certified laboratory throughput constraints are extending batch release timelines, complicating just-in-time distribution to retail and foodservice channels.
- Recycled content integration:Food-grade rPET supply scarcity is forcing producers to balance sustainability commitments against mechanical performance and regulatory approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Bottled Water Market |
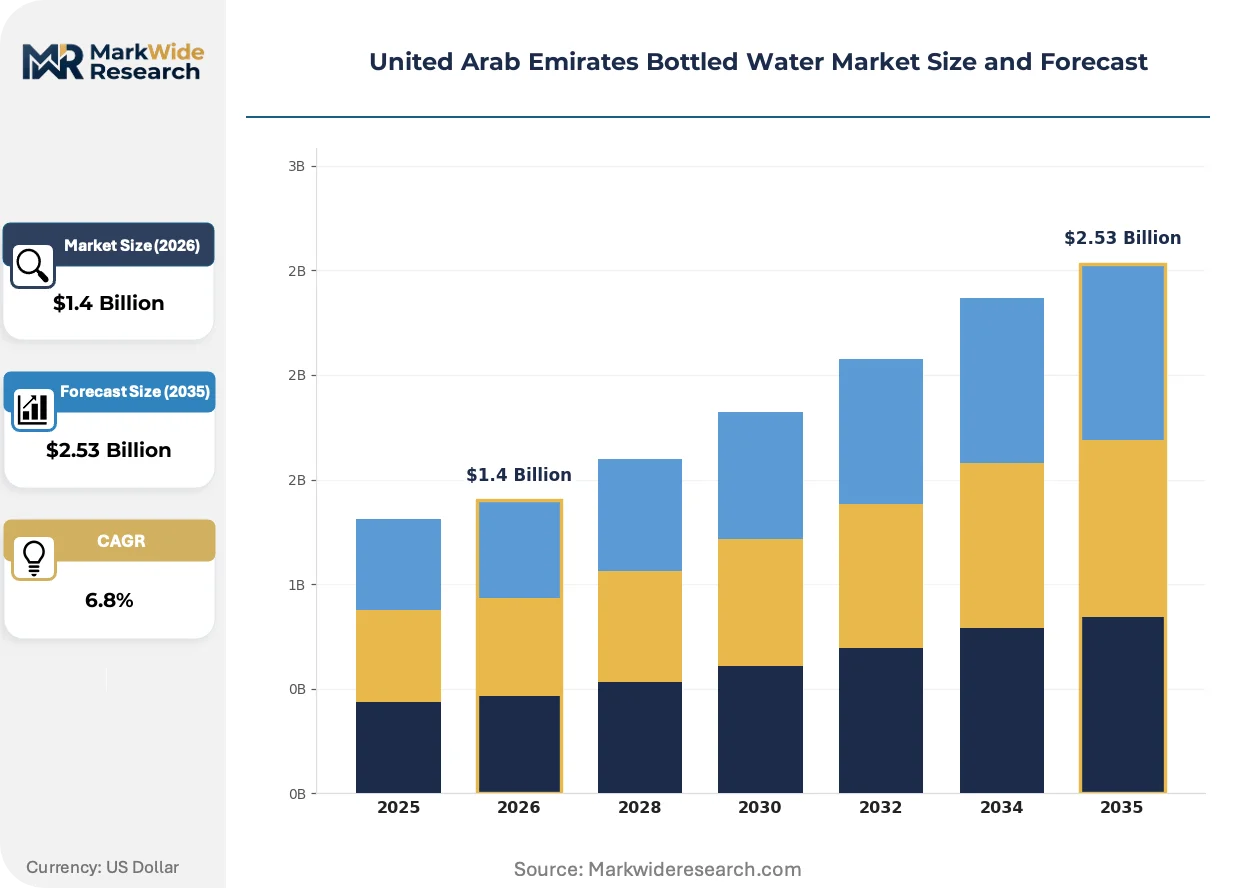
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Sparkling Water, Purified Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Agthia Group PJSC, Masafi Inc., Mai Dubai LLC, National Food Products Company, AL Ghadeer Drinking Water LLC, Nestlé S.A., PepsiCo Inc., The Coca-Cola Company, Danone S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Bottled Water Market Evolving Landscape
Packaging technology and regulatory compliance systems are converging to reshape production economics and channel access, with sustainability mandates accelerating material transitions across the value chain.
Ozonation coupled with advanced membrane filtration is electrifying microbiological safety protocols, enabling producers to reduce chemical additive dependence while extending shelf stability. Luxury hotel chains and airline catering services are adopting these systems fastest, compressing competitive differentiation timelines for laggard facilities.
MOHAP's evolving labeling disclosure requirements are mandating granular source traceability and contaminant threshold documentation, forcing producers to deploy serialized batch tracking infrastructure. Domestic manufacturers face compressed certification windows compared to import brands, reshaping inventory planning and launch cadences.
Corporate procurement departments are consolidating hydration service contracts under facility management umbrellas, displacing fragmented retail purchasing. This concentration shifts volume toward direct-distribution agreements with bottlers, most visible in Dubai's commercial district towers and Abu Dhabi government complexes.
United Arab Emirates Bottled Water Market Segmentation
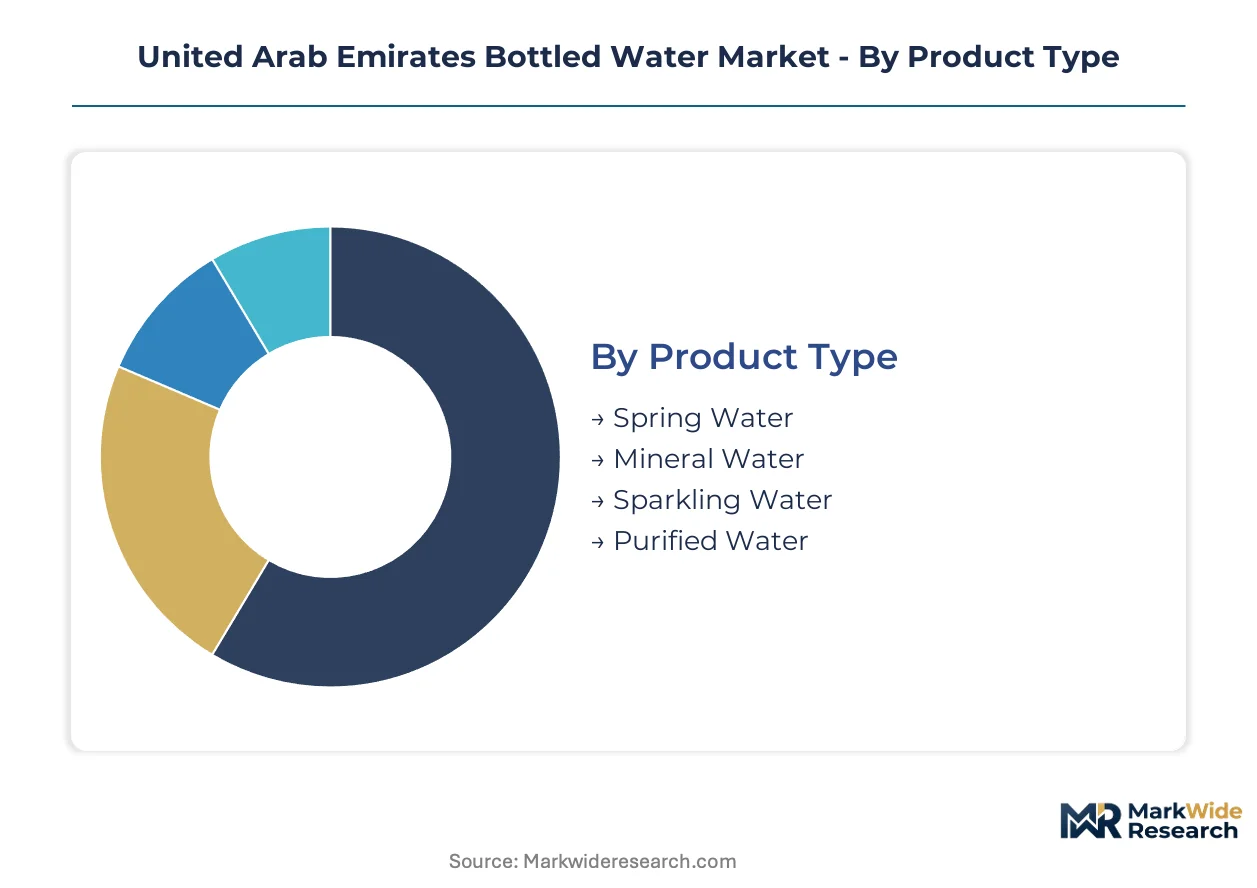
Segmentation in the UAE bottled water market reveals distinct margin architectures and procurement patterns across product formulations, packaging formats, and channel structures. Each dimension carries regulatory implications under MOHAP's evolving disclosure mandates.
Product Type:
Customization intensity spans from commodity purification to terroir-driven source differentiation, with production economics diverging sharply across the spectrum.
- Purified Water:Reverse osmosis and multi-stage filtration deliver microbiologically stable output from desalinated feedstock. Dubai's corporate catering contracts and mass retail shelves concentrate demand here, driven by cost efficiency and universal compatibility with existing bottling infrastructure.
- Mineral Water:Naturally occurring mineral content requires protected aquifer access and certified source documentation. Abu Dhabi's luxury hotel portfolios and fine-dining venues pull volume toward this tier, where ESMA's stricter contaminant thresholds and provenance labeling create compliance moats.
- Spring Water:Mountainous catchment in Ras Al Khaimah and Fujairah supplies differentiated positioning against desalination-dependent competitors.
- Sparkling Water:Carbonation infrastructure adds capital intensity; hospitality minibars and airline catering drive premium placement.
Most installed capacity flows through Purified Water. Expansion is steepest in Mineral Water.
Packaging Type:
Cost-to-presentation ratios stratify sharply, with material transitions accelerating under anticipated circular economy mandates.
- Plastic Bottles:Virgin PET dominates unit economics and logistics efficiency across ambient temperature distribution. Dubai-Al Ain corridor bottlers leverage this format for national penetration, though rPET integration timelines compress against food-grade supply scarcity.
- Glass Bottles:Aesthetic premium and thermal stability command placement in hotel minibars and high-end restaurant tables. Abu Dhabi's luxury hospitality developments are expanding glass-forward water programs, where presentation value offsets weight-based distribution penalties.
- Tetra Packs:Aseptic filling technology suits institutional bulk procurement and airline galley constraints.
- Pouches:Flexible format addresses event catering and outdoor recreation segments with lower per-unit freight costs.
Plastic Bottles carry the volume base. Glass Bottles are climbing the fastest on margin expansion.
Distribution Channel:
Channel concentration reflects UAE urban geography and purchasing behavior fragmentation between planned stock-up and immediate consumption occasions.
- Supermarkets:Hypermarket and supermarket chains anchor household pantry loading with multi-pack promotions and private label placement. Dubai's retail mall density sustains high-throughput SKU proliferation across temperature-controlled formats.
- Convenience Stores:Petrol station forecourts and urban corner shops capture impulse hydration in ambient temperature extremes. Abu Dhabi's highway corridor development extends reach for single-serve chilled formats.
- Online Retail:Subscription models and bulk delivery platforms are displacing traditional wholesale for residential and small commercial accounts.
- Vending Machines:High-traffic locations—metro stations, government complexes, university campuses—deploy refrigerated units with cashless payment integration.
Supermarkets process the majority of volume. Online Retail is gaining share fastest on corporate procurement consolidation.
End User:
Customer type segmentation maps directly to contract structure complexity, from transactional retail to multi-year facility management agreements.
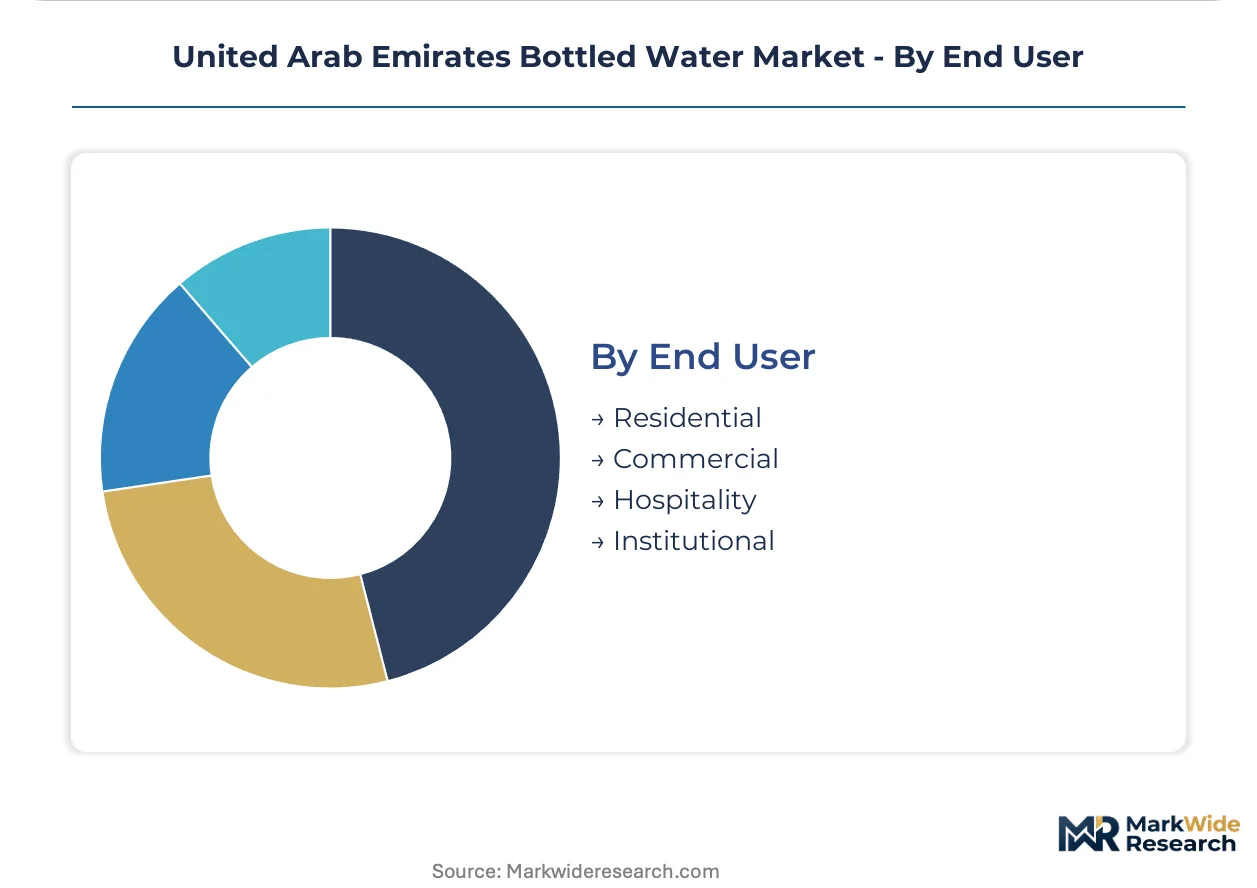
- Commercial:Office towers and business parks consolidate hydration under integrated facility services contracts. Dubai International Financial Centre and Abu Dhabi Global Market towers exemplify direct-distribution volume concentration.
- Hospitality:Luxury hotel portfolios and airline catering specifications drive premium SKU development and customized packaging. Jumeirah and Emaar hospitality assets maintain dedicated water programs with source-specific procurement.
- Residential:Household consumption mixes retail purchase with home delivery subscriptions across Emirates.
- Institutional:Government complexes, healthcare facilities, and educational institutions operate under tender-based procurement with sustainability scoring criteria.
Commercial accounts anchor contract value. Hospitality commands the steepest expansion trajectory on premium portfolio extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality corridor anchors production capacity and distribution infrastructure for the UAE bottled water sector. Abu Dhabi drives institutional procurement volume through government complex tenders. Northern emirates supply differentiated spring-sourced positioning.
Dubai
Luxury hotel portfolios along Sheikh Zayed Road and Downtown Dubai sustain premium mineral water demand with customized glass-bottle programs. MOHAP's batch-tracking mandates compress certification timelines for manufacturers operating in Jebel Ali industrial zones. The Dubai-Al Ain corridor bottling cluster leverages highway connectivity for national distribution reach.
Abu Dhabi
Government complexes and sovereign wealth fund headquarters consolidate hydration contracts under facility management umbrellas. ESMA's conformity assessment procedures filter shelf access for producers serving retail channels in Yas Island and Saadiyat developments. The Khalifa Industrial Zone concentration supports desalination-dependent purified water scale.
Sharjah
Mid-market retail and residential delivery subscriptions concentrate demand for cost-optimized PET formats. The emirate's logistics parks enable secondary distribution hub positioning for northern emirates penetration. Industrial city bottlers serve price-sensitive segments across the UAE's central corridor.
Northern Emirates
Ras Al Khaimah and Fujairah's mountainous aquifers enable spring-sourced differentiation against desalination competitors. Protected catchment areas support premium positioning for hospitality export and local terroir storytelling. Wadi-fed sources command authentication documentation under MOHAP's provenance labeling rules.
United Arab Emirates Bottled Water Market Competitive Landscape
Global majors compete with regional champions across source access and hospitality channel relationships. The vendor base stratifies between integrated beverage conglomerates, dedicated water specialists, and captive hospitality suppliers. Three archetypes dominate: desalination-scale operators, spring-source guardians, and diversified FMCG portfolios. Capacity expansion and source authentication infrastructure constitute the primary competitive moves.
Within the dedicated water specialist tier, Masafi Inc. exemplifies mountain-spring source anchoring, while Mai Dubai LLC occupies a position as infrastructure-scale national distributor. Agthia Group PJSC represents diversified beverage portfolio extension into hydration categories. These three entities illustrate distinct strategic postures: exclusive aquifer control, logistics-optimized scale, and cross-category retail integration.
| Leading Market Players |
|---|
| Agthia Group PJSC |
| Masafi Inc. |
| Mai Dubai LLC |
| National Food Products Company |
| AL Ghadeer Drinking Water LLC |
| Nestlé S.A. |
| PepsiCo Inc. |
| The Coca-Cola Company |
| Danone S.A. |
| Others |
Value Network & Pricing Analysis
MOHAP's recycled plastic content mandates are gating qualified supply access and premium-tier pricing power for UAE bottled water producers seeking hospitality channel placement. Producers lacking certified rPET sourcing face exclusion from government tender scoring and luxury hotel procurement specifications, compressing margin architecture toward compliant operators.
Pricing Analysis
Desalination energy costs pass through directly to purified water pricing, with feedstock volatility from coastal plant tariffs compressing margins for scale operators. Pricing stratifies across premium mineral water, standard purified formats, and economy private-label tiers, with source authentication and glass packaging as the primary differentiation drivers. Pricing pressure stems from virgin PET resin concentration with regional petrochemical complexes, forcing producers to absorb cost spikes or surrender volume. Corporate catering contracts show highest price sensitivity, while luxury hospitality maintains inelastic demand for provenance-certified mineral variants.
Supply Chain Analysis
Raw water intake rests on desalinated seawater from UAE coastal plants, with supplementary draw from Saudi groundwater agreements and Omani spring source partnerships for premium positioning. Virgin PET resin, food-grade rPET, and glass bottle stock constitute the three critical input dependencies. Single-source vulnerability concentrates at Jebel Ali port intake facilities, where infrastructure bottlenecks cascade to batch release delays. Distribution runs through the Dubai-Al Ain highway corridor for national retail penetration, with direct-distribution fleets serving corporate tower contracts in Abu Dhabi and Dubai commercial districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE bottled water market functions as a geographic-arbitrage play between desalination-dependent Gulf producers and European spring-source importers, with MOHAP compliance costs creating a regulatory moat that favors domestic scale operators over marginal import brands.
For Market Incumbents: Extend source authentication infrastructure to defend hospitality channel access against emerging spring-source specialists from northern emirates. Lock in multi-year desalination feedstock agreements before energy tariff adjustments compress purified water margins. Vertical integration into captive laboratory testing capacity reduces batch release timelines and MOHAP compliance vulnerability. For New Entrants and Emerging Players: Advanced ozonation and membrane filtration systems offer a technology-first wedge against legacy chemical-dependent producers in the corporate catering segment. Target underpenetrated institutional procurement in Sharjah and northern emirates government complexes, where sustainability scoring criteria favor local entrants with circular packaging roadmaps. Lead with deposit-return scheme readiness as a differentiated tender response. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale northern emirates spring-source operators because MOHAP provenance labeling rules create irreplicable aquifer access moats. Five-to-ten-year viability hinges on consolidated players capturing hospitality channel expansion in Abu Dhabi and Dubai luxury developments. Watch ESMA conformity assessment backlogs as an inflection signal for competitive shelf access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Spring Source Acquisition | Mountainous aquifer control in Ras Al Khaimah enables premium positioning against desalination competitors. |
| rPET Supply Agreement | Food-grade recycled resin contracts secure MOHAP compliance for government and hospitality tenders. |
| Laboratory Certification Investment | Certified testing capacity compresses batch release timelines and MOHAP audit readiness. |
| Direct-Distribution Fleet Expansion | Captive logistics in Dubai and Abu Dhabi commercial districts displace fragmented wholesale channels. |
| Glass Bottle Production Line | Aesthetic packaging capability captures hotel minibar and fine-dining premium placement. |
Research Methodology
Multiple input streams — bottling plant managers, hospitality procurement directors, MOHAP regulatory affairs leads, and retail category buyers — were reconciled with secondary validation from ESMA conformity databases, customs import records, and hotel group sustainability disclosures. Bottom-up volume triangulation against top-down market sizing anchored the analytical framework.
Historical consumption patterns were cross-referenced against panel input from distribution channel partners to model growth trajectories across the projection horizon. Segmentation dimensions included product formulation, packaging material, distribution channel structure, and end-user contract type. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost assumptions and hospitality sector expansion pipelines.
The model holds under stable MOHAP enforcement intensity and continued desalination capacity expansion; deviation in rPET supply scarcity or deposit-return scheme acceleration would shift volume and value trajectories. A small set of named triggers — ESMA certification backlog duration, northern emirates aquifer access rulings, and corporate procurement consolidation velocity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Africa Energy Drinks Market