
 Hydrogen Water Pitcher Market | 2026-2036
Hydrogen Water Pitcher Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Water Pitcher Market Insights
Multi-source component procurement is broadening across the hydrogen water pitcher supply chain as manufacturers diversify beyond single-region electrolysis cell suppliers. Echo leverages vertical integration in proton exchange membrane sourcing to control quality consistency across production batches. Piurify sustains geographic dominance in North American direct-to-consumer channels through dedicated fulfillment infrastructure. Guangzhou Olansi anchors cost-competitive manufacturing through scaled plate-type electrolysis assembly lines in southern China.
A hydrogen water pitcher is a consumer appliance that infuses drinking water with dissolved molecular hydrogen gas, typically achieving concentrations between 0.5 and 1.6 parts per million through electrolysis or magnesium reaction methods, primarily serving wellness-oriented consumers seeking antioxidant hydration products. Portable pitchers dominate unit volume due to lower price points and travel compatibility, while electric countertop models capture margin pools through advanced membrane technology and digital concentration displays. Solid state electrolysis represents the fastest-growing technology segment as manufacturers eliminate liquid electrolyte maintenance requirements. Glass and BPA-free plastic material splits reflect consumer prioritization of chemical safety transparency alongside durability preferences.
FDA material safety regulations for water-contact surfaces and FCC electromagnetic emissions standards for powered units create dual compliance thresholds for electric pitcher entrants. Japan's Ministry of Health, Labour and Welfare maintains distinctive hydrogen concentration labeling requirements that shape product claims and consumer communication strategies. South Korea's MFDS classifies certain hydrogen generators as functional health devices, triggering pre-market notification pathways distinct from general appliance categories. Stakeholders must monitor evolving electrolysis efficiency standards and regional classification shifts that could resegment market access requirements without warning.
Market Dynamics
Solid state electrolysis is compressing maintenance burdens while FDA material safety scrutiny tightens compliance thresholds for powered units entering North American channels.
Growth Catalysts
- Japan's MHLW concentration labeling framework:Standardized hydrogen parts-per-million disclosure requirements build consumer trust and reduce claim ambiguity for wellness-positioned products.
- Magnesium reaction method maturation:Passive hydrogen generation eliminates electrical components, opening battery-free portability for travel and outdoor recreation segments.
- South Korea's MFDS functional health device pathway:Pre-market notification clarity accelerates premium electric model approvals for domestic wellness retailers.
Market Restraints
- Proton exchange membrane supply concentration:Specialty fluoropolymer sourcing clusters in Japanese and German chemical suppliers, exposing batch-to-batch cost volatility.
- FCC electromagnetic emissions testing:Powered pitcher entrants face extended certification timelines for radio-frequency compliance, delaying US market entry.
- Alkaline water ionizer substitution:Established countertop appliances with broader pH adjustment claims compete for identical wellness-oriented kitchen counter space.
Strategic Opportunities
- Underpenetrated German wellness retail:Pharmacy and organic specialty channels lack dedicated hydrogen hydration fixtures despite mature antioxidant supplement demand.
- Subscription filter replacement models:Recurring revenue streams through PEM cartridge auto-ship programs deepen lifetime customer value beyond hardware margins.
- Glass-BPA-free hybrid material convergence:Premium positioning through visible hydrogen bubble formation in borosilicate chambers commands shelf differentiation.
Industry Challenges
- Electrochemistry talent scarcity:Specialized membrane electrode assembly expertise concentrates in fuel cell and automotive sectors, constraining appliance-grade hiring pipelines.
- Multi-jurisdiction labeling synchronization:Divergent concentration measurement protocols between Japan's MHLW and South Korea's MFDS force SKU fragmentation or claim dilution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Water Pitcher Market |
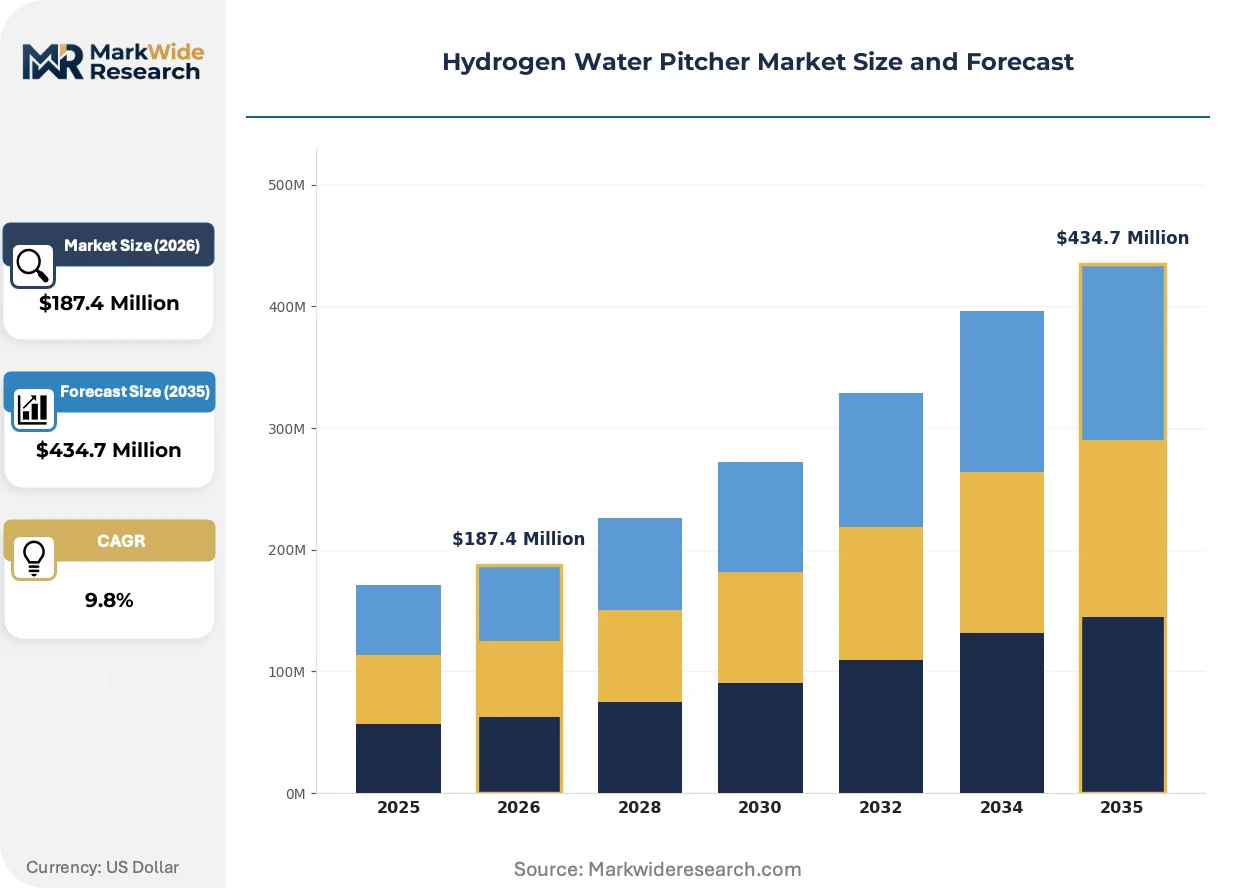
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pitchers, Countertop Models, Electric Pitchers, Manual Pitchers Material: Glass, BPA-Free Plastic, Stainless Steel, Ceramic Electrolysis Technology: Membrane Technology, Plate-Type Electrolysis, Solid State Electrolysis, Other Systems End User: Households, Gyms, Hotels, Restaurants |
| Companies Covered | Echo, PUREPEBRIX, Piurify, OCEMIDA, Synergy Science, Guangzhou Olansi, Buder Electric, SOLCO Biomedical, Nixcer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Water Pitcher Market Trends and Innovations
Electrolysis architecture is shedding liquid electrolyte dependencies while regulatory documentation burdens intensify across major wellness economies.
Solid state proton exchange membrane stacks are rewriting the service interval economics of countertop hydrogen generation. Wellness-focused households in Osaka and Seoul are adopting maintenance-free electric models at pace, compressing the addressable market for magnesium-based passive alternatives that require tablet replacement.
REACH substance restrictions on perfluorinated compounds are tightening membrane material specifications for EU-bound production. German and French environmental regulators are extending compliance documentation to electrolysis cell imports, forcing Asian contract manufacturers to reformulate fluoropolymer content or sacrifice continental market access.
Direct-to-consumer education investments are displacing traditional appliance retail dependence for hydrogen pitcher brands. Dedicated fulfillment infrastructure now anchors North American penetration, with subscription-filter bundling replacing big-box showroom placement as the primary customer acquisition channel in California and Texas metropolitan zones.
Hydrogen Water Pitcher Market Segmentation
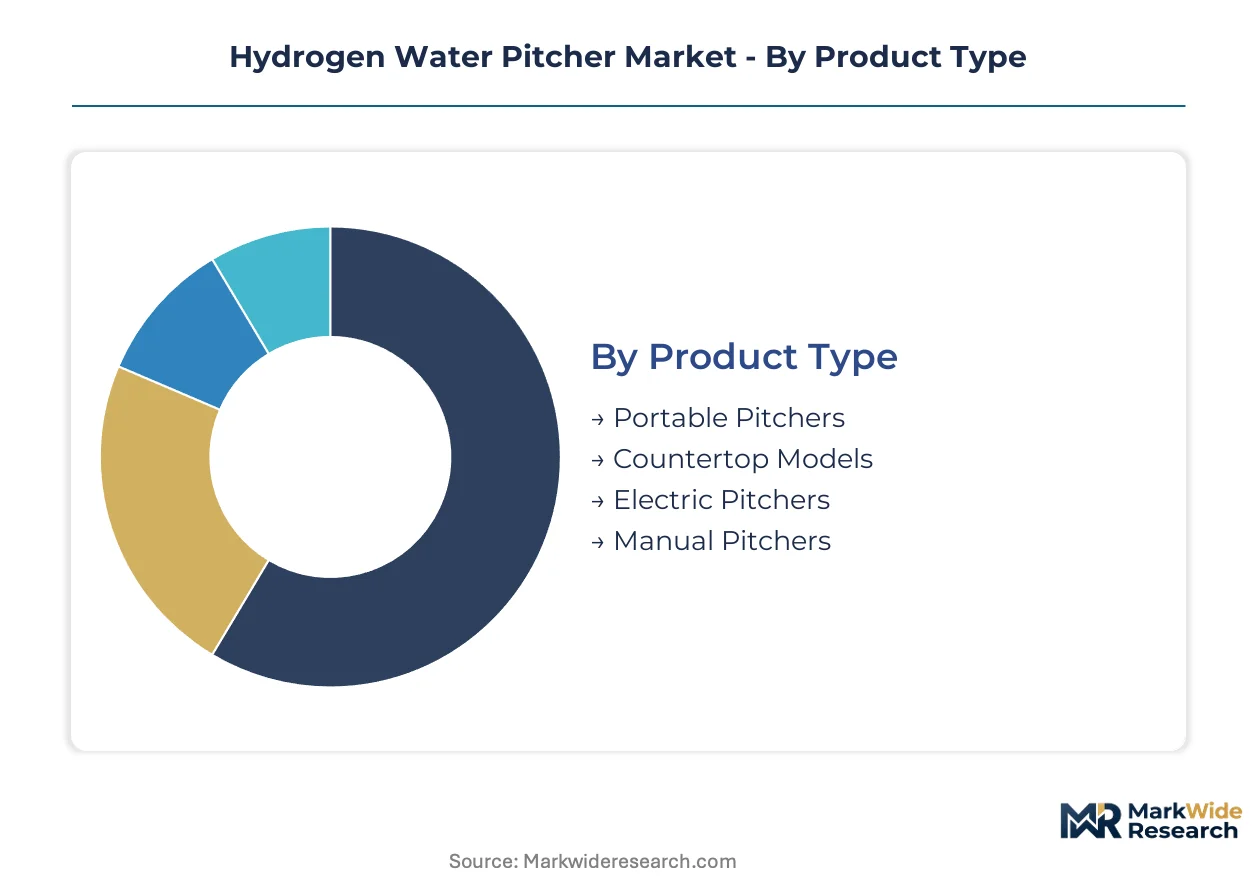
Hydrogen water pitcher segmentation reveals divergent capital requirements across product architectures and electrolysis methods. Manufacturers must align production investments with specific technology tiers and end-user price sensitivities to capture margin pools effectively.
Product Type:
Capital intensity varies sharply across this category, with electric countertop models demanding the highest upfront tooling and certification investment while manual alternatives require minimal fixed asset deployment.
- Portable Pitchers:Battery-powered or passive magnesium-reaction units designed for travel and outdoor use. Demand concentrates in Japanese metropolitan wellness retailers where commuter hydration habits drive replacement cycles. Lower price points expand addressable household penetration but compress per-unit margins.
- Countertop Models:Stationary electric appliances with dedicated power supplies and digital concentration displays. Seoul's premium kitchen appliance showrooms anchor demand as South Korean households prioritize countertop wellness technology integration. These units command the highest average selling prices and recurring filter revenue streams.
- Electric Pitchers:Plug-in powered systems with integrated electrolysis cells and automated hydrogen generation cycles.
- Manual Pitchers:Non-powered vessels relying on magnesium rods or tablets for passive hydrogen infusion.
Most installed capacity flows through Countertop Models. Expansion is steepest in Portable Pitchers.
Material:
Cost tier stratification separates premium borosilicate glass from mass-market polymer alternatives, with stainless steel occupying a narrowing middle position challenged by thermal conductivity limitations.
- Glass:Borosilicate chambers enabling visible hydrogen bubble formation and chemical inertness. German pharmacy channels show concentrated demand as REACH-compliant consumers prioritize substance migration transparency. Premium positioning supports 40-60% price elevation over polymer equivalents.
- BPA-Free Plastic:Tritan copolyester and Eastman Tritan formulations dominating North American mass-market penetration. California and Texas direct-to-consumer fulfillment infrastructure ships these variants at volume scale due to shipping weight advantages.
- Stainless Steel:Vacuum-insulated double-wall constructions targeting temperature retention priorities.
- Ceramic:Glazed stoneware vessels appealing to aesthetic-driven wellness consumers in traditional tea-drinking cultures.
Volume leadership sits with BPA-Free Plastic. Glass commands the steepest expansion trajectory in premium channels.
Electrolysis Technology:
Technology maturity curves separate established liquid-electrolyte systems from emerging solid-state architectures that eliminate maintenance burdens but require specialized membrane electrode assembly expertise.
- Membrane Technology:Proton exchange membrane stacks enabling precise hydrogen concentration control through voltage modulation. Japanese chemical suppliers anchor specialty fluoropolymer sourcing, exposing batch cost volatility that shapes procurement strategies. Osaka and Tokyo households show strongest adoption of PEM-equipped premium models.
- Solid State Electrolysis:Ceramic or polymer electrolyte systems eliminating liquid refill requirements. South Korean wellness retailers are accelerating placement of maintenance-free units as MFDS functional health device classification clarifies marketing claims. This architecture is gaining share fastest among technology-forward consumer segments.
- Plate-Type Electrolysis:Parallel electrode configurations common in cost-optimized manufacturing.
- Other Systems:Emerging electrochemical approaches including photocatalytic and ultrasonic hydrogen generation methods.
Plate-Type Electrolysis carries the heaviest installed base. Solid State Electrolysis is climbing the fastest as maintenance-free positioning resonates.
End User:
Customer type segmentation aligns procurement scale with usage intensity, from individual household replacement cycles to commercial hospitality fleet deployments requiring durability guarantees.
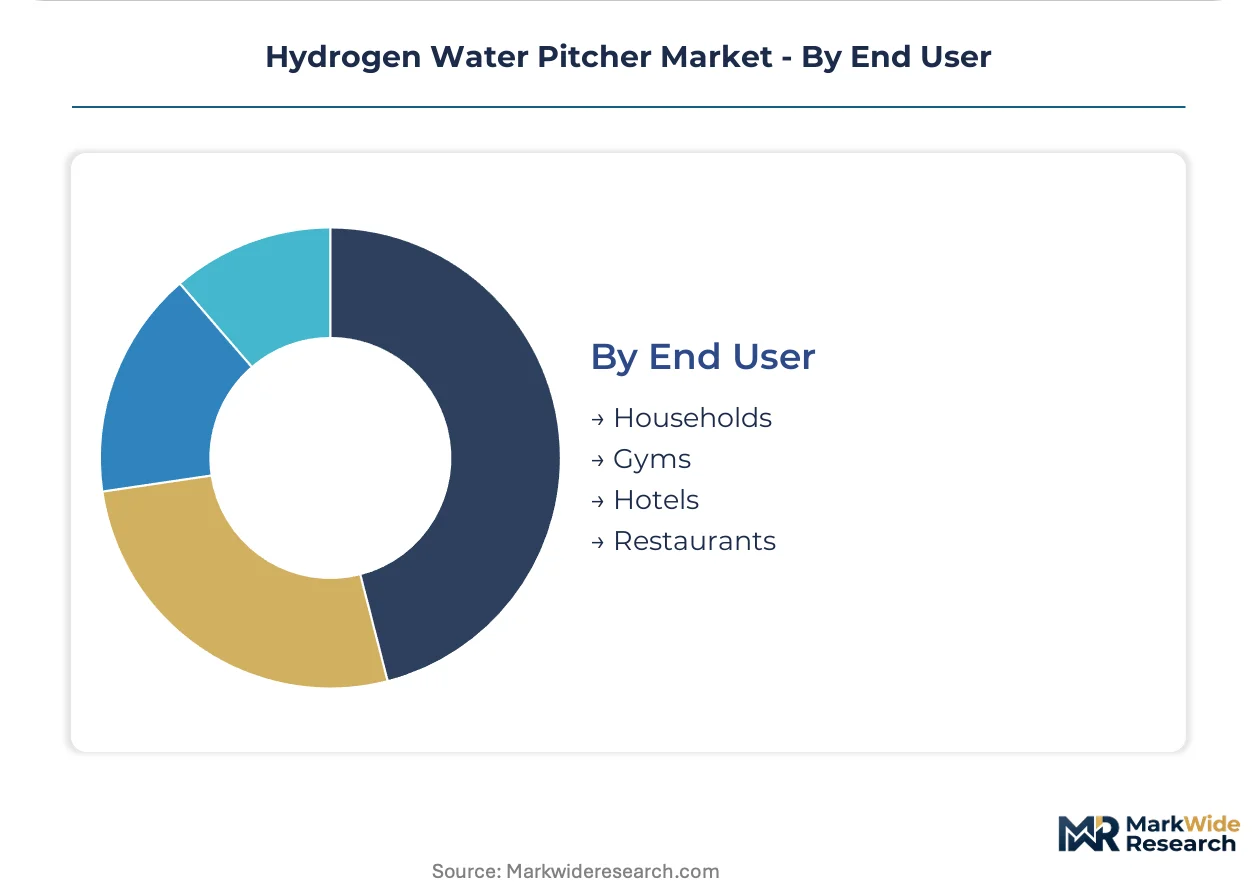
- Households:Individual wellness-oriented consumers purchasing single units for residential hydration routines. Japanese and South Korean metropolitan markets show deepest penetration as hydrogen health product familiarity reduces education burdens. Subscription filter replacement programs deepen lifetime value in this segment.
- Gyms:Fitness centers deploying countertop models for member amenity differentiation. California boutique fitness chains have pioneered hydrogen hydration station placement, with Texas and Florida markets replicating the model.
- Hotels:Premium hospitality properties offering in-room wellness amenities.
- Restaurants:Fine-dining establishments integrating hydrogen water into beverage programs.
Households absorb the dominant volume share. Gyms represent the steepest expansion channel as fitness amenity competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka and Seoul metropolitan clusters anchor hydrogen water pitcher adoption through mature wellness retail infrastructure and concentrated electrolysis device manufacturing expertise.
United States
California and Texas direct-to-consumer channels absorb the dominant North American volume through dedicated fulfillment infrastructure. FDA material safety regulations for water-contact surfaces and FCC electromagnetic emissions standards create dual compliance thresholds for electric pitcher entrants. Los Angeles and Dallas metropolitan wellness consumers drive subscription filter replacement program adoption.
Japan
Tokyo and Osaka households demonstrate deepest penetration as hydrogen health product familiarity reduces education burdens for wellness-oriented consumers. METI oversees industrial standards while MHLW concentration labeling requirements build consumer trust through standardized parts-per-million disclosure. Osaka retailers accelerate placement of maintenance-free solid state electrolysis models.
South Korea
Seoul Capital Area wellness retailers prioritize countertop electric models with digital concentration displays for kitchen appliance integration. MFDS functional health device classification triggers pre-market notification pathways distinct from general appliance categories. Busan-Ulsan manufacturing clusters supply specialized fluoropolymer membrane components.
Germany
Pharmacy and organic specialty channels in Berlin and Munich lack dedicated hydrogen hydration fixtures despite mature antioxidant supplement demand. REACH substance restrictions on perfluorinated compounds tighten membrane material specifications for EU-bound production. Bavarian environmental regulators extend compliance documentation to electrolysis cell imports.
China
Guangzhou and Shenzhen manufacturing bases anchor cost-competitive plate-type electrolysis assembly lines for export markets. MIIT oversees industrial appliance standards while SAMR monitors consumer product safety claims. Pearl River Delta contract manufacturers reformulate fluoropolymer content to preserve continental European market access.
Hydrogen Water Pitcher Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue maintenance-free solid state architectures and subscription-based filter replacement models. The vendor base stratifies across three tiers: premium electric countertop specialists, portable battery-powered fabricators, and cost-optimized manual magnesium-reaction suppliers. Two dominant competitive moves reshape positioning: backward integration into proton exchange membrane sourcing and geographic expansion through dedicated regional fulfillment infrastructure.
Within the premium-tier vector, Echo and Piurify exemplify divergent channel strategies, while Guangzhou Olansi occupies a position among scale-driven manufacturing specialists. Echo represents the vertically integrated archetype with captive membrane supply chains. Piurify anchors North American direct-to-consumer penetration through fulfillment infrastructure investments. Guangzhou Olansi exemplifies cost-competitive production positioning through southern China manufacturing concentration.
| Leading Market Players |
|---|
| Echo |
| PUREPEBRIX |
| Piurify |
| OCEMIDA |
| Synergy Science |
| Guangzhou Olansi |
| Buder Electric |
| SOLCO Biomedical |
| Nixcer |
| Others |
Pricing and Supply Chain Analysis
Backward integration into proton exchange membrane sourcing anchors Echo's pricing power through captive fluoropolymer supply chains, insulating batch costs from Japanese and German chemical supplier volatility while compressing margin exposure for competitors dependent on spot membrane procurement.
Pricing Analysis
Input-cost pass-through from specialty fluoropolymer membrane sourcing shapes tiered pricing across the hydrogen water pitcher landscape. Three-tier pricing structure across premium, standard, and economy levels separates PEM-equipped electric countertop models from passive magnesium-reaction portable units and manual alternatives. Pricing pressure stems from REACH substance restrictions tightening EU-bound membrane specifications, forcing reformulation investments. Household wellness consumers in Osaka and Seoul show lowest price sensitivity for maintenance-free solid state architectures, while North American direct-to-consumer channels absorb highest volume at compressed margins.
Supply Chain Analysis
Reverse-logistics flows for PEM cartridge replacement programs anchor recurring revenue infrastructure in California and Texas fulfillment zones, with subscription auto-ship models displacing traditional retail restocking patterns. Manufacturing concentrates in China, South Korea, and Japan, drawing from fluoropolymer membrane electrode assemblies, borosilicate glass chambers, and solid state ceramic electrolyte stacks. Single-source vulnerability clusters in Japanese and German specialty chemical suppliers for proton exchange membranes. Distribution runs through direct-to-consumer fulfillment infrastructure in North American metropolitan markets and dedicated wellness retail channels in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between East Asian manufacturing cost structures and North American premium wellness positioning, with FDA material safety compliance costs in the United States creating a regulatory moat that domestic entrants exploit against import-dependent competitors.
For Market Incumbents: Deploy subscription filter replacement programs as the primary retention lever, locking in lifetime value beyond hardware margins while alkaline water ionizer substitutes compete for identical kitchen counter space. Reinforce backward integration into membrane electrode assembly expertise, as electrochemistry talent scarcity concentrates in fuel cell sectors. Anchor capacity in Busan-Ulsan manufacturing clusters to preserve fluoropolymer sourcing proximity. For New Entrants and Emerging Players: Direct-to-consumer education investments bypass traditional appliance retail dependence, opening white-space penetration in German pharmacy and organic specialty channels where antioxidant supplement demand matures without dedicated hydrogen hydration fixtures. Target underpenetrated Berlin and Munich wellness retail as the most penetrable geography. Lead with glass-BPA-free hybrid material convergence for visible hydrogen bubble differentiation. For Investors and Strategic Acquirers: Roll-up economics work for maintenance-free solid state electrolysis specialists because MFDS functional health device classification in South Korea clarifies premium marketing claims and compresses competitive fragmentation. Five-to-ten-year viability hinges on electrolysis efficiency standard convergence across Japan's MHLW and South Korea's MFDS labeling protocols. Monitor multi-jurisdiction SKU fragmentation as the signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Sourcing | Echo's captive fluoropolymer supply chains insulate batch cost volatility from Japanese and German chemical suppliers. |
| Direct-to-Consumer Fulfillment Infrastructure | Piurify's dedicated California and Texas distribution anchors North American penetration against retail-dependent competitors. |
| Solid State Electrolysis Transition | Maintenance-free ceramic electrolyte systems eliminate liquid refill burdens for Osaka and Seoul wellness households. |
| Subscription Filter Replacement Programs | Recurring PEM cartridge auto-ship revenue deepens lifetime customer value beyond initial hardware margins. |
| REACH Compliance Reformulation | Asian contract manufacturers reformulate perfluorinated content to preserve continental European market access under tightening ECHA restrictions. |
Research Methodology
Direct dialogue with electrolysis cell engineers, wellness retail category managers, FDA regulatory consultants, and membrane electrode assembly specialists grounded qualitative findings, cross-referenced against customs trade records for fluoropolymer imports, SEC appliance manufacturer filings, MFDS functional health device notification databases, and METI industrial standards documentation. Bottom-up unit economics triangulated with top-down market sizing across the projection horizon.
Segmentation outputs reflect product type, electrolysis technology maturity, material composition tier, and end-user procurement scale modeled throughout the forecast period. CAGRs derived from electrolysis efficiency improvement curves, wellness consumer penetration rates, and regional regulatory approval velocity. Forecast inputs incorporated solid state electrolysis adoption trajectories and REACH substance restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic or ultrasonic hydrogen generation would alter the outlook if efficiency thresholds cross commercial viability. Practitioners should monitor divergence between Japan's MHLW and South Korea's MFDS concentration measurement protocols, fluoropolymer supply allocation shifts, and solid state electrolysis cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market