
 Japan Soy Beverages Market | 2026-2036
Japan Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Soy Beverages Market Foresight
A capital-intensity divergence between automated aseptic bottling lines and traditional carton filling is redrawing competitive boundaries among Japanese soy beverage producers. Kikkoman Corporation leverages its century-old fermentation infrastructure to sustain cost advantages in plain soy milk production. MARUSAN-AI Co., Ltd anchors its position through dedicated soymilk research facilities in Aichi Prefecture. Otsuka Pharmaceutical Co., Ltd. differentiates by dominating pharmaceutical-grade protein drink channels.
Soy beverages comprise aqueous extracts of whole soybeans or soy protein isolates, typically processed through grinding, enzymatic treatment, ultra-high temperature sterilization, and homogenization to achieve colloidal stability and shelf life exceeding 180 days in aseptic packaging. The product category serves commercial purposes spanning dairy alternatives, sports nutrition, and clinical dietary management. Soy milk occupies the largest volume position among product types, while soy protein drinks command premium shelf space in health stores and gym retail. Aseptic cartons retain dominance in packaging type due to ambient distribution economics, though bottles gain traction in convenience store chilled sets.
METI's Food Labeling Standards, JAS organic certification requirements, and the Consumer Affairs Agency's functional food notification system collectively shape product development timelines and marketing claims in Japan. PMDA oversight of FOSHU and qualified health claims creates a dual-track regulatory environment where standard beverages face lighter scrutiny than functional-positioned products. Stakeholders must monitor evolving protein content thresholds and allergen labeling precision as these standards tighten differentiation between commodity and premium-positioned offerings.
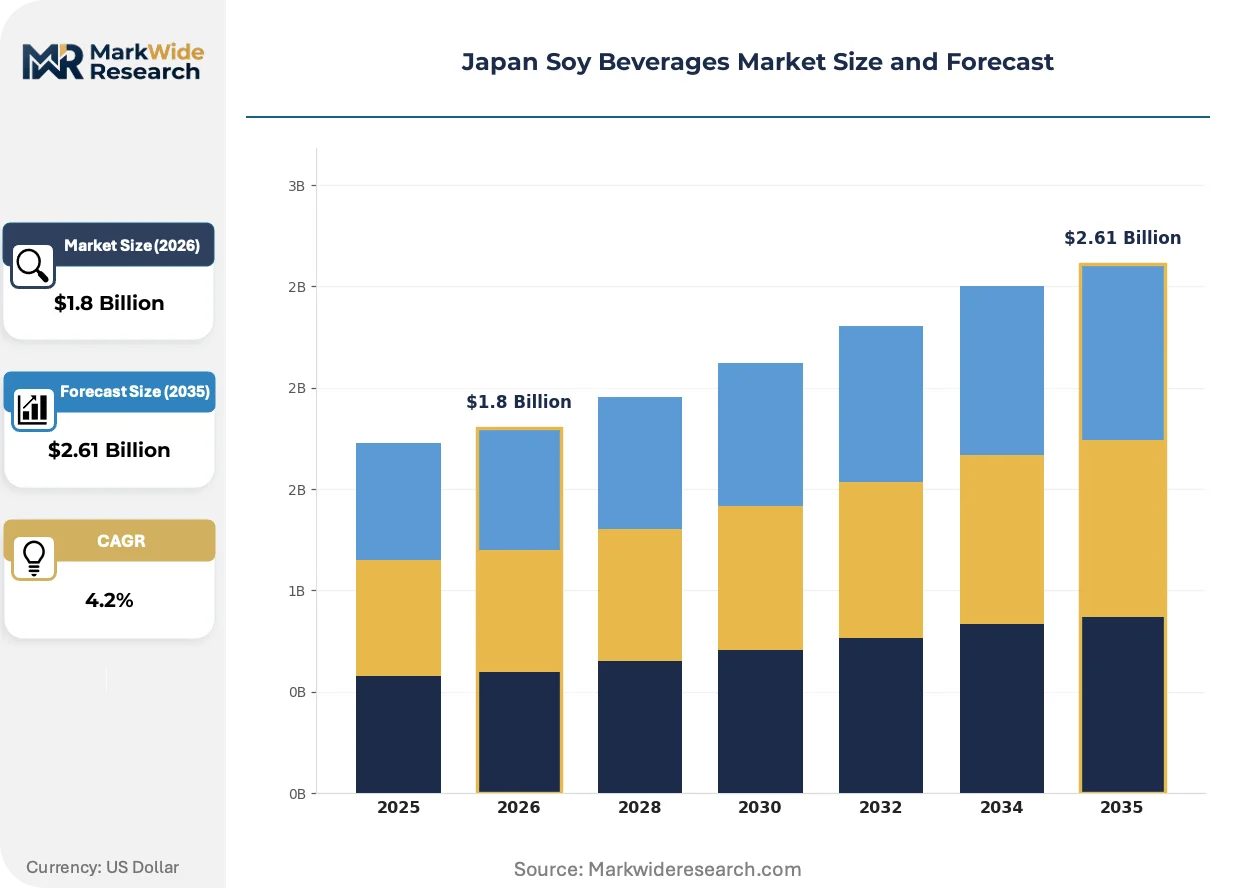
Market Dynamics
Japan's soy beverage sector faces intensifying pressure from METI's evolving Food Labeling Standards, which are compressing formulation cycles and forcing manufacturers to accelerate allergen precision investments ahead of compliance deadlines.
Growth Catalysts
- Protein fortification protocols:Fitness centers and wellness programs across Tokyo, Osaka, and Nagoya are normalizing soy protein drinks as standard recovery nutrition, creating institutional demand channels.
- METI labeling mandates:Stricter nutritional declaration requirements are rewarding early movers with cleaner formulations, accelerating premium product differentiation.
- Aichi Prefecture:Concentrated soymilk research infrastructure in this manufacturing hub is shortening innovation-to-shelf timelines for functional beverage variants.
Market Restraints
- Domestic soybean supply concentration:Import dependency on North American and Brazilian feedstock exposes processors to currency volatility and trade friction.
- Aseptic bottling capex thresholds:Automated sterilization lines require capital commitments that favor incumbents with legacy fermentation infrastructure.
- Oat and almond alternatives:Western-derived plant milks are capturing chilled retail space in convenience stores, constraining soy beverage shelf allocation.
Strategic Opportunities
- Kyushu and Tohoku regions:Underdeveloped specialty grocer penetration in these prefectures offers whitespace for premium soy protein drink distribution expansion.
- PMDA FOSHU pathway:The functional food notification system enables clinical-grade positioning for protein-fortified variants targeting dietary management segments.
- Chilled convenience store sets:Bottle formats are displacing ambient cartons in 7-Eleven and Lawson refrigerated sections, opening premium price realization.
Industry Challenges
- Enzymatic treatment expertise:Shortage of process engineers skilled in colloidal stability optimization is extending product development timelines.
- JAS organic certification:Multi-year farm-to-bottle traceability requirements are delaying organic line launches and locking up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Soy Beverages Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Soy Yogurt, Soy Protein Drinks, Soy-based Smoothies Flavor Profile: Original, Sweetened, Vanilla, Chocolate Packaging Type: Aseptic Cartons, Bottles, Cans, Pouches Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Stores |
| Companies Covered | Kikkoman Corporation, Lam Soon Group, Otsuka Pharmaceutical Co., Ltd., MARUSAN-AI Co., Ltd, The Hain Celestial Group, Vitasoy International Holdings Limited, Sapporo Holdings Limited, Danone S.A., Nestle S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Soy Beverages Market Shifts & Advancements
Japan's soy beverage landscape is being reconfigured by three intersecting movements: equipment downsizing for flexible production, regulatory precision demands, and channel-specific format innovation.
Membrane filtration technology for protein isolation and debittering is miniaturizing. Mid-tier processors in Saitama and Chiba Prefectures are adopting skid-mounted ultrafiltration units to bypass centralized toll processing. This distributed processing architecture is compressing logistics costs and enabling small-batch functional variants.
METI's 2025 enforcement timeline for revised allergen labeling precision is accelerating formulation audits. Manufacturers must now validate cross-contamination protocols at the enzyme supplier level. Premium-positioned soy protein drinks face the heaviest documentation burden, with several Aichi-based facilities restructuring supplier qualification workflows.
Convenience store buyers are unbundling ambient and chilled assortment decisions. Lawson's beverage procurement team now separates aseptic carton negotiations from refrigerated bottle tenders, enabling format-specific margin strategies. This bifurcation is most visible in Tokyo's 23 wards, where chilled soy milk bottles command shelf space previously reserved for dairy alternatives.
Japan Soy Beverages Market Segmentation
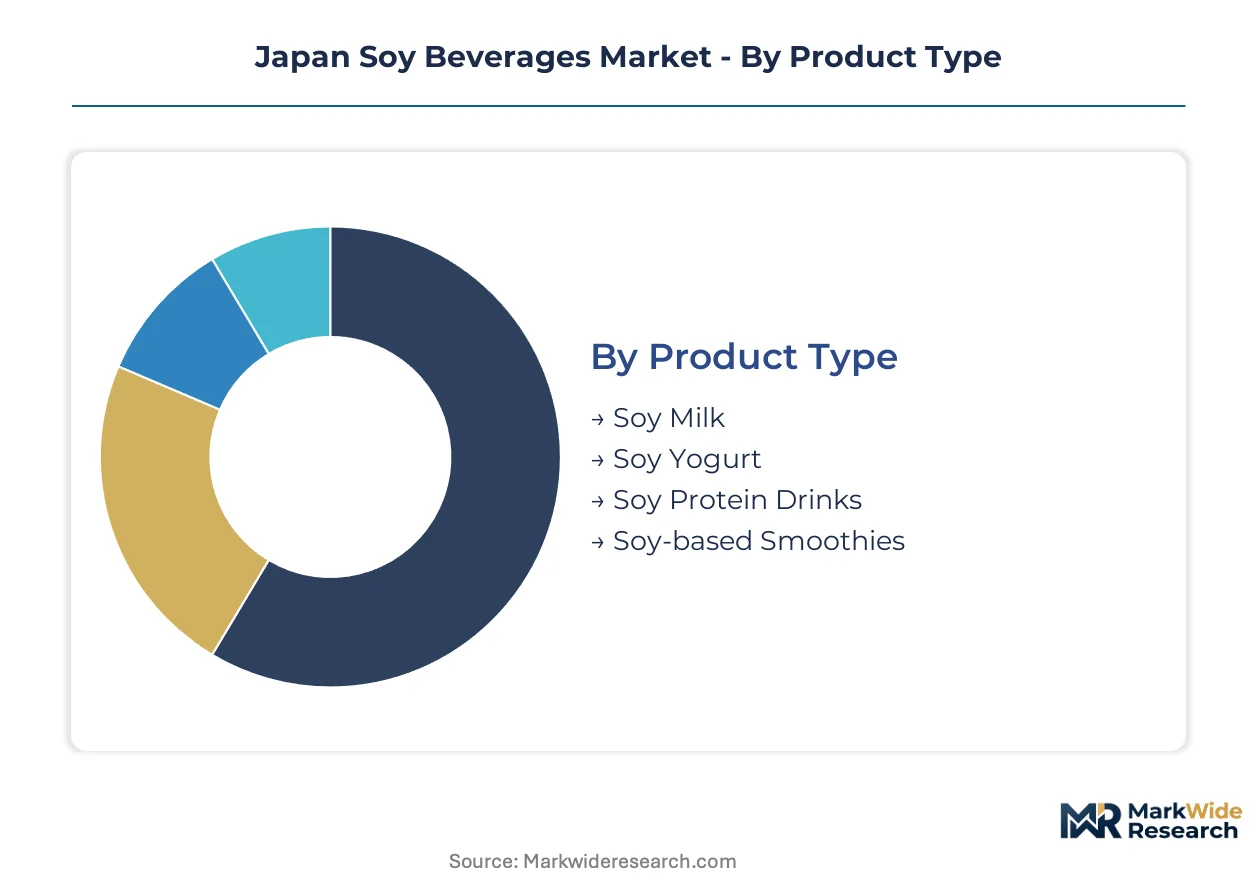
Segmentation in Japan's soy beverage market reveals how health positioning, shelf stability requirements, and retail channel economics partition margin capture. Manufacturers must align formulation investments with the specific compliance burdens and price elasticity of each segment cluster.
Product Type:
Margin pools concentrate in protein-fortified variants where clinical positioning commands shelf-space premiums and repeat purchase loyalty.
- Soy Milk:Aqueous extracts of whole soybeans processed through grinding, enzymatic treatment, and UHT sterilization to achieve colloidal stability. Tokyo's metropolitan retail corridor drives volume through convenience store chains and specialty grocers stocking expanded plain and flavored portfolios. METI's Food Labeling Standards mandate clear allergen declarations that favor established processors with validated supply chains.
- Soy Protein Drinks:Isolated protein formulations targeting sports nutrition and clinical dietary management with elevated protein density. Fitness centers and wellness programs across Tokyo, Osaka, and Nagoya normalize these as standard recovery nutrition, creating institutional demand channels with contracted volume commitments.
- Soy Yogurt:Fermented variants leveraging lactic acid cultures for digestive health positioning.
- Soy-based Smoothies:Ready-to-drink blended formats combining fruit purees with soy protein bases.
The dominant share belongs to Soy Milk, while Soy Protein Drinks is closing the gap fastest.
Flavor Profile:
Cost tier stratification separates commodity original formulations from premium positioned flavored variants with extended ingredient lists.
- Original:Unsweetened base formulations with minimal ingredient complexity and longest production runs. Plain soy milk occupies the largest volume position among product types, serving dairy alternative demand in household and foodservice channels.
- Sweetened:Sucrose or oligosaccharide-enhanced variants calibrated to Japanese palate preferences. Health-conscious consumers in fitness and wellness programs increasingly reject these for lower-glycemic alternatives, constraining growth in premium channels.
- Vanilla:Extract-infused positioning for younger demographics and dessert substitution occasions.
- Chocolate:Cocoa-fortified variants competing directly with dairy-based flavored milks in convenience store chilled sets.
Original formulations retain volume leadership, though Chocolate is expanding most quickly in convenience store refrigerated sections.
Packaging Type:
Application-specific requirements divide ambient distribution economics from chilled retail margin capture.
- Aseptic Cartons:Multi-layer laminated packaging enabling shelf life exceeding 180 days without refrigeration. Lawson's beverage procurement team separates aseptic carton negotiations from refrigerated bottle tenders, enabling format-specific margin strategies for ambient distribution.
- Bottles:PET or HDPE formats gaining traction in convenience store chilled sets. 7-Eleven and Lawson refrigerated sections now allocate shelf space previously reserved for dairy alternatives, opening premium price realization for bottle formats.
- Cans:Aluminum formats for single-serve consumption and vending machine compatibility.
- Pouches:Flexible packaging for portion-controlled and child-targeted product lines.
Aseptic Cartons dominate volume, yet Bottles is climbing the fastest as chilled channel bifurcation accelerates.
Distribution Channel:
Customer type concentration in health-motivated segments creates pricing power divergence between mass retail and specialty positioning.
- Supermarkets:Mass retail chains with standardized planogram negotiations and high-volume throughput. Kyushu and Tohoku regions present underdeveloped specialty grocer penetration, leaving supermarkets as the primary soy beverage access point in these prefectures.
- Health Stores:Dedicated wellness retailers stocking premium and functional-positioned variants. Soy protein drinks command premium shelf space in these channels, with PMDA FOSHU pathway enabling clinical-grade positioning for protein-fortified variants.
- Online Retail:Direct-to-consumer and marketplace platforms for subscription and bulk purchase models.
- Specialty Stores:Organic and natural product retailers with JAS certification requirements.
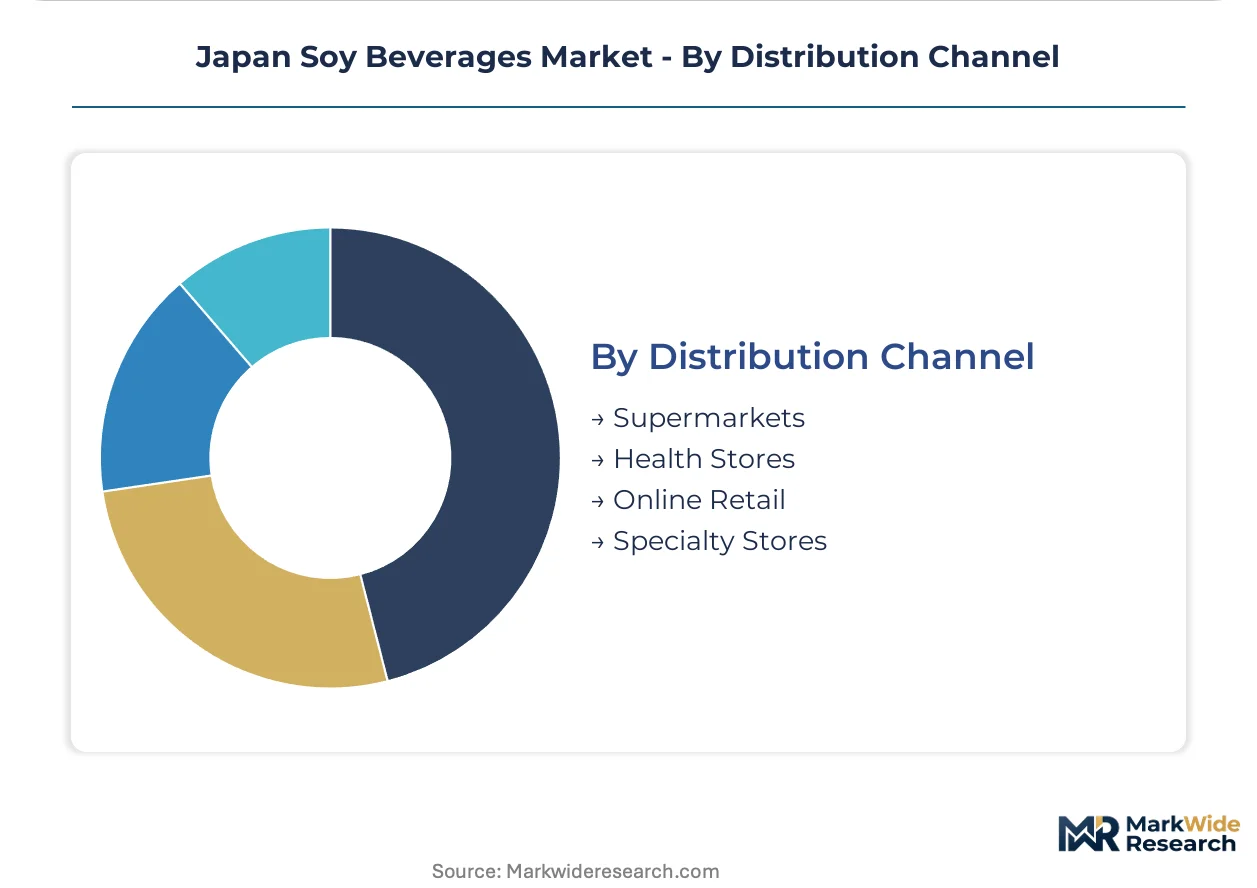
Supermarkets hold the dominant share, while Health Stores is gaining share fastest as functional positioning deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Japan's prefectures diverge sharply between metropolitan health-conscious adopters and rural traditional users. Tokyo's fitness culture normalizes protein-fortified variants, while Tohoku maintains stronger attachment to conventional plain soy milk in household cooking applications.
Kanto/Tokyo
Corporate wellness programs and boutique fitness studios drive institutional procurement of soy protein drinks. METI's Food Labeling Standards enforcement compresses formulation cycles for manufacturers headquartered in this corridor. Shibuya and Shinjuku convenience store clusters now allocate premium refrigerated shelf space to bottle-format soy beverages displacing dairy alternatives.
Kansai/Osaka
Traditional breakfast culture sustains volume demand for plain soy milk in foodservice channels. The Consumer Affairs Agency's functional food notification system sees concentrated filing activity from Osaka-based processors seeking FOSHU positioning. Sakai City's manufacturing belt hosts blending facilities serving western Japan's supermarket networks.
Chubu/Nagoya
Research infrastructure concentration in Aichi Prefecture shortens innovation-to-shelf timelines for functional variants. JAS organic certification requirements create compliance bottlenecks for processors sourcing from regional farm cooperatives. Toyota City's logistics hub enables efficient distribution to central Japan's specialty grocer channels.
Kyushu
Underdeveloped health store penetration leaves supermarkets as the primary soy beverage access point. Import dependency on North American feedstock exposes Fukuoka processors to currency volatility through Nagoya port clearance. Kumamoto's agricultural base supplies non-GMO soybeans for premium organic line development.
Tohoku
Demographic contraction constrains volume growth despite stable per-household consumption rates. Sendai's retail consolidation favors national brands with aseptic carton distribution economics over local bottlers. Iwate Prefecture's soybean cultivation supports traceable supply chains for JAS-certified organic positioning.
Japan Soy Beverages Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation heritage and pharmaceutical-grade positioning defining the upper layer. Mid-scale processors compete through format innovation in chilled convenience store channels. Three archetypes dominate: legacy brewers with captive soybean supply, pharmaceutical-derived nutrition specialists, and multinational dairy-alternative platforms. Competitive moves concentrate on aseptic bottling capacity expansion and PMDA FOSHU pathway navigation for functional claims.
Within the heritage-integrated tier, Kikkoman Corporation and MARUSAN-AI Co., Ltd anchor positions through Aichi and Chubu manufacturing concentration. Otsuka Pharmaceutical Co., Ltd occupies the clinical-positioning vector, representing the pharmaceutical-derived nutrition archetype. These three exemplify how vertical control over fermentation infrastructure or pharmaceutical distribution channels creates defensive moats against multinational entrants.
| Leading Market Players |
|---|
| Kikkoman Corporation |
| Lam Soon Group |
| Otsuka Pharmaceutical Co., Ltd. |
| MARUSAN-AI Co., Ltd |
| The Hain Celestial Group |
| Vitasoy International Holdings Limited |
| Sapporo Holdings Limited |
| Danone S.A. |
| Nestle S.A. |
| Others |
Supply & Pricing Matrix
METI's Food Labeling Standards gate both supplier qualification and price tier separation simultaneously. Manufacturers must validate cross-contamination protocols at the enzyme supplier level to access premium shelf space, while commodity plain soy milk competes on logistics efficiency alone.
Pricing Analysis
Long-term offtake contracts dominate procurement between Aichi-based processors and Tokyo metropolitan retailers, insulating volume commitments from currency swings. Three-tier pricing structure across premium, standard, and economy levels reflects JAS organic certification status and protein fortification density. Price differentiation centers on PMDA FOSHU pathway completion and aseptic bottling capability. Margins are tightening due to oat and almond alternatives capturing chilled retail space, with convenience store buyers extracting concessions through format-specific tenders.
Supply Chain Analysis
Inventory lead times for North American and Brazilian soybean feedstock stretch through Nagoya port clearance, exposing processors to working capital lockup. Geographic concentration draws from the United States, Brazil, and Canada for non-GMO and organic grades, while domestic Iwate Prefecture cultivation supports traceable JAS lines. The supply chain hinges on membrane filtration equipment sourced from specialized vendors in Saitama and Chiba. Tariff exposure on imported feedstock creates margin vulnerability. Distribution runs through Tokyo's metropolitan retail corridor, with Lawson and 7-Eleven procurement teams separating ambient carton from chilled bottle negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around convenience store chains and fitness center procurement committees, compressing manufacturer margins through format-specific tenders and institutional volume commitments.
For Market Incumbents: Shield fermentation infrastructure advantages by accelerating PMDA FOSHU filings for protein-fortified variants before regulatory documentation burdens intensify. Deepen backward integration into Iwate Prefecture organic soybean cultivation to secure JAS certification pipelines. Channel control through dedicated soymilk research facilities in Aichi Prefecture creates defensive moats against multinational entrants. For New Entrants and Emerging Players: JAS organic certification fast-track offers entry into specialty grocer channels with premium price realization. Kyushu and Tohoku regions present underdeveloped health store penetration where supermarket shelf access requires less capital intensity. Chilled convenience store bottle formats displace ambient cartons, enabling format-specific margin strategies without legacy aseptic line investments. For Investors and Strategic Acquirers: METI's 2025 allergen labeling enforcement timeline reshapes the acquisition landscape toward processors with validated supplier qualification workflows. Five-to-ten year viability favors pharmaceutical-derived nutrition specialists with clinical-grade distribution channels over commodity plain soy milk operators. Acquisition targets should demonstrate captive soybean supply or PMDA functional food notification pipeline depth. Monitor PMDA filing velocity as the inflection signal separating premium-positioned from commodity-tier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA FOSHU Pathway Navigation | Clinical-grade positioning unlocks health store shelf premiums and repeat purchase loyalty. |
| Aseptic Bottling Capacity Expansion | Automated sterilization lines favor incumbents with legacy fermentation infrastructure in Aichi. |
| Backward Integration into Organic Cultivation | Iwate Prefecture farm cooperatives supply traceable feedstock for JAS-certified line launches. |
| Chilled Distribution Channel Expansion | Lawson and 7-Eleven refrigerated sections displace dairy alternatives with bottle-format soy beverages. |
| Membrane Filtration Technology Adoption | Skid-mounted ultrafiltration units in Saitama enable small-batch functional variant production. |
Research Methodology
A standing panel of beverage procurement managers at convenience store chains, soymilk research directors in Aichi Prefecture, METI regulatory affairs specialists, and fitness center nutrition program coordinators provided ongoing calibration. Primary interviews combined with secondary validation against METI enforcement timelines, PMDA FOSHU filing databases, JAS organic certification records, and Lawson category management disclosures. Bottom-up volume modeling triangulated against top-down retail audit data from Tokyo's metropolitan corridor.
Consistency checks validated outputs against external benchmarks including customs records for North American and Brazilian soybean imports, aseptic packaging equipment deployment filings, and health store shelf-space allocation surveys. The analytical framework modeled product type, flavor profile, packaging format, and distribution channel dimensions across the analysis window. CAGRs derived from segment-level volume trajectories incorporating protein fortification protocol adoption rates and chilled channel bifurcation timing. Forecast inputs included enzymatic treatment expertise scarcity and JAS organic certification pipeline delays.
The analysis sits within stated boundaries; outcomes outside sustained METI enforcement intensity or abrupt feedstock trade friction would require recalibration. Forecasts reflect documented assumptions regarding convenience store buyer consolidation and PMDA notification processing capacity. Specific risks that could revise trajectories include currency volatility on Brazilian soybean imports and accelerated oat milk shelf capture in Tokyo's 23 wards. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market