
 Global Non-Alcoholic RTD Beverages Market | 2026-2036
Global Non-Alcoholic RTD Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Alcoholic RTD Beverages Market Foresight
Southeast Asia is tilting toward contract manufacturing expansion as multinational beverage firms seek lower-cost production bases with proximity to raw material suppliers. The Coca-Cola Company leverages its captive bottling network to control distribution density across emerging markets. PepsiCo anchors its growth in savory-snack and beverage cross-merchandising through controlled retail partnerships. Nestlé S.A. differentiates via R&D intensity in functional hydration and plant-based formulations.
Non-alcoholic RTD beverages comprise pre-packaged, shelf-stable or refrigerated drinks formulated without ethanol, typically processed through aseptic filling, hot-fill, or cold-press methods and preserved via pasteurization, carbonation, or acidification to achieve commercial sterility or extended ambient stability. Their primary purpose is to deliver convenient, portion-controlled refreshment and functional nutrition to away-from-home and at-home consumption occasions. Soft drinks and iced coffee command the largest volume pools, while iced tea and functional juices capture expanding margin pools as consumers trade up from commodity sodas. Online retail and specialty stores represent the fastest-growing distribution channels, though supermarkets still absorb the bulk of absolute volume throughput.
FDA nutrition labeling rules, EU Green Deal packaging mandates, and China's GB food safety standards collectively shape formulation choices, material specifications, and market access conditions across the three largest production zones. REACH chemical restrictions and evolving EFSA health claims protocols in Europe are forcing reformulations away from artificial sweeteners and toward natural extracts. Stakeholders must monitor how divergent recycling infrastructure investments across the United States, Germany, and Japan will reshape packaging format economics and brand compliance costs.
Market Dynamics
The EU Green Deal packaging mandates are compressing format economics across European supply chains while simultaneously accelerating investment in rPET and fiber-based alternatives. This regulatory pressure is hybridizing with consumer preference shifts toward functional hydration, creating a dual-force restructuring of formulation priorities and material specifications.
Growth Catalysts
- Functional Wellness Migration:Health clubs and fitness centers are expanding shelf space for electrolyte-enhanced and protein-fortified formats, pulling demand away from commodity soft drinks.
- REACH Chemical Reformulation:ECHA restrictions on artificial sweeteners are forcing natural extract adoption, opening margin pools for stevia and monk fruit suppliers.
- China Urban Format Shift:Middle-class consumers in Shanghai and Beijing are displacing traditional hot tea consumption with chilled, portable RTD alternatives.
Market Restraints
- rPET Supply Concentration:European recycling infrastructure bottlenecks in Germany and France are creating feedstock scarcity for compliant packaging.
- Input Cost Volatility:Aluminum can sheet and aseptic carton board prices fluctuate with energy market swings, compressing converter margins.
- Technical Shelf-Life Limitation:Cold-press and HPP-processed functional juices face shorter distribution radii than pasteurized alternatives, constraining channel expansion.
Strategic Opportunities
- Southeast Asia Contract Manufacturing:Vietnam and Indonesia offer proximity to tropical fruit raw materials with lower labor costs than coastal China.
- EU Green Deal Tailwind:Packaging directive compliance investments create first-mover advantage for brands with certified circular material flows.
- Online Retail Channel Innovation:Direct-to-subscription models bypass supermarket slotting fees while capturing consumer data for personalization.
Industry Challenges
- Formulation Talent Scarcity:Natural preservative chemistry and clean-label stability science require skill sets concentrated in limited geographic pools.
- Certification Timeline Friction:EFSA novel food and health claims approvals extend product development cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Alcoholic RTD Beverages Market |
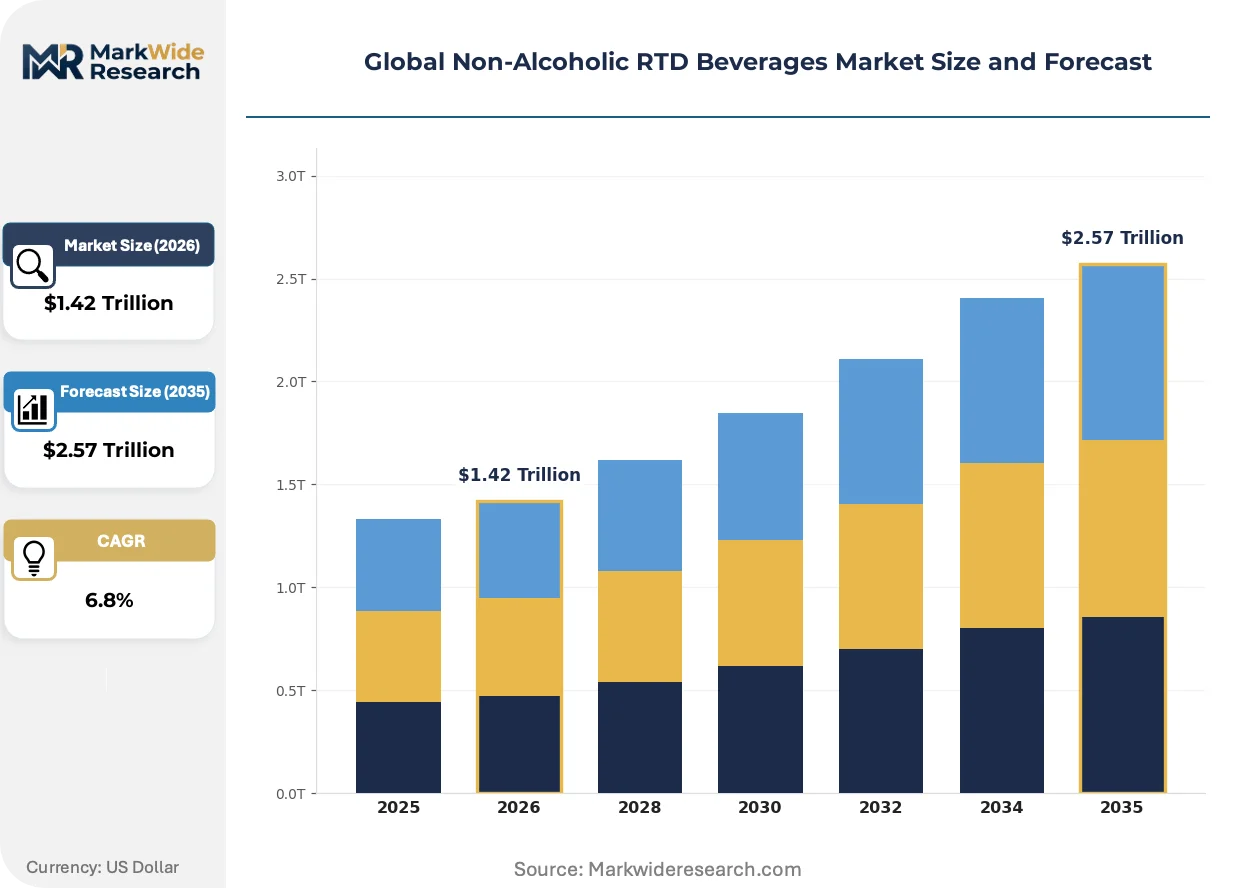
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.57 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juices, Soft Drinks, Iced Tea, Iced Coffee Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packaging Type: Bottles, Cans, Cartons, Pouches Customer Type: Retail Consumers, Foodservice Providers, Institutions, Health Clubs |
| Companies Covered | The Coca-Cola Company, PepsiCo, Inc., Keurig Dr Pepper Inc., Red Bull GmbH, Nestlé S.A., Suntory Holdings Limited, Danone S.A., Monster Beverage Corp., Asahi Group Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Alcoholic RTD Beverages Market Shifts & Advancements
Active hybridization across processing technologies, regulatory compliance frameworks, and distribution architectures is fragmenting the traditional mass-market model. Three converging developments are compressing legacy competitive advantages.
Aseptic filling technology is hybridizing with cold-press extraction methods to deliver extended ambient stability without thermal degradation of heat-sensitive actives. Premium functional juice brands in Germany and Japan are piloting these hybrid lines to capture both convenience and nutrition-positioning premiums. The structural consequence is margin compression for conventional hot-fill processors unable to justify capital conversion.
REACH chemical restrictions and evolving EFSA health claims protocols are forcing simultaneous reformulation of sweetener systems and substantiation of functional benefits. European brands must now document bioactive stability across shelf life while eliminating synthetic preservatives. The segment most affected is mid-tier functional waters, where compliance costs are displacing smaller regional players.
Health club procurement is consolidating around bundled hydration and recovery portfolios, compressing the number of approved vendor slots per facility chain. Specialty distributors with cold-chain capabilities are displacing traditional broadline foodservice suppliers in this channel. This pattern is most visible in the United States, where Equinox and Life Time Fitness have reduced their RTD beverage vendor bases by half since 2022.
Global Non-Alcoholic RTD Beverages Market Segmentation
Segmentation in the non-alcoholic RTD beverages market reveals how formulation priorities, channel economics, and material specifications diverge across consumption occasions. Each dimension carries distinct regulatory exposure and margin architecture that shapes competitive positioning.
Product Type:
Consumption occasions span from daily refreshment to functional performance, with formulation intensity and price positioning scaling accordingly.
- Soft Drinks:Carbonated formulations dominate absolute volume throughput, anchored by established bottling infrastructure and supermarket distribution density. Demand concentrates in emerging markets where price elasticity favors single-serve PET formats over premium alternatives.
- Iced Coffee:Cold-brew and dairy-integrated formulations command expanding shelf space in convenience channels across Japan and South Korea. Urban professionals in Seoul and Tokyo are displacing hot coffee consumption with ready-to-drink formats that merge caffeine delivery with portability.
- Juices:NFC and HPP-processed variants target wellness-positioned consumers seeking vitamin fortification without added sugars.
- Iced Tea:Botanical and adaptogen-infused formulations capture margin premiums in specialty retail, though volume remains concentrated in mass-market sweetened variants.
Established volume favors Soft Drinks; emerging adoption favors Iced Coffee.
Distribution Channel:
Channel selection determines cold-chain requirements, slotting fee exposure, and consumer data capture potential.
- Supermarkets:Traditional hypermarket and grocery chains absorb the bulk of absolute volume throughput, leveraging centralized procurement and promotional scale. Demand concentrates in suburban family purchasing across the United States and Germany, where multi-pack formats reduce per-unit cost.
- Online Retail:Direct-to-subscription and marketplace models bypass traditional slotting fees while enabling personalization through consumption data analytics. Urban millennials in Shanghai and London are driving subscription growth for functional hydration portfolios.
- Convenience Stores:Impulse-driven single-serve purchases dominate, with format size optimized for immediate consumption.
- Specialty Stores:Curated assortments of craft and functional brands target premium positioning with educated consumer bases.
Volume gravity centers on Supermarkets; margin expansion concentrates in Online Retail.
Packaging Type:
Material selection reflects regulatory compliance pressure, recycling infrastructure maturity, and product shelf-life requirements.
- Bottles:PET and rPET formats dominate still beverages, with lightweighting and recycled content ratios tightening under EU Green Deal mandates. German and French supply chains face feedstock scarcity as recycling infrastructure bottlenecks compress compliant material availability.
- Cans:Aluminum formats capture carbonated and energy drink segments, with sheet price volatility tracking energy market swings. Demand concentrates in sports and outdoor consumption occasions where durability and chill speed matter.
- Cartons:Aseptic carton board serves ambient-stable juices and dairy alternatives, though converter margins compress with pulp and energy input costs.
- Pouches:Flexible formats reduce material weight and shipping cube, finding traction in child-targeted and on-the-go segments.
Regulatory compliance favors Bottles; operational flexibility favors Pouches.
Customer Type:
End-user procurement patterns fragment across retail, institutional, and performance-oriented channels with divergent service requirements.
- Retail Consumers:Individual purchasers drive volume through supermarket and convenience channels, with loyalty programs and promotional elasticity shaping brand switching behavior.
- Health Clubs:Fitness center procurement is consolidating around bundled hydration and recovery portfolios, compressing approved vendor slots per facility chain. Equinox and Life Time Fitness in the United States have halved their RTD beverage vendor bases since 2022.
- Foodservice Providers:Restaurants and cafes source fountain and pre-packaged formats with cost and consistency priorities dominating selection.
- Institutions:Schools, hospitals, and corporate cafeterias operate under procurement regulations that favor nutritional labeling transparency and portion control.
Procurement consolidation concentrates in Health Clubs; volume scale remains with Retail Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Chinese consumers prioritize chilled portability over traditional hot formats, while German buyers respond to EU packaging mandates with recycled-content preferences. American fitness channels drive functional hydration demand distinct from commodity refreshment elsewhere.
United States
Health clubs and fitness centers are consolidating vendor portfolios around bundled hydration offerings. FDA nutrition labeling rules shape formulation transparency requirements for institutional procurement. Equinox and Life Time Fitness chains in California and Texas have halved approved RTD beverage suppliers since 2022.
China
Urban middle-class consumers in Shanghai and Beijing are displacing hot tea traditions with chilled portable formats. SAMR and GB food safety standards govern additive approvals and shelf-life claims. The Yangtze River Delta manufacturing corridor hosts expanding aseptic filling capacity for export-ready production.
Germany
EU Green Deal packaging directives are compressing rPET feedstock availability as recycling infrastructure bottlenecks persist. REACH chemical restrictions accelerate reformulation away from artificial sweeteners toward stevia and monk fruit extracts. Bavarian beverage converters face margin pressure from energy-linked aluminum sheet volatility.
Japan
Cold-brew coffee and dairy-integrated RTD formats command expanding convenience channel space. METI efficiency standards and JIS packaging specifications influence material selection and lightweighting targets. Tokyo and Osaka metropolitan clusters anchor premium functional beverage development for aging-consumer nutrition positioning.
Brazil
Tropical fruit raw material proximity supports contract manufacturing expansion for multinational brands. ANVISA regulates novel ingredient approvals and health claim substantiation with extended review timelines. São Paulo state concentrates blending and aseptic processing infrastructure for Mercosur distribution.
Global Non-Alcoholic RTD Beverages Market Competitive Landscape
Capability concentration sits with R&D-intensive functional specialists; scale advantage sits with captive bottling networks and cross-merchandising conglomerates. The market structures around three tiers: multinational beverage conglomerates with integrated distribution, regional contract manufacturers with tropical fruit access, and premium functional specialists with clean-label formulation science. Dominant competitive moves include strategic partnerships with health club chains and backward integration into recycled packaging feedstock.
Among multinational conglomerates, The Coca-Cola Company and PepsiCo occupy positions defined by distribution density and retail partnership control, while Nestlé S.A. exemplifies the R&D-intensive archetype through functional hydration and plant-based formulation investment. These three anchors represent distinct strategic postures: captive bottling network scale, savory-snack cross-merchandising synergy, and science-driven premium positioning respectively.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Keurig Dr Pepper Inc. |
| Red Bull GmbH |
| Nestlé S.A. |
| Suntory Holdings Limited |
| Danone S.A. |
| Monster Beverage Corp. |
| Asahi Group Holdings, Ltd. |
| Others |
Supply & Pricing Matrix
Aseptic filling overcapacity in coastal China is compressing contract manufacturing rates while simultaneously pulling formulation talent toward functional beverage specialists. This utilization asymmetry rewards brands with captive R&D capabilities and squeezes commodity processors dependent on spot production slots.
Pricing Analysis
Long-term offtake agreements between multinational brands and Southeast Asian contract manufacturers anchor volume pricing, with spot arrangements filling seasonal demand surges. Three-tier pricing structure across premium functional, standard refreshment, and economy private-label levels reflects certification grade and cold-chain investment differentiation. Cost compression in the standard tier is intensifying because aluminum sheet and aseptic carton board prices track energy market volatility. Health club procurement teams exhibit the lowest price sensitivity due to bundled portfolio requirements, while convenience store operators maximize margin through high-velocity commodity SKUs.
Supply Chain Analysis
Contract manufacturing concentration rests with Vietnamese and Indonesian processors serving tropical fruit-dependent formulations, while German and Japanese converters dominate aseptic technology deployment. Raw material sourcing draws from Brazilian orange concentrate, Indian stevia extracts, and Chinese aseptic carton board. Single-source vulnerability concentrates in German rPET recycling infrastructure, where feedstock scarcity threatens EU Green Deal compliance timelines. Distribution runs through captive bottling networks in emerging markets and specialty cold-chain distributors in health club channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional hydration represents a high-growth disruption as EU REACH restrictions and FDA labeling rules simultaneously force reformulation investment and substantiation science. This regulatory-technological inflection rewards first-movers with certified clean-label capabilities.
For Market Incumbents: Entrench market position through backward integration into recycled packaging feedstock and captive aseptic filling capacity in the Yangtze River Delta. Consolidate health club vendor relationships before procurement rationalization eliminates secondary suppliers. R&D intensity in natural preservative chemistry offers defensive moats against emerging clean-label specialists. For New Entrants and Emerging Players: Mid-tier functional waters in Germany and France represent the most penetrable entry point as compliance costs displace smaller regional players. Southeast Asian contract manufacturing partnerships with tropical fruit proximity enable cost-competitive botanical formulation. Direct-to-subscription models bypass supermarket slotting fees while capturing consumption data for personalization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among functional beverage specialists with health club subscription partnerships and certified circular packaging flows. Five-to-ten year viability favors targets with EFSA novel food approval pipelines and stevia supply chain control. Monitor EFSA health claims approval velocity as an inflection indicator for premium positioning sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Feedstock | EU Green Deal compliance creates first-mover certification advantage for circular material flows. |
| Health Club Subscription Partnerships | Equinox and Life Time Fitness procurement consolidation favors bundled hydration portfolio suppliers. |
| ASEAN Contract Manufacturing Expansion | Vietnamese and Indonesian processors offer tropical fruit proximity with lower labor costs than coastal China. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket slotting fees while capturing consumption analytics for personalization. |
| Natural Extract Formulation Investment | REACH chemical restrictions force stevia and monk fruit adoption, opening margin pools for compliant suppliers. |
Research Methodology
The analysis maps soft drinks, iced coffee, functional juices, and iced tea segments, each validated through supply chain interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners. Primary fieldwork combined with secondary validation from Nielsen retail audit data, customs records, SEC 10-K filings, and EFSA novel food approval databases. Bottom-up volume modeling and top-down macroeconomic triangulation anchored market sizing across the analysis window.
Assumptions held fixed include EU Green Deal packaging directive timelines, FDA nutrition labeling enforcement intensity, and China GB food safety standard stability; variables included aluminum and pulp input cost trajectories, health club procurement consolidation velocity, and EFSA health claims approval cadence. Segmentation modeling spanned product type, distribution channel, packaging format, and customer archetype dimensions. CAGRs derived from regression analysis against historical volume trends, with aseptic filling capacity expansion and functional ingredient adoption curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy market volatility, currency fluctuation across ASEAN manufacturing corridors, or recycling infrastructure investment delays would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and consumer preference stability. Quarterly review of EFSA approval pipelines, rPET feedstock pricing, and health club vendor consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market