
 Hydrogen Water Machine Market | 2026-2036
Hydrogen Water Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Water Machine Market Analysis
The hydrogen water machine market is recalibrating around a widening split between medical-grade electrolysis systems priced above five hundred dollars and entry-level portable units sold through mass retail. Olansi Healthcare Co., Ltd. leverages its manufacturing scale in Guangdong to supply private-label machines across Southeast Asian e-commerce channels. Tyent USA anchors its position in North American direct-to-consumer sales through extended warranty programs and certified installation networks. Enagic USA, Inc. differentiates through multi-level distribution that sustains premium positioning despite price competition from Chinese imports.
A hydrogen water machine generates dissolved hydrogen gas in potable water through electrolytic or catalytic processes, typically achieving concentrations between 0.5 and 1.6 parts per million depending on electrode material and chamber pressure. These devices serve health-conscious consumers seeking antioxidant intake through hydration rather than supplemental delivery. Portable units lead unit shipments among travelers and office workers prioritizing convenience over output volume, while under-sink installations command the strongest margin pools in residential renovation projects. Electrolysis technology dominates commercial specifications for gyms and medical facilities requiring consistent hydrogen concentration validation.
The US FDA regulates hydrogen water devices under food-contact substance notifications, while Japan's Consumer Affairs Agency enforces functional food labeling standards that constrain health-claim marketing. South Korea's MFDS maintains separate medical-device classification pathways for machines targeting therapeutic versus general wellness applications. Stakeholders must monitor evolving electrolyte membrane safety standards and country-specific import certification requirements that could reshape competitive access across Pacific Rim markets.
Market Dynamics
The hydrogen water machine market is bifurcating around electrolysis membrane quality tiers, with platinum-coated titanium electrodes separating medical-grade specifications from mass-market units and reshaping margin structures across manufacturing clusters.
Growth Catalysts
- Japan's functional food labeling standards:Certification pathways through the Consumer Affairs Agency legitimize health-positioning claims, accelerating retail penetration in Tokyo and Osaka wellness channels.
- Gym and medical facility procurement:Electrolysis-based systems with validated hydrogen concentration outputs are displacing catalytic alternatives in South Korean fitness chains and rehabilitation centers.
- Platinum electrode supply concentration:Japanese and German precious metals processors maintain quality benchmarks that sustain premium pricing for validated medical-grade installations.
Market Restraints
- Proton exchange membrane cost volatility:Perfluorinated ionomer supply tightness from Belgian and Japanese chemical producers compresses margins on mid-tier countertop units.
- FDA food-contact notification timelines:Pre-market clearance requirements for new electrode materials extend US commercialization cycles by eight to fourteen months versus Asian regulatory pathways.
- Portable hydrogen tablet substitution:Magnesium-based effervescent alternatives at one-tenth the unit cost capture price-sensitive travelers and occasional users in Southeast Asian markets.
Strategic Opportunities
- Underpenetrated German wellness retail:Pharmacy and physiotherapy channel gaps for certified hydrogen devices present first-mover positioning ahead of EFSA health claim harmonization.
- Integration with smart home water systems:IoT-enabled flow sensors and app-based concentration tracking are converging with existing under-sink filtration infrastructure in South Korean apartment renovations.
- South Korea MFDS medical-device pathway:Therapeutic classification for hydrogen inhalation-capable machines unlocks reimbursement-adjacent positioning in pulmonary rehabilitation clinics.
Industry Challenges
- Electrochemist talent scarcity:Specialized membrane fabrication and electrode coating expertise concentrates in Osaka and Stuttgart industrial clusters, constraining new entrant scale-up.
- Multi-jurisdiction certification complexity:Divergent electrical safety and materials testing requirements across PSE (Japan), KC (South Korea), and CE marking (EU) extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Water Machine Market |
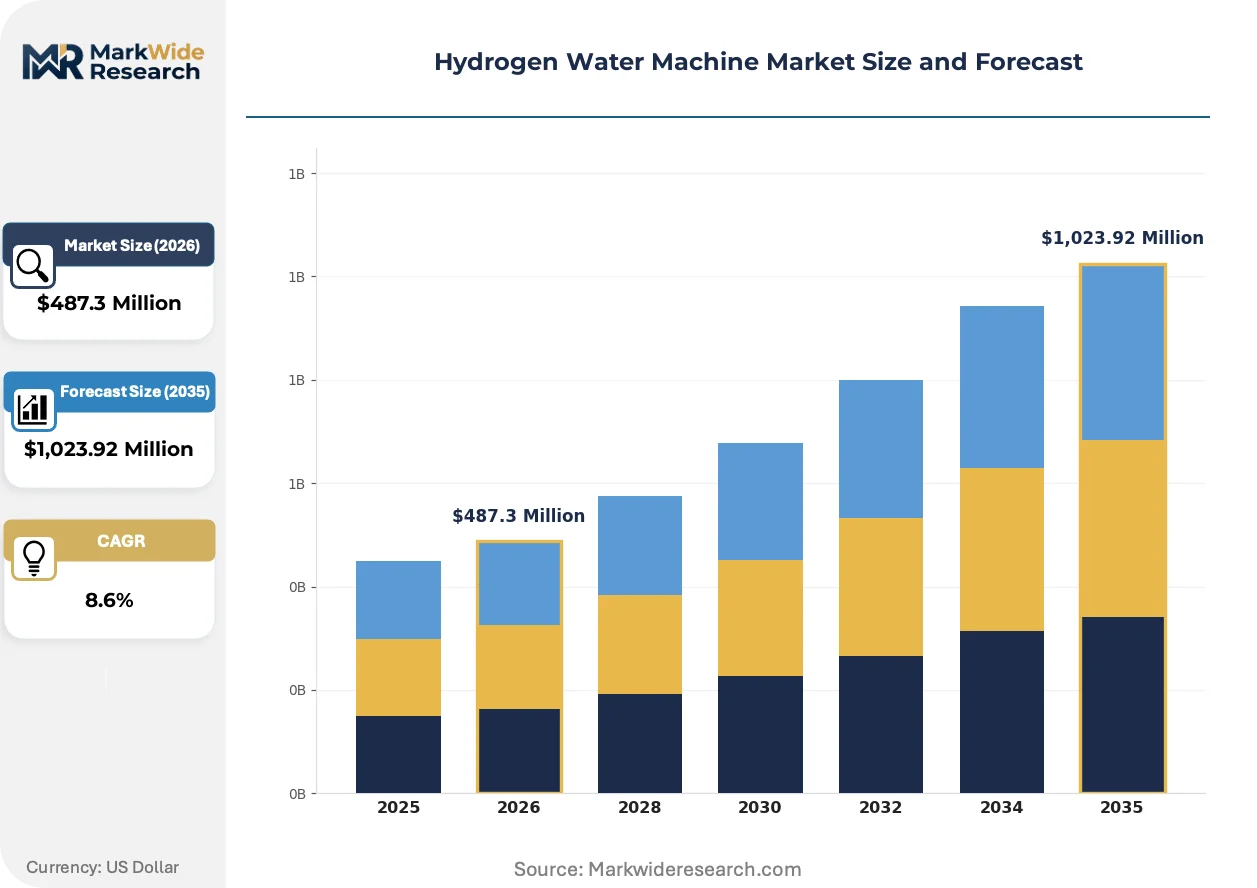
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Countertop, Under-Sink, Dispenser Technology: Electrolysis, Membrane Separation, Pressure Swing Adsorption, Catalytic Application: Health & Wellness, Hydration, Sports, Beauty End User: Households, Gyms, Spas, Medical Facilities |
| Companies Covered | Olansi Healthcare Co., Ltd., AlkaViva, LLC, Tyent USA, Enagic USA, Inc., Echo Water, Bawell, Trusii International, Lourdes Hydrogen Water, H2 Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Water Machine Market Emerging Trajectories
Solid-state electrolysis architectures and membrane electrode assembly miniaturization are compressing form factors while elevating output consistency, reshaping competitive differentiation around validation protocols rather than raw hydrogen concentration claims.
Solid polymer electrolyte stacks with platinum-clad titanium mesh electrodes are absorbing quality-sensitive demand from medical and athletic end-uses. Japanese rehabilitation centers and South Korean professional sports facilities specify these systems for session-to-session concentration reproducibility. The technology is absorbing margin pools previously captured by larger chamber volume designs.
South Korea's MFDS has tightened medical-device classification criteria for hydrogen inhalation functions, forcing manufacturers to separate wellness and therapeutic SKUs. This bifurcation is fragmenting product portfolios and requiring dual-track regulatory submissions. Portable units without inhalation modes face lighter compliance burdens and faster Korean market entry.
Direct-to-consumer subscription models for filter replacement and membrane refurbishment are displacing traditional distributor service networks. Australian and Canadian buyers increasingly expect app-managed consumable logistics bundled with hardware purchases. This unbundling is most visible in North American e-commerce channels where warranty registration rates correlate with subscription attachment.
Hydrogen Water Machine Market Segmentation
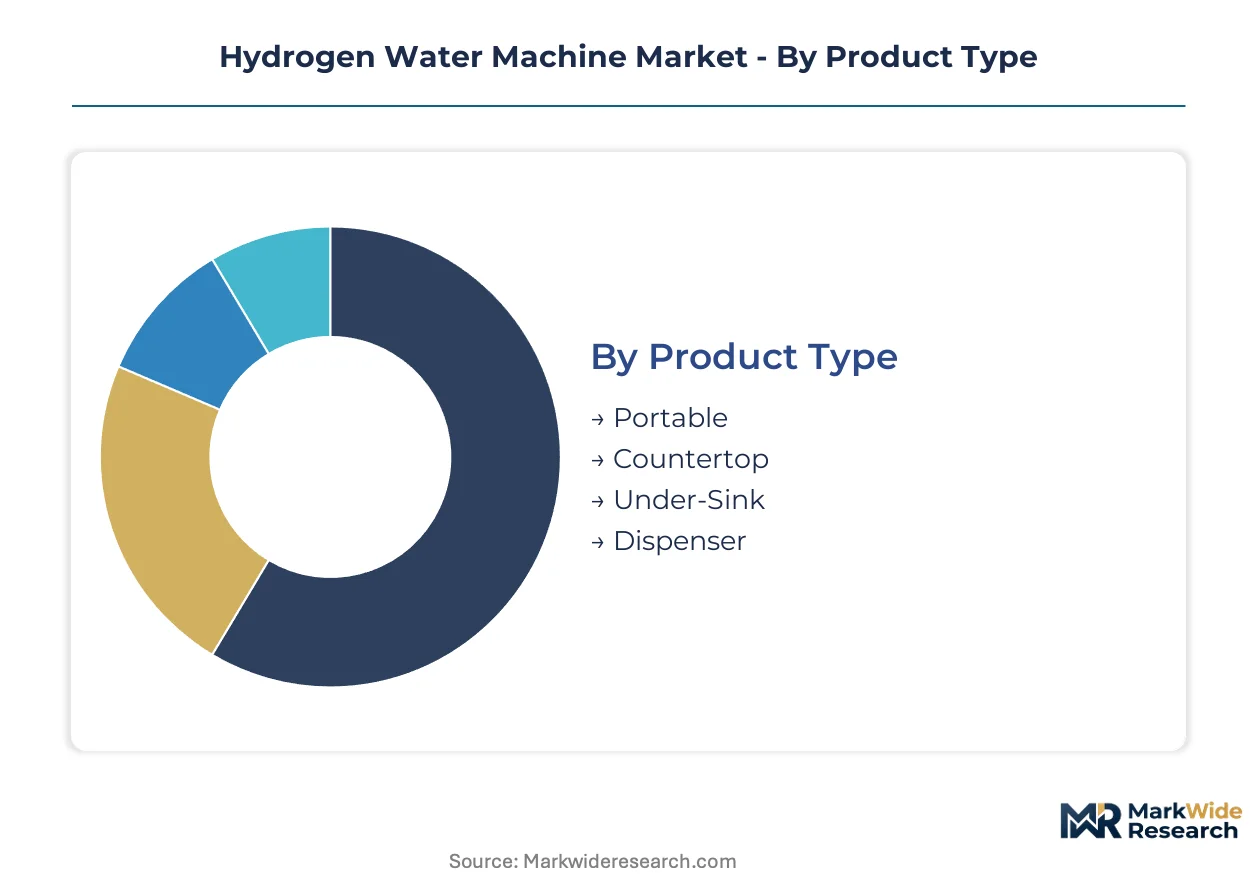
Upgrade cycles vary dramatically across hydrogen water machine categories. Medical facilities replace electrolysis membranes on fixed schedules, while households delay countertop refreshes until performance degradation becomes noticeable. Understanding these replacement rhythms clarifies where manufacturers should concentrate service revenue versus new-unit marketing.
Product Type:
Replacement urgency separates portable units—often discarded after two years—from under-sink installations where membrane refurbishment extends operational life to eight years.
- Portable:Compact battery-powered units with 200-500ml chamber capacity target travelers and office workers. Demand clusters in Tokyo and Osaka commuter corridors where convenience outweighs concentration consistency. Japanese airlines restrict hydrogen cylinder transport, accelerating interest in self-generating portable alternatives.
- Countertop:Plug-in units with 1-2 liter reservoirs dominate South Korean apartment kitchens. Seoul's dense housing favors space-efficient designs over under-sink complexity. MFDS certification requirements for countertop models remain lighter than medical-grade specifications.
- Under-Sink:Permanent installations with dedicated plumbing connections serve renovation-minded households. German wellness retail channels show emerging interest ahead of EFSA harmonization.
- Dispenser:High-volume floor-standing units for commercial settings. Gym chains in Busan and Gwangju specify validated output for member retention programs.
Volume placements concentrate in Countertop; the faster expansion belongs to Portable.
Technology:
Cost tiers stratify sharply by electrode material and membrane fabrication precision.
- Electrolysis:Platinum-coated titanium electrodes achieve 0.8-1.6 ppm dissolved hydrogen through proton exchange membrane stacks. Medical facilities in Osaka and rehabilitation centers in Daegu mandate this technology for session-to-session reproducibility. Belgian perfluorinated ionomer supply constraints compress margins on mid-tier implementations.
- Membrane Separation:Selective permeability films separate hydrogen from electrolytic byproducts without precious metal catalysts. Chinese manufacturers favor this approach for export price positioning.
- Pressure Swing Adsorption:Cyclic pressurization extracts hydrogen from mixed gas streams. Industrial-scale applications predominate; consumer adoption remains limited.
- Catalytic:Magnesium or aluminum alloys generate hydrogen through water reaction. Southeast Asian markets absorb these units where upfront cost sensitivity dominates.
Revenue pools concentrate in Electrolysis; Catalytic captures the steepest volume expansion trajectory in emerging markets.
Application:
Customer maturity determines whether purchases follow wellness trends or medical protocols.
- Health & Wellness:General antioxidant positioning targets prevention-focused consumers. Japan's Consumer Affairs Agency functional food labeling legitimizes claims, accelerating retail penetration in pharmacy channels.
- Hydration:Daily consumption habits drive replacement filter subscriptions. Australian direct-to-consumer models bundle membrane refurbishment with app-managed logistics.
- Sports:Athletic recovery protocols specify validated hydrogen concentration. South Korean professional baseball and football facilities require certified output documentation.
- Beauty:Topical and ingestible hydrogen applications for skin health. Tokyo aesthetic clinics pilot combination therapies ahead of broader adoption.
Placement frequency runs highest in Hydration; Sports applications are climbing the fastest among certified medical-grade purchasers.
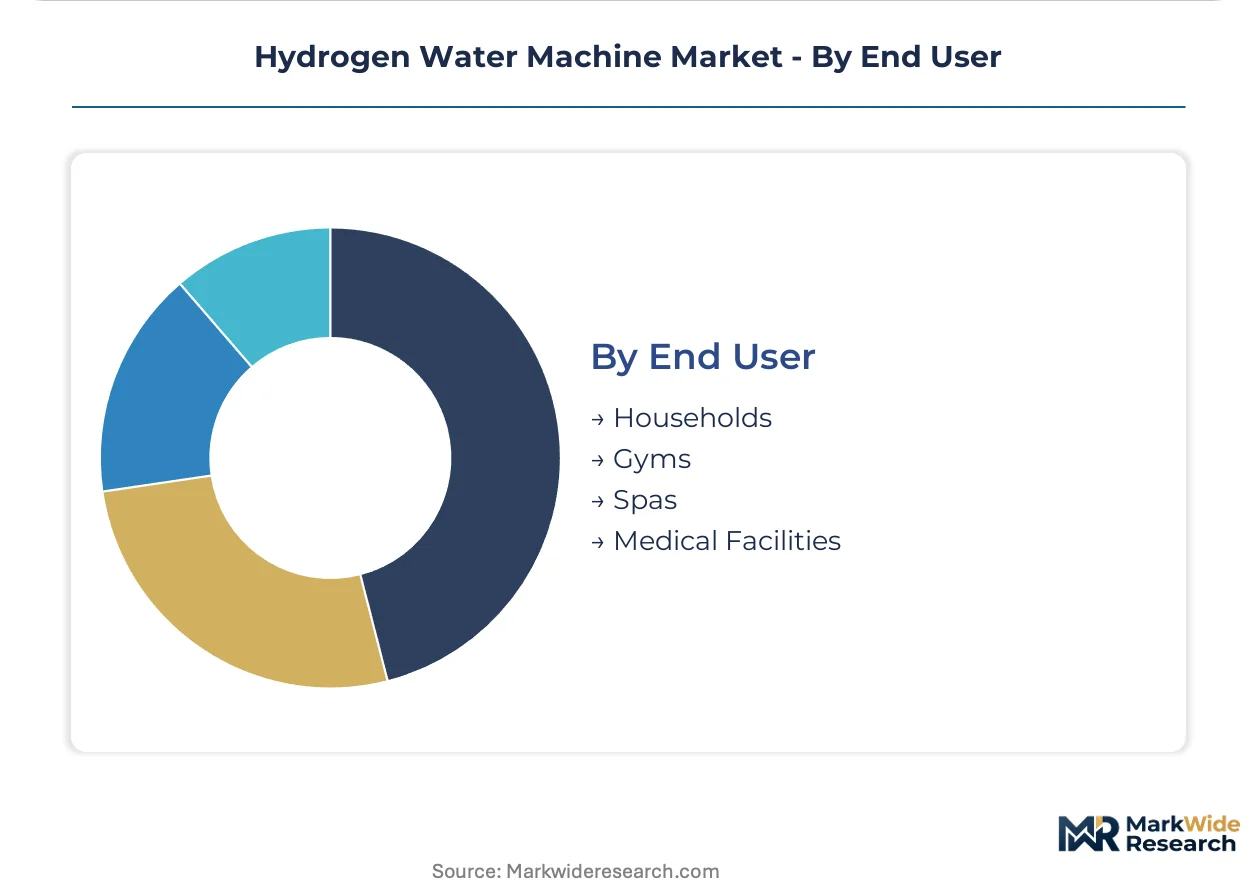
End User:
Procurement authority structures separate household discretionary spending from institutional specification committees.
- Households:Individual purchasers respond to wellness marketing and peer recommendations. Seoul apartment renovations increasingly specify IoT-enabled concentration tracking.
- Gyms:Facility managers balance member experience claims against capital expenditure constraints. South Korean fitness chains displace catalytic alternatives with validated electrolysis systems.
- Spas:Experience-oriented positioning emphasizes relaxation and recovery. Japanese onsen-integrated wellness resorts pilot hydrogen inhalation combination therapies.
- Medical Facilities:Rehabilitation centers and pulmonary clinics require therapeutic-grade classification. MFDS medical-device pathways for hydrogen inhalation functions force SKU bifurcation.
Unit shipments concentrate in Households; Medical Facilities command the strongest margin expansion as certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka's industrial corridor anchors electrolysis membrane fabrication for medical-grade hydrogen water systems, with precision electrode coating facilities supplying certified installations across East Asian rehabilitation networks.
Japan
Tokyo and Osaka wellness channels absorb premium countertop units as the Consumer Affairs Agency enforces functional food labeling standards that legitimize antioxidant positioning claims. METI coordinates with JIS standard-setters to validate electrode material safety for household installations. Nagoya's precision manufacturing cluster produces platinum-clad titanium mesh electrodes for session-to-session concentration reproducibility in medical facilities.
South Korea
Seoul apartment renovations specify IoT-enabled under-sink systems with app-based concentration tracking integrated into smart home water infrastructure. MFDS maintains separate medical-device classification pathways for therapeutic hydrogen inhalation functions versus general wellness applications. Busan and Gwangju gym chains displace catalytic alternatives with validated electrolysis systems for member retention programs.
United States
Direct-to-consumer channels concentrate in California and New York wellness markets where extended warranty programs anchor premium positioning. FDA food-contact substance notifications regulate new electrode materials, extending commercialization cycles versus Asian pathways. Certified installation networks in Texas and Florida support under-sink renovation demand.
Germany
Pharmacy and physiotherapy channel gaps in Bavaria and North Rhine-Westphalia present first-mover positioning ahead of EFSA health claim harmonization. CE marking requirements and RoHS compliance constrain electrode material sourcing for mass-market entry. Stuttgart's industrial cluster concentrates electrochemist talent for membrane fabrication expertise.
China
Guangdong manufacturing bases supply private-label machines across Southeast Asian e-commerce channels at compressed price points. SAMR and GB standards govern electrical safety and materials testing for domestic sales. Zhejiang and Jiangsu provinces concentrate catalytic unit production for export markets where upfront cost sensitivity dominates.
Hydrogen Water Machine Market Vendor Landscape
Premium-margin players sit above commodity-margin players across electrode material certification tiers, with platinum-coated titanium specifications separating medical-grade installations from mass-market portable units. The vendor base stratifies around three archetypes: Guangdong-based contract manufacturers supplying private-label channels, North American direct-to-consumer specialists bundling subscription services, and Japanese precision fabricators targeting institutional certification requirements. Dominant competitive moves include geographic expansion through e-commerce platform partnerships and portfolio diversification into hydrogen inhalation-capable SKUs.
Within the precision fabrication tier, Enagic USA, Inc. and Tyent USA exemplify warranty-backed positioning in certified installation networks, while Olansi Healthcare Co., Ltd. anchors the contract manufacturing archetype for Southeast Asian e-commerce penetration. These three entities occupy distinct margin tiers without overlapping channel strategies.
| Leading Market Players |
|---|
| Olansi Healthcare Co., Ltd. |
| AlkaViva, LLC |
| Tyent USA |
| Enagic USA, Inc. |
| Echo Water |
| Bawell |
| Trusii International |
| Lourdes Hydrogen Water |
| H2 Life |
| Others |
Supply Flow & Price Mechanics
Electrochemist talent concentration in Osaka and Stuttgart industrial clusters creates labor-cost differentials that widen pricing-tier spreads between medical-grade and mass-market hydrogen water machines. Premium fabricators absorb specialized membrane-coating expertise into platinum-electrode specifications, while Guangdong contract manufacturers exploit assembly-labor arbitrage to supply private-label channels at compressed price points.
Pricing Analysis
Outcome-based pricing anchors on validated hydrogen concentration reproducibility rather than hardware specifications alone. Three-tier pricing structure across premium, standard, and economy levels separates platinum-clad titanium medical-grade installations from mid-tier countertop units and catalytic portable alternatives. Cost compression in the mid-tier segment is intensifying because Belgian perfluorinated ionomer supply constraints squeeze membrane margins. Household purchasers in Southeast Asian e-commerce channels exhibit the highest price sensitivity, while Japanese rehabilitation centers and South Korean professional sports facilities demonstrate minimal elasticity for certified therapeutic-grade systems.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precious metals processors for platinum-clad titanium electrode fabrication. Manufacturing draws from concentrated supply bases in Japan, South Korea, and China's Guangdong province for electrolysis membrane stacks, precision coating equipment, and final assembly operations. Raw material dependencies include platinum group metals from South African and Russian mining operations, perfluorinated ionomers from Belgian and Japanese chemical producers, and titanium mesh substrates from Chinese metallurgical facilities. Tariff exposure on electrode materials shipped across Pacific Rim trade lanes threatens margin stability for North American direct-to-consumer brands. Distribution runs through certified installation networks for under-sink systems, pharmacy and physiotherapy channels for medical-grade units, and e-commerce platforms for portable and countertop alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capability barriers that force undercapitalized catalytic-unit assemblers toward private-label commoditization or exit.
For Market Incumbents: Hedge platinum-electrode supply exposure through captive relationships with Nagoya precision-coating facilities or backward integration into membrane-electrode assembly operations. Defensive moves must address magnesium-based tablet substitution threatening portable-unit margins in Southeast Asian travel segments, while reinforcing MFDS therapeutic-classification pathways to lock in medical-facility procurement specifications. For New Entrants and Emerging Players: The mid-tier price-point gap between premium electrolysis systems and economy catalytic units offers white-space positioning for membrane-separation technology without precious-metal catalysts. German pharmacy and physiotherapy channels ahead of EFSA health-claim harmonization represent the most penetrable geography. A direct-to-consumer subscription model bundling filter replacement with app-managed logistics offers the clearest go-to-market angle against established distributor networks. For Investors and Strategic Acquirers: Re-rating potential sits with precision-fabrication specialists possessing dual-track regulatory submissions across MFDS wellness and therapeutic classifications given tightening certification requirements. Long-term viability favors acquirers targeting membrane-electrode assembly expertise transferable across hydrogen inhalation-capable SKU expansions. The signal to watch is MFDS medical-device pathway approval velocity for hydrogen inhalation functions as inflection indicator for reimbursement-adjacent positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Regulatory Submission | MFDS wellness and therapeutic classifications unlock distinct margin pools in South Korean medical channels. |
| Backward Integration into Membrane Fabrication | Osaka and Stuttgart electrochemist talent concentration justifies captive coating facility investment for quality control. |
| IoT-Enabled Subscription Launch | Australian and Canadian direct-to-consumer markets demonstrate attach-rate correlation with warranty registration. |
| Pharmacy Channel Partnership | German Bavaria and North Rhine-Westphalia distribution gaps offer first-mover positioning before EFSA harmonization. |
| Platinum Electrode Supply Agreement | Japanese precious metals processors maintain quality benchmarks that sustain premium pricing for medical-grade installations. |
Methodological Framework
Document review covered SEC filings from hydrogen water machine manufacturers, FDA food-contact substance notification databases, MFDS medical-device registration records, and Japanese Consumer Affairs Agency functional food labeling standards, complemented by interviews with plant managers at Guangdong contract manufacturing facilities, procurement leads at South Korean gym chains, regulatory affairs specialists navigating multi-jurisdiction certification, and biomedical engineers specifying electrolysis systems for rehabilitation centers. Secondary validation drew from customs and trade data tracking electrode material flows, PSE and KC certification registries, and CE marking documentation for EU-bound equipment. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level outputs across product type, technology, application, and end-user dimensions were generated through structured modeling of replacement cycle dynamics, certification pathway timelines, and channel penetration rates. CAGRs were derived from logistic growth curve fitting anchored to observed adoption inflections in Japanese wellness retail and South Korean apartment renovation markets. Industry-specific forecast inputs included platinum group metal price volatility indices, perfluorinated ionomer supply tightness indicators, and smart home water system integration adoption curves in Seoul metropolitan renovations.
Inputs from primary interviews and regulatory filing databases were available through the study window; gaps in real-time channel inventory data and unreported private-label contract values introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding certification timeline stability, electrode material supply continuity, and health-claim regulatory harmonization velocity that could shift materially with policy changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Iced Tea Market