
 United States Energy Drink Market | 2026-2036
United States Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
United States Energy Drink Market Outlook
Asset-light contract manufacturing and co-packing arrangements is reconfiguring competitive entry barriers, allowing niche brands to scale without capital-intensive production facilities. Celsius Holdings Inc leverages direct-to-consumer subscription models to sustain recurring revenue streams outside traditional retail. Monster Beverage Corporation anchors its position through extensive fountain and cold-vault distribution partnerships with convenience store chains. Red Bull GmbH differentiates through event-sponsorship ecosystems and lifestyle media properties that extend brand equity beyond the beverage itself.
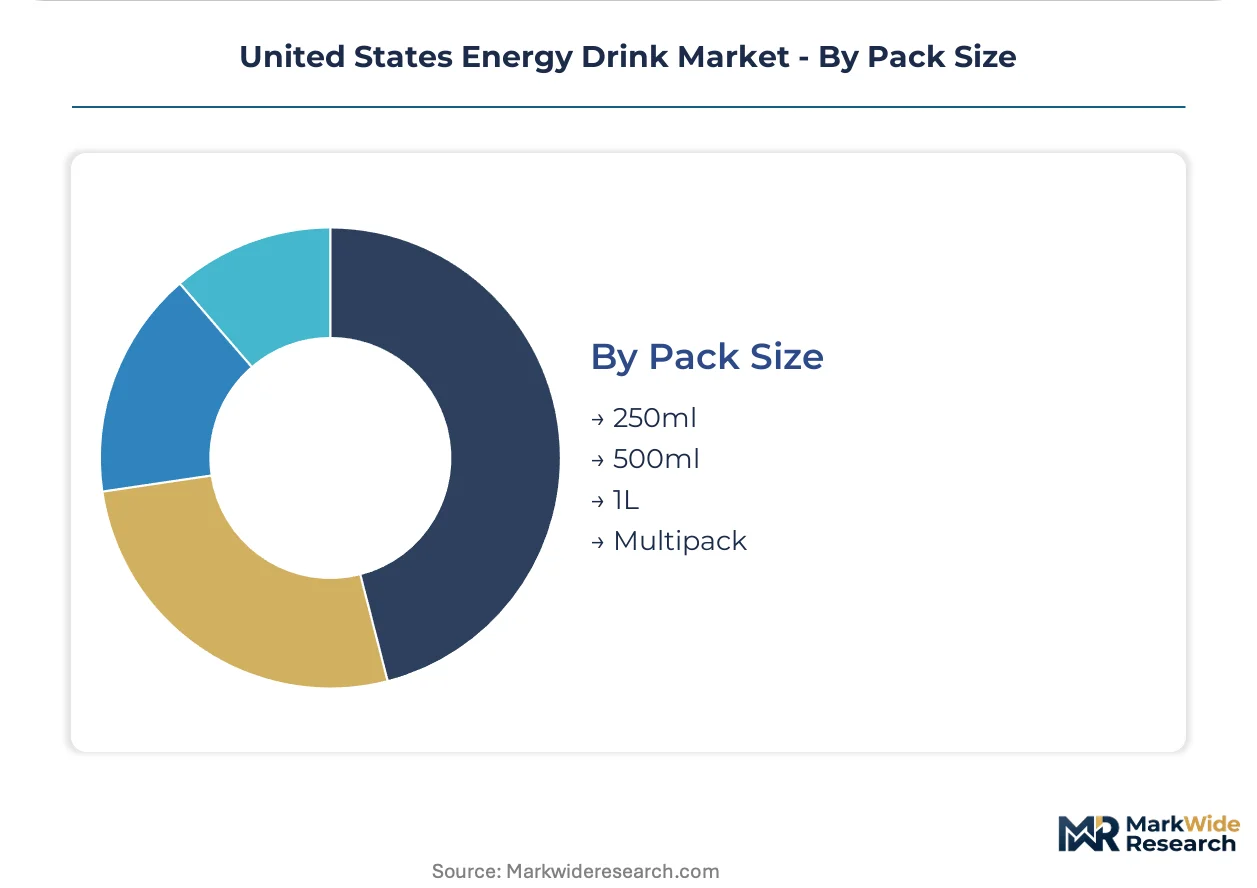
Energy drinks are non-alcoholic beverages formulated with caffeine, taurine, B-vitamins, and other stimulant compounds, typically containing 80-300mg of caffeine per serving, designed to enhance mental alertness and physical performance. Carbonated variants still occupy the largest revenue share, though organic and functional formulations are capturing margin-rich shelf space as consumers scrutinize ingredient transparency. The 500ml pack size dominates convenience channel velocity, while multipack configurations through online retail are accelerating household penetration among remote professionals.
The FDA oversees caffeine content limits and additive safety reviews, while state legislatures in California and New York have introduced bills targeting sugar content and youth marketing restrictions. These regulatory pressures are forcing reformulation toward natural caffeine sources and zero-sugar profiles ahead of anticipated federal preemption debates. Stakeholders must monitor pending FTC advertising guideline updates and state-level excise tax proposals that could reshape pricing architecture and channel profitability across the forecast horizon.
Market Dynamics
FDA caffeine labeling mandates and state-level sugar tax proposals are forcing simultaneous reformulation across caffeine sourcing and sweetener architectures, compressing product development cycles while expanding R&D overhead for domestic manufacturers.
Growth Catalysts
- Fitness Infrastructure Density:Urban centers with concentrated gym networks and boutique studio ecosystems are generating disproportionate per-capita consumption velocity among performance-oriented demographics.
- IRA Clean Energy Provisions:Domestic manufacturing tax credits for sustainable packaging materials are lowering barrier costs for biodegradable can and bottle adoption.
- Remote Professional Households:Multipack subscription configurations through direct-to-consumer channels are penetrating home-office environments previously underserved by single-serve convenience retail.
Market Restraints
- Natural Caffeine Input Volatility:Green coffee bean and yerba mate extract supplies face price instability tied to Brazilian and Argentinian harvest cycles.
- California Supply Concentration:Co-packing and contract manufacturing capacity clusters in Southern California create geographic vulnerability to port congestion and state regulatory velocity.
- FTC Advertising Friction:Pending guideline updates on performance claims are extending legal review timelines and constraining marketing agility for functional positioning.
Strategic Opportunities
- Zero-Sugar Regulatory Tailwind:Anticipated federal preemption debates on state sugar taxes are incentivizing early mover advantage in allulose and monk fruit formulations.
- Functional Beverage Convergence:Nootropic and adaptogenic ingredient stacks are hybridizing with traditional energy bases to capture wellness-adjacent consumers.
- Cold-Vault Channel Expansion:Fountain and dispenser partnerships with regional convenience chains remain underpenetrated relative to national retail concentration.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise bridging natural caffeine stability with clean-label taste profiles commands premium compensation and extended recruitment cycles.
- Co-Packer Integration Complexity:Asset-light brands scaling through contract manufacturing face quality control fragmentation across multiple production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Energy Drink Market |
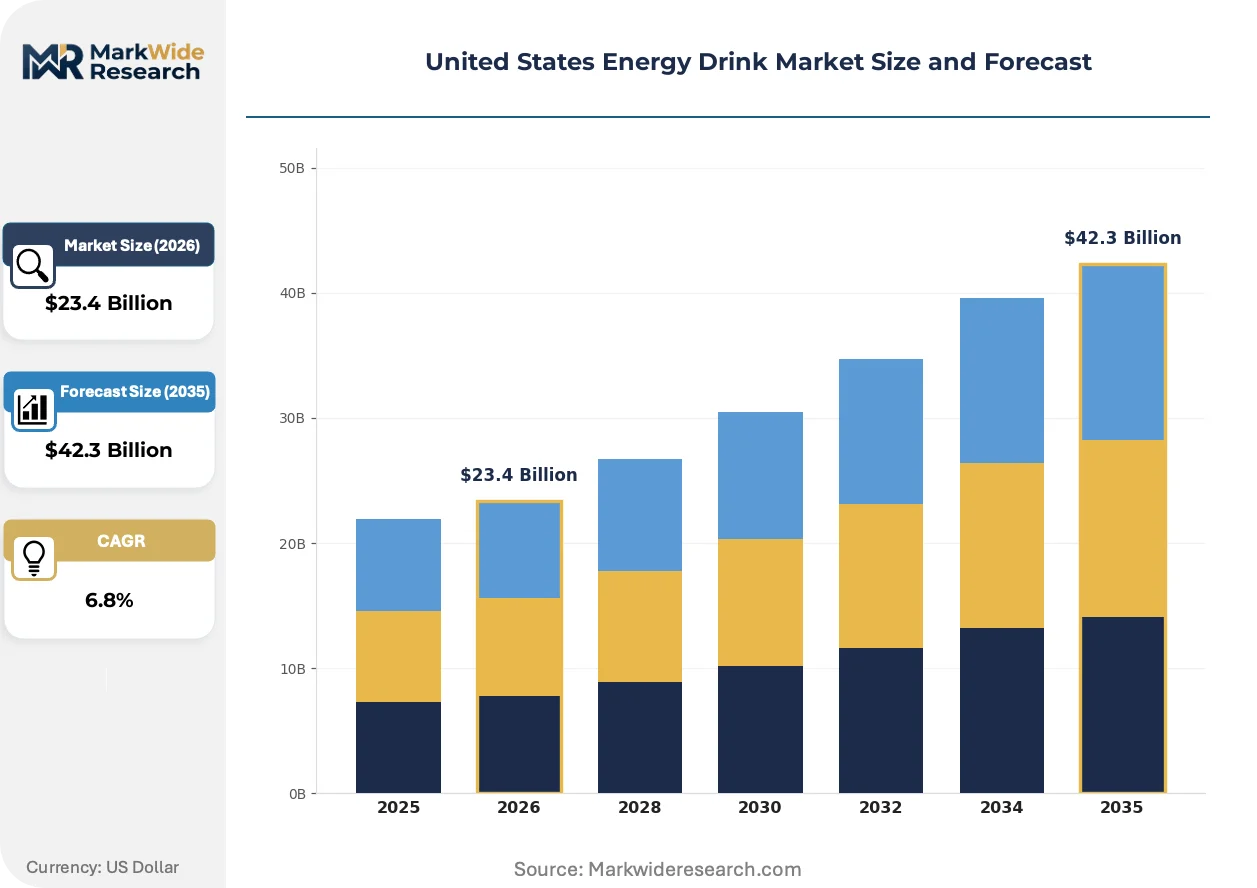
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $42.3 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Functional End User: Athletes, Students, Professionals, Fitness Enthusiasts Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Clubs Pack Size: 250ml, 500ml, 1L, Multipack |
| Companies Covered | The Coca-Cola Company, Celsius Holdings Inc, Red Bull GmbH, Congo Brands, Keurig Dr Pepper, Monster Beverage Corporation, National Beverage Corp, Living Essentials, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Energy Drink Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel transformation as natural ingredient transparency demands collide with performance efficacy expectations and channel diversification accelerates.
Microencapsulation technology for caffeine and B-vitamin stabilization is hybridizing with cold-brew extraction methods to extend shelf stability without synthetic preservatives. Premium positioning brands are adopting these dual-process systems to maintain clean-label credentials while preserving functional potency. The structural consequence is compressing margin for legacy thermal-processing facilities unable to retrofit.
State legislatures in New York and California have introduced parallel bills targeting sugar content thresholds and youth-directed marketing restrictions. These measures are forcing preemptive reformulation toward zero-calorie profiles and age-gating digital advertising protocols. Brands with existing sugar-free portfolios are capturing shelf space from slower-reacting competitors in these jurisdictions.
Subscription-based replenishment models are displacing impulse-driven convenience store purchasing among remote professionals and hybrid workers. Direct-to-consumer platforms with predictive reorder algorithms are capturing lifetime value previously fragmented across retail channels. Texas and Florida metropolitan areas exhibit the highest subscription adoption velocity, correlating with young professional household density and fitness club membership rates.
United States Energy Drink Market Segmentation
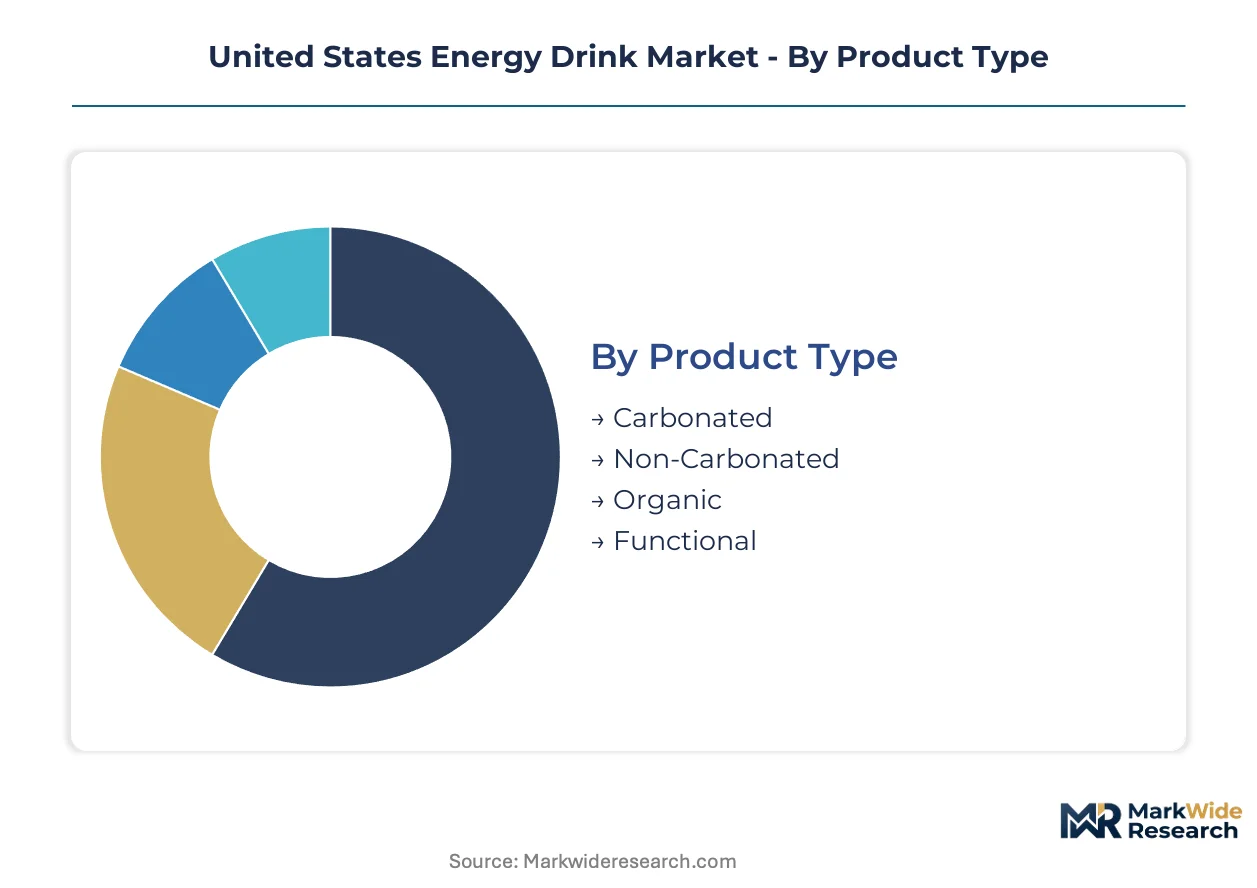
Energy drink segmentation reflects divergent consumption rituals across fitness, work, and social contexts. Each dimension—product chemistry, user identity, purchase location, and serving format—commands distinct formulation and channel strategies.
Product Type:
Cost tier differentiation separates mass-market refreshment from premium functional positioning, with ingredient transparency driving margin architecture.
- Carbonated:Traditional effervescent bases using synthetic caffeine and high-fructose corn syrup dominate fountain and cold-vault placements. Demand concentrates in Texas convenience corridors where price-sensitive volume purchasing sustains household penetration.
- Non-Carbonated:Still formulations using cold-brew coffee and tea extracts appeal to consumers avoiding carbonation bloat. California health clubs and boutique studios drive disproportionate per-capita velocity as pre-workout hydration alternatives.
- Organic:USDA-certified ingredient chains with natural caffeine from green coffee and yerba mate command shelf space in Whole Foods and Sprouts networks.
- Functional:Nootropic and adaptogenic stacks targeting cognitive performance rotate up fastest in direct-to-consumer subscription channels.
Carbonated holds installed capacity. Functional is rotating up the share rankings.
End User:
Application context dictates caffeine dosage, ingredient complexity, and purchase frequency across performance, academic, and professional use cases.
- Fitness Enthusiasts:Pre-workout formulations with 200-300mg caffeine, beta-alanine, and citrulline malate dominate gym-adjacent retail. Southern California and Miami metropolitan clusters generate highest per-gross-square-foot velocity through Equinox and LA Fitness partnerships.
- Professionals:Sustained-release caffeine with L-theanine targets remote workers seeking jitter-free focus. Texas and Florida subscription adoption correlates with young professional household density and hybrid work penetration.
- Athletes:NSF-certified competition-safe formulations with banned-substance testing command collegiate and amateur sports procurement.
- Students:Price-optimized 250ml cans with sugar-forward profiles concentrate in campus convenience stores and vending networks.
Fitness Enthusiasts holds installed capacity. Professionals is rotating up the share rankings.
Distribution Channel:
Volume concentration varies dramatically by purchase occasion—impulse, planned replenishment, or embedded consumption—shaping margin capture and brand control.
- Convenience Stores:Single-serve cold-vault and fountain placements drive immediate-consumption velocity. 7-Eleven and Circle K partnerships in California and Texas generate disproportionate revenue per linear foot through 24-hour urban access.
- Online Retail:Predictive-replenishment algorithms and multipack configurations capture lifetime value from remote professionals. Amazon and brand-direct platforms accelerate household penetration outside traditional retail footprints.
- Supermarkets:Mass-merchandise shelf sets with promotional pricing sustain family-pack purchasing in suburban markets.
- Health Clubs:Exclusive cooler placements and post-workout grab-and-go positioning command premium pricing in boutique fitness ecosystems.
Convenience Stores holds installed capacity. Online Retail is rotating up the share rankings.
Pack Size:
Customer type and consumption setting determine format economics, from on-the-go portability to household inventory management.
- 500ml:The dominant convenience channel format balances portability with perceived value. Urban centers with dense fitness infrastructure in California and Texas drive highest velocity through gas station and gym cooler placements.
- Multipack:4-pack and 12-pack configurations through subscription and e-commerce penetrate home-office environments. Remote professional households in Austin and Miami exhibit fastest adoption curves for predictive replenishment models.
- 250ml:Compact trial-size and price-entry formats concentrate in campus and vending applications.
- 1L:Value-oriented bulk formats target price-sensitive household replenishment in warehouse club channels.
500ml holds installed capacity. Multipack is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States energy drink market exhibits a net import position in specialty ingredients while maintaining domestic formulation and packaging dominance. Trade flows concentrate through West Coast ports for natural caffeine extracts and East Coast distribution hubs for finished goods.
California
Fitness culture penetration and health-conscious consumer density drive premium functional beverage demand across Los Angeles and San Francisco metropolitan clusters. State legislators have introduced sugar content threshold bills and youth marketing restrictions that accelerate zero-sugar portfolio transitions. Southern California co-packing corridors from San Diego to Orange County concentrate contract manufacturing capacity for emerging brands scaling through asset-light models.
Texas
Young professional household formation and hybrid work adoption generate the nation's highest subscription replenishment velocity through Austin and Dallas-Fort Worth corridors. The state maintains permissive regulatory posture on caffeine labeling relative to coastal jurisdictions, attracting formulation testing operations. Houston's petrochemical infrastructure supplies beverage-grade CO2 and packaging resins that feed regional production networks.
New York
Finance and media sector professionals sustain demand for sustained-release caffeine formulations with L-theanine in Manhattan and Brooklyn office districts. State assembly bills targeting sugar taxation and age-gated digital advertising create compliance complexity for national brands. Upstate New York warehouse distribution clusters serve as Northeast replenishment nodes for direct-to-consumer platforms.
Florida
Miami's boutique fitness ecosystem and Latin American consumer demographics drive disproportionate per-capita consumption of non-carbonated and tropical-flavored variants. The state Department of Agriculture and Consumer Services enforces fluid milk and juice standards that intersect with hybrid energy beverage classifications. Tampa and Orlando metropolitan areas exhibit fastest-growing convenience channel velocity through 24-hour retail access patterns.
Illinois
Chicago's central logistics position anchors Midwest distribution for both mass-market and premium energy beverage portfolios. State-level excise tax proposals on sugar-sweetened beverages remain under legislative consideration, creating planning uncertainty for regional pricing architectures. The city's food and beverage innovation corridor hosts pilot facilities for microencapsulation and cold-brew extraction technology development.
United States Energy Drink Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and co-packing services. The United States energy drink market structures around three distinct competitive tiers: multinational beverage conglomerates with diversified refreshment portfolios, pure-play energy specialists with focused brand equity, and emerging challengers scaling through contract manufacturing partnerships. Strategic moves concentrate on zero-sugar reformulation acceleration, direct-to-consumer channel capture, and exclusive distribution agreements with convenience store networks.
Within the multinational tier, The Coca-Cola Company and PepsiCo exemplify platform breadth that spans energy, sports, and hydration categories. Celsius Holdings Inc and Monster Beverage Corporation occupy specialist positions that concentrate resources on performance-oriented positioning and fitness channel penetration. Red Bull GmbH represents lifestyle-media integration that extends beverage economics into event sponsorship and content properties.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Celsius Holdings Inc |
| Red Bull GmbH |
| Congo Brands |
| Keurig Dr Pepper |
| Monster Beverage Corporation |
| National Beverage Corp |
| Living Essentials |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Southern California co-packing corridors is compressing contract manufacturing margins while simultaneously elevating pricing power for vertically integrated incumbents with captive production assets. This utilization asymmetry is reshaping supplier negotiations and forcing asset-light brands toward longer-term offtake commitments to secure capacity.
Pricing Analysis
Subscription-based buyers anchor the pricing architecture through recurring revenue predictability that commands volume discounts unavailable to impulse purchasers. Three-tier pricing structure across premium functional, standard carbonated, and economy private-label levels stratifies by ingredient transparency and caffeine sourcing certification. Cost compression in the standard tier is intensifying because of green coffee bean price volatility tied to Brazilian harvest cycles. Campus vending networks exhibit highest price sensitivity, while direct-to-consumer fitness subscribers demonstrate lowest elasticity due to habit formation and convenience premiums.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina for yerba mate extracts dominates supply chain risk planning for natural caffeine formulations. Raw material sourcing draws from Brazilian green coffee regions, Argentinian yerba mate plantations, and domestic cold-brew coffee processing facilities in California and Texas. Single-source vulnerability concentrates in Southern California co-packing clusters where port congestion and state regulatory velocity create simultaneous disruption vectors. Distribution runs through West Coast ingredient import hubs, regional contract manufacturing nodes, and direct-to-consumer fulfillment centers anchored in Texas and Florida metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States energy drink market rewards formulation chemistry expertise and cold-chain logistics mastery that remain scarce relative to brand proliferation velocity. This capability gap separates sustainable competitors from margin-compressed private-label imitators.
For Market Incumbents: Harden supply chain resilience through backward integration into natural caffeine extraction or captive co-packing capacity in Texas regulatory corridors. Accelerate zero-sugar portfolio transitions ahead of anticipated federal preemption debates to capture shelf space from reformulation-lagged competitors in California and New York jurisdictions. For New Entrants and Emerging Players: Pursue white-space penetration in functional nootropic-adaptogenic hybrid formulations through direct-to-consumer subscription channels serving remote professional households in Austin and Miami metropolitan clusters. Exploit flavor chemist talent scarcity by partnering with university food science programs for pipeline access rather than competing for premium-compensation experienced hires. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light contract manufacturing models that scale without production facility ownership. Target acquisition archetypes include emerging brands with proven subscription retention metrics and exclusive health club distribution partnerships. Monitor FDA caffeine labeling mandate implementation velocity as inflection indicator for reformulation cost acceleration and competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Sugar Portfolio Acceleration | Preemptive reformulation captures shelf space from slower competitors in California and New York regulatory jurisdictions. |
| Direct-to-Consumer Subscription Launch | Predictive replenishment algorithms secure lifetime value from remote professional households in Texas and Florida corridors. |
| Backward Integration into Natural Caffeine | Captive supply of green coffee and yerba mate extracts insulates margins from Brazilian harvest volatility. |
| Health Club Distribution Partnership | Exclusive cooler placements in Equinox and LA Fitness networks command premium pricing in Southern California clusters. |
| Functional Beverage Convergence | Nootropic and adaptogenic ingredient stacks hybridize with energy bases to capture wellness-adjacent consumer segments. |
Study Parameters
A spread of perspectives from brand managers at energy drink manufacturers, category buyers at convenience store chains, supply planners at co-packing facilities, and formulation chemists at ingredient suppliers converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from FDA regulatory filings, Nielsen retail audit data, SEC 10-K disclosures, and customs import records for natural caffeine extracts. Bottom-up segment sizing and top-down market triangulation cross-checked projections against operating metrics reported across the value chain.
Demand-supply balance modeling anchored the forecast framework, with consumption velocity projections tested against co-packing capacity utilization and ingredient import flows across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-user application context, distribution channel format, and pack size configuration. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift dynamics. Industry-specific inputs incorporated fitness club membership density correlations and subscription replenishment algorithm adoption curves.
Sensitivities concentrate around FDA caffeine labeling mandate timing, state-level sugar tax preemption outcomes, and Brazilian green coffee harvest variability. Forecasts reflect documented assumptions subject to revision from regulatory, climatic, or competitive dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market