
 Surface Water Sports Equipment Market | 2026-2036
Surface Water Sports Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Water Sports Equipment Market Outlook
Asset-light leasing models for jet ski and paddleboard fleets is rewriting competitive entry barriers across the surface water sports equipment landscape. Johnson Outdoors Inc. leverages its vertically integrated manufacturing footprint to control component costs across kayak and canoe lines. Decathlon SA anchors its position through direct retail density in European and Asian waterfront markets. O'Brien Watersports specializes in towable and board sport categories where product refresh cycles compress replacement timelines.
Surface water sports equipment encompasses manually propelled and motorized vessels designed for open-water recreation, competition, and instruction, typically constructed from thermoformed polyethylene, vacuum-infused fiberglass, or carbon fiber composite laminates to achieve specific buoyancy-to-weight ratios and impact resistance thresholds. Kayaks and paddleboards command the largest installed base due to lower storage and transport barriers, while jet skis generate disproportionate revenue per unit through higher price points and accessory attachment rates. Carbon fiber construction differentiates premium racing and expedition segments where stiffness-to-weight performance justifies material cost premiums over rotomolded plastic alternatives.
EPA emissions standards for personal watercraft engines and REACH compliance for marine coatings constrain product design choices across North American and European supply chains. The EU Green Deal's extended producer responsibility frameworks are pressuring manufacturers to establish closed-loop recycling for fiberglass and polymer hulls. China's GB standards for small vessel safety and Australia's mandatory personal flotation device regulations add compliance layers for exporters targeting Asia-Pacific markets. Stakeholders must track evolving material certification requirements as sustainability mandates migrate from voluntary eco-labeling toward enforceable product passport obligations.
Market Dynamics
The EU Green Deal's extended producer responsibility frameworks are forcing manufacturers to abandon linear hull production models. Recycled polymer construction mandates are rewriting material sourcing strategies across the supply base.
Growth Catalysts
- REACH compliance migration:European coating reformulations are accelerating adoption of bio-based marine finishes among hull manufacturers serving EU markets.
- Tour operator fleet expansion:Experiential travel operators in coastal tourism corridors are scaling jet ski and paddleboard inventories to capture premium activity bookings.
- Rotomolding process refinements:Thermoformed polyethylene production advances are reducing kayak and canoe unit costs while improving impact resistance thresholds.
Market Restraints
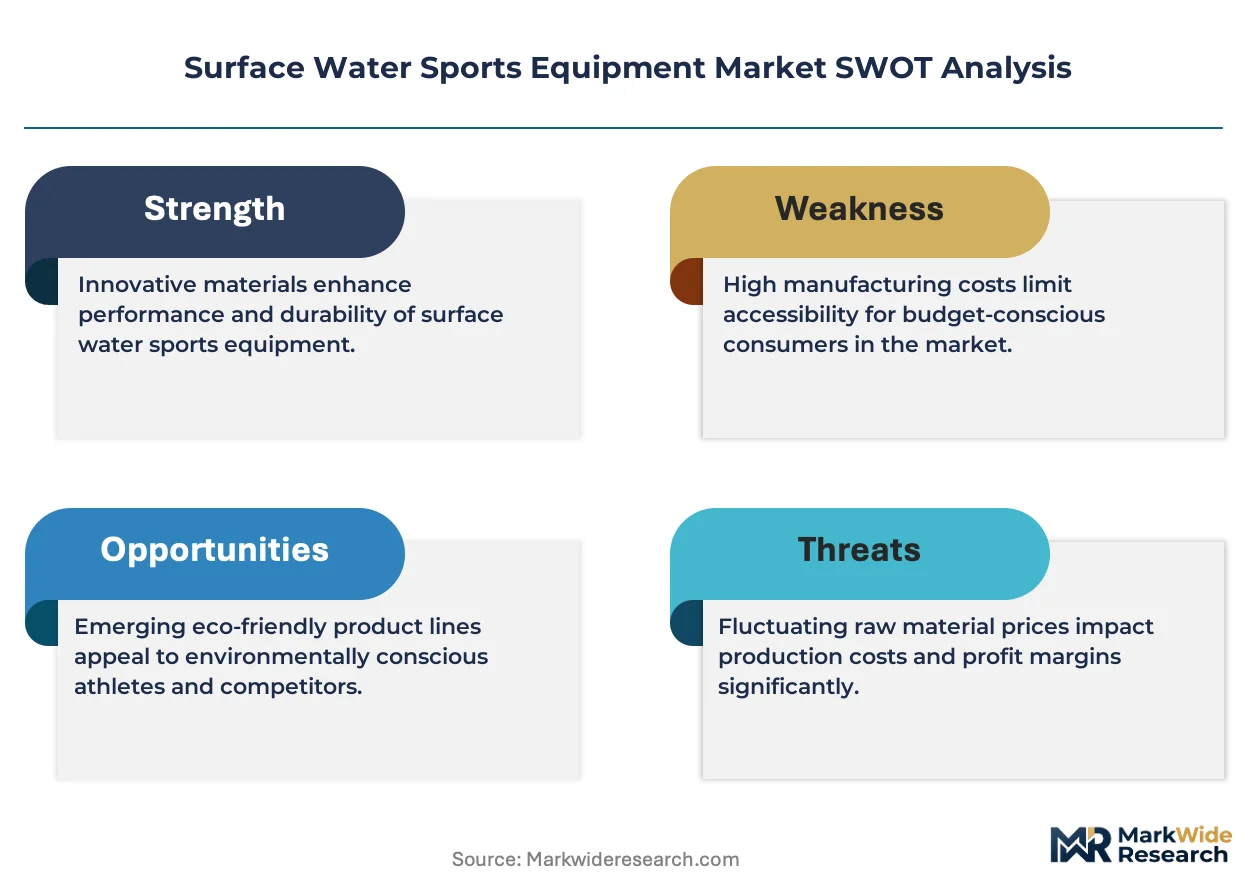
- Petrochemical feedstock volatility:Polyethylene and fiberglass resin input costs fluctuate with crude oil pricing, compressing margin predictability for hull fabricators.
- Carbon fiber supply concentration:Premium racing and expedition segment manufacturers depend on concentrated Asian precursor suppliers, creating single-source vulnerability.
- EPA emissions certification timelines:Personal watercraft engine approval processes extend product development cycles by 18-24 months for North American market entry.
Strategic Opportunities
- Closed-loop hull recycling infrastructure:EU Green Deal mandates create first-mover advantage for manufacturers establishing polymer and fiberglass reclamation networks.
- Asset-light leasing channels:Waterfront hospitality operators in Thailand and Brazil are adopting subscription-based fleet models, reducing customer capex barriers.
- Dual-carbon goal alignment:China's MEE standards for small vessel manufacturing reward low-emission production with preferential licensing treatment.
Industry Challenges
- Composite repair technician scarcity:Vacuum-infused fiberglass and carbon fiber hull maintenance requires specialized labor pools that remain underdeveloped outside major manufacturing hubs.
- Multi-jurisdiction certification overlap:Australia's TGA-mandated personal flotation device standards, China's GB small vessel safety codes, and EPA emissions requirements create redundant testing burdens for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Water Sports Equipment Market |
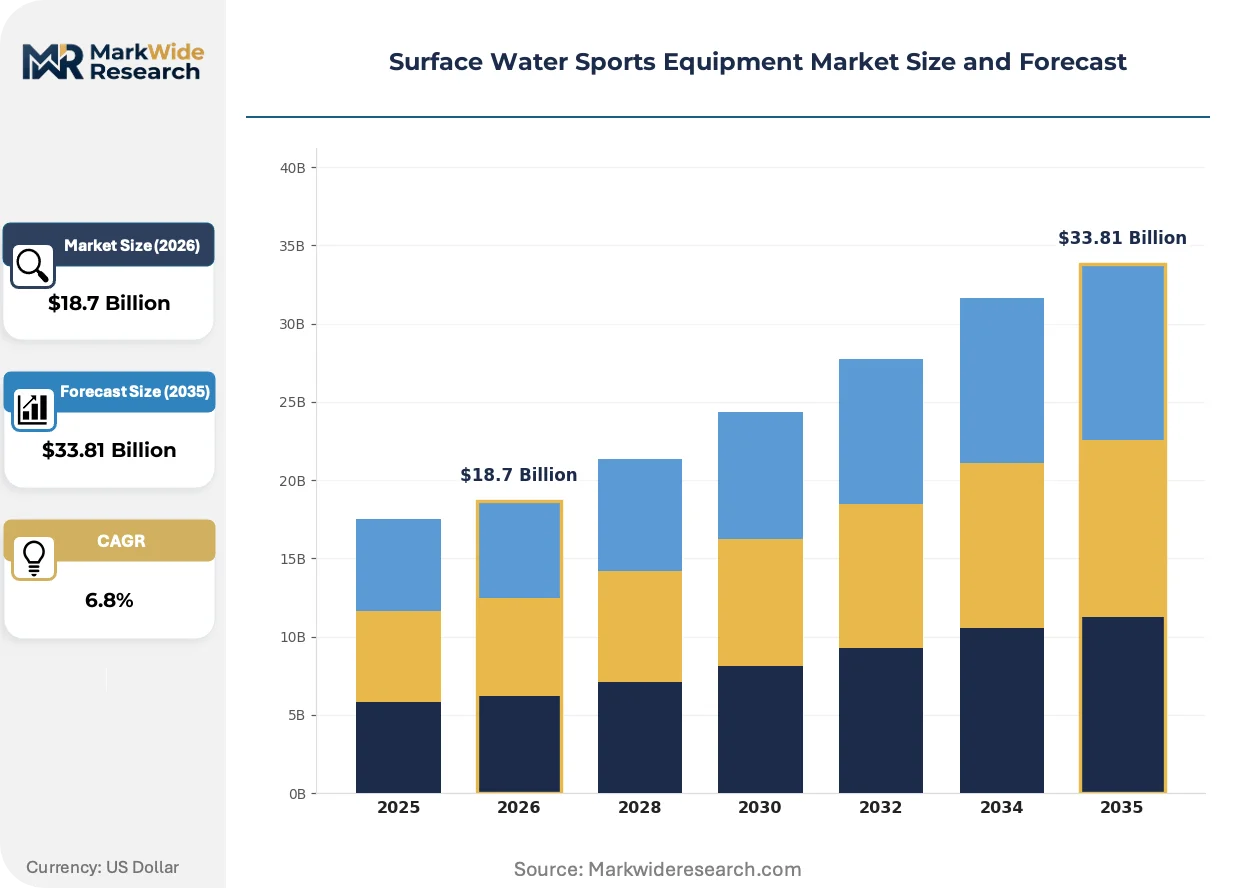
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kayaks, Paddleboards, Canoes, Jet Skis End User: Recreational Users, Professional Athletes, Schools, Tour Operators Distribution Channel: Online Retail, Sporting Goods Stores, Direct Sales, Specialty Shops Material: Fiberglass, Plastic, Aluminum, Carbon Fiber |
| Companies Covered | Johnson Outdoors Inc., Decathlon SA, O’Brien Watersports, Belassi GmbH, Body Glove International, Aqua Lung International, Cressi Sub S.p.A., Kent Water Sports LLC, Jobe Sports International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Water Sports Equipment Market Strategic Shifts
Material science breakthroughs and regulatory pressure are converging to transform hull construction methods. Procurement patterns among fleet operators are simultaneously reshaping distribution architectures.
Recycled ocean plastic feedstock is migrating from niche eco-labeling to mainstream hull production. Kayak and paddleboard manufacturers serving European markets are adopting post-consumer polymer blends at scale. This material transition is compressing virgin resin demand while commanding 12-15% price premiums in sustainability-positioned retail channels.
REACH substance restrictions on marine coatings are forcing reformulation of antifouling and UV-resistant finishes. Hull manufacturers must certify new chemical compositions through ECHA notification procedures. The racing and expedition segment faces the steepest compliance burden, as high-performance coatings historically relied on now-restricted biocidal compounds.
Outcome-based fleet management contracts are displacing outright equipment purchases among commercial operators. Waterfront hotels and tour aggregators in Australia and Thailand now demand performance guarantees covering maintenance, replacement, and seasonal storage. This service unbundling concentrates purchasing power with leasing intermediaries and compresses manufacturer-direct sales margins.
Surface Water Sports Equipment Market Segmentation
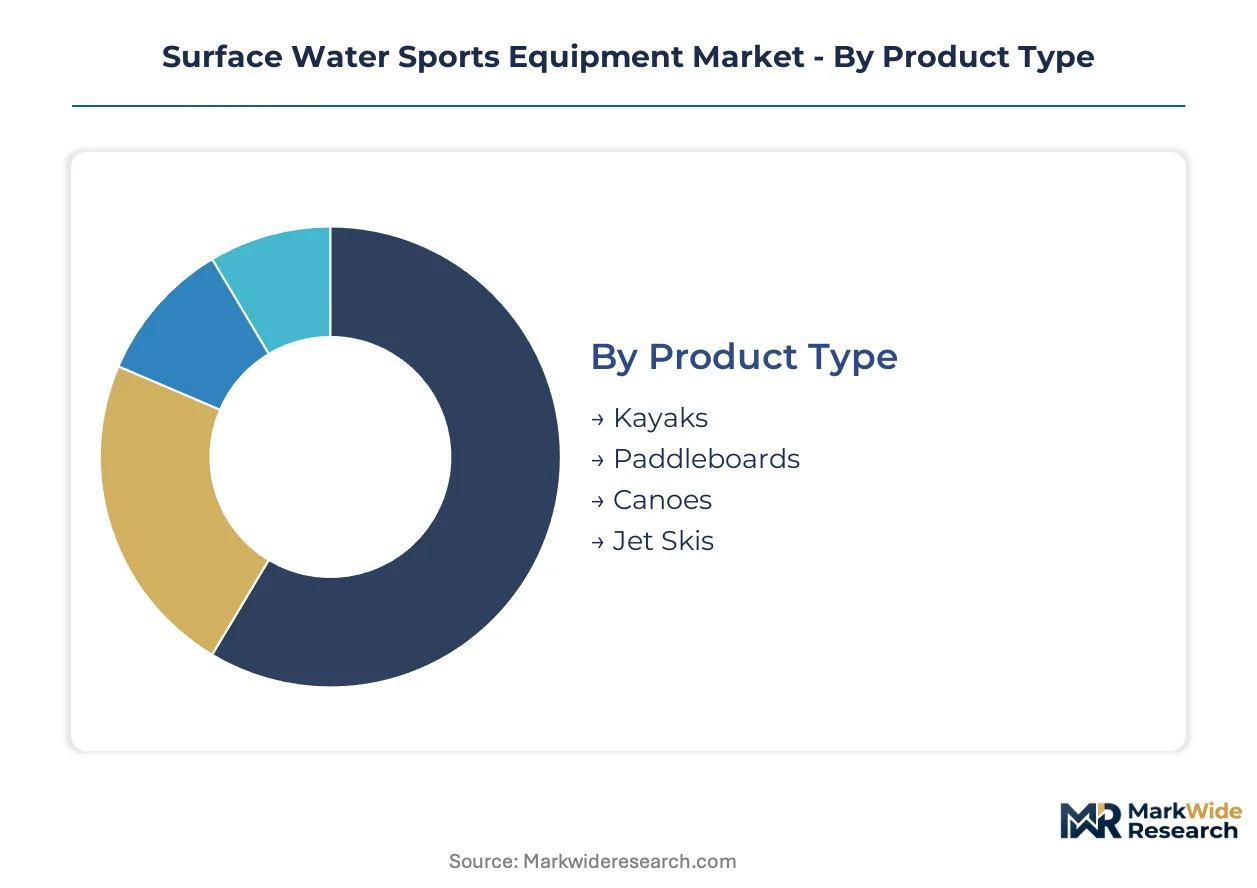
Segmentation in surface water sports equipment reveals divergent replacement economics across product categories. Material composition and end-use intensity create distinct margin profiles that manufacturers must navigate simultaneously.
Product Type:
Kayaks and paddleboards turn inventory every 4-6 years in recreational channels, while jet skis compress replacement cycles to 2-3 years under commercial fleet stress.
- Kayaks:Rotomolded polyethylene hulls dominate recreational sales due to impact resistance and sub-$1,000 entry pricing. Demand concentrates in Australian and Brazilian coastal tourism corridors where rental fleets prioritize durability over weight.
- Paddleboards:Inflatable PVC construction captures 60% of unit volume for transport-constrained urban buyers. Thailand's waterfront hospitality operators are scaling inflatable fleet purchases to reduce storage footprints.
- Canoes:Thermoformed tandem designs serve North American lake recreation and outdoor education programs.
- Jet Skis:Personal watercraft engines face EPA emissions certification timelines that extend product development cycles by 18-24 months.
Kayaks dominate installed base. Jet skis are where expansion concentrates.
End User:
Professional athletes and tour operators drive premium material adoption, while recreational users and schools anchor volume tiers.
- Recreational Users:Weekend paddlers in Australia and Brazil prioritize storage convenience and sub-$800 price points over performance specifications.
- Professional Athletes:Carbon fiber construction commands 12-15% price premiums for stiffness-to-weight ratios in racing applications. REACH compliance for marine coatings adds reformulation costs that concentrate in this segment.
- Schools:Institutional procurement favors rotomolded plastic durability for instructional fleet longevity.
- Tour Operators:Experiential travel operators in Thailand are adopting asset-light leasing models that shift capital requirements to fleet intermediaries.
Recreational users anchor volume. Tour operators are climbing the fastest.
Distribution Channel:
Direct sales capture margin in premium carbon fiber segments, while online retail and sporting goods stores compete on polyethylene commodity hulls.
- Online Retail:Inflatable paddleboards and accessories migrate fastest to digital channels due to shipping logistics advantages.
- Sporting Goods Stores:Decathlon SA's waterfront retail density in European and Asian markets moves volume kayak and canoe inventory.
- Direct Sales:Custom carbon fiber racing hulls bypass intermediaries to preserve margin on low-volume, high-specification orders.
- Specialty Shops:Regional dealers in Australian coastal clusters provide repair services that online channels cannot replicate.
Sporting goods stores dominate installed base. Online retail is where expansion concentrates.
Material:
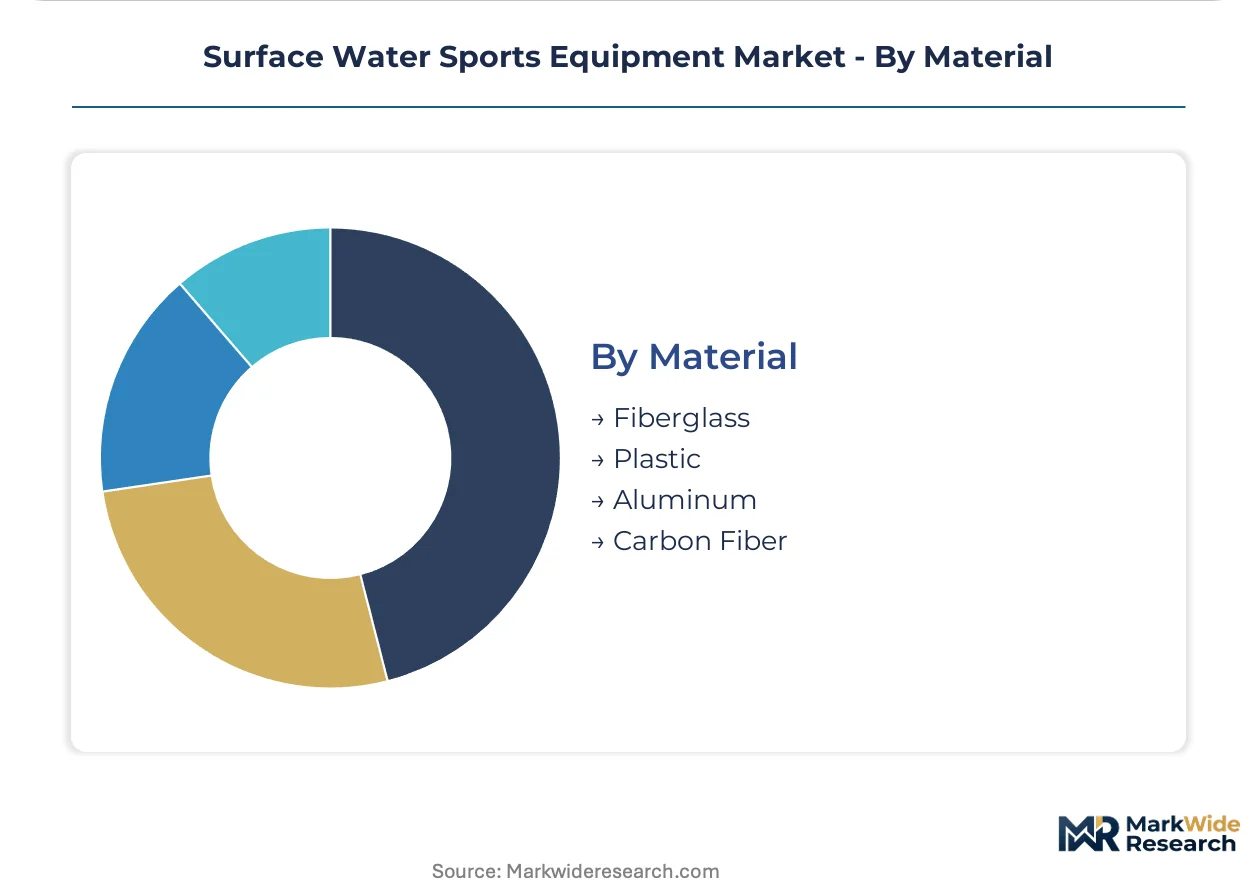
Fiberglass and carbon fiber concentrate in premium racing and expedition segments, while plastic and aluminum serve price-sensitive volume tiers.
- Fiberglass:Vacuum-infused construction balances weight and cost for mid-tier touring kayaks. EU Green Deal extended producer responsibility frameworks are pressuring manufacturers to establish closed-loop recycling infrastructure.
- Plastic:Rotomolded polyethylene achieves lowest unit cost for recreational kayak and canoe production. Petrochemical feedstock volatility compresses margin predictability for hull fabricators.
- Aluminum:Small craft and fishing vessel applications favor corrosion resistance in saltwater environments.
- Carbon Fiber:Asian precursor supply concentration creates single-source vulnerability for premium racing segment manufacturers.
Plastic dominates installed base. Carbon fiber is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal distinct regional specialization patterns across surface water sports equipment. Manufacturing gravity concentrates in coastal economies with established polymer processing and composite fabrication infrastructure, while demand clusters in tourism-dependent waterfront markets.
United States
Recreational boating culture and lake-based outdoor education programs sustain polyethylene kayak demand. EPA emissions certification timelines for personal watercraft engines extend product development cycles by 18-24 months, favoring established manufacturers with regulatory compliance infrastructure. Florida's coastal tourism corridor anchors jet ski fleet procurement for experiential travel operators.
Germany
REACH compliance migration drives bio-based marine coating adoption among hull manufacturers serving EU markets. The EU Green Deal's extended producer responsibility frameworks pressure fabricators to establish closed-loop recycling for fiberglass and polymer hulls. Bavaria's outdoor equipment manufacturing cluster specializes in vacuum-infused fiberglass touring kayaks for premium segments.
China
Dual-carbon goal alignment through MEE standards rewards low-emission production with preferential licensing treatment. GB standards for small vessel safety add compliance layers for exporters targeting domestic and Asia-Pacific markets. The Yangtze River Delta concentrates carbon fiber precursor supply for premium racing segment manufacturers.
Australia
TGA-mandated personal flotation device standards and coastal tourism operator fleet expansion drive paddleboard and kayak procurement. Sydney and Gold Coast waterfront hospitality clusters adopt asset-light leasing models that shift capital requirements to fleet intermediaries. Queensland's reef tourism operators scale jet ski inventories to capture premium activity bookings.
Brazil
Rio de Janeiro and São Paulo coastal corridors concentrate experiential travel operator demand for rotomolded polyethylene rental fleets. Petrochemical feedstock proximity supports domestic hull fabrication cost structures. Northeastern beach tourism destinations in Bahia and Pernambuco drive inflatable paddleboard adoption for storage-constrained waterfront operators.
Surface Water Sports Equipment Market Competitive Environment
On the supply side, the industry is structured around three distinct tiers: vertically integrated outdoor conglomerates with captive manufacturing footprints, specialized watersports fabricators focused on narrow product categories, and mass-market sporting goods retailers with direct sourcing relationships. Strategic archetypes include durability-focused rental fleet suppliers, stiffness-to-weight premium racing specialists, and convenience-optimized inflatable product innovators. Competitive moves concentrate on backward integration into polymer compounding and geographic expansion through waterfront retail density.
Among European-based fabricators, Belassi GmbH exemplifies the specialized personal watercraft engineering archetype, while Cressi Sub S.p.A. occupies a position within the diving and watersports crossover tier. Johnson Outdoors Inc. represents the vertically integrated outdoor recreation conglomerate model with in-house manufacturing control across multiple hull categories. These three anchors illustrate how competitive positioning diverges between component-cost control, category specialization, and portfolio breadth strategies.
| Leading Market Players |
|---|
| Johnson Outdoors Inc. |
| Decathlon SA |
| O'Brien Watersports |
| Belassi GmbH |
| Body Glove International |
| Aqua Lung International |
| Cressi Sub S.p.A. |
| Kent Water Sports LLC |
| Jobe Sports International B.V. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta container freight corridors feed directly into hull fabrication cost structures across Chinese manufacturing clusters, compressing polyethylene unit economics for Australian and Brazilian fleet buyers while amplifying price spreads between rotomolded commodity tiers and carbon fiber premium segments.
Pricing Analysis
Tour operators anchor a three-tier pricing structure across premium, standard, and economy levels in surface water sports equipment procurement. Price differentiation rests on certification grade alignment with EPA emissions standards and REACH marine coating compliance, alongside volume scale commitments from waterfront hospitality aggregators. Pricing pressure stems from petrochemical feedstock volatility eroding margin predictability for hull fabricators serving rental fleet channels. Recreational users in Australian coastal corridors exhibit highest price sensitivity, while professional athletes in racing segments absorb 12-15% premiums for stiffness-to-weight carbon fiber performance.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta carbon fiber precursor suppliers are reshaping working capital requirements for premium racing hull manufacturers. Geographic supply concentration centers on China for composite precursors, Germany for vacuum-infused fiberglass touring kayaks, and Brazil for rotomolded polyethylene rental fleets. Raw material dependencies draw from petrochemical polyethylene resins, Asian carbon fiber feedstock, and bio-based marine coating reformulations. Single-source vulnerability in Asian precursor supply creates structural risk for expedition segment fabricators. Distribution runs through sporting goods retail density in European waterfront markets and direct sales channels for custom racing specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite repair technician scarcity constrains aftermarket service scalability across Australian and Thai coastal tourism corridors, creating a capability bottleneck that separates fleet operators able to self-maintain from those tethered to manufacturer service networks.
For Market Incumbents: Harden closed-loop hull recycling infrastructure ahead of EU Green Deal extended producer responsibility enforcement, securing first-mover positioning in polymer and fiberglass reclamation networks. Deepen backward integration into recycled ocean plastic feedstock compounding to insulate margin structures from virgin resin volatility. Defend against asset-light leasing intermediaries by embedding performance guarantees into manufacturer-direct fleet contracts. For New Entrants and Emerging Players: Pursue inflatable paddleboard fleet procurement channels in Thailand's waterfront hospitality sector, where storage-constrained operators are scaling PVC inventory with compressed replacement timelines. Target outcome-based fleet management contracts that displace outright purchases among Australian tour operators. Anchor go-to-market positioning through seasonal maintenance and storage bundling that incumbent manufacturers underprice. For Investors and Strategic Acquirers: EU Green Deal enforcement milestones reshape the acquisition landscape toward fabricators with certified bio-based marine coating pipelines and established reclamation infrastructure. Long-term viability favors specialists with regulatory compliance bandwidth across REACH, EPA, and GB standards rather than commodity hull producers. Target acquisition archetypes include regional carbon fiber repair service networks and polymer compounding facilities with recycled feedstock certification. Watch for REACH substance restriction expansion beyond biocidal compounds into UV-resistant finish categories as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Hull Recycling Infrastructure | EU Green Deal extended producer responsibility mandates reward early reclamation network establishment with preferential market access. |
| Bio-Based Marine Coating Reformulation | REACH compliance migration forces ECHA notification procedures that concentrate R&D burden among premium racing segment specialists. |
| Asset-Light Fleet Leasing Expansion | Thai and Brazilian waterfront hospitality operators are adopting subscription models that shift capital requirements to intermediaries. |
| Recycled Ocean Plastic Feedstock Integration | Post-consumer polymer blends command sustainability premiums in European retail channels while compressing virgin resin demand. |
| Carbon Fiber Repair Technician Certification | Vacuum-infused and composite hull maintenance scarcity creates service revenue concentration in Australian coastal clusters. |
Study Parameters
Cross-validation between tour operator procurement directors and marine coating formulators anchors the qualitative findings in operational reality across fleet management and hull fabrication tiers. Primary interviews with experiential travel operators, composite fabrication plant managers, and waterfront hospitality procurement leads combined with secondary validation from customs trade records, EPA emissions certification filings, and ECHA substance restriction notifications. Bottom-up unit economics across kayak, paddleboard, and jet ski categories triangulate against top-down tourism expenditure flows in Australian, Thai, and Brazilian coastal corridors.
Calibration against historical replacement cycle patterns and regulatory compliance cost trajectories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user intensity, and distribution channel structure alongside regional regulatory cluster alignment. CAGRs derive from installed base turnover rates, fleet expansion trajectories among experiential travel operators, and material substitution elasticities under sustainability mandates. Industry-specific forecast inputs incorporate REACH substance restriction timelines and EPA emissions certification pipeline durations.
Sensitivities concentrate around petrochemical feedstock volatility, carbon fiber precursor supply disruptions, and accelerated EU Green Deal enforcement timelines. Forecasts reflect assumptions on tour operator fleet expansion rates and recycled polymer blend adoption curves. Macroeconomic contraction in coastal tourism corridors, unilateral regulatory acceleration, or breakthrough inflatable hull durability technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Mouthguard Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Balance Bike Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Kneeboard Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Football Equipment Market