
 Knee Pads Market | 2026-2036
Knee Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Pads Market Analysis
Asset-light leasing and project-based procurement is narrowing the capital barrier for smaller contractors to access certified protective equipment. 3M Company leverages its industrial distribution network to sustain bulk supply relationships with major construction firms. Honeywell International Inc. anchors its position through integrated safety portfolios that bundle knee protection with broader personal protective equipment systems. Decathlon SA competes on retail accessibility, positioning affordable sports-oriented knee pads through mass-market channels.
Knee pads are wearable protective devices engineered with energy-absorbing materials such as EVA foam, gel inserts, or hardened polymer shells to attenuate impact forces and distribute pressure across the patellar region during kneeling or collision events. Manufacturing processes typically involve compression molding of closed-cell foams followed by textile lamination to achieve specified thickness and durometer ratings for distinct hazard classes. Hard knee pads dominate commercial construction applications where puncture resistance commands premium positioning, while gel knee pads capture expanding share among professional tradespeople who prioritize sustained comfort during extended kneeling intervals. Soft knee pads lead sports activities due to flexibility requirements, though foam knee pads retain volume in home improvement segments where cost sensitivity prevails over performance specifications.
OSHA mandates in the United States, CE marking requirements under European PPE regulations, and BIS certification standards in India collectively shape product testing protocols and market access conditions for knee pad manufacturers. Compliance with these frameworks determines labeling authority, batch traceability obligations, and material disclosure requirements that directly influence procurement decisions by institutional buyers and government contractors. Stakeholders must monitor evolving harmonized standards for impact attenuation and chemical restriction thresholds that will determine which material formulations and design architectures retain commercial viability.
Market Dynamics
OSHA's updated workplace safety enforcement and the European Union's tightened PPE Regulation (EU) 2016/425 compliance timelines are compressing certification cycles and forcing manufacturers to consolidate testing capabilities or exit non-compliant product lines.
Growth Catalysts
- Construction Safety Mandates:OSHA workplace safety standards in the United States mandate knee protection for kneeling-intensive tasks, institutionalizing procurement across commercial building projects and infrastructure maintenance contracts.
- REACH Chemical Restrictions:The European Chemicals Agency's evolving substance restrictions on phthalates and heavy metals in polymer formulations are accelerating R&D investment in bio-based foam alternatives and closed-loop material recovery systems.
- Gel Insert Technology:Advanced viscoelastic polymer formulations are extending comfortable kneeling duration for professional tilers and flooring installers, converting previously resistant trades to premium protective equipment categories.
Market Restraints
- Petrochemical Input Volatility:Ethylene-vinyl acetate foam and polyurethane gel precursors face price instability tied to crude oil fluctuations, compressing margin predictability for mid-tier manufacturers without long-term supply contracts.
- Chinese Manufacturing Concentration:Compression molding capacity and textile lamination infrastructure cluster in Guangdong and Zhejiang provinces, creating geographic supply risk amplified by port congestion and trade policy uncertainty.
- Disposable Alternative Threat:Low-cost foam kneeling mats and temporary protective boarding substitute for permanent knee pad purchases in residential renovation segments where tool ownership rates remain depressed.
Strategic Opportunities
- Indian Industrial Expansion:Bureau of Indian Standards certification requirements under the mandatory PPE quality control order create first-mover advantage for compliant suppliers targeting infrastructure build-out in Maharashtra and Karnataka construction corridors.
- Smart Wearable Convergence:Integration of pressure sensors and IoT connectivity into protective knee pads is digitizing worksite ergonomics monitoring, opening recurring revenue streams through subscription-based safety analytics platforms.
- Amazon Business Procurement:Institutional purchasing through e-procurement marketplaces is disintermediating traditional industrial distributors, enabling direct manufacturer relationships with mid-sized contractors previously locked out of volume pricing tiers.
Industry Challenges
- Multi-Jurisdiction Certification Overhead:Simultaneous pursuit of CE marking, OSHA NIOSH recognition, and BIS ISI certification demands dedicated regulatory affairs capacity that strains smaller manufacturers' administrative bandwidth.
- Legacy Equipment Integration:New gel-core and smart-sensor knee pad designs require fit compatibility with existing tool belt systems and harness configurations, complicating product development timelines and user adoption pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Pads Market |
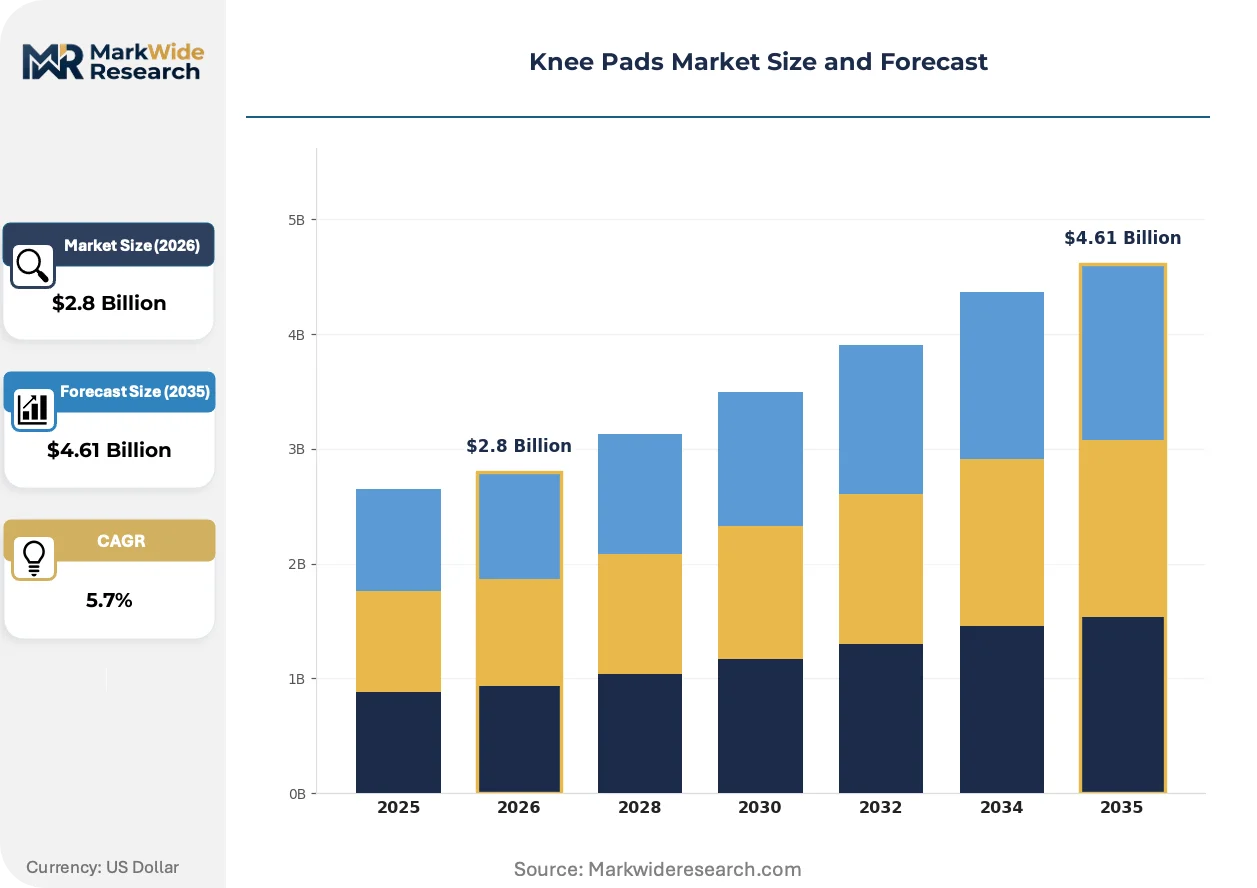
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Knee Pads, Hard Knee Pads, Gel Knee Pads, Foam Knee Pads End User: Construction Workers, Athletes, Gardeners, Homeowners Material: Nylon, Neoprene, EVA Foam, Rubber Application: Sports Activities, Construction Work, Gardening, Home Improvement |
| Companies Covered | 3M Company, Nike Inc., Honeywell International Inc., Decathlon SA, ASICS Corporation, Bauerfeind AG, Stanley Black & Decker Inc., Tommyco Knee Pads Inc., McDavid Holdings Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Pads Market Emerging Trajectories
Wearable technology integration and material science advances are compressing product lifecycles while regulatory harmonization efforts are standardizing performance benchmarks across previously fragmented national markets.
Pressure-mapping sensor arrays embedded in gel-core knee pads are digitizing real-time load distribution data for construction safety officers. Large infrastructure contractors in Germany and Australia are piloting these systems to validate ergonomic compliance and reduce workers' compensation claims. The technology is digitizing post-incident liability documentation and enabling predictive maintenance scheduling for protective equipment replacement cycles.
The European Union's 2024 amendment to PPE Regulation (EU) 2016/425 expands documentation requirements for chemical substance disclosure and supply chain traceability. Manufacturers must now maintain batch-level material certificates for foam formulations and polymer shells, increasing administrative overhead but creating competitive differentiation for compliant suppliers. Hard-shell knee pad categories face the steepest compliance burden due to multi-component construction and imported raw material dependencies.
Project-based equipment leasing through specialized safety service providers is displacing capital purchase models among smaller mechanical and electrical contractors. This arrangement bundles knee pad provision with laundering, inspection, and replacement services, converting fixed equipment costs to variable operational expenditures. The shift is most pronounced in United Kingdom commercial fit-out sectors where contractor liquidity constraints and short project tenures dominate procurement decision frameworks.
Knee Pads Market Segmentation
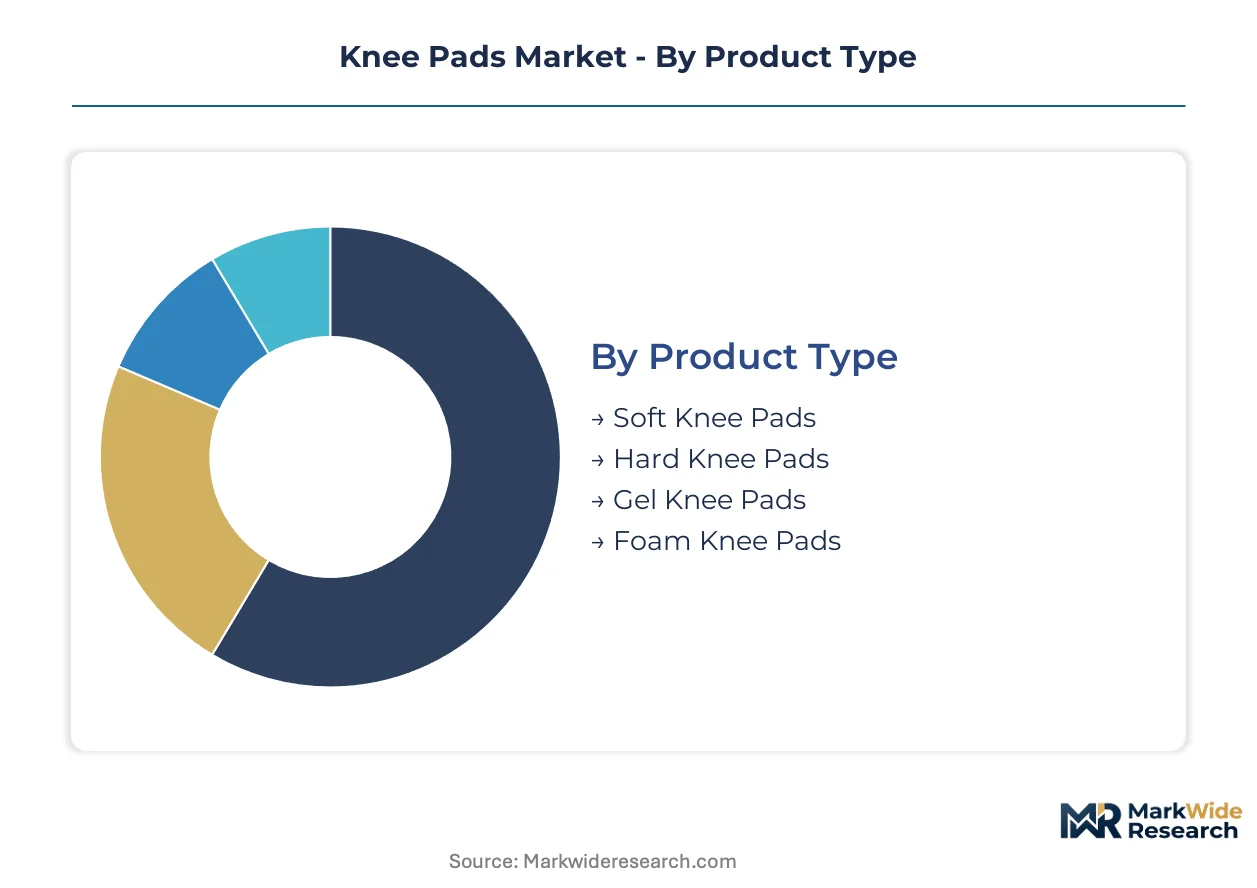
Segmentation in the knee pads market reveals how protective equipment demand fragments across radically different performance requirements, price sensitivities, and regulatory exposure. Understanding these divides allows manufacturers to align material investments, certification strategies, and channel positioning with commercially distinct buyer clusters.
Product Type:
Cost tier stratification separates commodity foam products from premium gel formulations and specialized hard-shell architectures.
- Soft Knee Pads:Fabric-encased foam or fiber padding prioritizes flexibility and breathability for dynamic movement. Athletes in basketball and volleyball drive procurement volumes in the United States and Germany, where sports participation rates sustain replacement cycles.
- Hard Knee Pads:Rigid polymer shells bonded to cushioned backing deliver puncture resistance against rebar, gravel, and construction debris. Commercial contractors in Australia and Canada specify these for infrastructure maintenance contracts where OSHA-equivalent mandates enforce compliance.
- Gel Knee Pads:Viscoelastic polymer inserts distribute pressure across the patellar region during extended kneeling intervals. Professional tilers and flooring installers in the United Kingdom convert to this category as ergonomic claims reduce workers' compensation exposure.
- Foam Knee Pads:Compression-molded closed-cell EVA constructions dominate residential renovation segments. Homeowners in India and Brazil select these for intermittent DIY use where tool ownership rates remain depressed and cost sensitivity prevails.
Hard knee pads command the established base in commercial construction procurement. The steepest expansion runs through gel knee pads as professional trades prioritize sustained comfort over initial purchase price.
End User:
Application intensity and regulatory proximity separate institutional buyers from discretionary consumers.
- Construction Workers:Daily kneeling exposure across 8-12 hour shifts creates predictable replacement demand. Infrastructure contractors in Germany and Japan bundle knee protection with broader personal protective equipment systems to satisfy site safety officers.
- Athletes:Collision-prone sports participants require impact attenuation without mobility restriction. Basketball and volleyball leagues in the United States specify certified protective gear that meets NCAA and amateur federation standards.
- Gardeners:Seasonal kneeling patterns generate intermittent purchase cycles concentrated in spring retail windows. Mass-market garden centers in France and Italy stock affordable neoprene-backed options for hobbyist cultivation.
- Homeowners:Infrequent home improvement projects sustain entry-level foam pad volumes through hardware retail. Big-box channels in Canada and Australia capture this segment with private-label products priced below professional grades.
Construction workers anchor institutional procurement volumes. Athletes represent the most brand-sensitive segment with replacement-driven recurring revenue.
Material:
Supply chain geography and petrochemical input volatility differentiate synthetic polymer options from natural rubber alternatives.
- Nylon:High-tensile synthetic textile provides abrasion-resistant outer shells for hard knee pad constructions. Injection molding clusters in Guangdong province supply fabricators serving North American and European safety distributors.
- Neoprene:Chloroprene rubber formulations deliver water-resistant flexibility for wet-environment gardening applications. Formulators in Japan and South Korea supply specialty grades with enhanced UV stability for outdoor retail channels.
- EVA Foam:Ethylene-vinyl acetate copolymers enable compression-molded cushioning at scale. Price instability tied to crude oil fluctuations compresses margin predictability for mid-tier manufacturers without long-term supply contracts.
- Rubber:Natural and synthetic elastomer compounds retain share in cost-sensitive emerging markets. Indian domestic producers leverage local rubber cultivation to undercut imported polymer alternatives for BIS-certified product lines.
EVA foam dominates volume production. Neoprene commands premium positioning in weather-exposed applications.
Application:
Regulatory enforcement intensity and injury liability exposure separate mandated workplace use from discretionary consumer purchase.
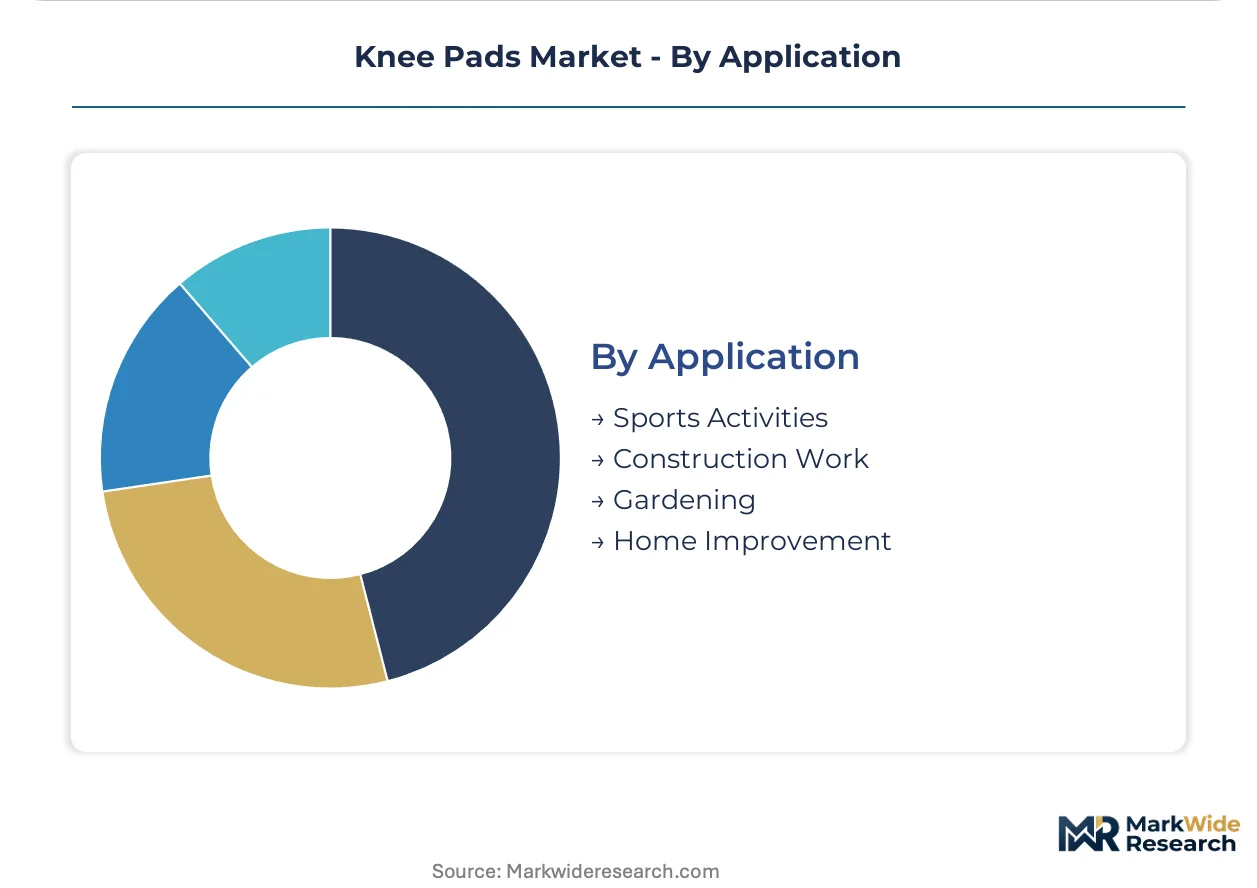
- Sports Activities:Governing body certification requirements and league insurance mandates institutionalize protective gear procurement. Amateur athletic associations in the United States and Germany specify impact-tested knee pads for organized competition.
- Construction Work:OSHA workplace safety standards and CE marking under EU PPE Regulation (EU) 2016/425 compress non-compliant product viability. Large infrastructure contractors in Australia pilot sensor-embedded smart knee pads to digitize ergonomic compliance documentation.
- Gardening:Low-frequency kneeling tasks sustain soft pad demand through seasonal retail peaks. Mass-market channels in Italy and France capture this segment with affordable textile-laminated constructions.
- Home Improvement:Project-based tool acquisition patterns concentrate demand in hardware retail. Disposable foam kneeling mats substitute for permanent knee pad purchases where residential renovation activity remains sporadic.
Construction work anchors regulatory-driven procurement stability. Sports activities generate the highest brand premium capture and fastest product lifecycle turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The knee pads market exhibits pronounced trade asymmetry, with finished protective equipment flowing from East Asian manufacturing clusters toward North American and European institutional buyers. Import dependency concentrates in advanced economies where domestic foam molding capacity cannot satisfy construction sector procurement volumes.
United States
OSHA workplace safety mandates institutionalize knee protection procurement across commercial building and infrastructure maintenance contracts. The Department of Labor enforces kneeling-intensive task protocols that compress non-compliant product viability. Industrial distributors in Texas and California anchor bulk supply relationships with major construction firms.
Germany
REACH chemical restrictions on phthalates and heavy metals accelerate R&D investment in bio-based foam alternatives among domestic formulators. The European Chemicals Agency's evolving substance disclosure requirements shape batch-level certification obligations. Manufacturing clusters in Bavaria and North Rhine-Westphalia specialize in premium gel-core constructions for professional trades.
China
Compression molding capacity concentrates in Guangdong and Zhejiang provinces, supplying global volume demand for EVA foam and textile lamination. The country's national standards administration maintains GB certification protocols for domestic PPE distribution. Port infrastructure in Shenzhen and Ningbo channels exports toward North American safety distributors.
India
Bureau of Indian Standards certification requirements under mandatory PPE quality control orders create first-mover advantage for compliant suppliers. The national infrastructure build-out in Maharashtra and Karnataka construction corridors generates institutional procurement demand. Domestic rubber cultivation in Kerala and Tamil Nadu undercuts imported polymer alternatives for cost-sensitive segments.
Australia
Large infrastructure contractors pilot sensor-embedded smart knee pads to digitize ergonomic compliance documentation. The national workplace safety regulator enforces kneeling protection standards equivalent to OSHA frameworks. Mining and construction activity in Western Australia and Queensland sustains replacement-driven demand for hard-shell puncture-resistant designs.
Knee Pads Market Vendor Landscape
On the supply side, the industry is tiered between diversified industrial conglomerates, specialized safety equipment manufacturers, and mass-market sporting goods retailers. Strategic archetypes include integrated PPE portfolio providers, component-focused gel technology specialists, and retail-accessible volume distributors. Competitive moves concentrate on certification consolidation across multi-jurisdiction frameworks and e-procurement channel disintermediation of traditional industrial distributors.
Among diversified industrial conglomerates, 3M Company and Honeywell International Inc. exemplify the integrated PPE portfolio archetype, bundling knee protection with broader safety systems to satisfy institutional procurement requirements. Decathlon SA occupies a position within the retail-accessible tier, leveraging mass-market channel density to capture sports-oriented and residential renovation segments. These three entities represent distinct competitive vectors: industrial distribution scale, integrated safety system bundling, and consumer retail accessibility.
| Leading Market Players |
|---|
| 3M Company |
| Nike Inc. |
| Honeywell International Inc. |
| Decathlon SA |
| ASICS Corporation |
| Bauerfeind AG |
| Stanley Black & Decker Inc. |
| Tommyco Knee Pads Inc. |
| McDavid Holdings Company LLC |
| Others |
Supply Flow & Price Mechanics
Petrochemical input volatility in ethylene-vinyl acetate foam and polyurethane gel precursors compresses margin predictability across all pricing tiers while simultaneously forcing supply chain consolidation toward vertically integrated manufacturers with captive polymer sourcing. This dual pressure widens spreads between premium gel formulations and commodity foam products as smaller fabricators exit non-compliant product lines.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing that stratifies across premium gel-core, standard hard-shell, and economy foam tiers. Price differentiation hinges on CE marking tier and volume scale, with certified construction-grade products commanding substantial premiums over residential DIY alternatives. Cost compression in the economy tier intensifies because crude oil fluctuations transmit directly to EVA foam input costs. Home improvement retailers exhibit the highest price sensitivity, while infrastructure contractors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Extended payment terms from major construction distributors and supply-chain finance facilities from industrial distributors shape working capital requirements for manufacturers. Compression molding capacity concentrates in China, India, and Vietnam, with textile lamination infrastructure clustering in Guangdong and Zhejiang provinces. Raw material dependencies center on petrochemical-derived EVA copolymers, synthetic textile fibers, and viscoelastic polymer gels. Single-source vulnerability runs through Guangdong province molders serving North American safety distributors. Distribution runs through industrial safety distributors, mass-market sporting goods retailers, and emerging e-procurement marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The knee pads market sits in early-cycle expansion as gel insert technology converts previously resistant professional trades to premium protective equipment categories. OSHA enforcement tightening and European PPE Regulation compliance timelines institutionalize replacement demand across commercial construction.
For Market Incumbents: Build certification moats across multi-jurisdiction frameworks including CE marking, OSHA NIOSH recognition, and BIS ISI certification to exclude smaller competitors. Consolidate testing capabilities in-house to compress certification cycle times. Add compression molding capacity in India to serve Maharashtra and Karnataka construction corridors while reducing exposure to Chinese port congestion. Vertical integration into bio-based foam R&D addresses REACH chemical restrictions on phthalates. For New Entrants and Emerging Players: India's BIS certification requirements under mandatory PPE quality control orders represent the most penetrable geographic entry point for compliant suppliers. Target professional flooring installer segments in the United Kingdom where ergonomic claims reduce workers' compensation exposure and gel knee pad conversion remains incomplete. Pursue Amazon Business procurement channels to disintermediate traditional industrial distributors and access mid-sized contractors previously locked out of volume pricing tiers. For Investors and Strategic Acquirers: The market sits at a technology-integration phase that favors component-focused gel technology specialists with sensor-embedded product pipelines. Long-term viability across the five-to-ten year window rests on convergence with IoT-enabled safety analytics platforms generating recurring revenue streams. Acquisition target archetypes include smart wearable technology developers with pressure-mapping sensor arrays and established certification infrastructure. The signal to watch is pilot adoption rates among German and Australian infrastructure contractors digitizing ergonomic compliance documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Consolidation | Simultaneous CE marking, OSHA NIOSH, and BIS pursuit excludes smaller competitors lacking dedicated regulatory affairs capacity. |
| Gel-Core Technology R&D Investment | Advanced viscoelastic polymer formulations extend comfortable kneeling duration for professional tilers and flooring installers. |
| Smart Sensor Integration | Pressure-mapping arrays digitize real-time load distribution data for construction safety officers reducing workers' compensation claims. |
| E-Procurement Channel Development | Amazon Business institutional purchasing disintermediates traditional industrial distributors serving mid-sized contractors. |
| Indian Manufacturing Footprint Expansion | BIS-compliant domestic production captures infrastructure build-out demand in Maharashtra and Karnataka construction corridors. |
Methodological Framework
A standing panel of safety equipment procurement managers at major construction firms, regulatory affairs specialists at PPE manufacturers, industrial distribution channel partners, and worksite safety officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from OSHA enforcement databases, EU PPE Regulation compliance filings, Bureau of Indian Standards certification records, and customs trade data for EVA foam and polymer gel imports. Bottom-up product-type and end-user segmentation triangulated against top-down construction sector expenditure patterns.
Scenario-bracketing around petrochemical price volatility, regulatory enforcement intensity, and smart wearable adoption rates bounded projections across the analysis window. Segmentation dimensions modeled include product type tier, end-user application intensity, material formulation, and regional regulatory cluster. CAGRs derived from historical replacement cycle analysis and penetration rate assumptions for gel and smart-sensor categories. Industry-specific inputs incorporated construction employment trends and sports participation rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by diversified industrial conglomerates would shift outcomes. Macroeconomic deviation in crude oil markets, regulatory acceleration in chemical restrictions, or breakthroughs in bio-based foam alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Mini Balance Beam Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Mouthguard Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Crampon Market
Sports Equipment
Slam Ball Market
Sports Equipment
Racket Sports Equipment Market