
 Asia Pacific Sports Promoter Market | 2026-2036
Asia Pacific Sports Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sports Promoter Market Insights
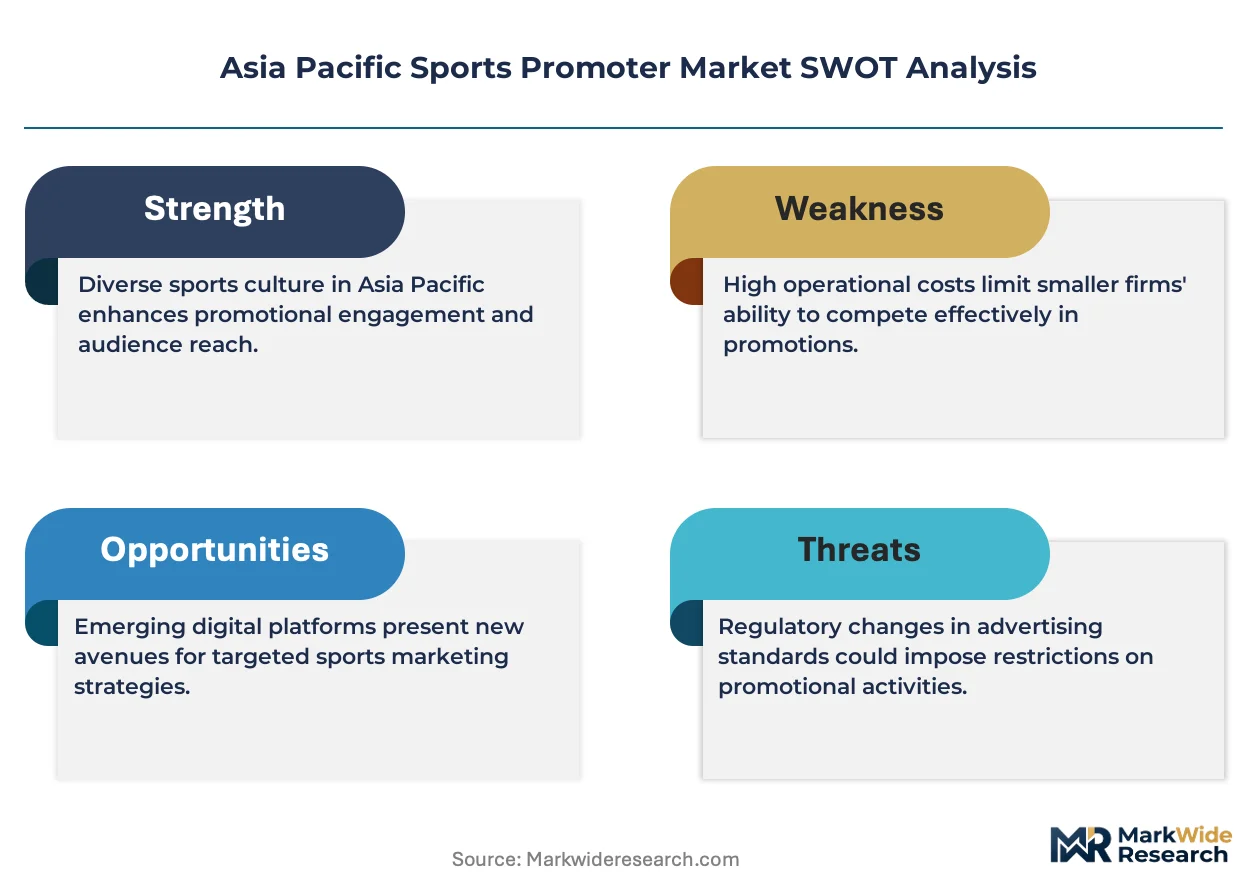
Digital media rights packaging is realigning what sports promoters sell across Asia Pacific, shifting from fixed-fee event management to recurring revenue from streaming partnerships and content licensing. Endeavor leverages its transnational talent network to control premium athlete representation contracts in cricket and mixed martial arts. JSW Sports anchors Indian market presence through deep vertical ties to domestic leagues and franchise operations. Singapore Sports Hub competes by operating integrated stadium-entertainment complexes that bundle promotion with venue infrastructure.
Asia Pacific sports promoters are entities that plan, finance, market, and execute sporting events across professional and amateur tiers, typically managing broadcast coordination, sponsorship procurement, and ticket distribution through centralized operational platforms. Their commercial purpose centers on converting athletic competition into monetizable entertainment products through audience aggregation and brand association. Event promotion commands the largest revenue pool among service types due to the capital intensity of securing venue rights and talent contracts, while sponsorship management represents the fastest-expanding segment as brands seek measurable engagement metrics beyond logo placement. Media rights as a revenue stream increasingly determines promoter profitability as streaming platforms displace traditional broadcasters across Southeast Asian markets.
China's SAMR monitors anti-competitive practices in sports media rights auctions, while India's TRAI regulates broadcast tariff structures that directly shape promoter revenue sharing with platforms. Japan's METI promotes sports industry growth through event tourism initiatives that alter promoter geographic priorities. Stakeholders must track how platform-specific content regulations in each jurisdiction reshape contract structures and audience access models.
Market Dynamics
Streaming platforms are compressing promoter revenue cycles by demanding exclusive content windows and direct-to-consumer distribution rights, forcing traditional event managers to restructure talent contracts around recurring digital output rather than one-off gate receipts.
Growth Catalysts
- India's PLI scheme for sports infrastructure:Production-linked incentives for broadcasting technology and venue construction are accelerating private capital deployment into integrated event management capabilities.
- China's state-backed sports development programs:Mega-event hosting rights are restructuring promoter contract awards toward multi-year bundled service agreements with state entities.
- 5G broadcast infrastructure rollout:Low-latency streaming is enabling real-time wagering integration and interactive viewer formats that expand monetizable inventory per event.
Market Restraints
- Talent contract inflation:Exclusive representation agreements with elite athletes in cricket and mixed martial arts are compressing promoter margins on fixed-fee events.
- Venue supply concentration:Premium stadium infrastructure clusters in Singapore, Sydney, and Tokyo limit promoter bargaining power on rental terms for marquee events.
- TRAI broadcast tariff regulations:India's price caps on sports channel subscriptions constrain revenue-sharing negotiations between promoters and streaming platforms.
Strategic Opportunities
- Vietnam and Philippines event tourism:Underdeveloped sports entertainment infrastructure creates first-mover advantages for promoters establishing localized talent development pipelines.
- Japan's METI event tourism initiatives:Government subsidies for international sporting events are lowering promoter customer acquisition costs in secondary cities.
- Blockchain-based ticketing and royalty tracking:Smart contract automation is reducing secondary market leakage and enabling fractional athlete investment instruments.
Industry Challenges
- Cross-border content licensing complexity:Platform-specific regulations in China, India, and Australia require jurisdiction-specific contract structures that fragment media rights packaging.
- Legacy broadcast partnership renegotiation:Existing exclusive agreements with terrestrial networks are blocking direct-to-consumer streaming pivots in Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sports Promoter Market |
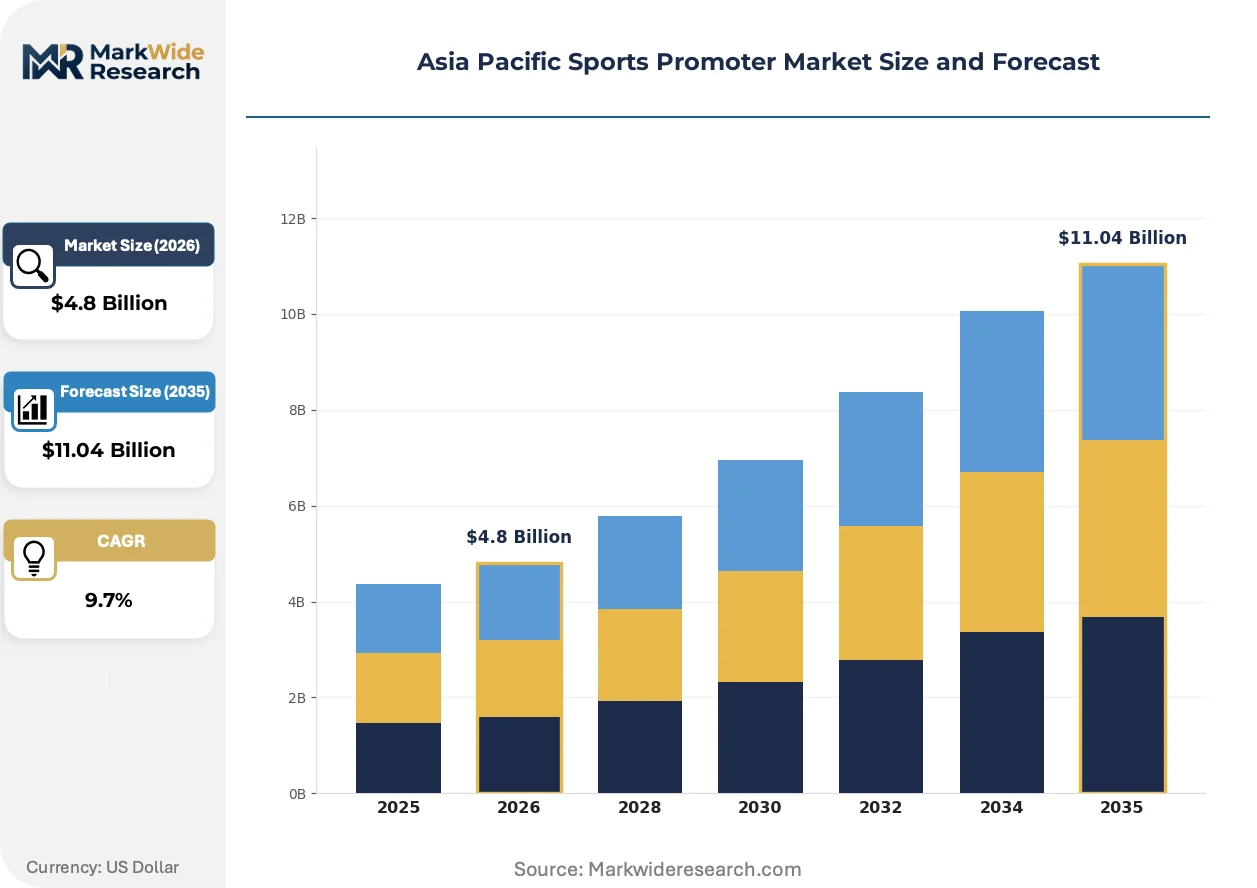
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Promotion, Sponsorship Management, Marketing Consultation, Athlete Representation Client Type: Professional Teams, Sports Federations, Corporate Sponsors, Individual Athletes Revenue Stream: Ticket Sales, Merchandise, Media Rights, Sponsorship Fees Marketing Channel: Social Media, Traditional Media, Direct Outreach, Partnerships |
| Companies Covered | Sports Next Asia, Ten Events Asia, GAA Events, Event Planning Group, Rise Worldwide, China Sports Media, Singapore Sports Hub, Endeavor, JSW Sports, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sports Promoter Market Trends and Innovations
Artificial intelligence and immersive media formats are redefining how promoters aggregate and monetize audiences, shifting competitive advantage from venue control toward data-driven personalization and virtual participation models.
AI-powered real-time highlight generation is electrifying content production workflows for sports promoters across Asia Pacific. Regional streaming platforms including those in India and Southeast Asia are adopting automated clipping systems to feed short-form video distribution. This compression of post-production timelines is enabling same-event monetization across multiple content formats and platform windows.
China's SAMR anti-competitive practice monitoring in sports media rights auctions is reshaping how exclusive broadcast contracts are structured and awarded. The regulator's intervention against bundled rights packages is fragmenting previously centralized promoter-platform negotiations. Promoters in China are responding by unbundling digital and terrestrial rights to maintain compliance while preserving revenue floors.
Viewer engagement patterns are pivoting toward on-demand and interactive formats that bypass traditional linear broadcast schedules. Younger demographics in India and Southeast Asia are consuming sports content through mobile-first platforms that emphasize wagering integration and social viewing features. This behavioral shift is most visible in cricket and esports verticals where promoters are restructuring event formats around shorter durations and real-time participation mechanics.
Asia Pacific Sports Promoter Market Segmentation
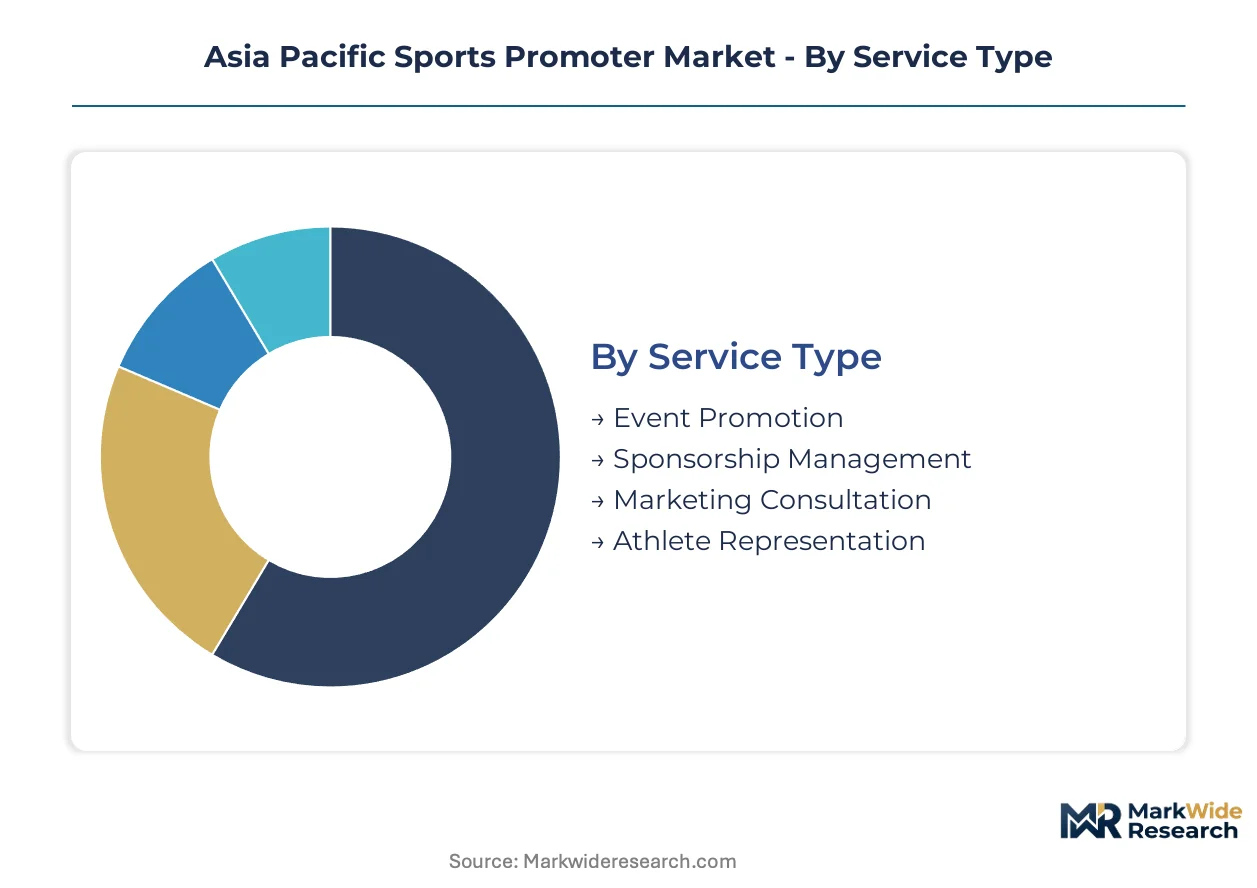
Sports promoter revenue models in Asia Pacific fragment across service delivery methods and client relationship structures. Each segment carries distinct regulatory exposure and margin profiles that determine competitive positioning.
Service Type:
Certification requirements vary sharply across service types, with athlete representation demanding licensing from national sports federations while event promotion operates under municipal entertainment permits and broadcasting clearances.
- Event Promotion:Capital-intensive coordination of venue rights, talent contracts, and broadcast logistics through centralized operational platforms. Demand concentrates in China where state-backed mega-event hosting programs are restructuring contract awards toward multi-year bundled service agreements with government entities, compressing promoter margins through volume commitments.
- Sponsorship Management:Procurement and activation of brand partnerships with measurable engagement metrics beyond logo placement. Growth accelerates in India as PLI scheme incentives for sports infrastructure attract private capital into integrated event management capabilities, creating demand for sophisticated sponsorship analytics.
- Marketing Consultation:Strategic advisory on audience aggregation and brand association architectures.
- Athlete Representation:Exclusive talent contracts and commercial rights negotiation with elite performers.
Leading the category by volume: Event Promotion. Growing fastest: Sponsorship Management.
Client Type:
Cost tiers separate retained relationships from project-based engagements, with professional teams commanding premium pricing for integrated season-long services versus transactional event contracts.
- Professional Teams:Franchise-based organizations requiring continuous commercial optimization across ticketing, merchandise, and digital content. India's IPL franchises and Australia's Big Bash League clubs are expanding retained promoter relationships to capture recurring revenue from streaming partnerships rather than one-off gate receipts.
- Sports Federations:Governing bodies managing international competition calendars and qualification pathways. China's General Administration of Sport is consolidating promoter contracts under state-directed procurement frameworks that bundle domestic and international event rights.
- Corporate Sponsors:Brand principals seeking direct association with athletic competition and audience aggregation.
- Individual Athletes:Elite performers negotiating commercial representation and personal brand monetization.
Dominant by contract value: Professional Teams. Expanding most quickly: Sports Federations.
Revenue Stream:
Application-specific monetization models determine working capital intensity, with ticket sales requiring upfront venue deposits while media rights generate deferred payment schedules.
- Ticket Sales:Direct-to-consumer distribution through primary and secondary market channels. Singapore Sports Hub and Sydney's stadium infrastructure clusters limit promoter bargaining power on rental terms, compressing margins for marquee events in supply-constrained markets.
- Media Rights:Licensing of broadcast and streaming distribution rights across platform windows. Southeast Asian markets are displacing traditional broadcasters with platform-specific streaming services, forcing promoters to unbundle digital and terrestrial rights to maintain compliance with China's SAMR anti-competitive practice monitoring.
- Merchandise:Branded product licensing and event-specific retail activation.
- Sponsorship Fees:Fixed and performance-based brand partnership compensation.
Highest revenue concentration: Media Rights. Steepest expansion trajectory: Sponsorship Fees.
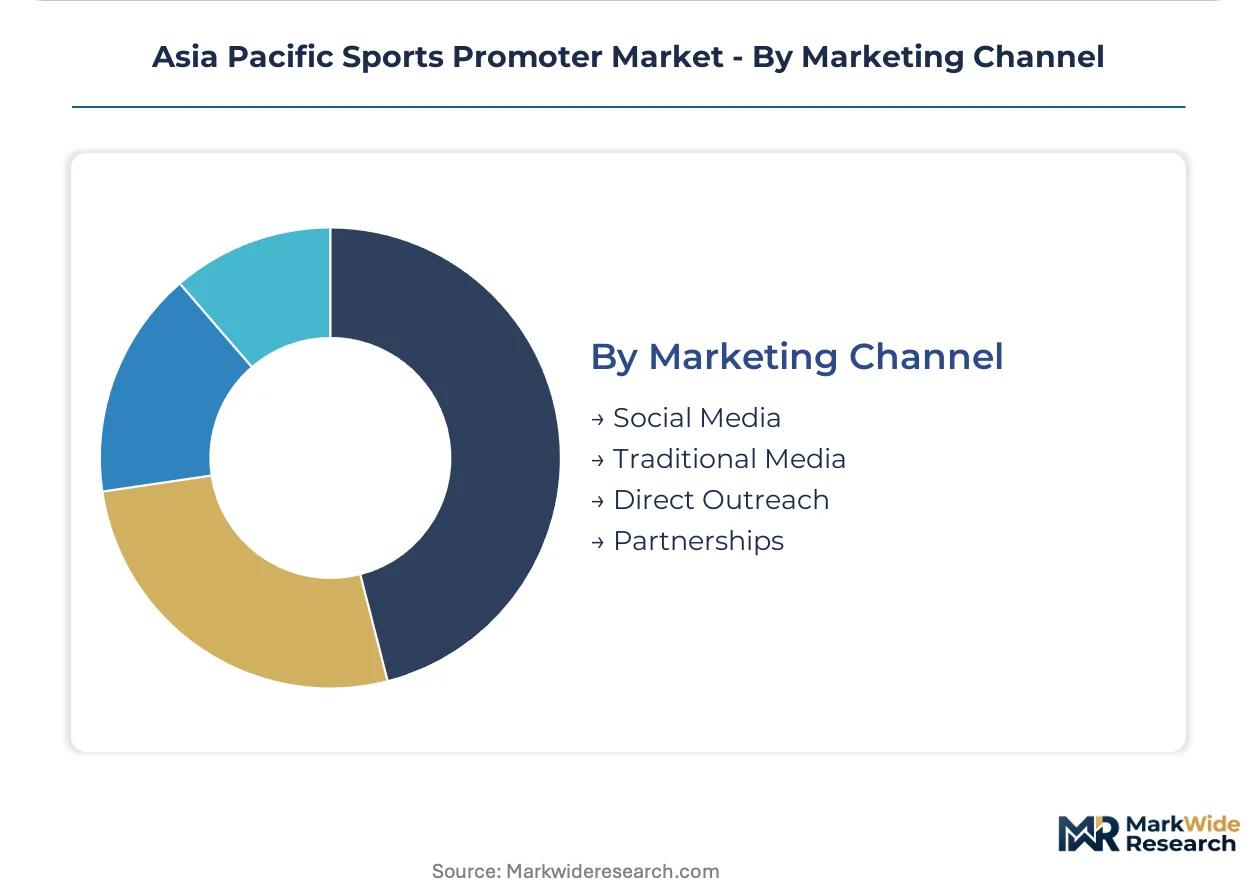
Marketing Channel:
Customer acquisition costs diverge by channel maturity, with social media commanding platform-dependent content production investments versus traditional media's fixed placement fees.
- Social Media:Short-form video distribution and influencer-integrated campaign architectures. India's TRAI broadcast tariff regulations constrain direct revenue-sharing negotiations, pushing promoters toward platform-agnostic social distribution that bypasses price-capped sports channel subscriptions.
- Traditional Media:Terrestrial television, radio, and print placement for demographic reach. Legacy broadcast partnership renegotiation in Southeast Asia blocks streaming pivots, preserving traditional media's role in markets with exclusive terrestrial network agreements.
- Direct Outreach:Database-driven email and SMS campaigns with personalized ticketing offers.
- Partnerships:Cross-promotional arrangements with complementary entertainment and hospitality verticals.
Widest reach: Traditional Media. Gaining share fastest: Social Media.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Event production capacity concentrates in China's state-backed mega-event infrastructure, while consumption demand fragments across India's franchise leagues and Southeast Asia's emerging digital audiences. Promoters bridge this divide through localized partnership structures and jurisdiction-specific media rights packaging.
China
State-directed procurement frameworks bundle domestic and international event rights under centralized contracts. SAMR monitors anti-competitive practices in media rights auctions, fragmenting previously centralized promoter-platform negotiations. Shanghai and Beijing host the primary infrastructure clusters where promoters unbundle digital and terrestrial rights to maintain compliance.
India
IPL franchises and Big Bash League clubs drive retained promoter relationships for streaming revenue capture. TRAI broadcast tariff regulations constrain direct revenue-sharing negotiations, pushing promoters toward platform-agnostic social distribution. Mumbai and Delhi-NCR anchor the talent representation and event management concentration.
Japan
METI event tourism initiatives lower customer acquisition costs for international sporting events in secondary cities. Government subsidies restructure promoter geographic priorities toward regional urban centers. Osaka and Nagoya emerge as alternative event destinations outside the Tokyo infrastructure cluster.
Australia
Premium stadium infrastructure in Sydney limits promoter bargaining power on rental terms for marquee events. Supply-constrained venue markets compress margins through concentrated landlord negotiating leverage. Melbourne's integrated sports-entertainment complexes compete through bundled venue-promotion service offerings.
Singapore
Singapore Sports Hub operates integrated stadium-entertainment complexes that bundle promotion with venue infrastructure. City-state scale enables centralized regulatory coordination for international event licensing. The regional hub position attracts cross-border promoter operations serving Southeast Asian market entry.
Asia Pacific Sports Promoter Market Competitive Landscape
Top-tier vendors anchor integrated service platforms, while mid-tier specialists concentrate on single-service excellence or geographic niches. The market structures around three strategic archetypes: transnational talent networks controlling premium athlete representation, domestic league-anchored vertical integrators, and infrastructure-linked venue operators. Consolidation pressures favor multi-service bundling and direct-to-consumer streaming pivots over traditional event management.
Within the transnational network tier, Endeavor occupies a position exemplifying cross-border talent control in cricket and mixed martial arts. JSW Sports represents the domestic vertical integrator archetype through deep franchise league ties. Singapore Sports Hub anchors the infrastructure-operator model by bundling venue management with promotion services. These three patterns illustrate how competitive positioning fragments across service integration strategies rather than scale alone.
| Leading Market Players |
|---|
| Sports Next Asia |
| Ten Events Asia |
| GAA Events |
| Event Planning Group |
| Rise Worldwide |
| China Sports Media |
| Singapore Sports Hub |
| Endeavor |
| JSW Sports |
| Others |
Pricing and Supply Chain Analysis
5G broadcast infrastructure rollout across Asia Pacific simultaneously compresses production cost curves and concentrates technical talent pools in Singapore, Sydney, and Tokyo. Low-latency streaming capabilities reshape what promoters pay for venue access versus what they recapture through wagering-integrated content formats.
Pricing Analysis
Margin tightening in event promotion reflects talent contract inflation and venue supply concentration. Three-tier pricing structure across premium, standard, and economy levels separates retained franchise relationships from transactional single-event contracts and talent representation agreements. Price differentiation hinges on athlete exclusivity tiers and broadcast window guarantees. Cost-down pressure accelerates because streaming platforms demand direct-to-consumer distribution rights that bypass traditional gate-receipt economics. Corporate sponsors show least price sensitivity for integrated season-long packages, while amateur sports federations face acute budget constraints.
Supply Chain Analysis
Technical workforce availability in Singapore, Sydney, and Tokyo anchors broadcast production and venue management capacity. Supply draws from China's state-backed mega-event infrastructure programs, India's PLI scheme-supported broadcasting technology deployment, and Japan's METI-subsidized regional event tourism networks. Critical inputs include 5G transmission equipment, AI-powered content generation systems, and blockchain-based ticketing platforms. Single-source vulnerability concentrates in premium stadium infrastructure clusters. Distribution runs through centralized promoter operational platforms that bundle venue rights, talent contracts, and broadcast logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific sports promotion is consolidating around multi-service bundling as streaming platform demands and talent contract inflation force pure-play event managers toward acquisition or exit.
For Market Incumbents: Acquire AI-powered content generation capabilities to defend against streaming platform disintermediation. Deepen backward integration into venue infrastructure through long-term lease structures in Singapore and Sydney. Build exclusive talent pipelines in cricket and mixed martial arts before representation costs escalate further. Secure blockchain ticketing patents to capture secondary market revenue leakage. For New Entrants and Emerging Players: India's PLI scheme for sports infrastructure opens a window for localized event management capabilities in tier-two cities. Vietnam and Philippines event tourism presents white-space targets with underdeveloped sports entertainment infrastructure and government appetite for international event subsidies. Pursue sponsorship management specialization with measurable engagement analytics rather than capital-intensive event promotion. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure-linked venue operators with integrated promotion capabilities. Long-term viability favors promoters controlling recurring streaming revenue shares over transactional gate-receipt dependence. Target acquisition archetypes include domestic vertical integrators with deep franchise league ties. Watch for SAMR regulatory intervention in China fragmenting bundled media rights as inflection signal for unbundling plays elsewhere.| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Rights Unbundling | China's SAMR anti-competitive monitoring fragments digital and terrestrial rights to maintain compliance. |
| Venue Infrastructure Acquisition | Singapore Sports Hub model bundles promotion with stadium operations in supply-constrained markets. |
| AI Content Generation Investment | Automated highlight systems compress post-production timelines for same-event multi-format monetization. |
| Blockchain Ticketing Deployment | Smart contract automation reduces secondary market leakage and enables fractional athlete instruments. |
| Regional Event Tourism Expansion | Japan's METI subsidies lower customer acquisition costs in Osaka and Nagoya secondary markets. |
Research Methodology
Document review covered sports federation procurement frameworks, streaming platform licensing agreements, and national sports infrastructure investment programs, complemented by interviews with event promotion executives, broadcast technology procurement leads, venue operations managers, and athlete representation agents. Secondary sources included TRAI broadcast tariff filings, SAMR anti-competitive practice decisions, METI event tourism subsidy disclosures, and PLI scheme implementation guidelines. Bottom-up service-type revenue estimates were triangulated against top-down regional market sizing.
Historical revenue trajectories were cross-referenced against expert panel input on platform migration timing and regulatory enforcement intensity. The analytical framework modeled segmentation across service type, client relationship structure, revenue stream composition, and marketing channel mix throughout the forecast period. CAGRs were derived from streaming penetration curves, venue capacity expansion pipelines, and talent contract inflation trends.
Caveats apply where SAMR regulatory intervention intensity, TRAI tariff structure revisions, or 5G infrastructure deployment delays could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Smart Fitness Device Market