
 Smart Fitness Wear Market | 2026-2036
Smart Fitness Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fitness Wear Market Intelligence
The buyer base for smart fitness wear is expanding from niche fitness enthusiasts to a broader demographic of casual users and health-conscious consumers. Apple leverages its powerful ecosystem to integrate health features deeply into its smart watches. Garmin specializes in high-performance devices for dedicated athletes and outdoor adventurers. Xiaomi competes on price and accessibility, capturing a large volume of the casual user segment.
Smart fitness wear comprises electronic devices worn on the body, designed to collect and transmit data related to physical activity and health metrics. These devices integrate biometric sensors, such as optical heart rate monitors or accelerometers, to track vitals and movement. While smart watches lead the market in value, dedicated fitness trackers remain popular for their simplicity and lower cost. The professional athletes end-user segment drives innovation in sensor accuracy and data analytics.
Regulatory frameworks like the FDA's guidance on medical devices in the United States and the CE marking requirements in Europe define the pathway for clinical-grade features. In China, the NMPA oversees devices with medical claims, influencing product design and data handling protocols. Stakeholders must navigate the diverging requirements for consumer wellness gadgets versus regulated medical-grade wearables.
Market Dynamics
The market's central dynamic is the divergence between consumer-grade wellness devices and medically certified wearables. This split forces manufacturers to choose between mass-market volume and high-margin clinical applications, influencing sensor investment, software development, and regulatory strategy.
Growth Catalysts
- Government Wellness Initiatives:Public health campaigns, particularly China's "Healthy China 2030" plan, promote preventative health and physical activity, creating a large, state-supported user base for fitness tracking technology.
- Professional Athlete Adoption:Elite sports organizations and professional athletes demand high-fidelity biometric data for performance optimization, driving innovation in sensor accuracy and advanced analytics that eventually trickles down to consumer products.
- Sensor Miniaturization:Advances in micro-electro-mechanical systems (MEMS) and optical sensor technology enable the integration of more sophisticated monitoring capabilities, such as SpO2 and ECG, into smaller, more comfortable form factors.
Market Restraints
- Data Privacy Concerns:Consumer apprehension regarding the security and use of sensitive personal health data, governed by regulations like GDPR in Europe, can limit adoption and data-sharing willingness.
- Regulatory Compliance Costs:Achieving medical device certification from bodies like the FDA in the United States or through CE marking in Europe involves significant investment and lengthy validation cycles, creating a high barrier to entry for clinical-grade features.
- Battery Life Limitations:The inclusion of advanced sensors and high-resolution displays increases power consumption, creating a technical trade-off between device functionality and battery longevity that constrains user experience.
Strategic Opportunities
- Targeting Chronic Disease Management:Developing wearables with features for monitoring conditions like diabetes or hypertension opens a high-value market segment, integrating with telehealth platforms and insurance provider programs.
- Corporate Wellness Programs:Partnering with corporations to provide employees with subsidized fitness wearables offers a scalable B2B2C distribution channel, promoting employee health and generating large-volume sales.
- Expansion in Underserved Geographies:Markets like India and Brazil, with their large populations and rising health consciousness, present significant growth opportunities for affordably priced smart fitness devices.
Industry Challenges
- Data Interoperability:A lack of standardization presents a significant challenge in ensuring seamless data flow between different wearable ecosystems, electronic health records (EHR), and third-party fitness applications, limiting the utility of collected data.
- Clinical Validation Timelines:The lengthy and rigorous process of conducting clinical trials to validate the accuracy of medical-grade sensors for regulatory bodies like the NMPA in China can delay product launches by years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fitness Wear Market |
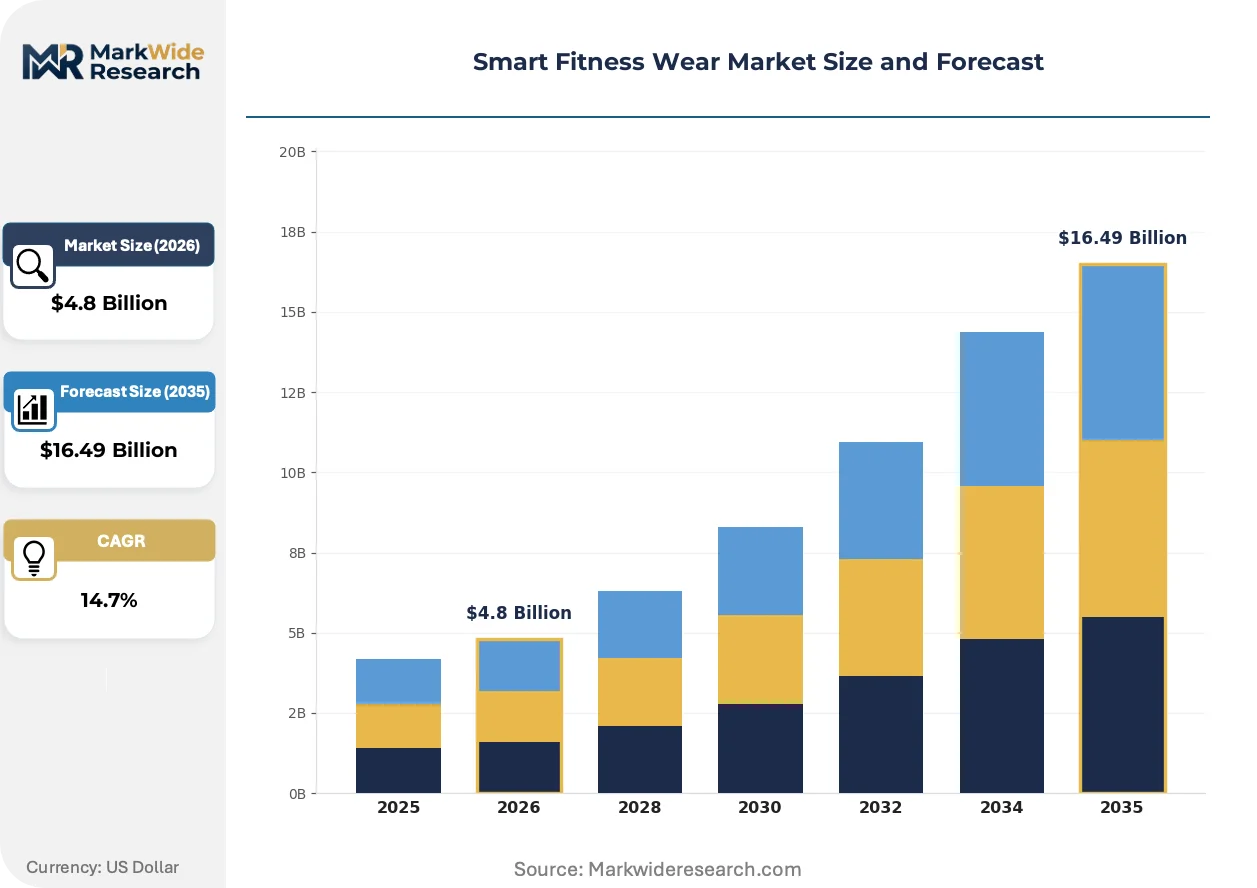
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.49 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Watches, Fitness Trackers, Smart Clothing, Heart Rate Monitors Technology: Wireless Connectivity, GPS, Biometric Sensors, Heart Rate Monitoring End User: Fitness Enthusiasts, Professional Athletes, Casual Users, Trainers Distribution Channel: E-commerce, Specialty Stores, Direct Sales, Retail Chains |
| Companies Covered | Amazfit, Withings, Fitbit, Samsung, Huawei, Garmin, Xiaomi, Google, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fitness Wear Market Strategic Shifts & Innovations
The evolution from simple activity counting to sophisticated health monitoring is the defining trend. This shift is driven by sensor advancements and a growing consumer expectation for actionable insights, pushing wearables into the realm of preventative health and remote patient monitoring.
Advanced biosensing modules, which provide continuous, non-invasive physiological data, are a primary focus of product innovation. Health-conscious consumers and individuals managing chronic conditions are the earliest adopters of this technology. This capability is expanding into the domain of personal health management, blurring the line between consumer electronics and regulated medical instruments.
Regulatory frameworks are adapting to the convergence of wellness and medical technology. The EU's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on any wearable making a medical claim. Consequently, manufacturers aiming for the European clinical market must invest heavily in rigorous validation, altering product roadmaps and go-to-market timelines.
A transition toward subscription-based service models is altering the market's revenue structure. This change disrupts the traditional one-time hardware sale, creating recurring revenue from digital coaching, advanced data analytics, and personalized health reports. This trend is most prominent in North America and Europe, where mature user bases show a willingness to pay for ongoing value beyond the physical device.
Smart Fitness Wear Market Segmentation
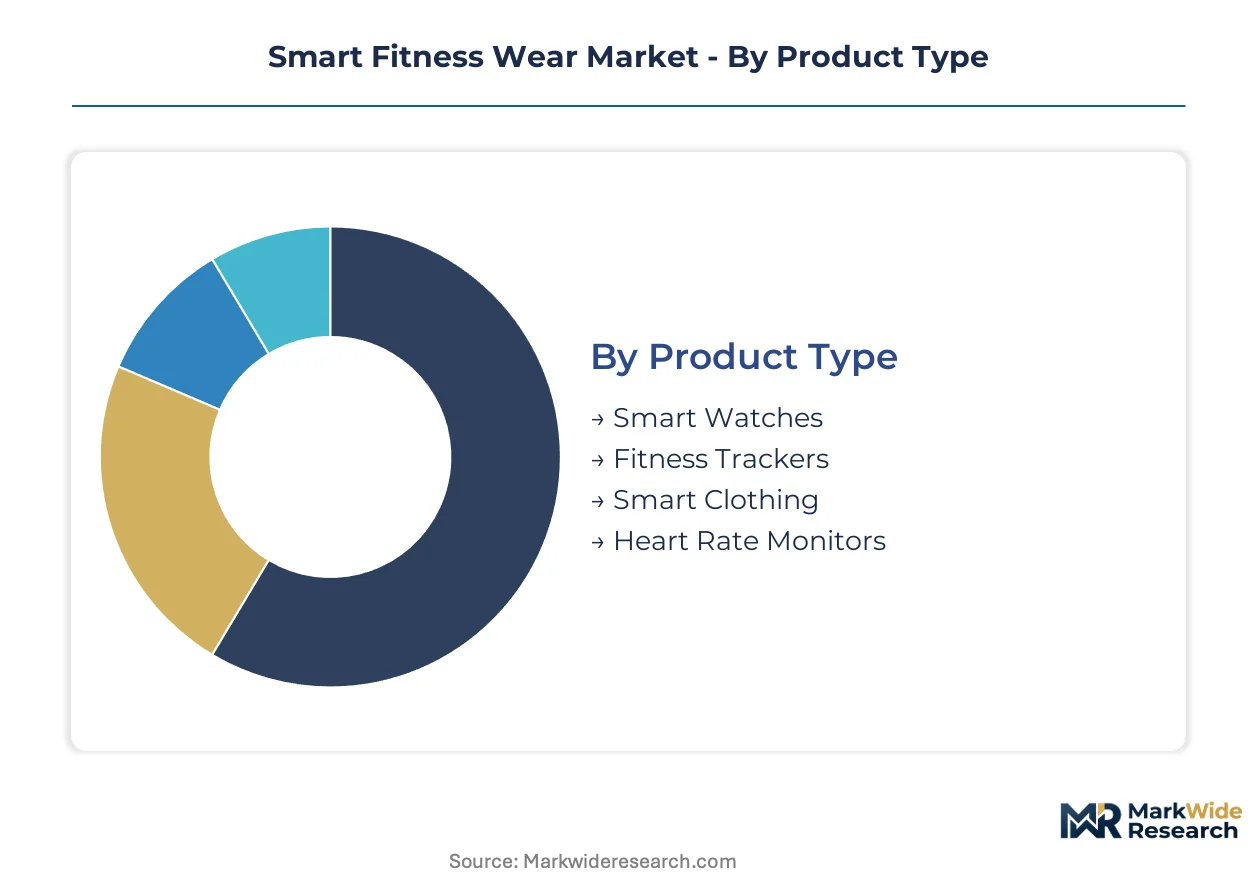
The smart fitness wear market's structure reflects diverse consumer needs and technological capabilities. Understanding these segments is crucial for manufacturers to tailor product development and market strategies effectively. This analysis identifies key divisions within the market, highlighting variations in product functionality, underlying technology, target users, and sales channels.
Product Type:
Buyer preferences in smart fitness wear are primarily differentiated by the form factor and integrated features consumers prioritize for their activity and health monitoring needs.
- Smart Watches:These multi-functional devices integrate advanced biometric tracking with communication and app capabilities, often leveraging extensive digital ecosystems. Demand concentrates among tech-savvy consumers in urban centers who seek comprehensive health and lifestyle management tools.
- Fitness Trackers:Dedicated to activity and sleep monitoring, these devices offer essential metrics in a simpler, often more affordable package compared to smartwatches. Their appeal is strong among first-time users and those prioritizing basic health insights without smartphone integration.
- Smart Clothing:Garments embedded with sensors provide discreet and continuous physiological data, capturing metrics like heart rate or muscle activity directly from the body.
- Heart Rate Monitors:Specialized devices, often chest straps or armbands, deliver highly accurate heart rate data, primarily used by athletes and individuals focused on cardiovascular training.
Volume sits with Fitness Trackers; growth tilts toward Smart Watches.
Technology:
The core technological components determine the capabilities and accuracy of smart fitness wear, influencing product performance and data reliability for various applications.
- Biometric Sensors:These integrated components, such as optical heart rate sensors or accelerometers, collect physiological data directly from the user's body. Innovation in miniaturization and accuracy drives demand for more sophisticated health tracking across all device types.
- Wireless Connectivity:Technologies like Bluetooth and Wi-Fi enable seamless data transfer from the wearable device to smartphones, cloud platforms, or other connected health systems. This capability is essential for real-time monitoring and data analysis, particularly in remote patient care.
- GPS:Global Positioning System modules provide precise location tracking, enabling accurate distance and route mapping for outdoor activities like running, cycling, and hiking.
- Heart Rate Monitoring:This fundamental technology, often optical or electrical, measures cardiac activity, providing crucial data for exercise intensity, recovery, and overall cardiovascular health assessment.
The market's expansion is most significantly driven by advancements in Biometric Sensors, while Wireless Connectivity represents the fastest-growing trajectory in integration.
End User:
Smart fitness wear adoption varies significantly across different user demographics, reflecting diverse motivations from casual wellness to elite athletic performance.
- Casual Users:This broad segment includes individuals seeking basic activity tracking, step counting, and general wellness insights without intensive training goals. The large consumer base in China and India drives significant volume for accessible and user-friendly devices.
- Professional Athletes:Elite sports professionals and teams utilize highly accurate smart wearables for performance optimization, injury prevention, and detailed physiological analysis. Their demand for precision drives innovation in sensor technology and advanced analytics.
- Fitness Enthusiasts:Individuals regularly engaged in sports or gym activities use smart wearables for detailed workout tracking, performance metrics, and progress monitoring.
- Trainers:Fitness coaches and personal trainers leverage smart fitness devices to monitor client progress, tailor exercise programs, and provide data-driven feedback.
The largest user base resides with Casual Users, while Professional Athletes are demonstrating the steepest expansion trajectory in high-end device adoption.
Distribution Channel:
The channels through which smart fitness wear reaches consumers play a critical role in market penetration, influencing brand visibility and purchasing convenience.
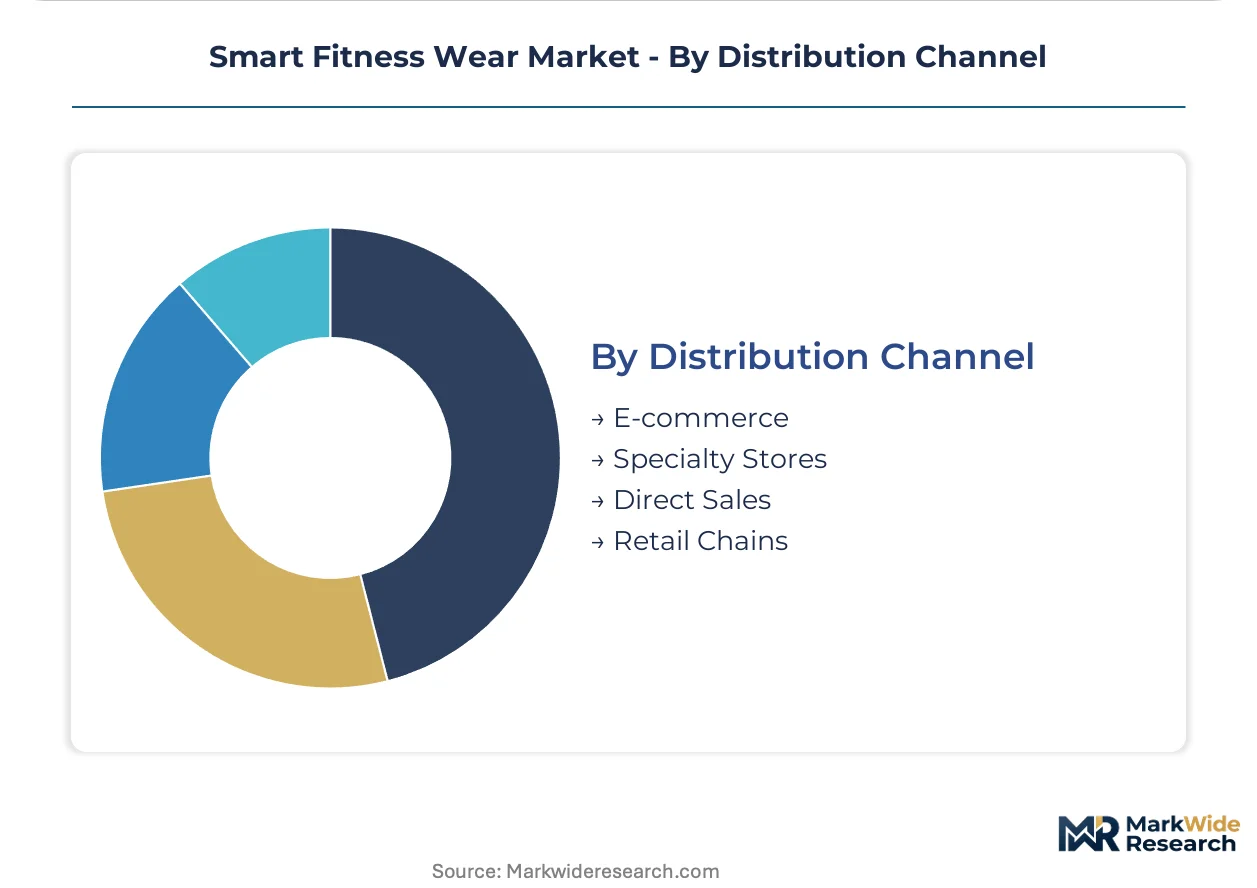
- E-commerce:Online platforms provide extensive product ranges, competitive pricing, and direct-to-consumer models, appealing to tech-savvy buyers and those in less accessible regions. This channel benefits from low overheads and broad geographical reach, particularly in North America and Europe.
- Retail Chains:Large electronics stores and department stores offer physical touchpoints, allowing consumers to experience products firsthand and receive immediate assistance. These chains are crucial for mass-market penetration and brand building among a wider consumer base.
- Specialty Stores:Outlets focused on sports equipment or health products offer expert advice and curated selections, catering to fitness enthusiasts and professional athletes seeking specialized devices.
- Direct Sales:Manufacturers selling directly to consumers through their own websites or dedicated stores provide complete brand control and direct customer relationships, often offering exclusive products.
Market share is predominantly captured by E-commerce, with Retail Chains also showing considerable scaling in product availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for smart fitness wear is particularly notable in China, where government wellness initiatives and a vast consumer base create a highly fertile market. This global market exhibits varied adoption patterns, driven by distinct consumer preferences, regulatory environments, and economic conditions across key countries. Manufacturers must tailor product strategies to address these localized dynamics.
China
Public health campaigns, including the "Healthy China 2030" plan, promote preventative health and physical activity, creating a state-supported user base for fitness tracking technology. The NMPA oversees devices with medical claims, influencing product design and data handling protocols for local manufacturers. The Yangtze River Delta region, particularly around Shanghai and Hangzhou, serves as a hub for smart device manufacturing and consumer electronics innovation.
United States
A broad demographic of casual users, health-conscious consumers, and professional athletes drives demand for sophisticated health tracking. The FDA's guidance on medical devices defines the pathway for clinical-grade features, impacting development timelines for new products. Silicon Valley in California remains a primary center for technology development, attracting significant venture capital for wearable tech startups.
Germany
Health-conscious consumers with high disposable incomes demand advanced and reliable smart fitness wear, often integrating with comprehensive health management systems. Compliance with CE marking requirements and the EU's Medical Device Regulation (MDR) is essential for market entry and product validation. The Munich region in Bavaria is a strong cluster for medical technology and precision engineering, fostering innovation in biosensing modules.
India
Rising health consciousness among a large population presents significant growth opportunities for affordably priced smart fitness devices. BIS standards for electronics and CDSCO regulations for medical devices guide product development and market access. Bengaluru in Karnataka serves as a prominent tech hub, driving software integration and mobile app development for fitness wearables.
Brazil
A large population coupled with increasing awareness of preventative health measures fuels demand for accessible smart fitness solutions. ANVISA oversees health products and medical devices, influencing certification processes for wearables with health claims. The São Paulo metropolitan area functions as a major economic center, facilitating distribution channels and consumer electronics sales for smart fitness wear.
Smart Fitness Wear Market Key Industry Players
North American producers anchor the premium and high-performance tier, while Asian specialists hold a significant share in the volume-driven, accessible segments. The market structure is tiered, reflecting a divergence between consumer-grade wellness devices and medically certified wearables. Strategic archetypes include ecosystem-integrated tech giants, dedicated sports performance brands, and value-focused mass-market providers. Companies are actively pursuing portfolio diversification and geographic expansion to capture new user segments.
Within the ecosystem-integrated tech giants, Apple exemplifies comprehensive health features deeply integrated into its smartwatches, leveraging its powerful digital ecosystem. Garmin occupies a position as a high-performance specialist, catering to dedicated athletes and outdoor adventurers with robust devices. Xiaomi represents the volume-driven accessible segment, competing on price and accessibility to capture a large casual user base.
| Leading Market Players |
|---|
| Amazfit |
| Withings |
| Fitbit |
| Samsung |
| Huawei |
| Garmin |
| Xiaomi |
| Apple |
| Others |
Cost & Logistics Intelligence
Consumer apprehension regarding data privacy and security, governed by regulations like GDPR, forces manufacturers to invest in robust data handling protocols, influencing supply chain choices and the pricing of advanced features.
Pricing Analysis
Volume-driven segments compete on accessibility and affordability, while high-performance devices command premium pricing based on advanced features. Pricing stratifies across premium, standard, and economy tiers, differentiating products by sensor accuracy and ecosystem integration. Downward pricing pressure stems from Xiaomi's strategy of capturing large casual user segments with cost-effective solutions. Professional athletes demonstrate the least price sensitivity, prioritizing performance and data fidelity, while casual users are highly price-sensitive, seeking basic functionality.
Supply Chain Analysis
Workforce availability in manufacturing hubs like China and Vietnam remains critical for scaling production of smart fitness wear. The supply chain relies heavily on specialized component providers for biometric sensors and micro-electromechanical systems. Geopolitical tensions affecting semiconductor supply from Taiwan present a structural risk to device production. Distribution runs through a dual model of e-commerce platforms and established retail chains, ensuring broad market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as stringent regulatory frameworks for medical-grade features force smaller players to exit or specialize.
For Market Incumbents: Acquire advanced biosensing technology companies to enhance clinical-grade feature development. Focus on securing regulatory certifications from bodies like the FDA and NMPA to mitigate the threat of market fragmentation between wellness and medical devices. Invest in robust data security infrastructure to counter consumer data privacy concerns. Deepen ecosystem integration with existing health platforms to create switching costs for users.
For New Entrants and Emerging Players: Develop specialized AI analytics platforms as a technology-first wedge into niche segments. Target underserved geographies like India and Brazil with affordably priced devices that offer essential health monitoring. Partner with corporate wellness programs to establish scalable B2B2C distribution channels. Focus on subscription-based service models for recurring revenue, offering personalized health insights beyond basic device functionality.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to integrate specialized sensor developers or AI-driven health analytics companies. Long-term viability hinges on the ability to navigate diverging regulatory pathways for consumer and medical-grade wearables. An important signal to watch is the approval of new medical claims by regulators like the FDA, indicating market readiness for clinical-grade features.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introduces novel biosensing modules for enhanced health monitoring capabilities. |
| Platform Integration | Ensures seamless data flow between wearables and broader telehealth ecosystems. |
| Strategic Partnership | Leverages medical device expertise for accelerated regulatory compliance in Europe. |
| Acquisition of Specialist Firm | Secures proprietary sensor technology for superior accuracy in athletic performance. |
| Geographic Expansion | Captures new user segments in high-growth markets like India and Brazil. |
Research Approach
Government health reports, technology patents, and financial filings formed the secondary backbone, providing foundational market data. Primary research involved interviews with product managers, R&D engineers, regulatory specialists, and e-commerce managers to gather qualitative insights. This approach combined bottom-up data collection with top-down market sizing for comprehensive validation.
A bottom-up analytical lens informed the market sizing, aggregating data across product type, technology, end user, distribution channel, and key regional markets. This framework modeled growth trajectories over the projection horizon, with CAGRs derived from historical trends and anticipated technological advancements. Industry-specific forecast inputs included sensor miniaturization rates and regulatory approval timelines for medical claims.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts affecting component supply or major data breaches impacting consumer trust. Forecasts reflect assumptions regarding stable economic conditions and consistent regulatory evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
AI Fitness Mirror Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
China Gym Accessories Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Gym Accessories Market