
 Fresh Water Rowing Boats Market | 2026-2036
Fresh Water Rowing Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Water Rowing Boats Market Insights
Maintenance subscription packages for shell refurbishment and rigging calibration is realigning how rowing programs budget capital expenditures. WinTech Racing leverages direct-to-club service networks to sustain recurring revenue from university customers. Empacher anchors its position through German manufacturing scale and Olympic pedigree. Concept2 differentiates by controlling the ergometer-to-shell ecosystem, locking training facilities into integrated fleet ecosystems.
Fresh water rowing boats are narrow, lightweight competitive shells constructed from carbon fiber, fiberglass, or laminated wood composites, designed for propulsion by oars on lakes, rivers, and protected inland waterways with hull beams typically under 60 centimeters to minimize drag. Carbon fiber construction commands the premium tier due to stiffness-to-weight ratios that competitive programs demand, while fiberglass occupies the volume position among scholastic and recreational buyers. Recreational rowing is expanding fastest as aging demographics seek low-impact fitness alternatives, though competitive rowing still captures the majority of margin pools through custom rigging and national-team certification standards.
The EPA regulates volatile organic compound emissions from fiberglass resin applications in US manufacturing facilities, while the EU Green Deal's carbon border adjustments pressure European builders to document supply chain emissions for imported carbon fiber. ISO 12217 small craft stability standards govern hull certification requirements for international competition eligibility. Stakeholders must monitor how evolving sustainability disclosure rules in Europe and North America reshape material sourcing decisions and club procurement timelines.
Market Dynamics
The EU Green Deal's carbon border adjustments are forcing European shell builders to requalify carbon fiber suppliers, compressing procurement timelines while elevating bio-based resin R&D budgets across the competitive fleet segment.
Growth Catalysts
- University fleet modernization:North American collegiate athletic departments are expanding shell procurement to support NCAA rowing program expansion.
- REACH compliance innovation:EU chemical safety mandates are accelerating bio-epoxy formulation development among German and Italian manufacturers.
- Recreational demographic pull:Aging fitness seekers in Scandinavia are driving demand for stable recreational singles and doubles.
Market Restraints
- Carbon fiber supply concentration:Toray and Hexcel dominate aerospace-grade fiber allocation, constraining shell builder access during capacity crunches.
- EPA VOC thresholds:US fiberglass lamination facilities face emission caps that limit batch size economics.
- Rowing machine substitution:Connected ergometers from Concept2 capture training budgets that might otherwise flow to on-water fleet expansion.
Strategic Opportunities
- Club subscription services:Shell refurbishment and rigging calibration packages create recurring revenue streams from cash-constrained university programs.
- Eastern European club formation:Czech and Polish rowing federations are subsidizing equipment grants for emerging competitive programs.
- Recycled carbon fiber integration:Pyrolysis reclamation processes enable price-competitive shells for scholastic entry segments.
Industry Challenges
- Composite technician scarcity:Vacuum infusion and autoclave operation skills concentrate among aging workforces in Bavaria and Connecticut manufacturing clusters.
- ISO 12217 certification lag:Stability testing protocols delay new hull launches by 8-14 months for international competition eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Water Rowing Boats Market |
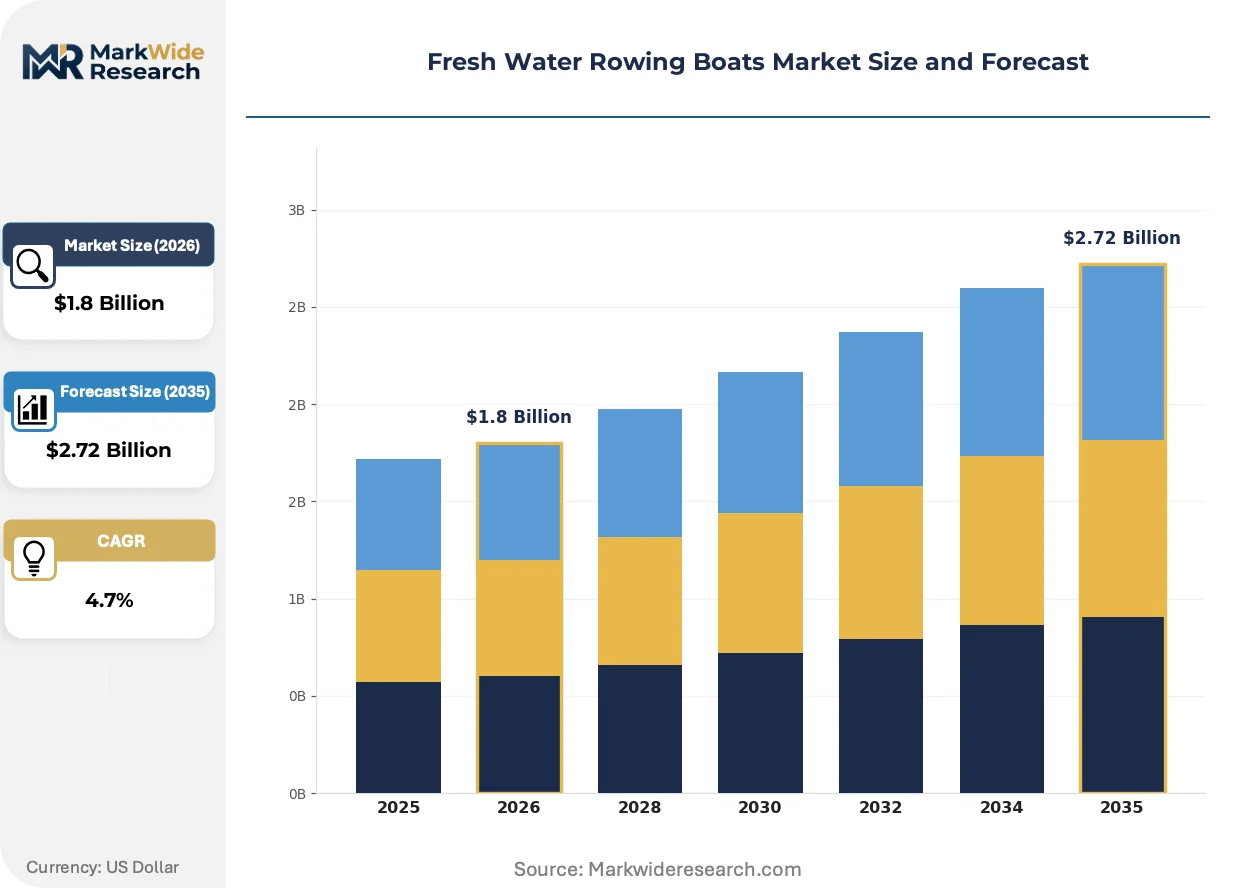
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Single Scull, Double Scull, Quadruple Scull, Eight Material: Fiberglass, Carbon Fiber, Wood, Aluminum Use Case: Competitive Rowing, Recreational Rowing, Training, Touring Size: Small, Medium, Large, Extra Large |
| Companies Covered | WinTech Racing, Empacher, Filippi Boats, Hudson Boat Works, Swift Racing, Vespoli USA, Concept2, Janousek & Stampfli, Durham Boat Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Water Rowing Boats Market Trends and Innovations
Automated manufacturing and sustainability disclosure requirements are compressing traditional build cycles while fragmenting how rowing programs evaluate total cost of ownership across fleet lifecycles.
Robotic fiber placement is automating carbon fiber layup in high-volume shell production, reducing variance in hull stiffness profiles. German and Swiss builders are adopting these systems fastest to maintain Olympic-grade consistency. The technology is automating quality control steps that previously required master craftsmen, compressing skilled labor dependency.
The EU Green Deal's carbon border adjustment mechanism is requiring documented supply chain emissions for imported carbon fiber and epoxy resins. European builders must now obtain third-party verification for Asian-sourced materials or face tariff penalties. Competitive fleet manufacturers in Germany and Italy are responding by qualifying domestic and Turkish fiber suppliers.
After-sales service unbundling is separating shell refurbishment, rigging calibration, and storage from initial purchase contracts. North American university programs are shifting from capital purchase models to multi-year service agreements that smooth budget volatility. This pattern is most visible in the Big Ten and Pac-12 conference athletic departments.
Fresh Water Rowing Boats Market Segmentation
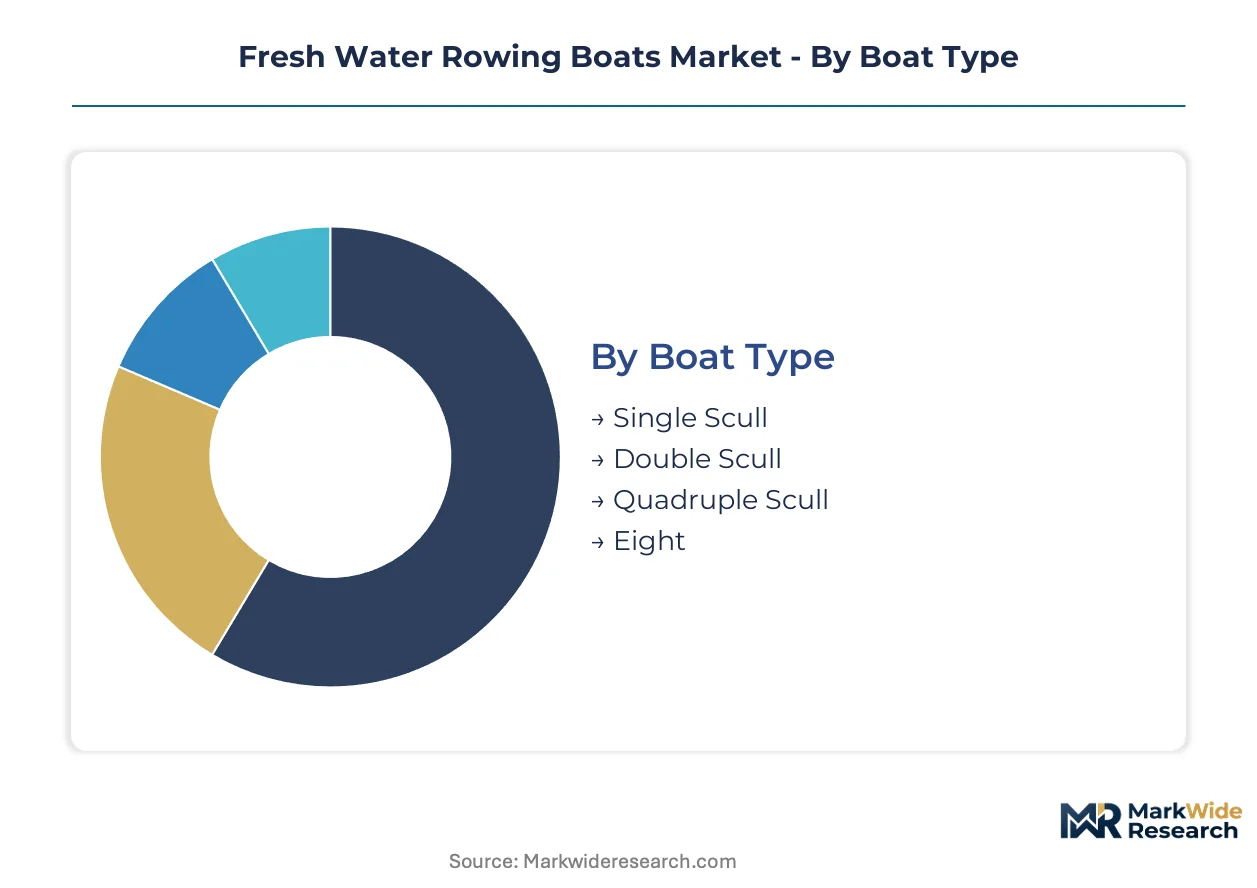
Fresh water rowing boats fragment across four structural dimensions that shape procurement economics and fleet lifecycle costs. Boat type and material composition determine capital intensity, while use case and size govern utilization patterns and replacement cycles across university, club, and recreational buyer segments.
Boat Type:
Capital intensity escalates sharply with crew capacity, as hull length, rigging complexity, and transport infrastructure requirements multiply.
- Single Scull:Narrow hulls under 8.5 meters constructed from carbon fiber or fiberglass composites, designed for individual propulsion with sliding seat mechanisms. Demand concentrates among masters-aged recreational rowers in Germany and aging fitness demographics across Scandinavia seeking low-impact cardiovascular alternatives.
- Double Scull:Tandem shells requiring synchronized stroke mechanics and adjustable rigging geometry for mixed-gender or adaptive crew pairings. North American university programs in the Pac-12 conference prioritize these for novice athlete development and technical skill acquisition before eight-oar transition.
- Quadruple Scull:Four-person sweep shells with coxless configurations demanding precise weight distribution and hull stiffness uniformity. Club formation grants in Poland and the Czech Republic subsidize these for emerging competitive programs building fleet depth.
- Eight:Eight-oar sweep shells exceeding 18 meters in length, representing the pinnacle of competitive fleet investment with custom rigging and national-team certification requirements. German national federation subsidies compress procurement timelines for Bundesliga clubs pursuing Olympic qualification standards.
Eight-oar shells absorb the bulk of installed capacity value; single sculls are expanding most quickly among recreational demographic pull.
Material:
Material selection stratifies across performance tier, certification grade, and budget cycle constraints.
- Carbon Fiber:Aerospace-grade fiber prepregs with autoclave-cured epoxy matrices delivering superior stiffness-to-weight ratios for competitive hulls. REACH compliance mandates in Germany and Italy are accelerating bio-epoxy formulation development among premium tier manufacturers.
- Fiberglass:E-glass and S-glass reinforced polyester or vinyl ester laminations occupying the volume position among scholastic and entry-level club buyers. EPA VOC emission caps constrain batch size economics at Connecticut and Florida manufacturing facilities.
- Wood:Traditional cedar, mahogany, or laminated marine plywood construction persisting in heritage craft and ceremonial fleet segments. Artisan builders in Bavaria and Connecticut clusters maintain limited production for museum and exhibition markets.
- Aluminum:Welded alloy hulls for rental and institutional durability applications where impact resistance outweighs weight penalties. Municipal recreation departments in France and Switzerland specify these for public lake access programs.
Carbon fiber commands the premium tier margin pool; recycled carbon fiber reclamation processes are climbing the fastest among sustainability disclosure pressures.
Use Case:
Use case segmentation governs rigging specification, certification requirements, and service attachment rates.
- Competitive Rowing:FISA-compliant shells with ISO 12217 stability certification, custom rigging geometry, and national-team equipment standards. German and Italian builders anchor supply through Olympic pedigree and manufacturing scale.
- Recreational Rowing:Stable hull forms with wider beams and fixed-seat options for non-athletic fitness seekers. Aging demographics across Denmark and Sweden drive steepest expansion trajectory in this category.
- Training:Durable construction prioritizing impact resistance and simplified maintenance over weight minimization. University athletic departments in the Big Ten conference prioritize these for novice squad development.
- Touring:Self-bailing designs with storage compartments and stability-optimized hull profiles for multi-hour inland waterway expeditions. Austrian and Swiss alpine lake operators specify these for guided excursion fleets.
Competitive rowing captures the majority of margin pools through custom specification; recreational rowing is gaining share fastest among demographic tailwinds.
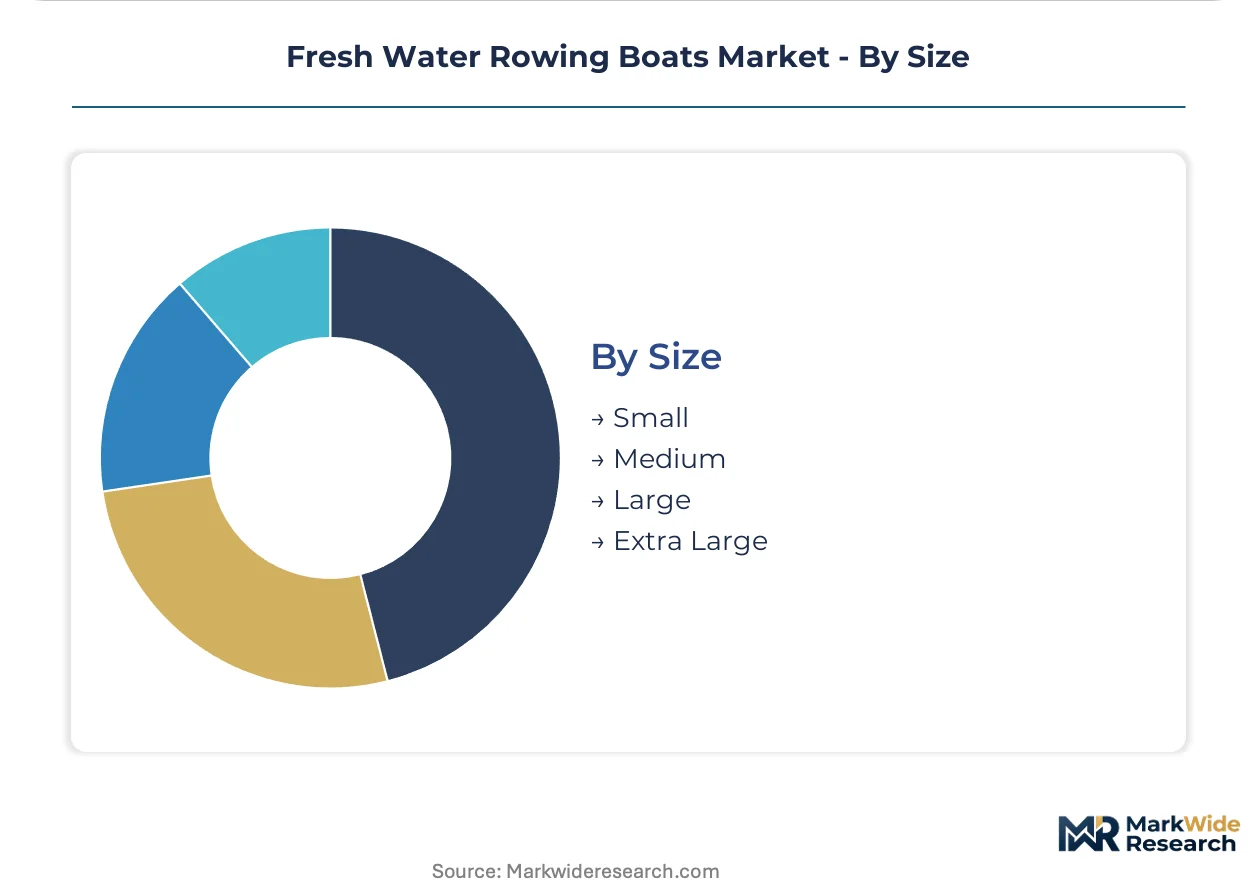
Size:
Size classification correlates with transport logistics, storage infrastructure, and crew scalability requirements.
- Small:Single and double sculls under 9 meters, trailer-transportable by standard vehicles without specialized permitting. Individual owners and small clubs across the Netherlands favor these for flexible fleet management.
- Medium:Quadruple sculls and coxed fours requiring extended trailers and dedicated boathouse bay dimensions. Regional training centers in Bavaria standardize on this footprint for program scalability.
- Large:Coxless fours and lightweight eights demanding specialized transport vehicles and crane-assisted launching infrastructure. National training centers in Germany and the UK concentrate procurement here.
- Extra Large:Heavyweight eights and adaptive rowing platforms with reinforced hull structures for mixed-ability crew accommodation. Paralympic program subsidies in Italy and France support limited production runs.
Medium-size shells dominate club procurement volumes; small-size configurations are expanding most quickly among aging recreational adopters seeking storage simplicity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oberbayern's carbon fiber manufacturing corridor around Lake Starnberg anchors competitive shell production, with Empacher and other Bavarian builders supplying Olympic-grade equipment to federations worldwide. This industrial concentration shapes procurement patterns across three continents.
Germany
The German Rowing Federation subsidizes Bundesliga club equipment upgrades, compressing replacement cycles for eight-oar shells. REACH compliance mandates from ECHA accelerate bio-epoxy formulation development among Bavarian manufacturers. The Lake Starnberg corridor concentrates autoclave-cured carbon fiber production for competitive fleets.
United States
NCAA rowing program expansion drives fleet procurement across Big Ten and Pac-12 athletic departments. EPA VOC emission caps constrain batch size economics at Connecticut and Florida lamination facilities. The Connecticut River Valley cluster maintains heritage wood composite craftsmanship alongside modern fiberglass production.
Italy
Paralympic program subsidies support limited production runs of adaptive rowing platforms for mixed-ability crews. ECHA chemical safety regulations push Italian builders toward domestic fiber qualification under EU Green Deal carbon border adjustments. The Lake Como region hosts specialist touring shell fabricators serving alpine lake operators.
United Kingdom
The national training center at Caversham concentrates procurement of large-format shells for Olympic qualification programs. ISO 12217 stability certification requirements delay new hull launches by 8-14 months for international competition eligibility. The Thames Valley corridor maintains traditional boatbuilding expertise alongside composite innovation.
Poland
Club formation grants from the national rowing federation subsidize quadruple scull procurement for emerging competitive programs. EU Green Deal supply chain documentation requirements pressure builders to verify emissions for imported carbon fiber. The Greater Poland Voivodeship hosts expanding composite manufacturing capacity for scholastic entry segments.
Fresh Water Rowing Boats Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models. The vendor base stratifies into three tiers: Olympic-pedigree specialists commanding premium pricing through national-team certification, volume-positioned scholastic suppliers optimizing fiberglass batch economics, and integrated training equipment providers locking facilities into ecosystem dependencies. Consolidation pressure concentrates among Bavarian and Connecticut manufacturing clusters where composite technician scarcity elevates acquisition premiums. Dominant competitive moves include backward integration into carbon fiber reclamation processes and geographic expansion through direct-to-club service networks.
Within the Olympic-pedigree tier, Empacher GmbH and Filippi Boats exemplify manufacturing-scale defenders leveraging autoclave-cured production and federation relationships to sustain pricing power. WinTech Racing occupies a position among North American volume suppliers, while Concept2 anchors the integrated training equipment archetype through ergometer-to-shell ecosystem control. These three represent distinct strategic postures: certification-grade premium positioning, scholastic market scale optimization, and vertical training platform integration.
| Leading Market Players |
|---|
| WinTech Racing |
| Empacher |
| Filippi Boats |
| Hudson Boat Works |
| Swift Racing |
| Vespoli USA |
| Concept2 |
| Janousek & Stampfli |
| Durham Boat Company |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's carbon border adjustment mechanism gates qualified supply access for European shell builders while simultaneously compressing premium-tier pricing power through documented emissions verification requirements. Builders lacking third-party-certified fiber sources face tariff penalties that disqualify them from Bundesliga club procurement, effectively bifurcating the market between compliant and non-compliant supply tiers.
Pricing Analysis
Olympic-grade hull stiffness consistency anchors value-based pricing for competitive eight-oar shells, with German and Italian manufacturers commanding substantial premiums through FISA certification and national-team pedigree. Three-tier pricing structure across premium carbon fiber, standard fiberglass, and economy recycled composite levels stratifies buyer segments, with university athletic departments exhibiting highest price sensitivity due to capital budget volatility while national training centers demonstrate lowest sensitivity given federation subsidy coverage. Cost compression in the fiberglass tier is intensifying as EPA VOC caps constrain Connecticut and Florida batch economics, forcing volume-positioned suppliers to absorb compliance costs or cede share to imports.
Supply Chain Analysis
Shell refurbishment and rigging calibration networks are creating reverse-logistics revenue streams that extend fleet lifecycles and compress replacement demand timing for original equipment manufacturers. Aerospace-grade carbon fiber supply concentrates in Japan, the United States, and Germany, with Toray and Hexcel allocations constraining builder access during capacity crunches. Raw material dependencies rest on epoxy resin formulations, autoclave-cured prepregs, and bio-based alternative feedstocks. Single-source vulnerability in aerospace fiber allocation represents the dominant structural risk. Distribution runs through direct-to-club service networks for premium tiers and regional dealer channels for scholastic entry segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over carbon fiber reclamation processes and captive refurbishment capacity determines margin sustainability. Players securing pyrolysis-based recycled fiber supply and multi-year university service agreements are building structural advantages that transactional competitors cannot replicate.
For Market Incumbents: Lock in federation relationships through extended equipment certification partnerships that embed shells into Olympic qualification pathways. Acquire distressed composite manufacturing capacity in Eastern European clusters to preempt emerging competitor formation subsidized by Polish and Czech rowing federations. Connected ergometer ecosystems from integrated training equipment providers threaten to capture capital budgets that would otherwise flow to on-water fleet expansion.
For New Entrants and Emerging Players: Begin with recreational singles and doubles targeting aging Scandinavian fitness demographics where stability-optimized hull forms face minimal certification barriers and brand loyalty remains unformed. The masters-aged recreational segment in Denmark and Sweden offers the most penetrable entry point. A direct-to-consumer digital configuration platform with seasonal storage bundling provides differentiated go-to-market positioning against established dealer networks.
For Investors and Strategic Acquirers: Bavarian composite technician retirement waves accelerating to 15% annual turnover is the leading indicator that manufacturing-scale defenders will face acute capability scarcity and elevated acquisition premiums. Long-term viability over the next decade favors asset-light designers with proprietary hull geometry IP over capital-heavy autoclave operators facing workforce replacement costs. Target acquisition archetypes include regional refurbishment service networks with embedded university relationships and bio-epoxy formulation specialists with REACH-compliant product pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Reclamation Integration | Pyrolysis-based recycled fiber supply secures price-competitive positioning for scholastic entry segments under EU Green Deal pressure. |
| Direct-to-Club Service Network Expansion | Multi-year refurbishment and rigging calibration agreements smooth university budget volatility and create recurring revenue streams. |
| Bio-Epoxy Formulation Development | REACH-compliant resin systems from German and Italian manufacturers unlock continued access to European competitive fleet procurement. |
| Eastern European Manufacturing Footprint | Polish and Czech club formation grants subsidize equipment demand that localized production can capture with reduced logistics costs. |
| Integrated Training Equipment Ecosystem | Ergometer-to-shell platform control locks training facilities into proprietary fleets that resist competitive displacement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with shell manufacturing plant managers, university athletic procurement directors, rowing club equipment officers, and composite materials R&D leads. FISA equipment certification databases, EPA air quality compliance reports, ECHA REACH substance registrations, and German Rowing Federation subsidy disbursement records provided secondary validation. Bottom-up triangulation across boat type, material composition, and use case segments converged with top-down macroeconomic demand modeling.
Granularity-level modeling disaggregated volume and value outputs across single scull, double scull, quadruple scull, and eight-oar configurations; carbon fiber, fiberglass, wood, and aluminum material tiers; and competitive, recreational, training, and touring use cases. CAGRs were derived from replacement cycle analysis, fleet expansion patterns, and demographic penetration curves. Forecast inputs incorporated NCAA program expansion trajectories, EU Green Deal compliance cost pass-through assumptions, and recreational demographic adoption rates across Scandinavian markets.
Federation subsidy discontinuation, aerospace fiber allocation shocks, and bio-resin performance validation failures are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding sustained regulatory pressure on supply chain emissions documentation and stable university athletic department capital allocation priorities. Practitioners should monitor ECHA substance restriction proposals, Toray capacity expansion announcements, and German federal sport budget appropriations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Agility Ladders Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Padel Balls Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Gymnastic Bars Market