
 Sports Eyewear Market | 2026-2036
Sports Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Eyewear Market Outlook
ANSI Z87.1 certification is rotating the competitive set by filtering out suppliers lacking industrial-grade impact testing infrastructure. EssilorLuxottica leverages its captive lens laboratories to fast-track compliance across multiple sport categories. Oakley anchors its position through proprietary Plutonite lens chemistry that exceeds baseline impact thresholds. Nike, Inc. competes by embedding prescription-ready architectures into performance frames, broadening addressable user pools.
Sports eyewear denotes purpose-built optical devices engineered with shatter-resistant substrates, UV-blocking coatings, and aerodynamic frame geometries to protect vision and enhance visual acuity during high-velocity or high-glare athletic activity. Polycarbonate lenses dominate volume production due to their superior strength-to-weight ratio and inherent UV absorption across the 280-400 nanometer spectrum. Goggles capture the fastest expansion trajectory within product types, driven by snowsport and motocross participation where full-seal designs prevent particulate intrusion. Cycling applications concentrate margin pools in premium photochromic and prescription-integrated configurations where technical complexity limits commoditization.
The U.S. Food and Drug Administration classifies prescription sports lenses as medical devices, imposing quality system regulations that elevate manufacturing barriers for new entrants. The EU PPE Regulation mandates CE marking and third-party conformity assessment for eye protectors sold across member states, redirecting R&D budgets toward certification documentation. ASTM International and ISO 12312-1 standards further fragment compliance requirements by geography, compelling multinationals to maintain parallel testing protocols. Stakeholders must monitor convergence between fashion eyewear distribution channels and specialty sporting goods retail, as this channel overlap determines which brands capture casual fitness enthusiasts migrating toward performance-grade equipment.
Market Dynamics
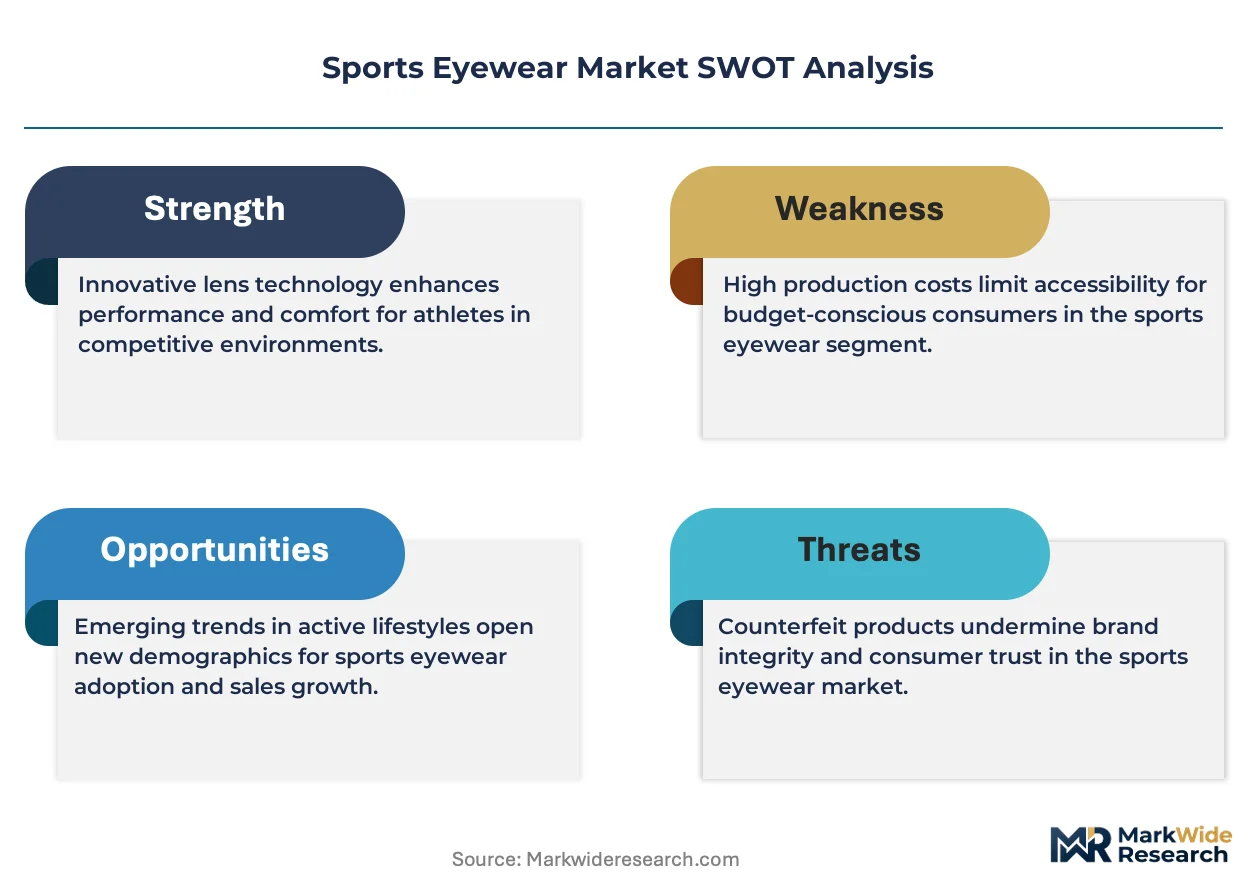
The Sports Eyewear Market is undergoing structural compression as certification mandates from ANSI Z87.1 and EU PPE Regulation force capital reallocation toward impact-testing infrastructure, filtering out suppliers lacking laboratory scale while concentrating volume among vertically integrated lens manufacturers.
Growth Catalysts
- ANSI Z87.1 Compliance Thresholds:Updated impact-resistance standards in the United States are eliminating marginal suppliers and redirecting procurement toward certified manufacturers with captive testing facilities.
- German Cycling Infrastructure:Federal investment in dedicated bike lanes and amateur racing league expansion is sustaining dual-season equipment turnover for photochromic and prescription-integrated configurations.
- Polycarbonate Substrate Advances:Superior strength-to-weight ratios and inherent UV absorption across the 280-400 nanometer spectrum are cementing this material's dominance in high-velocity athletic applications.
Market Restraints
- Petrochemical Input Volatility:Polycarbonate resin prices fluctuate with benzene and bisphenol-A feedstock markets, compressing margin stability for mid-tier frame assemblers.
- FDA Medical Device Classification:Prescription sports lenses fall under quality system regulations that elevate manufacturing barriers and extend new entrant timelines by 18-24 months.
- Fragmented Standardization:Parallel compliance requirements across ASTM International, ISO 12312-1, and EU PPE Regulation force multinationals to maintain redundant testing protocols.
Strategic Opportunities
- Prescription-Ready Architecture:Embedded Rx compatibility in performance frames is broadening addressable user pools beyond traditional contact lens wearers in cycling and snowsport segments.
- Goggle Category Expansion:Full-seal designs for snowsport and motocross participation are capturing the fastest product-type trajectory as particulate intrusion prevention becomes non-negotiable.
- Channel Convergence:Fashion eyewear distribution networks are overlapping with specialty sporting goods retail, creating capture potential for brands targeting casual fitness enthusiasts migrating toward performance-grade equipment.
Industry Challenges
- Certification Documentation Burden:CE marking and third-party conformity assessment under EU PPE Regulation are redirecting R&D budgets away from product innovation toward regulatory paperwork.
- Multi-Protocol Testing Infrastructure:Geographically fragmented standards require simultaneous maintenance of ANSI, ISO, and ASTM testing capabilities, straining capital allocation for regional specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Eyewear Market |
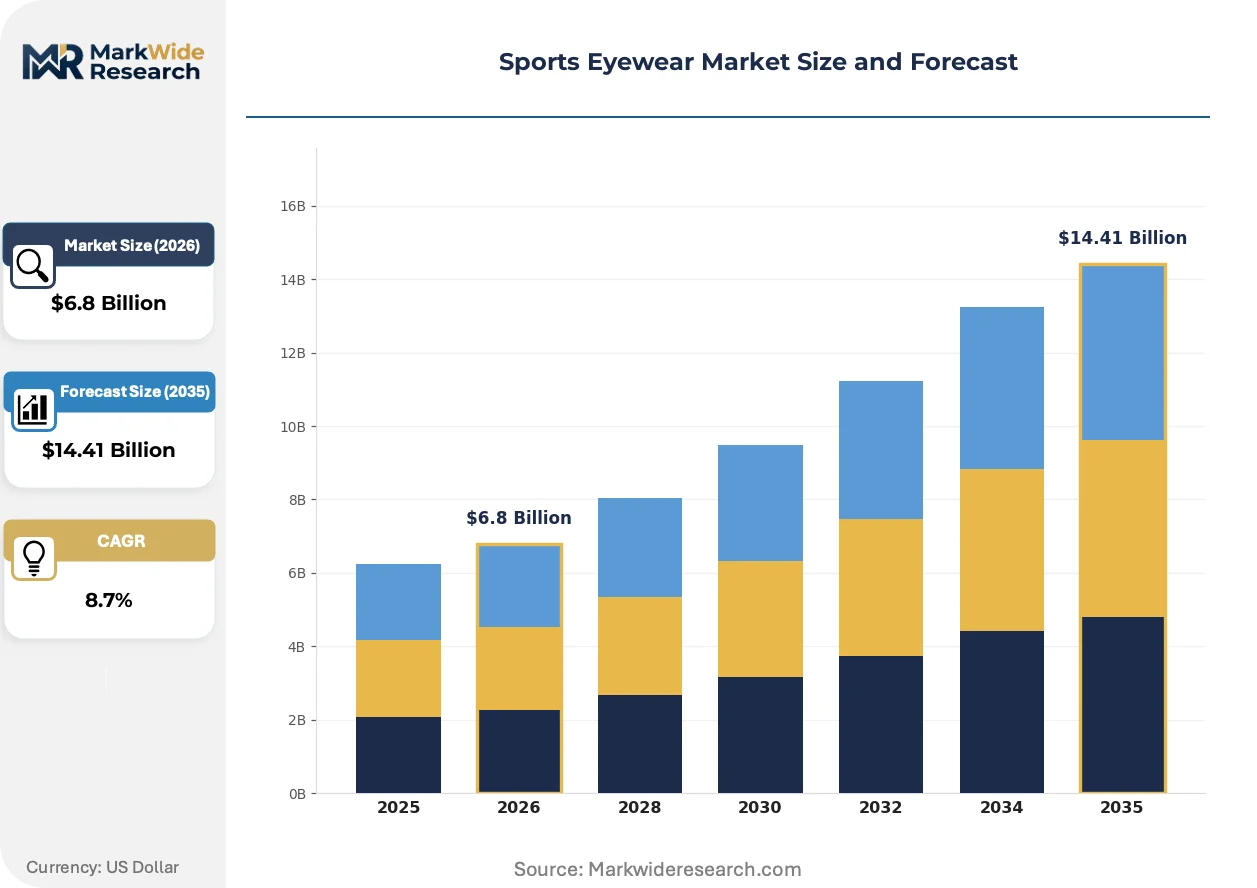
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glasses, Goggles, Sunglasses, Visors Application: Running, Cycling, Swimming, Skiing End User: Athletes, Coaches, Casual Users, Fitness Enthusiasts Material: Polycarbonate, Nylon, Glass, TR90 |
| Companies Covered | EssilorLuxottica, Nike, Inc., Adidas AG, Oakley, Under Armour, Inc., Safilo Group, Smith Optics, Maui Jim, ZEISS Vision Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Eyewear Market Strategic Shifts
Material science breakthroughs and regulatory convergence are actively compressing the competitive set in sports eyewear, as lens chemistry and frame architecture evolve faster than distribution channels can absorb premium positioning.
Photochromic lens technology is displacing fixed-tint configurations in cycling and running segments. Amateur racing leagues and recreational clubs in Germany and the United States are adopting variable-transmission optics at replacement cycles of 18-24 months. This shift is compressing inventory turns for retailers holding static SKU depth and forcing manufacturers to integrate faster activation chemistry into base lens platforms.
EU PPE Regulation mandates are tightening third-party conformity assessment protocols for eye protectors sold across member states. Industrial-grade impact testing infrastructure is becoming a prerequisite for market access rather than a premium differentiator. Snowsport and motocross goggle manufacturers are responding by consolidating supply relationships with laboratories holding dual ANSI Z87.1 and CE marking accreditation.
Specialty sporting goods retail is losing exclusive custody of performance-grade equipment as fashion eyewear chains expand athletic product lines. Casual fitness enthusiasts in urban clusters are purchasing photochromic cycling glasses through optometry channels that previously ignored sport-specific SKUs. This channel migration is most visible in German metropolitan markets where cycling infrastructure investment has normalized commuter use of performance frames.
Sports Eyewear Market Segmentation
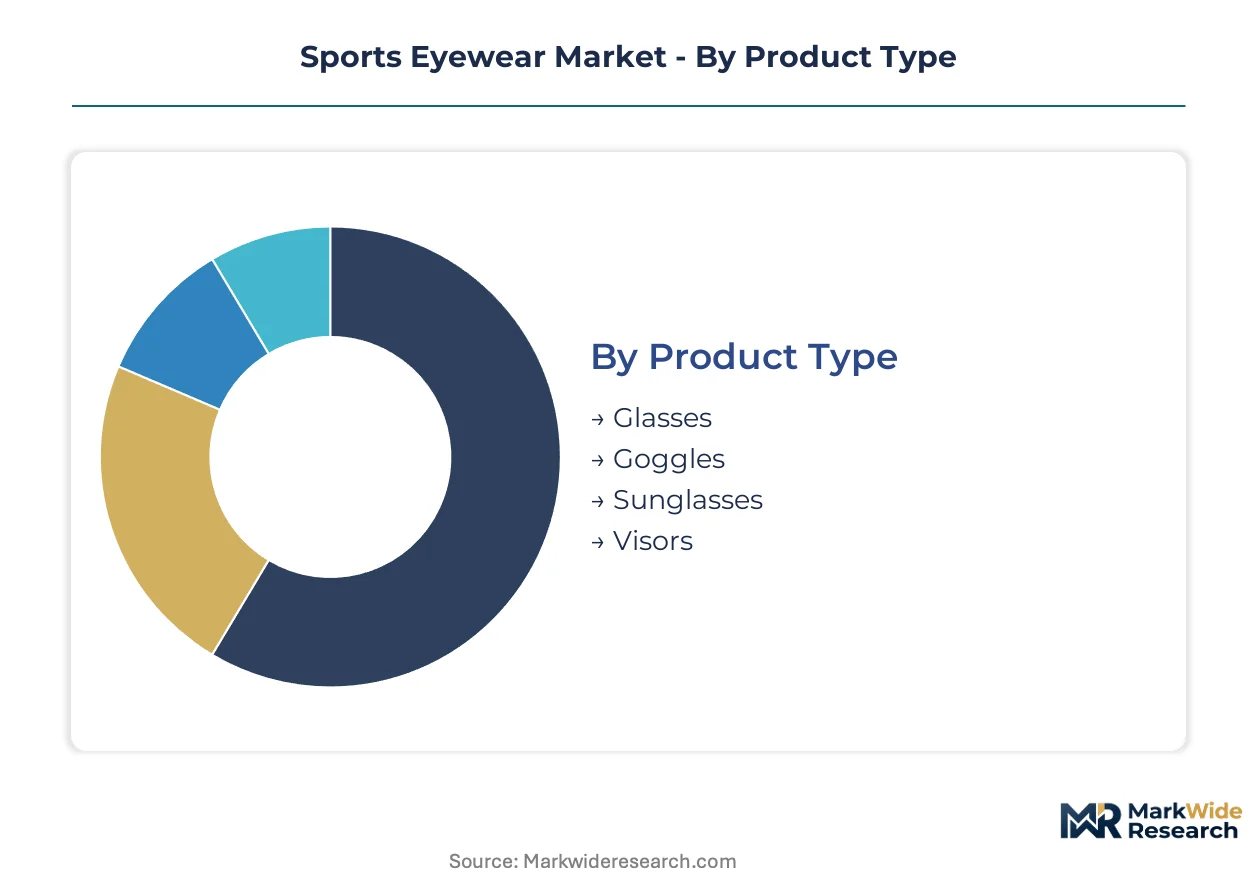
Sports eyewear segmentation determines which technical specifications unlock premium pricing versus mass-market volume. Regulatory compliance tiers, material science thresholds, and end-user athletic intensity create divergent margin structures across each dimension.
Product Type:
ANSI Z87.1 and EU PPE Regulation certification requirements split this category between industrial-grade impact testing and consumer-grade optical standards.
- Goggles:Full-seal designs with dual-lens thermal barriers and anti-fog coatings dominate snowsport and motocross applications. German ski tourism infrastructure and amateur racing league expansion sustain replacement cycles for particulate-intrusion prevention systems.
- Glasses:Aerodynamic frame geometries with prescription-ready architectures capture cycling club procurement in Germany and the United States. Photochromic lens integration elevates technical complexity beyond fixed-tint commoditization.
- Sunglasses:UV-blocking coatings across 280-400 nanometer spectrum serve running and casual fitness segments with lighter certification burdens.
- Visors:Helmet-integrated designs concentrate in motorsport and elite cycling team equipment with limited retail distribution.
Established volume favors Glasses; emerging adoption favors Goggles.
Application:
Cost tier differentiation separates medical-device-classified prescription configurations from over-the-counter protective equipment.
- Cycling:Federal infrastructure investment in Germany and United States metropolitan clusters sustains dual-season equipment turnover. Photochromic and prescription-integrated configurations command premium positioning through FDA quality system regulation compliance.
- Skiing:EU PPE Regulation mandates CE marking for snowsport eye protectors sold across member states. Full-seal goggle designs with impact-resistant substrates dominate alpine and Nordic disciplines.
- Running:Lightweight polycarbonate frames with fixed-tint UV absorption serve recreational road and trail segments at lower certification thresholds.
- Swimming:Hydrodynamic gasket seals with anti-fog chemistry address pool and open-water participation with specialized hydrodynamic requirements.
Margin concentration sits with Cycling; volume scale favors Running.
End User:
Customer type determines whether procurement flows through specialty sporting goods retail or converging fashion eyewear channels.
- Athletes:Amateur racing leagues and professional team equipment managers demand ANSI Z87.1-certified impact resistance with prescription integration capabilities.
- Fitness Enthusiasts:Casual urban commuters in German metropolitan markets purchase photochromic cycling glasses through optometry channels previously ignoring sport-specific SKUs.
- Coaches:Institutional procurement for training facility equipment prioritizes durability and multi-user sanitization protocols over individual fit customization.
- Casual Users:Fashion eyewear chain expansion into athletic product lines captures this segment migrating toward performance-grade equipment without specialty retail engagement.
Technical specification intensity peaks with Athletes; channel migration velocity peaks with Casual Users.
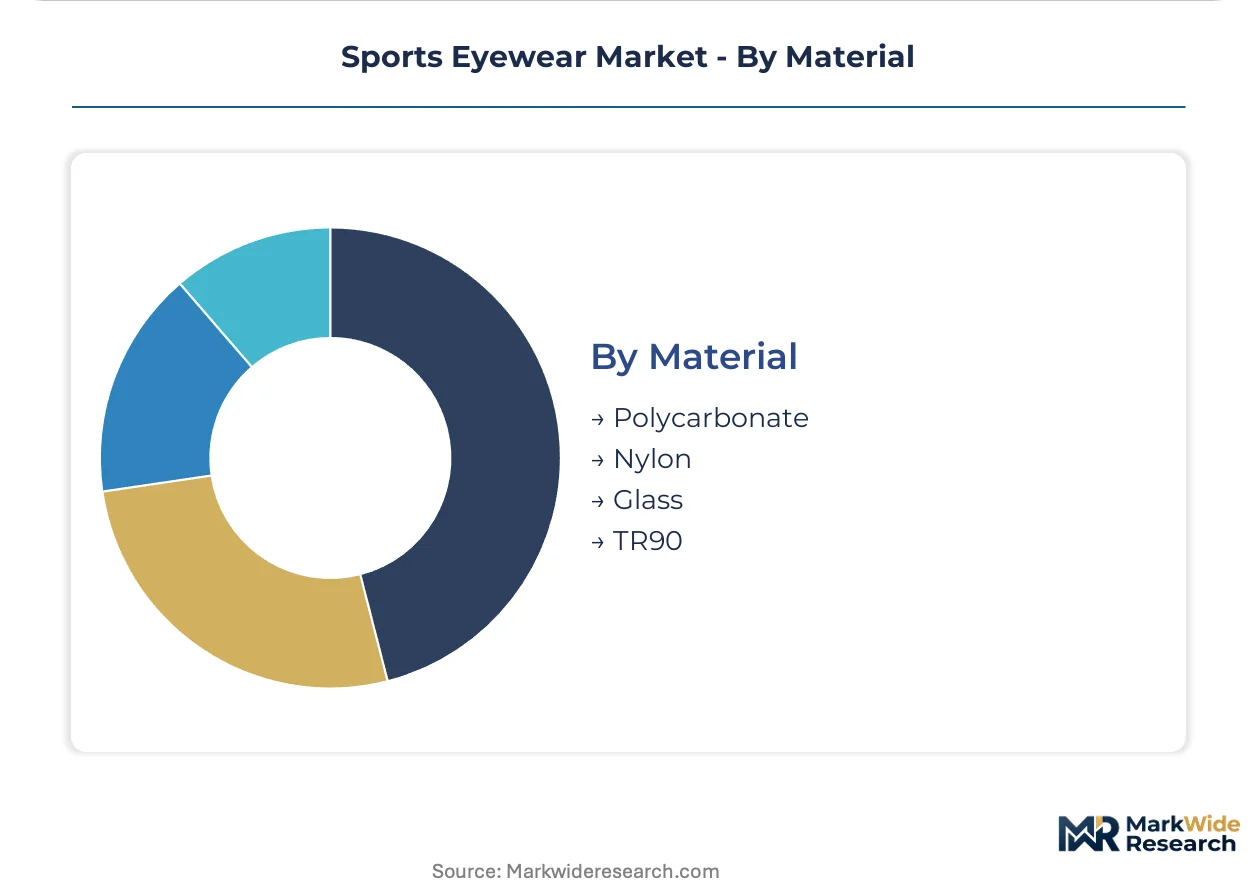
Material:
Supply concentration in petrochemical feedstock markets creates margin volatility differentiated by substrate processing complexity.
- Polycarbonate:Superior strength-to-weight ratios and inherent UV absorption cement dominance in high-velocity athletic applications. Benzene and bisphenol-A price fluctuations compress stability for mid-tier frame assemblers dependent on external resin supply.
- TR90:Thermoplastic polyamide with memory-flex properties serves premium frame architectures requiring repeated deformation recovery without structural fatigue.
- Nylon:Cost-optimized injection molding substrate for mass-market frame production with lower impact resistance thresholds.
- Glass:Optical clarity superiority in prescription lens applications offset by weight penalties and shatter-risk limitations in contact sports.
Volume manufacturing gravitates toward Polycarbonate; premium flexibility demands favor TR90.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal cycling infrastructure programs and EU PPE Regulation harmonization are redrawing procurement maps across major economies, concentrating equipment turnover in markets with dedicated lane networks and stringent conformity assessment protocols.
United States
Metropolitan cycling club expansion in Colorado and California sustains demand for ANSI Z87.1-certified photochromic configurations. FDA quality system regulations for prescription sports lenses extend manufacturing timelines for new market entrants. The Pacific Northwest cluster around Portland and Seattle anchors dual-season turnover through integrated commuter-racing equipment procurement.
Germany
Federal transport ministry investments in Rhine-Ruhr and Bavarian bike lane networks sustain amateur racing league equipment replacement cycles. EU PPE Regulation mandates CE marking with third-party conformity assessment for all eye protectors sold across member states. The Munich-Stuttgart corridor concentrates premium frame assembly operations serving alpine and Nordic ski tourism infrastructure.
China
Domestic motocross participation growth and winter sport facility construction in Heilongjiang and Jilin provinces expand goggle category demand. GB standards administered by SAMR impose parallel testing requirements for impact-resistant substrates. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou dominates polycarbonate lens substrate production for export markets.
Japan
METI-sponsored urban mobility initiatives in Tokyo and Osaka metropolitan areas normalize commuter cycling with performance-grade protective equipment. JIS standards for optical devices create certification overlap with ISO 12312-1 requirements. The Chubu region around Nagoya hosts precision molding operations serving domestic cycling team equipment procurement.
Australia
State-level cycling infrastructure programs in New South Wales and Victoria sustain club-level racing equipment turnover through photochromic lens adoption. TGA medical device classification for prescription lenses elevates manufacturing barriers equivalent to FDA protocols. The Melbourne-Geelong corridor anchors specialty retail distribution for snowsport goggle imports serving domestic alpine tourism.
Sports Eyewear Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure, as publicly traded optical conglomerates with captive laboratory networks face independent frame assemblers dependent on external testing facilities. Market structure tilts toward consolidated lens chemistry and fragmented frame architecture, with three archetypes dominating: vertically integrated optical conglomerates controlling substrate-to-retail pipelines, sport-specialist brands anchored in single-category technical positioning, and fashion-luxury houses extending athletic product lines through licensed distribution. Competitive moves concentrate on laboratory accreditation expansion for dual ANSI-CE marking and prescription-ready architecture integration.
Among vertically integrated optical conglomerates, EssilorLuxottica and Safilo Group occupy positions defined by captive lens laboratory networks and multi-brand portfolio architecture. Oakley exemplifies the sport-specialist archetype through proprietary substrate chemistry and category-exclusive technical positioning. These three entities represent the competitive tension between scale-driven certification throughput and technical specialization in high-velocity athletic applications.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Nike, Inc. |
| Adidas AG |
| Oakley |
| Under Armour, Inc. |
| Safilo Group |
| Smith Optics |
| Maui Jim |
| ZEISS Vision Care |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for polycarbonate resin feedstock compress margin flexibility for mid-tier frame assemblers, concentrating pricing power with vertically integrated manufacturers holding captive lens laboratories and dual-certification testing infrastructure. The interplay between petrochemical input volatility and certification documentation burdens forces capital allocation trade-offs that stratify competitive positioning across compliance tiers.
Pricing Analysis
Certification level creates the primary spread between premium ANSI Z87.1-plus-CE dual-marked configurations and single-standard consumer-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA medical device classification thresholds, prescription-ready architecture complexity, and after-sales service bundling. Cost compression in mid-tier polycarbonate frames intensifies because benzene and bisphenol-A feedstock markets transmit volatility directly to resin-dependent assemblers. Amateur racing leagues and cycling clubs exhibit lowest price sensitivity due to procurement prioritizing impact-resistance documentation over unit economics.
Supply Chain Analysis
Yangtze River Delta polycarbonate substrate production anchors global lens manufacturing, with secondary concentration in the Chubu region around Nagoya for precision molding operations. Raw material flows draw from benzene crackers in South Korea and Saudi Arabia, bisphenol-A facilities in China and the United States, and specialty coating chemistries from German industrial suppliers. Single-source vulnerability concentrates in dual ANSI-CE accredited testing laboratories, where limited laboratory scale creates queue bottlenecks for new product qualification. Distribution runs through specialty sporting goods retail converging with fashion eyewear chains and optometry channels serving prescription-integrated demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sports eyewear market sits in a cyclical recovery phase as federal cycling infrastructure investment and amateur racing league expansion restock equipment inventories depleted during prior participation troughs.
For Market Incumbents: Compound laboratory accreditation advantages by acquiring regional testing facilities in Germany and the United States to eliminate third-party queue dependencies. Backward integration into polycarbonate resin compounding buffers margin pressure from petrochemical volatility. Priority investment targets captive prescription lens processing capabilities to defend against Nike and Adidas embedding Rx architectures into performance frames. For New Entrants and Emerging Players: Anchor in the goggle category expansion trajectory where snowsport and motocross participation growth outpaces incumbent capacity addition. White-space concentration sits with full-seal designs for Asian winter sport facility construction and Latin American motocross league formation. Go-to-market execution should leverage direct-to-cyclist digital channels bypassing specialty retail gatekeepers in German metropolitan markets. For Investors and Strategic Acquirers: Long-term, this sits as a certification-infrastructure play because regulatory convergence between ANSI Z87.1 and EU PPE Regulation creates durable competitive moats around accredited testing networks. Acquisition target archetype: mid-tier frame assemblers with established distribution relationships but lacking captive lens laboratories, where certification investment unlocks premium tier access. Signal to watch is queue length at dual-accredited testing laboratories as indicator of supply-constrained pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Accreditation Expansion | Dual ANSI-CE marking capability eliminates third-party conformity assessment bottlenecks for EU market access. |
| Prescription-Ready Architecture Integration | Embedded Rx compatibility broadens addressable user pools beyond contact lens wearers in cycling segments. |
| Photochromic Chemistry Investment | Faster activation speeds capture replacement cycles from amateur racing leagues adopting variable-transmission optics. |
| Channel Convergence Exploitation | Fashion eyewear distribution partnerships capture casual fitness enthusiasts migrating toward performance-grade equipment. |
| Raw Material Backward Integration | Captive polycarbonate resin compounding insulates margin stability from benzene and bisphenol-A price fluctuations. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with product development directors at optical conglomerates, certification laboratory managers, specialty sporting goods retail buyers, and amateur racing league equipment coordinators; and secondary validation through FDA 510(k) filings for prescription sports lenses, EU PPE Regulation conformity assessment databases, ANSI Z87.1 test report repositories, and polycarbonate resin trade flow data from customs authorities. Bottom-up triangulation across manufacturer shipment disclosures and top-down reconciliation against end-user participation statistics anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application intensity, certification tier, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated cycling infrastructure investment pipelines, ski tourism arrival forecasts, and motocross participation registration trends.
Decision-makers should treat outputs as directional under sustained federal transport ministry spending and stable petrochemical feedstock pricing; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU PPE Regulation enforcement intensity and ANSI Z87.1 update timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Mini Balance Beam Market