
 Air Sports Equipment Market | 2026-2036
Air Sports Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Sports Equipment Market Analysis
Recreational users is bifurcating from professional athletes as the dominant buyer archetype in equipment procurement, with weekend enthusiasts now accounting for the bulk of paraglider and kitesurfing unit volume. Ozone Paragliders LTD leverages its Chamonix engineering base to sustain technical credibility among competitive pilots. SUP'AIR anchors the European school and tandem-operator channel through its harness specialization. Advance Paragliders competes on material innovation, dominating lightweight nylon and carbon-fiber layup development for hike-and-fly segments.
Air sports equipment encompasses engineered apparatus designed for human flight or aerial maneuver in unpowered or minimally powered conditions, including paragliders with ripstop nylon canopies rated for specific load factors, hang gliders with aluminum-tube airframes and polyester sail surfaces, and kitesurfing rigs with inflatable leading-edge bladders and carbon-fiber control bars. The primary commercial purpose spans recreational aviation, competitive aerobatics, and tourism-based instruction where equipment reliability directly governs participant safety and operator liability. Paragliders and kitesurfing gear lead unit shipments due to lower training barriers and transportability, while hang gliders occupy a mature niche with slower replacement cycles. Carbon-fiber materials capture premium margin pools as manufacturers substitute metal components to reduce all-up weight for hike-and-fly and acro disciplines.
FAA Part 103 ultralight regulations in the United States and EASA CS-LSA certification frameworks in Europe govern airworthiness standards and pilot qualification requirements that equipment makers must design around. REACH chemical restrictions and CE marking obligations under EU PPE directives constrain textile treatments, resin systems, and harness hardware composition for products sold across European markets. ISO safety standards for mountaineering and aerial sports equipment provide baseline testing protocols that manufacturers reference for product liability defense. Stakeholders must monitor evolving national drone-integration rules and potential reclassification of powered paragliders as these regulatory shifts could redraw competitive boundaries between traditional air sports and emerging aerial mobility segments.
Market Dynamics
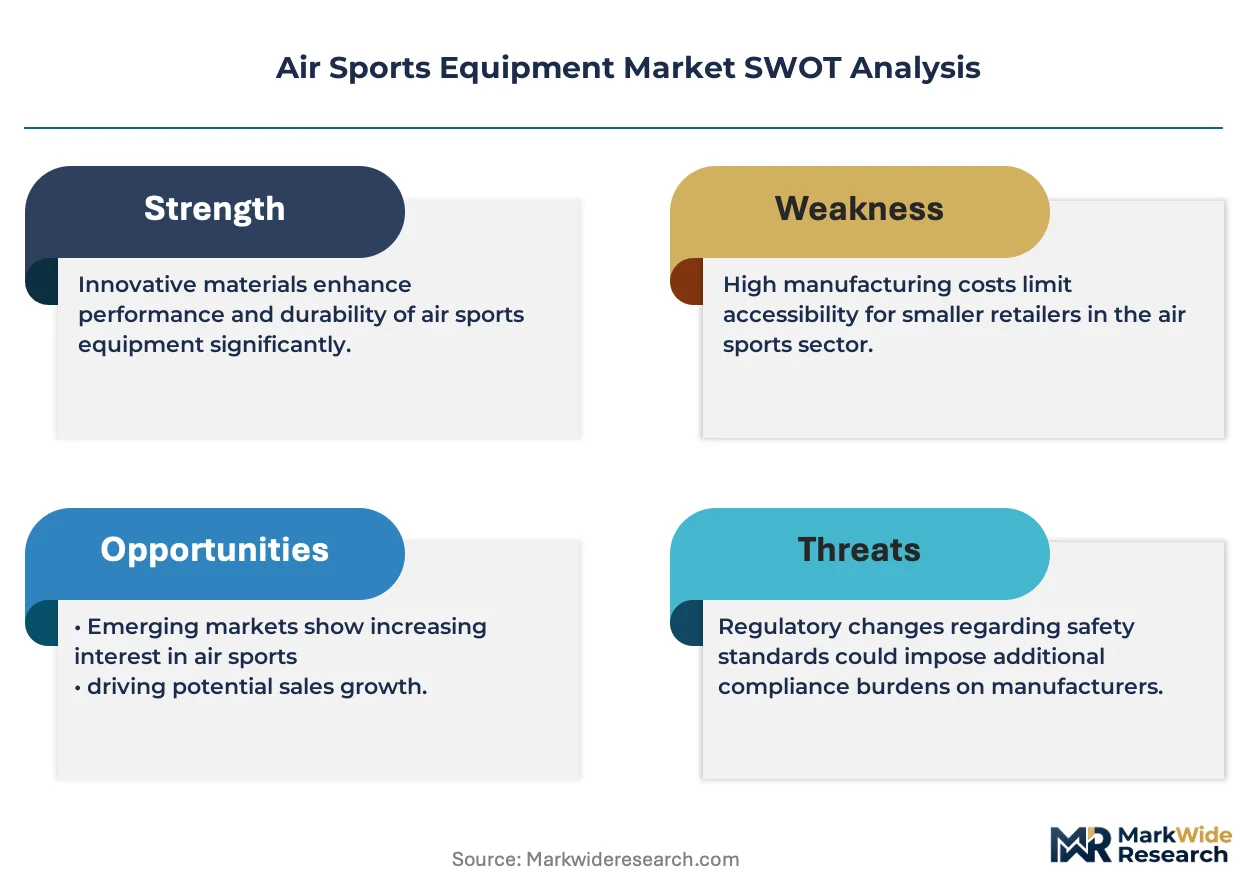
Recreational buyer proliferation is compressing equipment replacement cycles while simultaneously diluting average selling prices, as weekend enthusiasts prioritize portability and cost over competition-grade specifications that professional pilots demand.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement of restricted substance lists is accelerating R&D investment in bio-based resin systems and water-based textile coatings, creating technical differentiation for compliant manufacturers.
- Hike-and-fly discipline expansion:Alpine tourism operators in France, Switzerland, and Italy are bundling lightweight paraglider rentals with guided summit experiences, expanding addressable user bases beyond traditional flight schools.
- Carbon-fiber layup automation:Automated fiber placement and out-of-autoclave curing processes are reducing wing spar and control bar production costs, enabling price accessibility for entry-level hang glider segments.
Market Restraints
- Ripstop nylon supply concentration:Technical fabric weaving capacity clusters in South Korea and Taiwan, exposing manufacturers to freight cost volatility and single-source qualification risks for load-rated canopy materials.
- FAA Part 103 weight restrictions:United States ultralight category limits constrain powered paraglider motor integration, blocking product development paths that European EASA CS-LSA frameworks permit.
- Indoor skydiving substitution:Vertical wind tunnel facilities in urban centers capture trial users who might otherwise pursue initial skydiving certification, compressing first-rig purchase timing for traditional dropzone operators.
Strategic Opportunities
- Coastal Brazil kitesurfing corridors:Underdeveloped equipment retail infrastructure along Ceará and Rio Grande do Norte coastlines presents direct-to-consumer e-commerce penetration potential for rig and board bundles.
- EU Green Deal procurement incentives:Public tourism development grants in Portugal and Spain prioritize sustainable material certifications, rewarding manufacturers with bio-based supply chain documentation.
- Paramotor-tourism convergence:Hybrid powered paraglider platforms are attracting safari operators in Kenya and Tanzania seeking low-impact aerial wildlife viewing alternatives to helicopter charters.
Industry Challenges
- Certified rigger talent scarcity:FAA Master Rigger and EASA Part 66 license holders remain concentrated in legacy aviation maintenance hubs, constraining skydiving rig inspection capacity at expanding dropzone networks.
- CE PPE testing backlog:European notified body queue times for harness and reserve parachute conformity assessments extend 14-18 months, delaying product launches and freezing working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Sports Equipment Market |
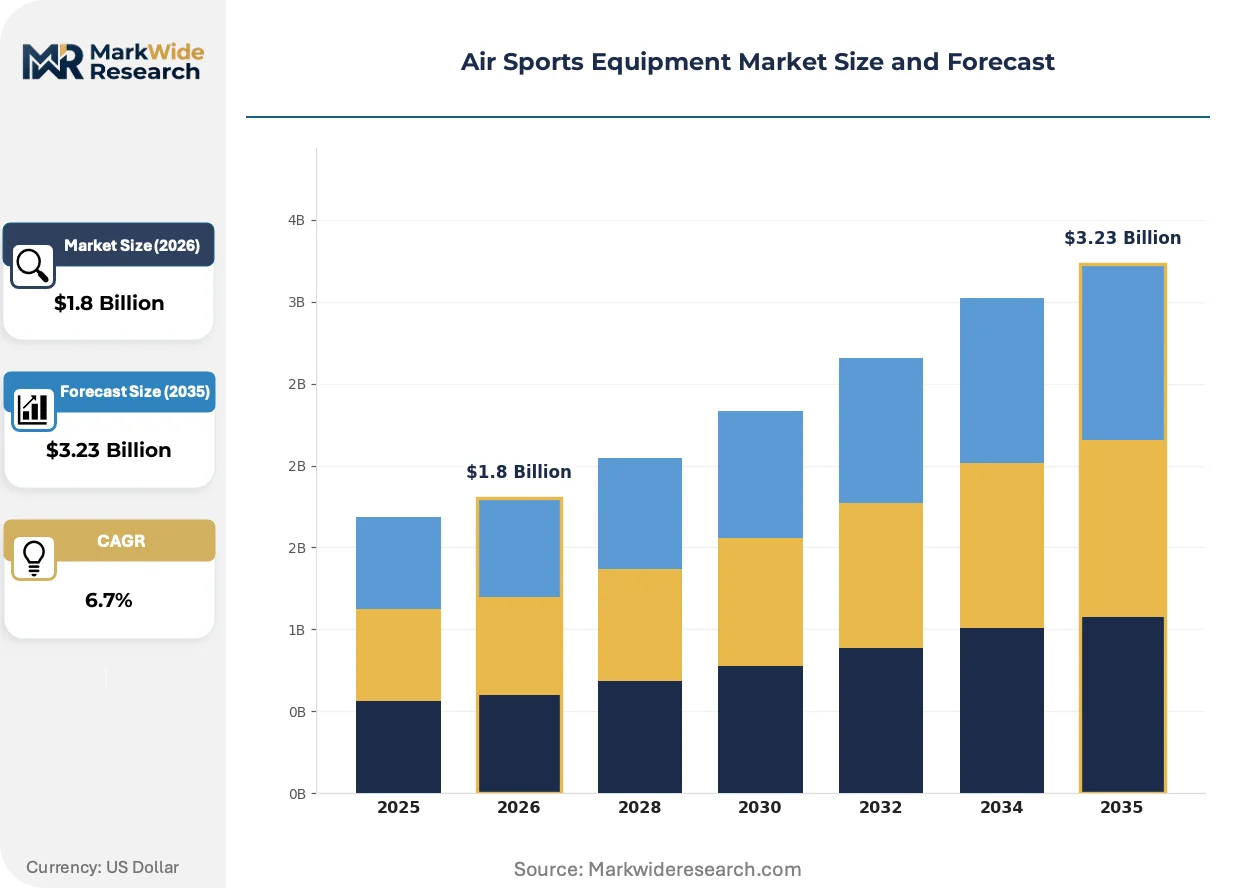
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paragliders, Kitesurfing Gear, Hang Gliders, Drones End User: Recreational Users, Professional Athletes, Schools, Tour Operators Material: Nylon, Carbon Fiber, Polyester, Aluminum Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Velocity Sports Equipment Sdn Bhd, Ozone Paragliders LTD, SUP’AIR, Sun Path Products, Inc., Apco Aviation Ltd., Aerodyne Research LLC, Peregrine Manufacturing, Inc., Advance Paragliders, Phoenix Fly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Sports Equipment Market Emerging Trajectories
Material science breakthroughs and regulatory recalibration are compressing development timelines while fragmenting buyer expectations across performance, portability, and price dimensions.
Aluminum-lithium alloy tubing is supplanting traditional 6061-T6 aluminum in high-performance hang glider airframes, delivering 12-15% weight reduction without structural compromise. Competitive aerobatics pilots in Germany and the Czech Republic are transitioning fleets rapidly, forcing manufacturers to dual-source metallurgical supply chains or cede premium segment position.
EASA CS-LSA framework revisions are tightening noise emission thresholds for powered paragliders, compelling Austrian and Italian engine manufacturers to redesign exhaust systems and propeller geometries. The regulatory pressure is accelerating electric propulsion partnerships, with battery-electric paramotors gaining provisional type acceptance ahead of fossil-fuel alternatives in noise-sensitive Alpine valleys.
Direct-to-consumer video consultation is displacing traditional dealer network touchpoints for initial harness fitting and wing sizing, particularly among urban professionals seeking weekend entry into paragliding. Australian and Canadian retailers report 40% of unit volume now ships without physical fitting, relying on biometric measurement apps and remote expert review to reduce geographic access barriers.
Air Sports Equipment Market Segmentation
Equipment procurement patterns diverge sharply between weekend enthusiasts seeking portability and competitive pilots demanding certified performance. Channel strategies must align with these divergent buyer archetypes to capture margin pools across the value chain.
Product Type:
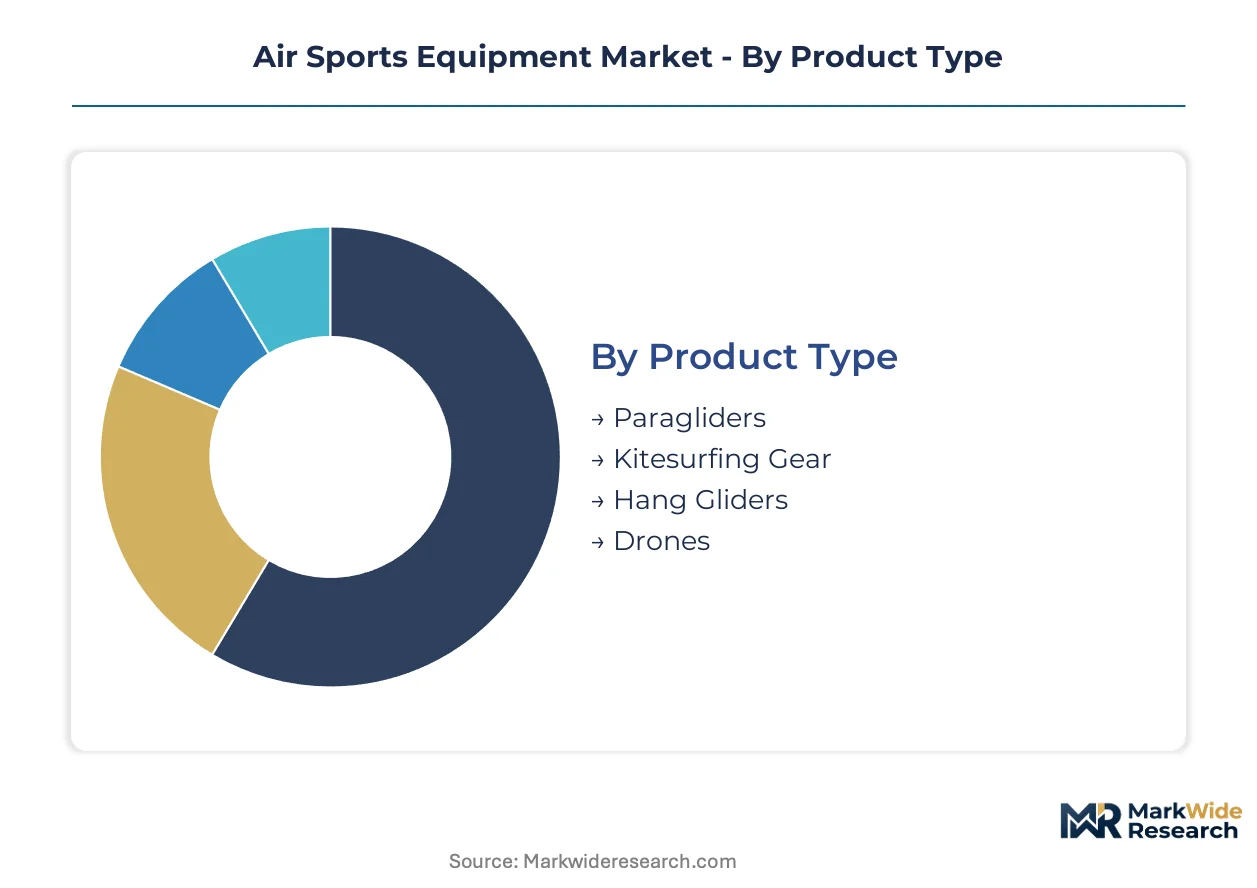
Paragliders flow through specialized flight schools and direct-to-consumer channels, while kitesurfing gear penetrates coastal surf retailers and beachfront rental operators. Hang gliders and drones occupy distinct distribution pathways reflecting their technical complexity and regulatory status.
- Paragliders:Ripstop nylon canopies with load-rated line systems and certified harness integration. Demand concentrates in France's Annecy cluster and Switzerland's Alpine valleys, driven by hike-and-fly tourism bundling with guided summit experiences.
- Kitesurfing Gear:Inflatable leading-edge bladders with carbon-fiber control bars and twin-tip or directional board configurations. Australia's Gold Coast and Brazil's Ceará coastline anchor volume, where coastal tourism operators expand rental fleet procurement.
- Hang Gliders:Aluminum-tube airframes with polyester sail surfaces for unpowered flight.
- Drones:Unmanned aerial systems with camera stabilization for aerial photography and racing applications.
Paragliders dominate installed base. Kitesurfing gear is where expansion concentrates.
End User:
Cost tiers stratify procurement behavior, with recreational users prioritizing entry-level pricing and professional athletes absorbing premium certification costs. Schools and tour operators negotiate volume discounts that reshape manufacturer margin structures.
- Recreational Users:Weekend enthusiasts purchasing through e-commerce channels with remote fitting consultation. This segment accounts for bulk unit volume in paragliding and kitesurfing, compressing replacement cycles while diluting average selling prices.
- Professional Athletes:Competitive pilots and aerobatics specialists requiring EN-certified wings and competition-grade harness systems. Germany's sailplane regions and the Czech Republic anchor demand, where aluminum-lithium alloy transitions are accelerating fleet replacement.
- Schools:Training institutions procuring tandem-certified equipment with enhanced durability specifications.
- Tour Operators:Safari and alpine tourism bundling lightweight rentals with guided experiences.
Recreational users command unit volume. Professional athletes capture premium margin pools.
Material:
Supply concentration in Asian textile weaving and European carbon-fiber prepreg manufacturing dictates procurement risk profiles. REACH compliance and FAA airworthiness directives constrain material substitution pathways.
- Nylon:Ripstop weave canopies with polyurethane coating for UV resistance and tear propagation containment.
- Carbon Fiber:Pre-impregnated layups for wing spars, control bars, and lightweight frame components. France's Chamonix engineering base and Italian manufacturers drive specification standards, with automated fiber placement reducing production costs for entry-level segments.
- Polyester:Sail surfaces for hang glider wings with dimensional stability under load.
- Aluminum:6061-T6 and aluminum-lithium alloy tubing for high-performance hang glider airframes.
Nylon dominates canopy production. Carbon fiber is climbing the fastest as manufacturers substitute metal components.
Price Tier:
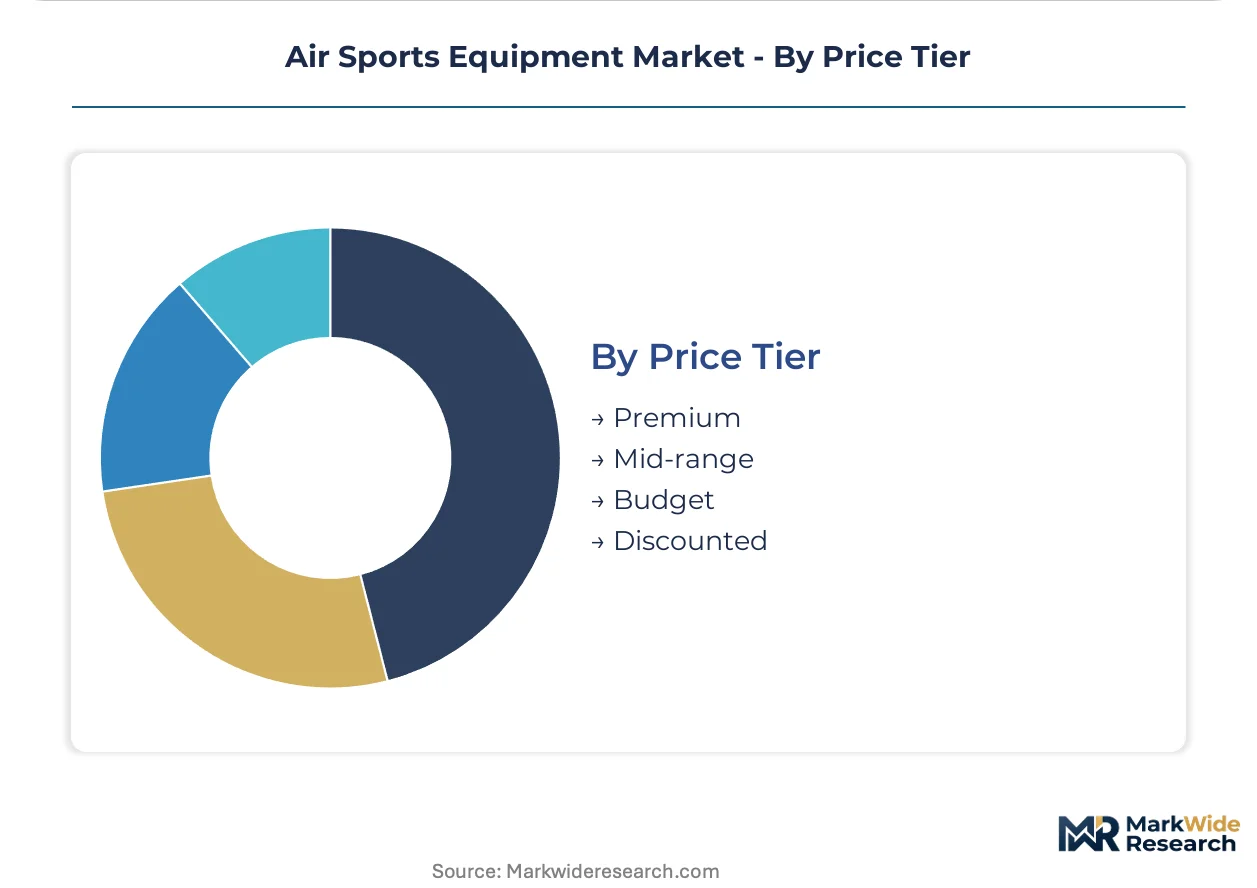
Certification grade and volume scale differentiate pricing architecture across the market. Three-tier structures separate competition-grade specifications from school-rental durability and entry-level portability priorities.
- Premium:EN-D certified paragliders, competition kitesurfing rigs, and aluminum-lithium hang gliders with full carbon-fiber options. EASA CS-LSA compliance and extended warranty terms justify positioning.
- Mid-range:EN-B/C certified wings and school-grade harness systems with standardized reserve integration. France's tandem-operator channel and Germany's flight schools anchor procurement volume.
- Budget:Entry-level paragliders and kitesurfing starter packages targeting first-time buyers.
- Discounted:Prior-season inventory and rental fleet decommissioned equipment.
Mid-range equipment dominates school procurement. Premium tier is gaining share fastest as competitive pilots upgrade fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sailplane regions export carbon-fiber wing spars to Australian coastal operators, while French canopy weavers supply ripstop nylon to Brazilian kitesurfing corridors along Ceará.
United States
FAA Part 103 ultralight regulations constrain powered paraglider motor integration, blocking development paths permitted under European frameworks. Indoor skydiving facilities in urban centers capture trial users who might otherwise pursue initial certification. Dropzone networks in Florida and California face certified rigger talent scarcity as FAA Master Rigger license holders concentrate in legacy aviation maintenance hubs.
Germany
Aluminum-lithium alloy transitions are accelerating fleet replacement among competitive aerobatics pilots in sailplane regions. EASA CS-LSA framework revisions tighten noise emission thresholds, compelling engine manufacturers to redesign exhaust systems. The country's national aviation regulator enforces extended conformity assessment timelines for harness and reserve parachute systems.
France
Annecy's paragliding cluster anchors demand for EN-certified wings and tandem-operator channel procurement. Alpine tourism operators bundle lightweight paraglider rentals with guided summit experiences. ECHA REACH chemical standards constrain textile treatments and resin systems for products sold across European markets.
Australia
Coastal kitesurfing corridors along the Gold Coast expand rental fleet procurement as tourism operators target weekend enthusiasts. Direct-to-consumer video consultation displaces traditional dealer networks, with retailers reporting significant unit volume shipping without physical fitting. The country's therapeutic goods regulator maintains baseline testing protocols for aerial sports equipment safety certification.
Brazil
Underdeveloped equipment retail infrastructure along Ceará and Rio Grande do Norte coastlines presents direct-to-consumer e-commerce penetration potential. ANVISA, the national health surveillance agency, oversees import compliance for inflatable leading-edge bladder materials. Beachfront rental operators prioritize cost-efficient rig and board bundles over competition-grade specifications.
Air Sports Equipment Market Vendor Landscape
Player mix skews toward specialized engineering houses with concentrated geographic footprints in Alpine valleys and coastal manufacturing zones. The vendor base organizes around technical credibility anchored in specific flight disciplines rather than diversified portfolio scale. Two strategic archetypes dominate: canopy specialists leveraging textile innovation credentials and harness manufacturers controlling school and tandem-operator channels. Competitive moves center on automated fiber placement investments for carbon-fiber cost reduction and direct-to-consumer biometric fitting platforms that bypass traditional dealer networks.
Within the Alpine engineering tier, Ozone Paragliders LTD and Advance Paragliders exemplify contrasting specialization vectors—one sustaining technical credibility among competitive pilots through mountain-valley engineering proximity, the other dominating material innovation for hike-and-fly portability demands. SUP'AIR occupies a distinct channel position as a harness specialist anchoring European school procurement. These three companies represent the core competitive structure: engineering-credibility players, material-innovation specialists, and channel-anchored equipment suppliers.
| Leading Market Players |
|---|
| Velocity Sports Equipment Sdn Bhd |
| Ozone Paragliders LTD |
| SUP'AIR |
| Sun Path Products, Inc. |
| Apco Aviation Ltd. |
| Aerodyne Research LLC |
| Peregrine Manufacturing, Inc. |
| Advance Paragliders |
| Phoenix Fly |
| Others |
Supply Flow & Price Mechanics
Carbon-fiber substitution for aluminum-lithium alloys in high-performance hang glider airframes is redrawing procurement geography from German metallurgical suppliers toward French and Italian prepreg manufacturers, compressing wing spar costs while elevating resin-system compliance burdens under REACH chemical standards. This materials transition simultaneously fragments supplier power across Alpine engineering corridors and Asian textile weaving clusters, forcing manufacturers to dual-source or surrender margin control.
Pricing Analysis
Current-generation aluminum-lithium alloy airframes command substantial premiums over legacy 6061-T6 configurations, while next-generation electric paramotor platforms threaten to reset pricing architectures entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by EN certification grade and carbon-fiber content share, with EASA CS-LSA compliance adding fixed certification overhead. Cost compression in entry-level paraglider segments is intensifying because recreational buyers prioritize portability over competition-grade specifications. Weekend enthusiasts exhibit highest price sensitivity, while professional aerobatics pilots absorb premium tier increases without volume erosion.
Supply Chain Analysis
Taiwan Strait shipping lanes constrain ripstop nylon delivery schedules for canopy manufacturers dependent on South Korean and Taiwanese technical weaving capacity. Raw material procurement draws from polyurethane-coated nylon textiles, carbon-fiber prepreg laminates, and aluminum-lithium alloy tubing. Single-source vulnerability concentrates in load-rated line system certification, where qualified suppliers remain limited to Alpine engineering houses. Distribution runs through specialized flight schools for paragliders, coastal surf retailers for kitesurfing gear, and direct-to-consumer biometric fitting platforms displacing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric propulsion integration and EASA noise-emission revisions are disrupting established fossil-fuel paramotor supply chains, creating acquisition opportunities for battery-electric platform developers ahead of regulatory deadlines.
For Market Incumbents: Fortify certification investment in EASA CS-LSA and FAA Part 103 compliance to defend against electric propulsion entrants capturing noise-sensitive Alpine valleys. Deepen backward integration into carbon-fiber prepreg manufacturing to secure margin pools as automated fiber placement commoditizes wing spar production. Channel control through school and tandem-operator relationships anchors recurring revenue against direct-to-consumer erosion. For New Entrants and Emerging Players: CE PPE testing fast-tracks for harness and reserve parachute systems offer regulatory arbitrage against incumbent product launch delays. Coastal Brazil kitesurfing corridors present the most penetrable geography, with underdeveloped retail infrastructure enabling e-commerce rig and board bundles. Biometric fitting apps bypass geographic access barriers for urban professional segments seeking weekend entry. For Investors and Strategic Acquirers: Capital is best deployed toward automated fiber placement specialists with out-of-autoclave curing capabilities that reduce carbon-fiber component costs for entry-level segments. Long-term viability rests on manufacturers bridging electric propulsion partnerships ahead of fossil-fuel platform obsolescence. Watch EASA CS-LSA framework revisions as the signal for paramotor-tourism convergence timing in safari and alpine markets.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Investment | Reduces carbon-fiber wing spar production costs for entry-level hang glider segments. |
| Electric Propulsion Partnership | Positions manufacturers ahead of EASA noise-emission thresholds tightening in Alpine corridors. |
| Direct-to-Consumer Biometric Platform | Bypasses traditional dealer networks for urban professionals seeking remote harness fitting. |
| REACH-Compliant Resin System Development | Secures European market access as ECHA enforcement accelerates bio-based substitution. |
| Coastal Brazil E-Commerce Penetration | Captures rig and board bundle demand in underdeveloped Ceará and Rio Grande do Norte retail corridors. |
Methodological Framework
A standing panel of flight school operators, tandem-certification instructors, dropzone riggers, and carbon-fiber manufacturing engineers provided ongoing calibration against secondary validation from EASA certification databases, FAA Master Rigger license records, and EU PPE notified body assessment queues. Bottom-up equipment shipment triangulation combined with top-down tourism operator procurement surveys anchored volume estimates across the analysis window.
Consistency checks validated projection outputs against Alpine tourism bundling penetration rates, coastal kitesurfing rental fleet expansion, and electric paramotor provisional type acceptance timelines. Segmentation modeling spanned product type, end-user archetype, material composition, and price tier across the projection horizon. CAGRs derived from equipment replacement cycle compression, hike-and-fly discipline expansion, and carbon-fiber cost curve trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EASA regulatory stability and REACH compliance cost pass-through; material deviation in electric propulsion adoption curves or certification backlog resolution would warrant model refresh. Practitioners should keep alternative scenarios live as FAA Part 103 weight restriction debates and indoor skydiving substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Sports Mouthguard Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Knee Pads Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
China Sports Optic Market