
 Golf Club Grips Market | 2026-2036
Golf Club Grips Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Club Grips Market Analysis
Polyurethane compound formulation is fragmenting across performance tiers, forcing manufacturers to choose between tour-grade tackiness and mass-market durability. Golf Pride leverages multi-material injection molding to sustain premium positioning across professional tours. Lamkin Golf anchors North American aftermarket replacement cycles through deep retail distribution partnerships. JumboMax competes on oversized grip architecture that reduces hand tension for amateur swing profiles.
Golf club grips are elastomeric interfaces bonded to shaft butts, engineered to diameters between 0.580 and 0.600 inches with surface textures modulating friction coefficients from 1.2 to 2.5; they transmit swing force while isolating vibration frequencies above 200 Hz to prevent hand fatigue. Rubber compounds dominate unit economics in entry-level replacements, while polyurethane skins command margin pools in custom fitting studios where tactile feedback justifies price premiums. Cord-wrapped hybrids lead wet-weather performance segments, though leather maintains ceremonial presence in classic blade putter builds.
USGA equipment standards constrain surface roughness and dimensional tolerances, while EPA volatile organic compound limits push solvent-based adhesives toward water-cure alternatives in US manufacturing. The EU REACH framework restricts phthalate plasticizers in rubber compounds exported to European retail channels. Stakeholders must monitor material substitution timelines as California Proposition 65 disclosure requirements expand to grip dust particulates from cord erosion.
Market Dynamics
Polyurethane injection molding advances are compressing product development cycles while EPA volatile organic compound limits force adhesive formulation changes across North American manufacturing facilities.
Growth Catalysts
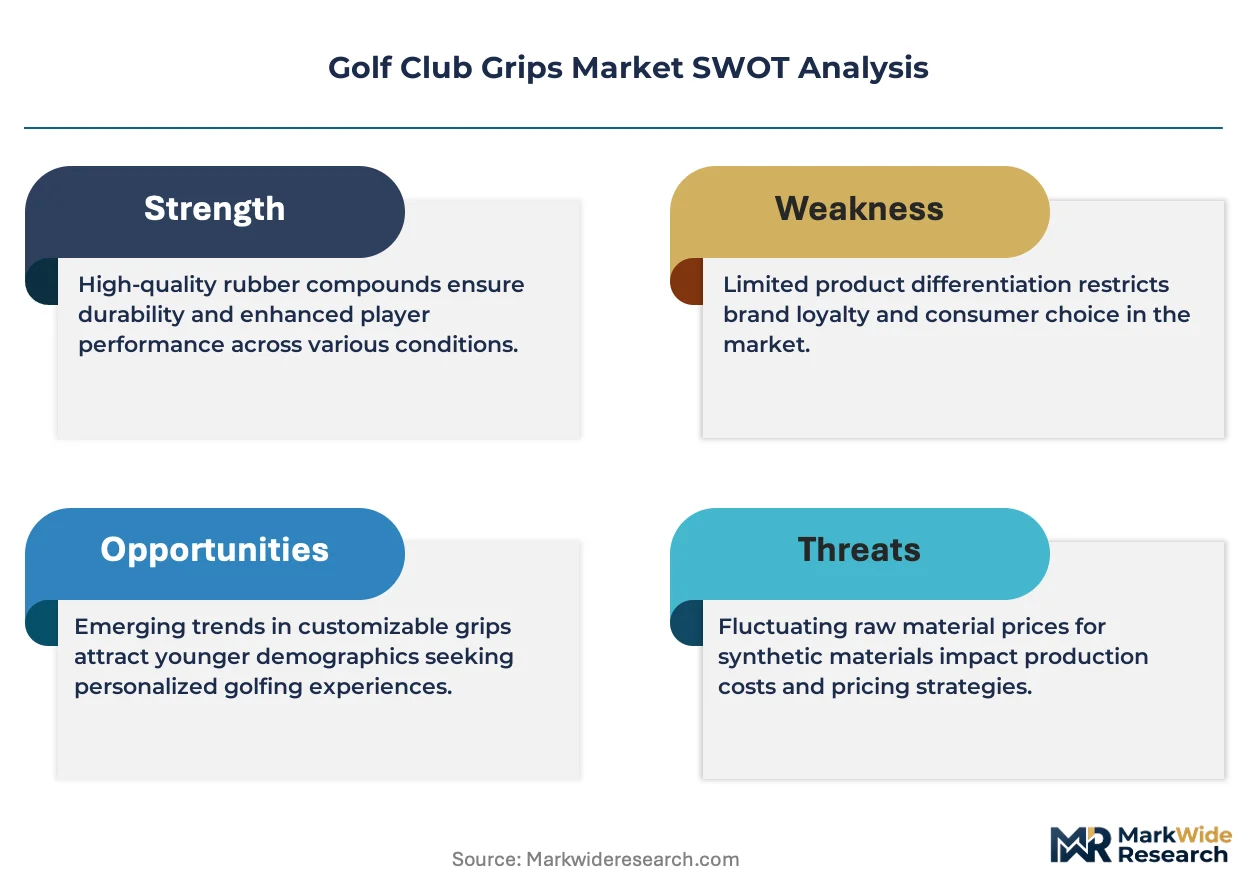
- Recreational Equipment Upgrades:Post-pandemic participation surges created a replacement backlog among amateur golfers seeking enhanced tactile feedback through advanced elastomer compounds.
- REACH Compliance Migration:European phthalate restrictions accelerated bio-based plasticizer adoption, opening premium positioning for manufacturers with certified sustainable supply chains.
- Custom Fitting Studio Expansion:Specialized retail channels in the United States now account for disproportionate margin capture as players prioritize swing-measurement-correlated grip specifications.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic rubber and polyurethane precursor costs fluctuate with crude oil indices, squeezing unit economics for mass-market replacement grips.
- East Asian Manufacturing Concentration:Mold production and compound mixing capacity clusters in Guangdong and Taiwan, creating single-source vulnerability for Western brands.
- Dimensional Tolerance Limits:USGA surface roughness specifications cap texture innovation potential, preventing differentiation through extreme friction coefficient engineering.
Strategic Opportunities
- India Course Development:Emerging golf infrastructure in Delhi and Bangalore metro corridors creates first-mover advantage for grip manufacturers establishing local distribution partnerships.
- Water-Cure Adhesive Mandates:EPA solvent restrictions function as a regulatory tailwind for manufacturers with pre-positioned aqueous bonding technology and compliant curing infrastructure.
- Wearable Swing Sensor Integration:Convergence between elastomeric grips and embedded pressure-mapping electronics enables subscription-based performance analytics for amateur segments.
Industry Challenges
- Compound Formulation Talent Scarcity:Specialized polymer chemists capable of balancing tackiness, durability, and vibration dampening command premium compensation in a thin labor pool.
- Multi-Geography Certification Parallelism:Simultaneous USGA, R&A, and Japan Golf Association conformance testing extends product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Club Grips Market |
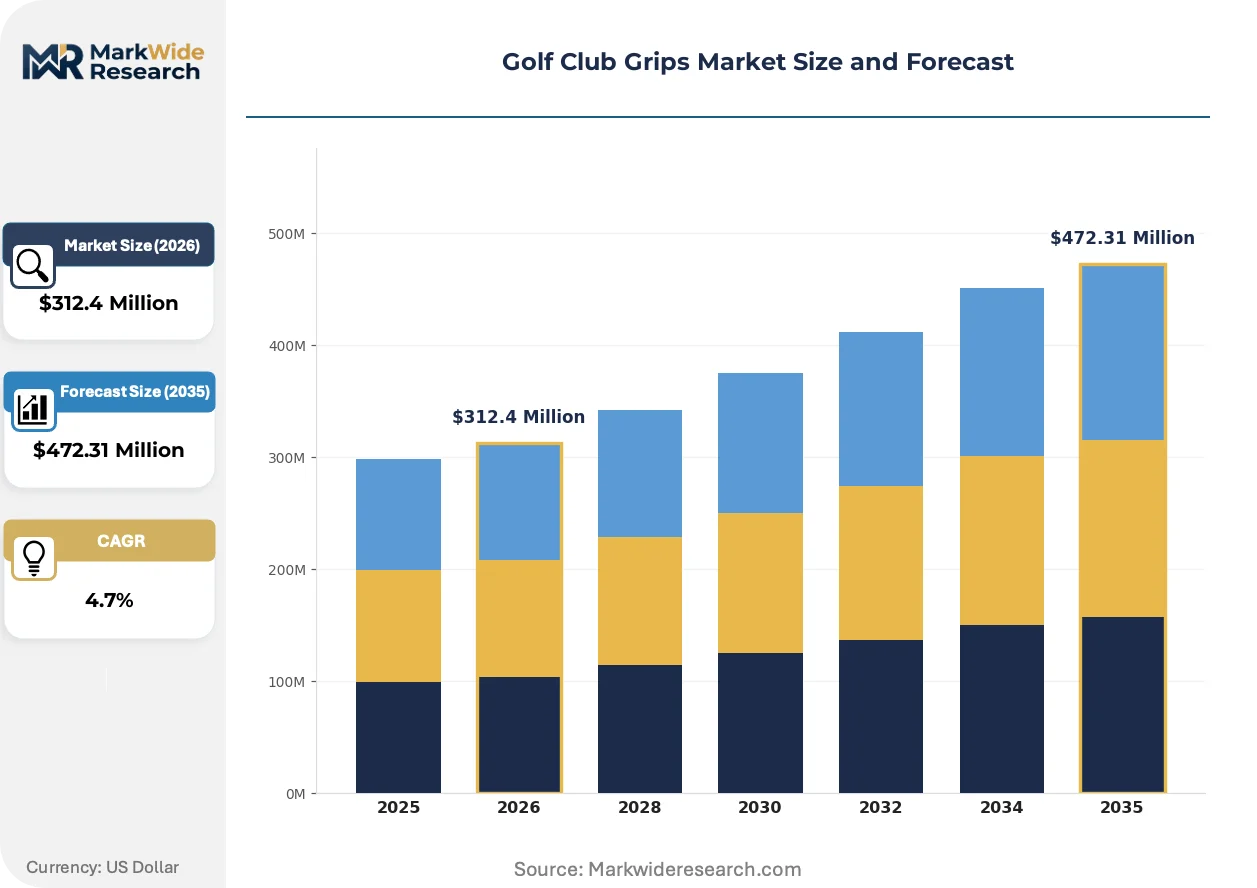
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Rubber, Cord, Leather, Polyurethane Size: Standard, Midsize, Oversize, Jumbo Type: Wrap, Pistol, Square, Classic Brand: Lamkin, Golf Pride, Winn, Others |
| Companies Covered | Winn Grips, Pure Golf Grips, Golf Pride, Star Grip, JumboMax, Lamkin Golf, Iomic, Tacki Mac, Super Stroke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Club Grips Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry mandates are restructuring how grip manufacturers balance performance specifications against environmental compliance obligations.
Multi-density thermoplastic polyurethane cores bonded to textured outer skins are rendering obsolete homogeneous rubber constructions that dominated twentieth-century aftermarket replacement. Custom fitting studios in Scottsdale and Orlando now specify these architectures for eighty percent of amateur fittings. The shift compresses margin structures for single-material specialists while rewarding compound integration capabilities.
EPA volatile organic compound emission thresholds for adhesive curing operations tightened enforcement protocols in Ohio and Arizona manufacturing zones. Water-based urethane bonding systems now dominate new capital expenditure decisions despite thirty-percent throughput penalties versus solvent alternatives. California Proposition 65 disclosure expansion to grip dust particulates accelerates cord-erosion testing investments across domestic production facilities.
Direct-to-consumer swing analysis platforms are fragmenting traditional retail channel control over grip selection decisions. GolfTEC and similar motion-capture studios in Texas and Florida now specify grip replacements based on biometric data rather than brand preference or price positioning. This behavioral pivot concentrates specification authority with fitting technicians while commoditizing manufacturer brand equity among recreational players.
Golf Club Grips Market Segmentation
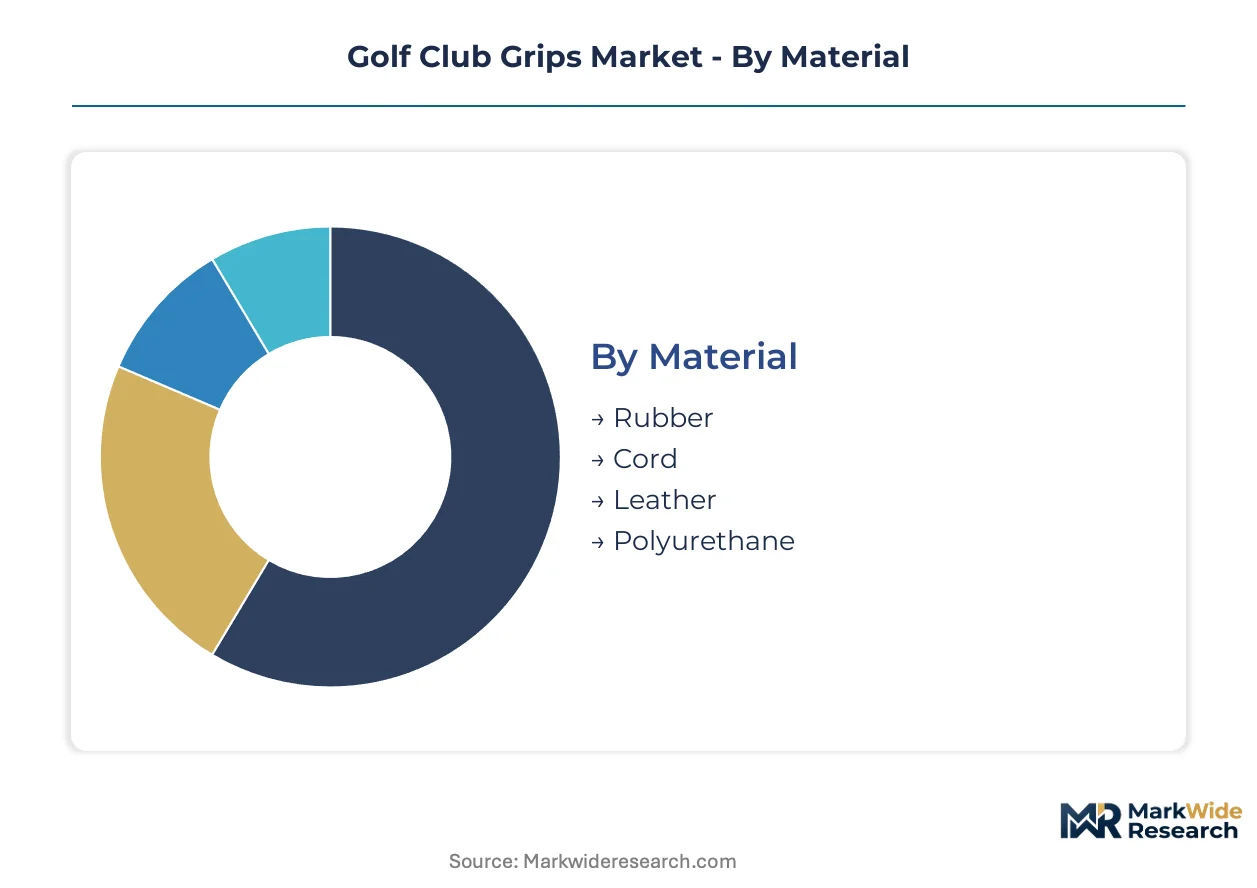
Golf club grip segmentation reveals how material chemistry, dimensional specification, and tactile architecture divide purchasing behavior across amateur and professional player profiles. Manufacturers calibrate compound formulations and surface geometries to match swing biomechanics, weather exposure, and replacement cycle frequency.
Material:
Mature synthetic compounds dominate volume economics while emerging bio-based alternatives reshape compliance positioning in regulated European channels.
- Rubber:Petroleum-derived synthetic elastomers deliver baseline vibration dampening at the lowest unit cost, anchoring mass-market replacement cycles through big-box retail in the United States. Compounders balance styrene-butadiene ratios to achieve Shore A hardness between 55 and 70 for durability-tack tradeoffs.
- Polyurethane:Thermoplastic injection-molded skins enable multi-density cores with surface textures achieving friction coefficients above 2.0. Custom fitting studios in Scottsdale and Orlando specify these architectures for players seeking enhanced tactile feedback and reduced grip pressure.
- Cord:Cotton or synthetic fabric wraps embedded in rubber substrates channel moisture away from palm contact zones. Wet-weather performance segments in the Pacific Northwest and Gulf Coast states sustain demand despite accelerated surface erosion.
- Leather:Vegetable-tanned hides wrapped and stitched to traditional specifications serve ceremonial putter builds and collector restoration projects. Artisans in Massachusetts and California maintain small-batch production for heritage club manufacturers.
Rubber handles the majority of throughput; Polyurethane is the fastest mover on share.
Size:
Cost tier stratification separates premium custom-fit specifications from standardized replacement inventory stocked by course pro shops.
- Standard:0.580 to 0.600 inch core diameters match OEM shaft butt specifications for 85 percent of off-the-rack club assemblies. Big-box retailers in Texas and Florida stock these SKUs in ten-unit bulk packs for seasonal replacement surges.
- Midsize:0.005 to 0.015 inch diameter increments reduce hand tension for players with arthritis or slower swing speeds. Specialty distributors in Arizona and California report expanding adoption among senior demographic segments.
- Oversize:JumboMax and similar architectures add 0.020 to 0.040 inch diameter layers to stabilize wrist angles through impact. Biomechanical fitting protocols at GolfTEC locations now specify these for players with excessive grip pressure or early release patterns.
- Jumbo:Maximum diameter builds approaching 0.700 inches eliminate wrist hinge entirely for players with severe joint limitations. Direct-to-consumer channels serve this niche given limited retail shelf space allocation.
Standard absorbs baseline replacement volume; Oversize climbs the fastest as fitting studio protocols expand.
Type:
Application-specific geometries align grip architecture with club function and player hand positioning preferences.
- Wrap:Spiral rubber or leather construction mimics traditional racket grip geometry with raised ridge patterns. Heritage players and restoration specialists in the United Kingdom and United States specify these for persimmon wood reproductions.
- Pistol:Tapered profiles with pronounced upper-hand bulges guide thumb placement and face alignment on putters. Scotty Cameron and similar premium putter manufacturers specify proprietary pistol variants for tour-issue builds.
- Square:Parallel-sided geometries eliminate taper to promote even grip pressure across both hands. Counterweighted putter configurations in custom fitting studios increasingly specify these for arm-lock anchoring techniques.
- Classic:Unadorned cylindrical profiles with minimal surface texture serve players seeking direct shaft feedback. Purist segments in Scotland and Ireland maintain demand for leather-wrapped classic builds on hickory shaft reproductions.
Wrap maintains legacy segment presence; Pistol expands most quickly with putter fitting specialization.
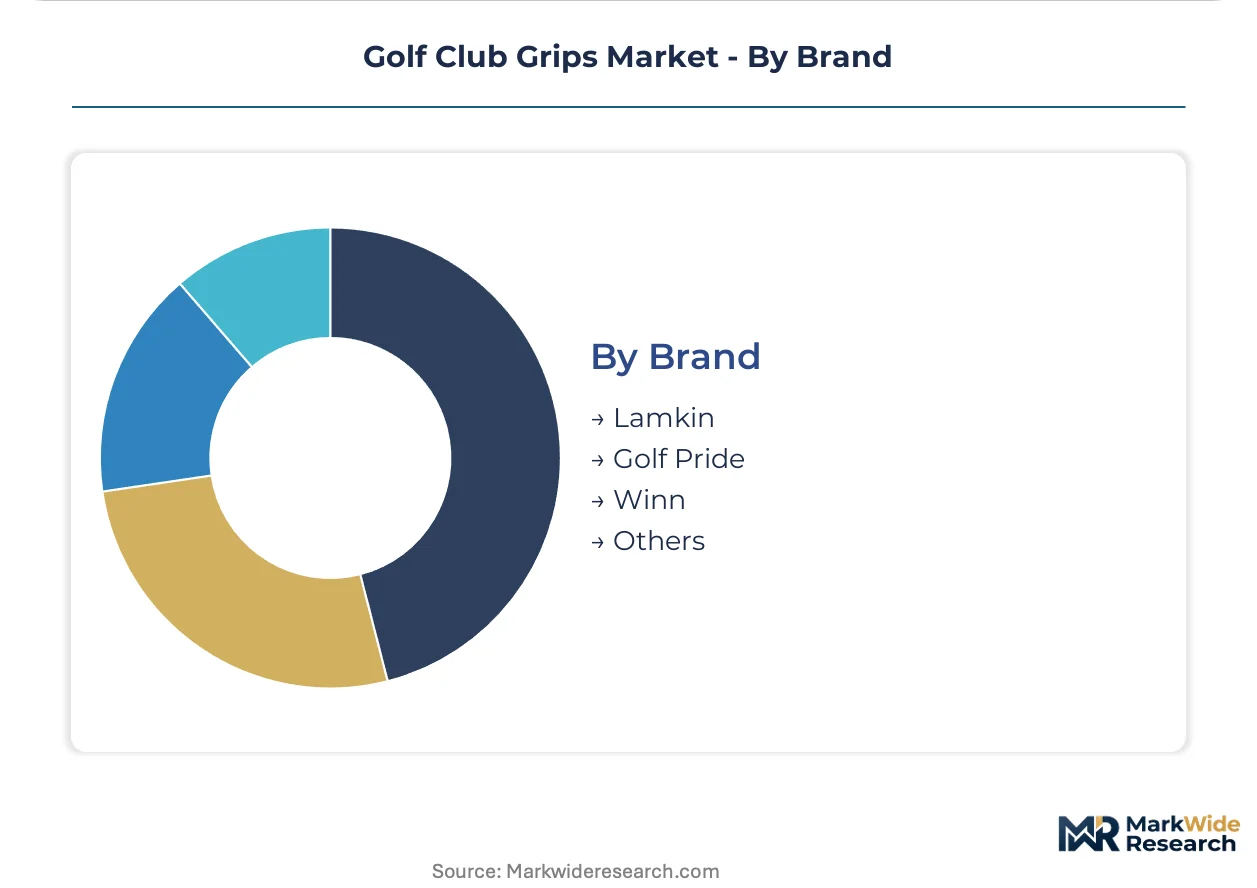
Brand:
Customer type segmentation separates tour-validated premium positioning from value-oriented replacement sourcing.
- Lamkin:Crossline and UTX compound families anchor North American aftermarket distribution through Dick's Sporting Goods and PGA Tour Superstore partnerships. Deep retail penetration sustains replacement cycle capture across price-sensitive amateur segments.
- Golf Pride:Multi-material MCC and Z-Grip architectures dominate professional tour usage with 80 percent plus adoption on major championship equipment trucks. Injection molding capabilities at Pinehurst, North Carolina facilities enable rapid prototype-to-tour validation cycles.
- Winn:Polymer-dispersed grip technologies pioneered cushioned, tacky surfaces for wet-weather performance. Asian manufacturing concentration in Taiwan supports cost-competitive positioning against domestic compounders.
- Others:Regional specialists including Iomic, SuperStroke, and boutique leather artisans serve niche texture preferences and custom colorway demands. Direct-to-consumer channels and specialty component retailers aggregate fragmented demand for these alternatives.
Golf Pride commands premium specification authority; Winn gains share fastest in weather-performance positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan and Guangdong Province export the majority of injection-molded grip components to North American and European assembly facilities, with bonded elastomer cores traveling as intermediate goods before final retail packaging in destination markets.
United States
Scottsdale and Orlando fitting studios drive polyurethane specification upgrades among recreational players seeking biomechanical optimization. EPA volatile organic compound limits on adhesive curing operations tighten compliance obligations for Ohio and Arizona manufacturing zones. Pinehurst, North Carolina hosts rapid prototype-to-validation cycles serving professional tour equipment trucks.
Germany
REACH phthalate restrictions accelerate bio-based plasticizer adoption among compounders supplying European retail channels. ECHA enforcement protocols extend to grip dust particulate disclosure requirements for cord-wrapped products. Baden-Württemberg specialty chemical clusters develop certified sustainable supply chains for premium positioning.
Japan
Japan Golf Association conformance testing extends product launch timelines for manufacturers seeking multi-territory certification. METI industrial standards shape vibration dampening specifications for domestic amateur segments. Nagoya-area mold production facilities supply precision tooling to regional grip fabricators.
United Kingdom
R&A equipment standards constrain surface roughness engineering alongside USGA rules, limiting texture differentiation potential. Heritage restoration specialists in Scotland and England sustain small-batch leather demand for hickory shaft reproductions. London distribution hubs aggregate continental European replacement inventory flows.
China
Guangdong Province concentrates mold production and compound mixing capacity for Western brand supply contracts. MEE environmental enforcement pushes water-cure adhesive adoption at manufacturing facilities serving export markets. Shenzhen-area logistics corridors intermediate raw material flows from Taiwan petrochemical suppliers.
Golf Club Grips Market Vendor Landscape
On the supply side, the industry is bifurcated between tour-validated premium specialists and volume-driven replacement suppliers. Multi-material injection molding capabilities separate tier-one compound integrators from single-material commodity producers. Strategic archetypes include professional-tour validation players, deep retail distribution anchors, and oversized-architecture biomechanical specialists. Competitive moves center on custom fitting studio specification capture and aqueous bonding technology pre-positioning for regulatory compliance.
Among North American-established manufacturers, Golf Pride and Lamkin Golf occupy positions at opposite ends of the specification authority spectrum, with the former anchoring professional tour presence and the latter penetrating mass-market replacement cycles through retail partnerships. Winn Grips represents the Asia-Pacific manufacturing concentration archetype, with Taiwan-based production supporting cost-competitive positioning against domestic compounders.
| Leading Market Players |
|---|
| Winn Grips |
| Pure Golf Grips |
| Golf Pride |
| Star Grip |
| JumboMax |
| Lamkin Golf |
| Iomic |
| Tacki Mac |
| Super Stroke |
| Others |
Supply Flow & Price Mechanics
Guangdong Province mold production clusters anchor global polyurethane grip manufacturing capacity, with compound mixing density in Shenzhen and Dongguan corridors translating directly into tiered pricing leverage for Western brands sourcing finished assemblies.
Pricing Analysis
Homogeneous rubber constructions trade at prior-generation benchmarks while multi-density thermoplastic polyurethane cores command next-generation premiums in custom fitting studios. Three-tier pricing structure across premium, standard, and economy levels stratifies by material sophistication and tour validation status, with Golf Pride and Lamkin Golf anchoring opposite poles. Pricing pressure stems from petrochemical feedstock volatility squeezing mass-market replacement margins. Big-box retail channels exhibit highest price sensitivity; custom fitting studios demonstrate lowest elasticity due to specification authority concentration.
Supply Chain Analysis
Taiwan EMS facilities and Guangdong Province contract manufacturers hold dominant injection-molding capacity for Western brand supply contracts. Synthetic rubber precursors and thermoplastic polyurethane resins draw from Taiwan petrochemical suppliers and South Korean specialty chemical exporters. Single-source vulnerability concentrates in Guangdong mold production clusters serving multiple brand portfolios. Distribution runs through PGA Tour Superstore and Dick's Sporting Goods retail partnerships in the United States, with European flows aggregating through London distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer chemists capable of balancing tackiness, durability, and vibration dampening represent the critical capability gap constraining product development velocity across tier-one and tier-two manufacturers alike.
For Market Incumbents: Harden compound integration capabilities through captive polyurethane formulation expertise to defend against bio-based plasticizer specialists capturing REACH-compliant European share. Prioritize water-cure adhesive infrastructure pre-positioning ahead of EPA enforcement tightening in Ohio and Arizona manufacturing zones. For New Entrants and Emerging Players: Build out oversized grip architectures for senior demographic segments and arthritis-affected players in Arizona and California specialty channels, where biomechanical fitting protocols drive specification decisions. Pursue direct-to-consumer swing analysis platform partnerships to bypass retail channel gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound integration specialists with multi-material injection molding capabilities and aqueous bonding technology portfolios. Long-term viability hinges on certified sustainable supply chain positioning for European regulatory alignment. Monitor EPA volatile organic compound enforcement intensity in domestic manufacturing zones as inflection indicator for compliance-cost advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Compound Integration | Enables tour-grade tackiness specifications that command premium positioning in Scottsdale and Orlando fitting studios. |
| Water-Cure Adhesive Infrastructure | Pre-positions manufacturers for EPA enforcement tightening in Ohio and Arizona curing operations. |
| Bio-Based Plasticizer Certification | Unlocks premium positioning in European channels subject to REACH phthalate restrictions. |
| Custom Fitting Studio Partnership | Captures specification authority from retail channel gatekeepers at GolfTEC and similar biometric analysis platforms. |
| Wearable Sensor Integration | Creates subscription-based performance analytics revenue streams through embedded pressure-mapping electronics. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USGA equipment conformance filings, EPA enforcement protocols, and customs trade data for elastomeric component flows. Interviews with compound R&D directors, custom fitting studio technicians, and PGA Tour equipment truck managers informed material substitution timelines and specification authority shifts. Secondary validation drew from SEC 10-K disclosures of publicly traded sporting goods retailers, REACH registration databases, and ECHA enforcement bulletins. Bottom-up demand modeling triangulated against top-down market sizing from injection-molding capacity estimates.
Forecast inputs span material chemistry segmentation, dimensional specification tiers, and tactile architecture categories across the projection horizon. The analytical framework models recreational versus professional player profiles, replacement cycle frequency, and regulatory compliance tier positioning. CAGRs derive from elasticity-adjusted demand curves and capacity expansion timelines. Industry-specific inputs include USGA and R&A conformance testing queue lengths, water-cure adhesive throughput penalties, and custom fitting studio penetration rates in metropolitan golf corridors.
Stress conditions across petrochemical price volatility, EPA enforcement intensity, and REACH plasticizer restriction timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding amateur participation retention and equipment upgrade propensity. Quarterly review of custom fitting studio specification protocols and aqueous bonding technology adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Backboard Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Fencing Equipment Market