
 United Kingdom Sports Drink Market | 2026-2036
United Kingdom Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Sports Drink Market Analytics
Supermarket shelf space allocation is reconfiguring as health-conscious shoppers migrate toward functional beverages. Lucozade leverages its heritage positioning to sustain prominent placement in Tesco and Sainsbury's hydration aisles. Britvic plc anchors the convenience channel through its existing soft drink distribution network, while Science in Sport plc specializes in pharmacy and health food shop placements where premium sports nutrition commands higher margins.
Sports drinks are formulated aqueous solutions containing electrolytes, carbohydrates typically at six to eight percent concentration, and flavoring agents designed to replace fluid and energy losses during physical exertion. Isotonic formulations, where osmolarity matches human blood plasma at approximately 275 to 295 mOsm/kg, dominate mass-market positioning due to balanced absorption rates. The energy gel segment records the fastest growth trajectory as endurance athletes seek concentrated carbohydrate delivery in portable formats, while supermarket distribution channels capture the largest margin pool through high-volume, low-turnover inventory models.
The Food Standards Agency enforces compositional standards for sports drinks sold in England, Scotland, Wales and Northern Ireland, while HM Revenue and Customs administers the Soft Drinks Industry Levy that penalizes high-sugar formulations. These frameworks compel manufacturers to reformulate with alternative sweeteners or accept reduced price competitiveness. Stakeholders must monitor pending consultations on front-of-pack labeling rules that could reshape purchase decisions in grocery retail environments.
Market Dynamics
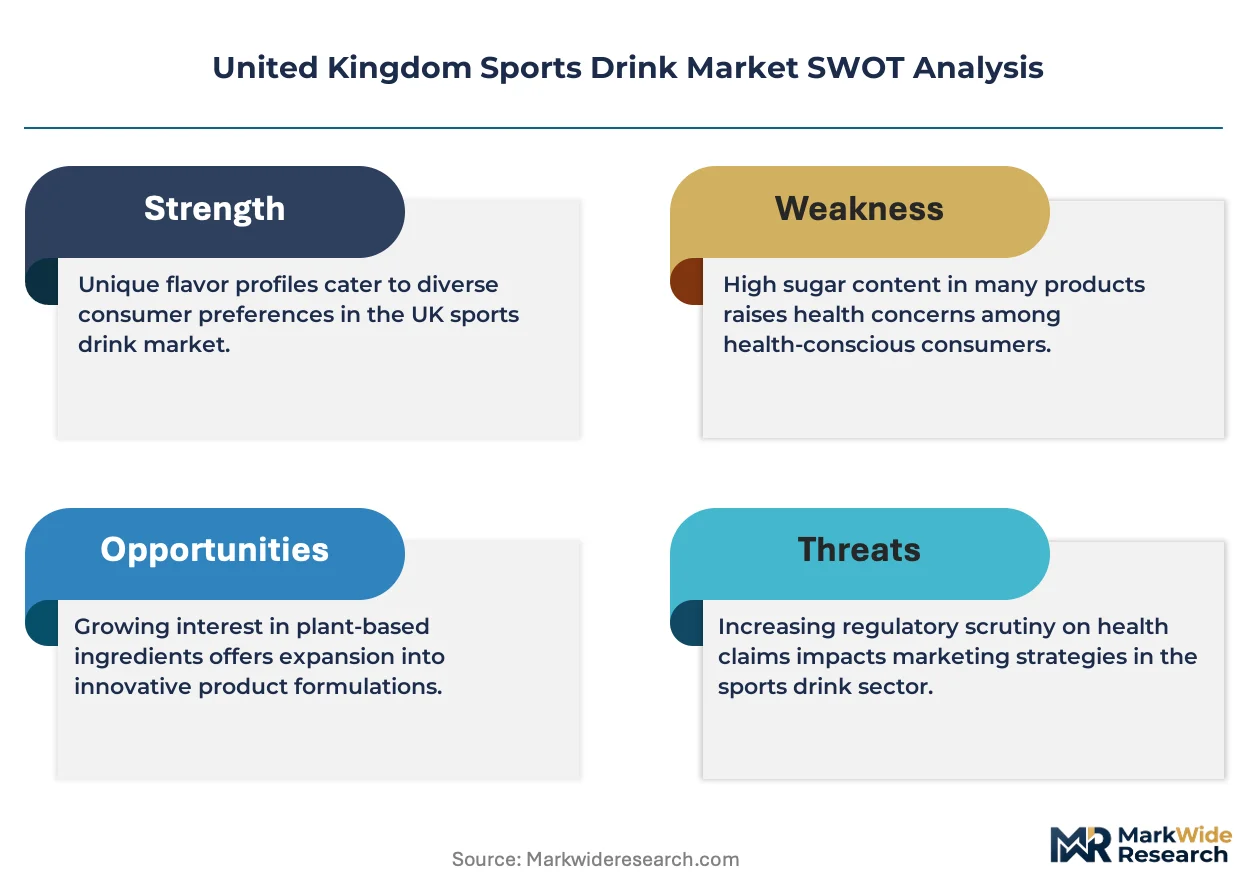
The Soft Drinks Industry Levy administered by HM Revenue and Customs is forcing manufacturers to strip sugar content from formulations while preserving palatability, creating a technical race among UK beverage producers to maintain shelf position without sacrificing taste profiles.
Growth Catalysts
- Elite training infrastructure:Professional football clubs and rugby academies across Greater Manchester and London are expanding dedicated sports nutrition budgets, creating institutional demand for isotonic formulations.
- Sugar tax compliance:The Soft Drinks Industry Levy incentivizes reformulation investment, rewarding early movers with sustained supermarket shelf space allocation in Tesco and Sainsbury's hydration aisles.
- Energy gel portability:Endurance athletes in the North West and South East are driving concentrated carbohydrate delivery formats that bypass traditional bottled distribution constraints.
Market Restraints
- Alternative sweetener cost volatility:Stevia and monk fruit extract prices fluctuate with agricultural yields, compressing margin recovery from reformulated low-sugar lines.
- Convenience channel concentration:Britvic plc's existing soft drink distribution network dominates forecourt and impulse locations, limiting challenger brand physical access.
- Functional beverage substitution:Kombucha and electrolyte-enhanced waters in health food shops capture crossover consumers seeking fermentation-derived benefits.
Strategic Opportunities
- Pharmacy channel expansion:Science in Sport plc's established placement in Boots and independent pharmacies demonstrates premium pricing tolerance that mass-market brands have not exploited.
- Front-of-pack labeling tailwind:Pending Food Standards Agency consultations on nutritional signage could advantage brands with cleaner ingredient decks in grocery retail environments.
- Hybrid consumption occasions:Office workers in London's Square Mile are adopting sports drinks for afternoon hydration, blurring the traditional athletic-use boundary.
Industry Challenges
- Reformulation R&D timelines:Achieving isotonic osmolarity at 275 to 295 mOsm/kg with alternative sweeteners requires extended sensory testing cycles that delay product launches.
- Cross-channel inventory synchronization:Supermarket high-volume, low-turnover models clash with pharmacy premium, slow-velocity requirements, complicating supply chain configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Sports Drink Market |
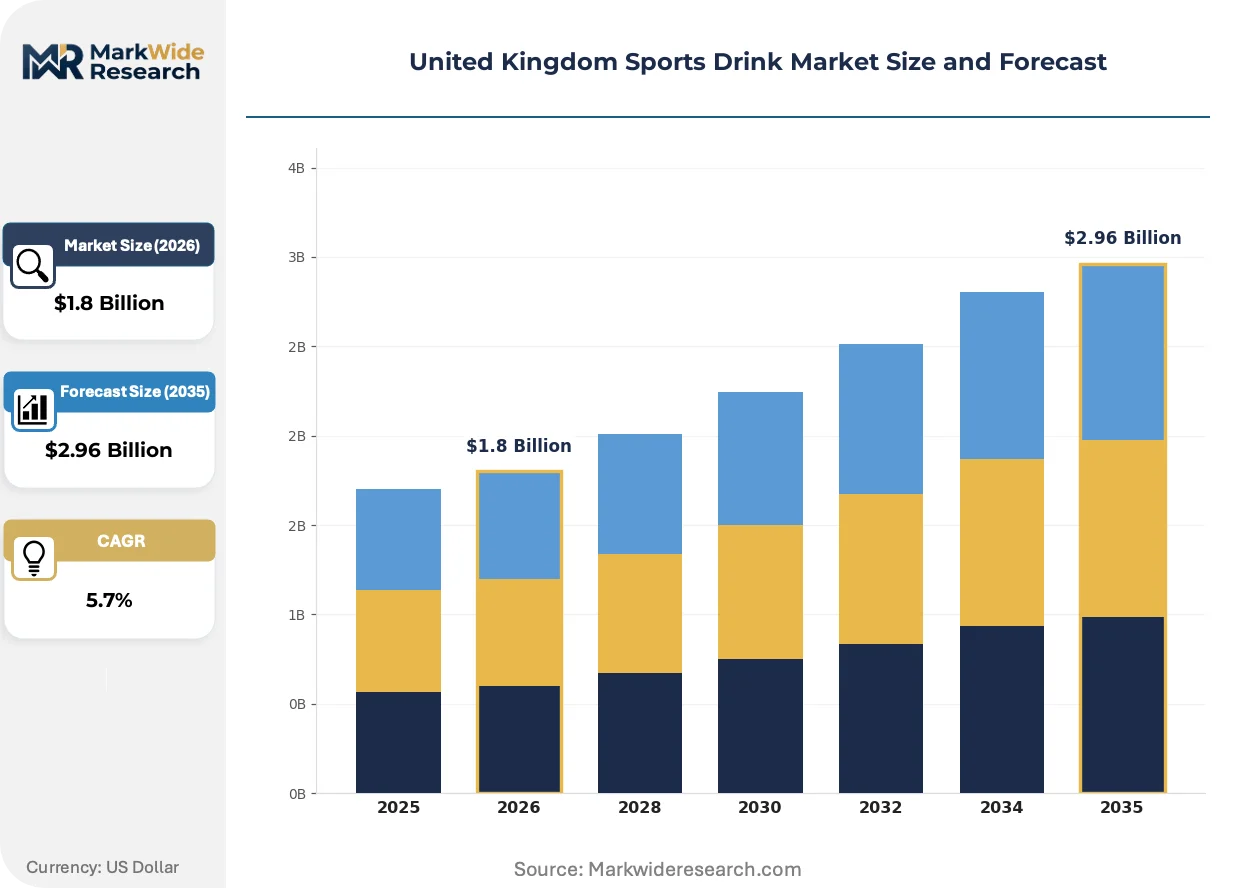
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Energy Gel End User: Athletes, Fitness Enthusiasts, Casual Consumers, Sports Teams Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Flavor Profile: Citrus, Berry, Tropical, Others |
| Companies Covered | Science in Sport plc, Red Bull GmbH, PepsiCo Inc., Carabao Group, Congo Brands, The Coca-Cola Company, Suntory Holdings Ltd, Lucozade, Britvic plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Sports Drink Market Evolving Landscape
Formulation science and retail channel evolution are compressing traditional category boundaries. Manufacturers now compete on biochemical precision and placement flexibility rather than brand heritage alone.
Electrolyte-carbohydrate matrices are hybridizing with nootropic and adaptogenic compounds. Endurance athletes and amateur gym-goers in the South East are adopting these enhanced formulations at accelerating rates. The technology is hybridizing recovery and cognitive performance claims into single-SKU solutions that command pharmacy-tier margins.
HM Revenue and Customs enforcement of the Soft Drinks Industry Levy tightens quarterly. High-sugar legacy formulations face progressive price disadvantages against reformulated competitors. Mass-market isotonic lines in Greater London supermarkets are responding with accelerated stevia and allulose transitions to preserve volume.
Health-conscious shoppers now prioritize functional ingredient transparency over calorie counts. Traditional sports drink placement in convenience channels is yielding to pharmacy and health food shop discovery journeys. This behavioral pivot concentrates in Greater London and the North West, where fitness club density and wellness retail overlap most intensely.
United Kingdom Sports Drink Market Segmentation
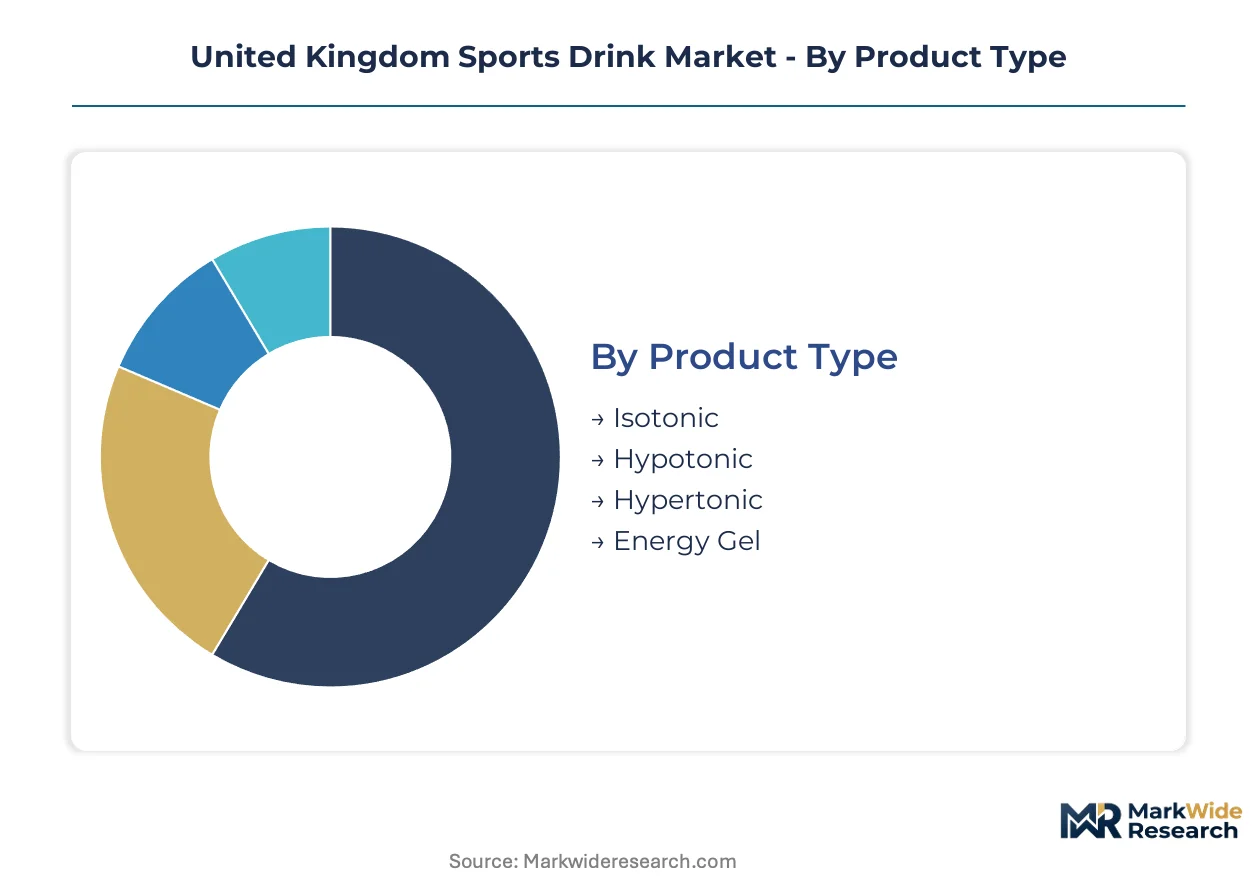
Sports drink segmentation in the United Kingdom reflects divergent hydration strategies across athletic intensity levels and retail channel economics. Formulation osmolarity, end-user physiology, and distribution margin structures create distinct competitive battlegrounds that manufacturers must navigate simultaneously.
Product Type:
Use-case spectrum spans rapid rehydration for casual exercisers to concentrated fuel delivery for endurance specialists, with osmolarity defining absorption speed and gastric tolerance.
- Isotonic:Formulations match blood plasma osmolarity at 275 to 295 mOsm/kg, enabling balanced fluid and electrolyte absorption without digestive distress. Premier League football academies in Greater Manchester and London specify isotonic protocols for training-ground hydration stations, driving institutional procurement volumes.
- Energy Gel:Concentrated carbohydrate matrices at 20-40% solids bypass fluid volume constraints during prolonged exertion. Marathon runners and triathletes in the South East are expanding gel consumption fastest as race-day fueling strategies professionalize.
- Hypotonic:Lower solute concentration accelerates gastric emptying for rapid rehydration without energy delivery. Recreational gym-goers in urban fitness clubs favor these for sub-60-minute sessions.
- Hypertonic:High carbohydrate density prioritizes energy replenishment over hydration speed. Post-exercise recovery protocols in rugby academies utilize hypertonic formulations for glycogen restoration.
Established volume favors isotonic formulations; emerging adoption favors energy gel portability.
End User:
Customer maturity gradients separate performance-optimized institutional buyers from price-sensitive occasional purchasers.
- Sports Teams:Professional football and rugby organizations negotiate bulk supply contracts with formulation customization. Budget expansion at West Midlands and North West training facilities is institutionalizing sports nutrition as competitive infrastructure.
- Fitness Enthusiasts:Regular gym attendees and amateur endurance athletes demonstrate premium pricing tolerance for pharmacy-tier positioning. Boots placement and subscription delivery models capture this cohort in Greater London.
- Athletes:Individual competitive performers seek batch-tested, contaminant-free certifications for anti-doping compliance. Science in Sport plc's Informed Sport accreditation dominates this specification-sensitive segment.
- Casual Consumers:Health-conscious shoppers purchasing for taste and perceived wellness benefits rather than performance optimization. Supermarket promotional cycles and sugar-tax-compliant labeling drive purchase decisions.
Institutional procurement concentrates with sports teams; margin expansion concentrates with fitness enthusiasts.
Distribution Channel:
Channel economics dictate inventory velocity requirements and promotional investment intensity.
- Supermarkets:Tesco and Sainsbury's hydration aisles allocate shelf space by volume turnover and sugar-tax compliance status. Lucozade leverages heritage positioning to defend prominent placement against reformulated challengers.
- Health Food Shops:Premium positioning tolerates slower inventory turns in exchange for higher unit margins. Kombucha and electrolyte-enhanced waters compete for crossover consumers seeking fermentation-derived benefits.
- Online Retail:Subscription models and bulk purchasing reduce per-unit logistics costs for committed athletes. Direct-to-consumer channels bypass convenience network gatekeeping.
- Convenience Stores:Impulse-driven, single-serve purchases at forecourts and transport hubs. Britvic plc's existing soft drink distribution network dominates physical access in this channel.
Volume concentration favors supermarkets; margin rate favors health food shops.
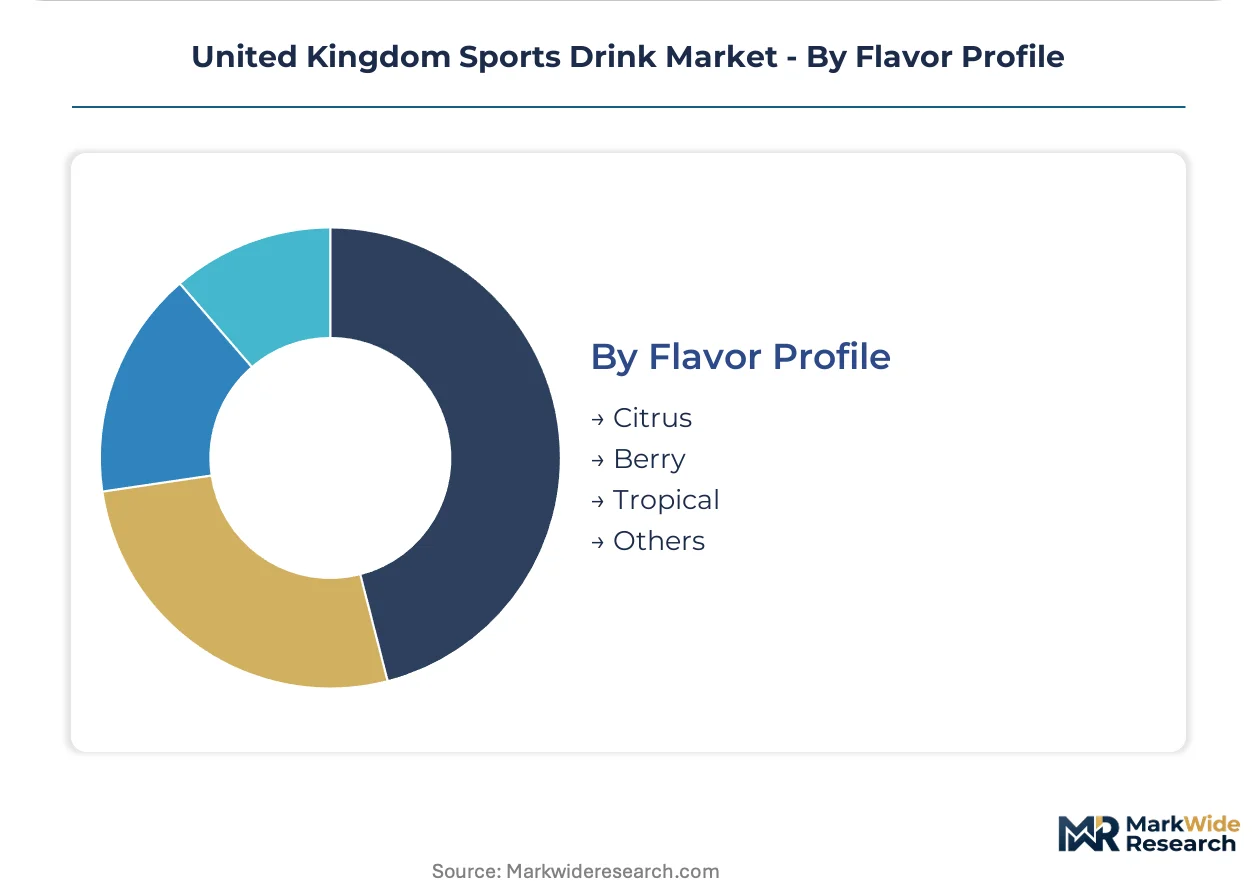
Flavor Profile:
Palatability engineering must overcome alternative sweetener aftertaste challenges while maintaining consumer recognition.
- Citrus:Lemon-lime and orange variants dominate isotonic formulations with established taste familiarity. Reformulation with stevia and allulose preserves citrus profiles in sugar-tax-compliant lines.
- Berry:Raspberry and mixed berry positioning targets female fitness enthusiasts and younger demographics. Energy gel formats favor berry for masking concentrated carbohydrate sweetness.
- Tropical:Pineapple and passionfruit variants differentiate premium offerings in pharmacy and health food channels. Limited edition tropical releases drive trial among casual consumers.
- Others:Cola, watermelon, and exotic botanical blends occupy niche positioning. Functional ingredient additions such as nootropic compounds pair with neutral base flavors.
Mainstream penetration favors citrus; differentiation investment favors berry and tropical variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HM Revenue and Customs anchors the United Kingdom's sports drink regulatory environment through the Soft Drinks Industry Levy, which shapes formulation decisions and shelf placement economics across England, Scotland, Wales and Northern Ireland. Demand concentrates in metropolitan training clusters where professional sports infrastructure and fitness club density overlap.
Greater London
Professional football academies in Chelsea and Tottenham Hotspur training grounds drive institutional procurement of isotonic formulations. The Food Standards Agency enforces compositional standards that mandate electrolyte disclosure on front-of-pack labels. Canary Wharf office workers are adopting sports drinks for afternoon hydration, blurring traditional athletic-use boundaries in the Square Mile.
North West England
Manchester United and Liverpool FC training facilities are expanding dedicated sports nutrition budgets for academy athletes. The Soft Drinks Industry Levy incentivizes reformulation investment among manufacturers supplying this region. Elite rugby academies in Greater Manchester specify hypertonic recovery protocols, creating distinct procurement specifications from football-focused buyers.
West Midlands
Aston Villa and Wolverhampton Wanderers football clubs are institutionalizing sports nutrition as competitive infrastructure. HM Revenue and Customs quarterly enforcement tightening affects legacy formulation pricing in Birmingham retail channels. Rugby training facilities in Coventry and Leicester are adopting batch-tested, contaminant-free certifications for anti-doping compliance.
South East England
Marathon runners and triathletes in Brighton and Southampton are expanding energy gel consumption fastest as race-day fueling strategies professionalize. The Food Standards Agency pending consultations on nutritional signage could advantage cleaner ingredient decks in grocery retail environments. Endurance athlete communities in Kent are driving subscription delivery models that bypass convenience network gatekeeping.
Scotland
Rugby academies in Edinburgh and Glasgow are expanding sports nutrition budgets alongside professional football club infrastructure. The Soft Drinks Industry Levy applies uniformly across Scottish retail channels, pushing reformulation timelines identical to England. Highland endurance cycling communities are adopting concentrated carbohydrate delivery formats that bypass traditional bottled distribution constraints.
United Kingdom Sports Drink Market Competitive Landscape
Heritage beverage conglomerates and specialized sports nutrition firms split the United Kingdom sports drink market along channel and formulation lines. Market structure reflects dual consolidation pressures: supermarket shelf space allocation favors volume-scale suppliers, while pharmacy and health food channels reward certification-heavy specialists. Three archetypes dominate: legacy soft drink multinationals with reformulated portfolios, dedicated sports nutrition pure-plays with anti-doping accreditation, and energy drink crossovers leveraging caffeine-hybrid positioning. Competitive moves center on sugar-tax-compliant reformulation speed and pharmacy channel expansion.
Within the specialized sports nutrition tier, Science in Sport plc exemplifies the certification-driven archetype through its Informed Sport accreditation and pharmacy-first placement strategy. Britvic plc anchors the convenience channel dominance archetype, leveraging existing soft drink distribution networks for forecourt and impulse location access. Lucozade occupies the heritage repositioning archetype, defending prominent supermarket placement in Tesco and Sainsbury's hydration aisles through reformulated low-sugar transitions.
| Leading Market Players |
|---|
| Science in Sport plc |
| Red Bull GmbH |
| PepsiCo Inc. |
| Carabao Group |
| Congo Brands |
| The Coca-Cola Company |
| Suntory Holdings Ltd |
| Lucozade |
| Britvic plc |
| Others |
Value Network & Pricing Analysis
Alternative sweetener cost volatility determines both tiered pricing spreads and supply chain configuration across the United Kingdom sports drink market. Stevia and monk fruit extract price swings compress margin recovery in reformulated low-sugar lines while forcing manufacturers into longer-term agricultural sourcing contracts.
Pricing Analysis
Customization-premium spreads separate institutional bulk contracts from standard retail pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with Science in Sport plc's Informed Sport accreditation commanding pharmacy-tier premiums. Pricing pressure stems from HM Revenue and Customs Soft Drinks Industry Levy enforcement, accelerating stevia transition costs. Casual consumers in supermarket channels exhibit highest price sensitivity; professional sports teams demonstrate lowest sensitivity due to performance-linked procurement specifications.
Supply Chain Analysis
Supplier-financing facilities extend payment terms for stevia processors in China and monk fruit extract suppliers in Southeast Asia. Raw material dependencies center on citric acid from Belgium, flavor compounds from Switzerland, and maltodextrin from the Netherlands. Single-source vulnerability concentrates in stevia leaf supply chains where agricultural yield fluctuations create inventory volatility. Distribution runs through Britvic plc's convenience network for impulse channels and Tesco's centralized distribution centers for supermarket volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reformulation chemistry expertise scarcity constrains competitive response speed. Brands lacking in-house sensory science capabilities face extended product launch timelines against levy-compliant rivals.
For Market Incumbents: Entrench pharmacy channel control through Boots placement expansion and Informed Sport certification investment. Accelerate backward integration into stevia processing to buffer agricultural price volatility. Defend against kombucha substitution by hybridizing electrolyte matrices with nootropic compounds. For New Entrants and Emerging Players: Pursue white-space in hybrid consumption occasions among Canary Wharf office workers seeking afternoon hydration solutions. Target underexploited health food shop channels in Scotland where fitness club density overlaps wellness retail concentration. Deploy subscription direct-to-consumer models bypassing Britvic plc's convenience network gatekeeping. For Investors and Strategic Acquirers: Pending Food Standards Agency front-of-pack labeling consultations reshape the acquisition landscape toward brands with cleaner ingredient decks. Five-to-ten-year viability favors certification-heavy specialists over heritage soft drink conglomerates dependent on reformulation speed. Target acquisition archetype: vertically integrated mid-cap specialists with captive stevia sourcing and pharmacy channel contracts. Signal to monitor: quarterly HM Revenue and Customs enforcement tightening against high-sugar legacy formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Acceleration | HM Revenue and Customs levy compliance preserves supermarket shelf space allocation against challengers. |
| Pharmacy Channel Expansion | Boots placement unlocks premium pricing tolerance unavailable in convenience retail environments. |
| Certification Investment | Informed Sport accreditation captures specification-sensitive athletes and institutional procurement contracts. |
| Subscription Model Launch | Direct-to-consumer channels bypass Britvic plc's forecourt distribution dominance for committed athletes. |
| Hybrid Formulation Development | Nootropic-electrolyte matrices command pharmacy-tier margins from office worker crossover segments. |
Research Methodology
Operator-level perspectives from sports nutrition formulators, pharmacy category buyers, supermarket hydration aisle managers, and HM Revenue and Customs policy specialists anchored the qualitative base. Primary interviews triangulated with secondary validation from Food Standards Agency consultation documents, Nielsen retail audit data, customs import records for stevia and monk fruit extracts, and SEC filings of listed beverage conglomerates. Bottom-up volume modeling across formulation types integrated with top-down market sizing from trade association aggregates.
Scenario-bracketing framed demand projections across the analysis window, modeling isotonic, energy gel, hypotonic, and hypertonic segments alongside distribution channel economics and end-user maturity gradients. CAGRs derived from segment-level growth rate reconciliation with macro consumption trend analysis. Forecast inputs incorporated Soft Drinks Industry Levy compliance timelines, front-of-pack labeling consultation outcomes, and elite training facility budget expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, agricultural commodity prices, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about levy compliance rates and reformulation adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Medicated Fitness Supplements Market