
 Triathlon Bikes Market | 2026-2036
Triathlon Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Triathlon Bikes Market Insights
Age-group amateur competitors is reorganizing demand patterns across the triathlon bikes landscape, pulling manufacturers toward more accessible price-performance tiers. Cervelo leverages its aerodynamic engineering heritage to dominate the high-performance professional segment while sustaining premium positioning. Trek competes through extensive dealer networks and in-house carbon fiber manufacturing that controls quality and lead times. Specialized differentiates via its Retul fit system integration, linking bike geometry to individual biomechanics.
Triathlon bikes are purpose-built time-trial machines optimized for aerodynamic efficiency across swimming, cycling, and running disciplines, typically featuring steep seat tube angles of 76-78 degrees to preserve running muscles and integrated hydration systems that reduce drag. Carbon fiber frames command the largest margin pool due to layup complexity and brand-proprietary molding processes, while electronic shifting configurations represent the fastest-growing gear category as wireless protocols eliminate cable maintenance and enable mid-race adjustment. Amateur competitors now drive volume expansion in adjustable geometry designs that accommodate fit evolution without frame replacement.
The U.S. Consumer Product Safety Commission enforces frame integrity standards that shape carbon fiber layup specifications and testing protocols, while the UCI equipment regulations indirectly constrain design parameters even for non-drafting triathlon events. ISO 4210 bicycle safety standards govern fork fatigue and frame impact resistance across export markets, creating compliance cost barriers for smaller assemblers. Stakeholders must monitor how evolving disc brake integration standards and emerging e-bike classification debates reshape product roadmaps and distribution eligibility across key cycling markets.
Market Dynamics
Amateur age-group athletes are compressing the traditional performance-to-price hierarchy, forcing manufacturers to engineer aerodynamic gains at accessible price points while maintaining professional-tier credibility. This demand democratization is restructuring R&D allocation across carbon fiber layup complexity and electronic shifting integration.
Growth Catalysts
- ISO 4210 bicycle safety standards:Harmonized frame fatigue and impact testing protocols across export markets reduce certification duplication for mid-tier assemblers, accelerating product launch velocity in Germany and Japan.
- Carbon fiber monocoque molding:Automated fiber placement and bladder molding techniques are cutting frame production cycle times by half, enabling faster inventory turns for specialty retailers.
- Ironman-branded event expansion:Sanctioned race calendar density in Texas, California, and Florida is shortening replacement cycles as participants upgrade equipment to match competitive aspirations.
Market Restraints
- Prepreg carbon fiber supply concentration:Toray, Mitsubishi Chemical, and Hexcel control 70% of aerospace-grade fiber supply, exposing bike manufacturers to allocation rationing during automotive and wind energy demand surges.
- UCI equipment regulations:Frame geometry restrictions originally drafted for mass-start road racing constrain triathlon-specific innovation even in non-drafting events, limiting seat tube angle experimentation.
- Direct-to-consumer assembly complexity:Integrated cable routing and hydraulic brake bleeding require technical competency that amateur buyers often lack, elevating return rates and warranty claim costs.
Strategic Opportunities
- Adjustable geometry platforms:Modular head tube and seat post systems allow fit evolution without frame replacement, capturing repeat purchase intent from maturing amateur competitors.
- India's emerging triathlon federation:Nascent age-group racing infrastructure in Goa and Mumbai offers first-mover positioning before established brands establish dealer density.
- Wireless electronic shifting convergence:ANT+ and Bluetooth protocol standardization is decomposing proprietary ecosystem lock-in, opening component sourcing flexibility for smaller frame builders.
Industry Challenges
- Bike fit specialist scarcity:Retul, Serotta, and F.I.S.T.-certified fitters concentrate in metropolitan clusters, creating service deserts that limit confident purchasing in secondary markets.
- Disc brake integration timelines:Frame and fork redesign cycles lag behind component availability, forcing manufacturers to manage multiple brake standard configurations simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triathlon Bikes Market |
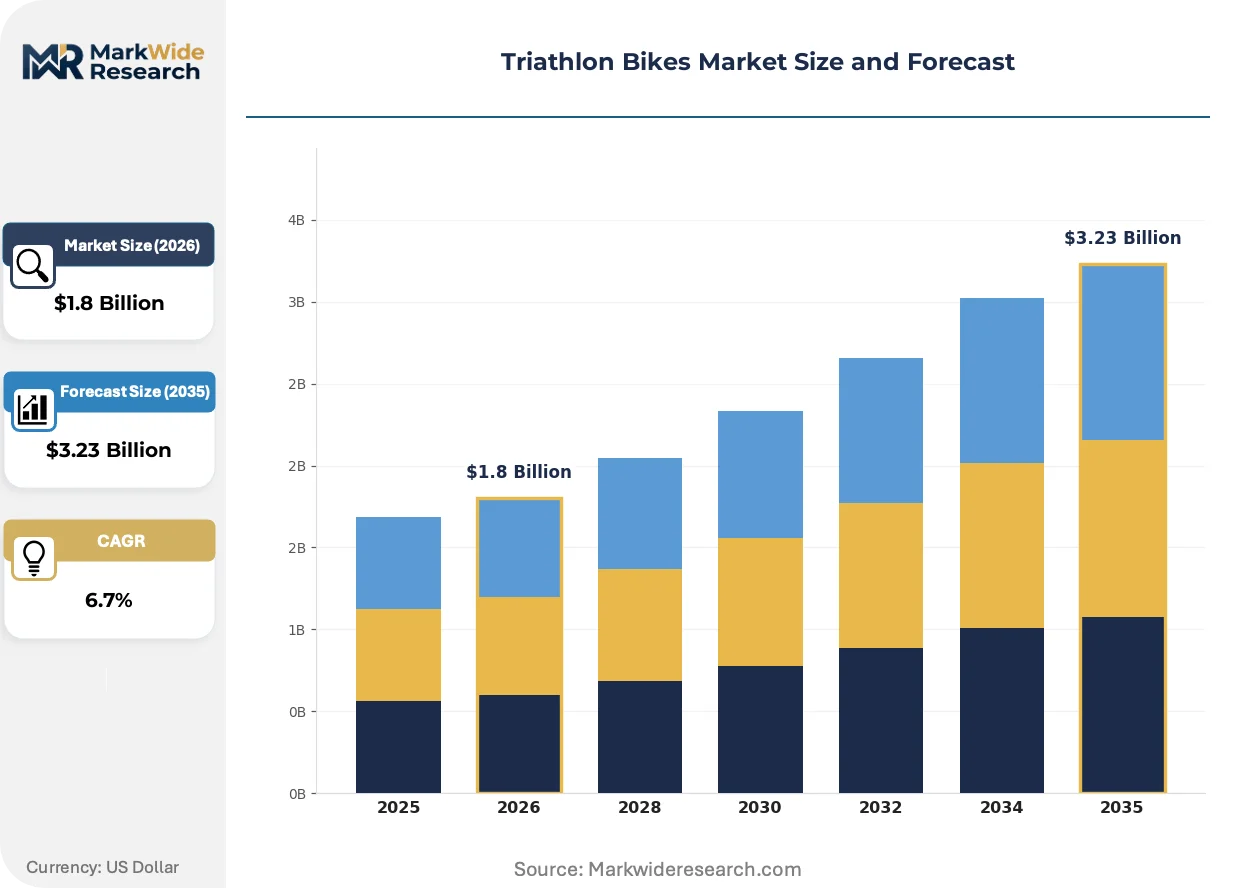
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Aluminum, Titanium, Steel Design Feature: Aerodynamic Frame, Adjustable Geometry, Integrated Storage, Disc Brakes Gear Configuration: Single Speed, 2x Drivetrain, 1x Drivetrain, Electronic Shifting Target User: Professional Athletes, Amateur Competitors, Leisure Riders, Triathlon Clubs |
| Companies Covered | Cervelo, Canyon, Trek, Quintana Roo, Felt, Specialized, Giant, BMC, Cadex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triathlon Bikes Market Trends and Innovations
Computational fluid dynamics and additive manufacturing are collapsing the traditional prototyping-to-production timeline, enabling rapid iteration on tube shaping and component integration. These tools are redistributing competitive advantage from scale economies toward design agility.
Aerodynamic frame architecture is decomposing the historical trade-off between stiffness and weight. Toray T1100G carbon fiber with nano-alloy resin systems permits thinner wall sections without sacrificing pedaling efficiency. Age-group competitors in Arizona and Colorado are adopting these platforms at rates previously reserved for professional teams. The technology is decomposing price-performance segmentation by delivering wind tunnel-validated shapes at mid-tier price points.
REACH substance restrictions on epoxy resin hardeners are forcing reformulation of carbon fiber prepregs used in European-market frames. Manufacturers serving Germany and the Netherlands must validate alternative curing agents that maintain Tg (glass transition temperature) thresholds for safety compliance. Frame builders with captive prepreg development capabilities are capturing share from assemblers dependent on third-party suppliers.
Club-based purchasing collectives are aggregating amateur demand to negotiate volume pricing previously inaccessible to individual buyers. Triathlon clubs in Sydney and Melbourne are coordinating seasonal orders through designated shop partners, compressing traditional retail margin structures. This behavior is most visible in Australia, where national federation membership links directly to retail partnership programs.
Triathlon Bikes Market Segmentation
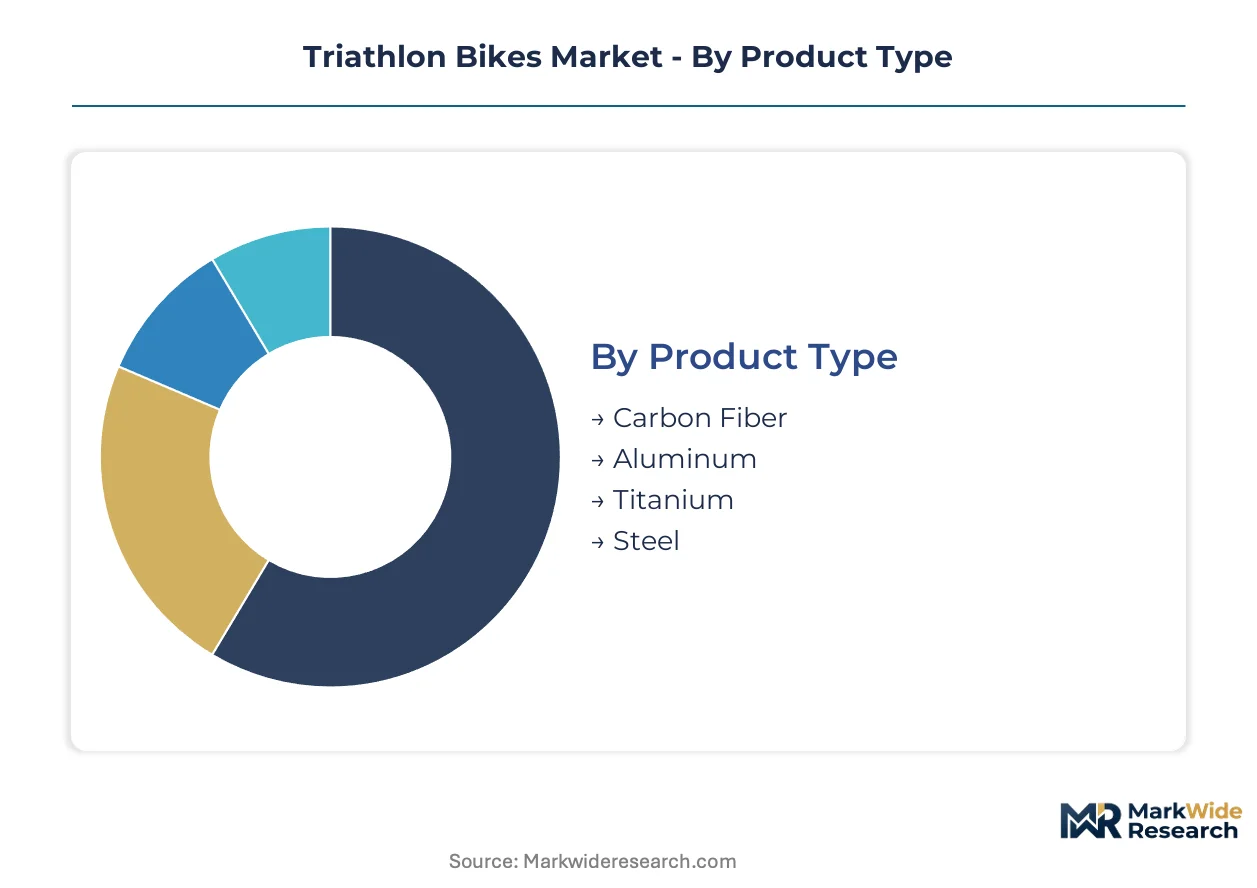
Triathlon bike segmentation reveals how material science, fit technology, and price-performance tiers fragment purchasing behavior across athlete maturity levels. Manufacturers must align R&D portfolios with where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Carbon fiber commands the deepest margin pools due to layup complexity and brand-proprietary molding processes that sustain premium positioning.
- Carbon Fiber:Toray T1100G and nano-alloy resin systems enable sub-900 gram frame weights with aerodynamic tube shaping validated in wind tunnels. Demand concentrates in Arizona and Colorado among age-group competitors seeking professional-tier equipment without sponsorship support.
- Aluminum:Hydroformed 6061-T6 and 7005 alloys deliver entry-level aerodynamic profiles at one-third the carbon cost. Volume expansion is accelerating in Texas and Florida where first-time Ironman participants prioritize durability over marginal weight savings.
- Titanium:Cold-worked 3Al-2.5V tubing offers fatigue resistance and ride quality for long-course specialists. The segment serves durability-focused buyers in coastal humidity markets.
- Steel:Chromoly double-butted frames persist in custom builder niches and retro-styled endurance builds. Artisan frame shops in Oregon and Pennsylvania sustain this legacy category.
Carbon fiber holds installed capacity. Aluminum is rotating up the share rankings.
Design Feature:
Adjustable geometry platforms are capturing repeat purchase intent as fit evolution eliminates frame replacement cycles.
- Aerodynamic Frame:Computational fluid dynamics-optimized tube profiles with truncated airfoil shapes reduce drag coefficients below 0.30 Cd. Integration with hydration systems and storage boxes preserves laminar flow across the complete bike-rider system.
- Adjustable Geometry:Modular head tube stacks and reversible seat posts accommodate 20mm+ fit range changes without component swaps. Amateur competitors in California and New York are adopting these platforms at rates previously reserved for professional fitting studios.
- Integrated Storage:Bento boxes, downtube bottles, and rear hydration systems molded into frame architecture eliminate accessory drag penalties. The feature is becoming standard in complete bike offerings rather than aftermarket add-ons.
- Disc Brakes:Flat-mount and post-mount standards with 140-160mm rotors deliver consistent modulation in wet conditions and steep descents. Frame redesign cycles are lagging component availability, forcing manufacturers to manage multiple brake configurations.
Aerodynamic frame configurations hold installed capacity. Adjustable geometry is climbing the fastest.
Gear Configuration:
Electronic shifting integration is decomposing proprietary ecosystem lock-in as wireless protocol standardization accelerates.
- Electronic Shifting:ANT+ and Bluetooth-enabled derailleurs eliminate cable maintenance and enable mid-race gear adjustment from handlebar-mounted controls. Demand is expanding most quickly among amateur age-group athletes seeking professional-tier functionality.
- 1x Drivetrain:Single chainring with wide-range cassettes simplifies shifting logic and reduces mechanical failure points. Gravel-adjacent triathletes in Colorado and Utah favor this configuration for hilly courses.
- 2x Drivetrain:Traditional double chainring preserves tight gear spacing for flat, fast courses and time-trial specialists. The configuration maintains dominance in draft-legal Olympic-distance racing.
- Single Speed:Fixed-gear and freewheel builds persist in urban triathlon training and velodrome crossover applications. Niche demand concentrates in metropolitan cycling clubs.
2x drivetrain holds installed capacity. Electronic shifting is gaining share fastest.
Target User:
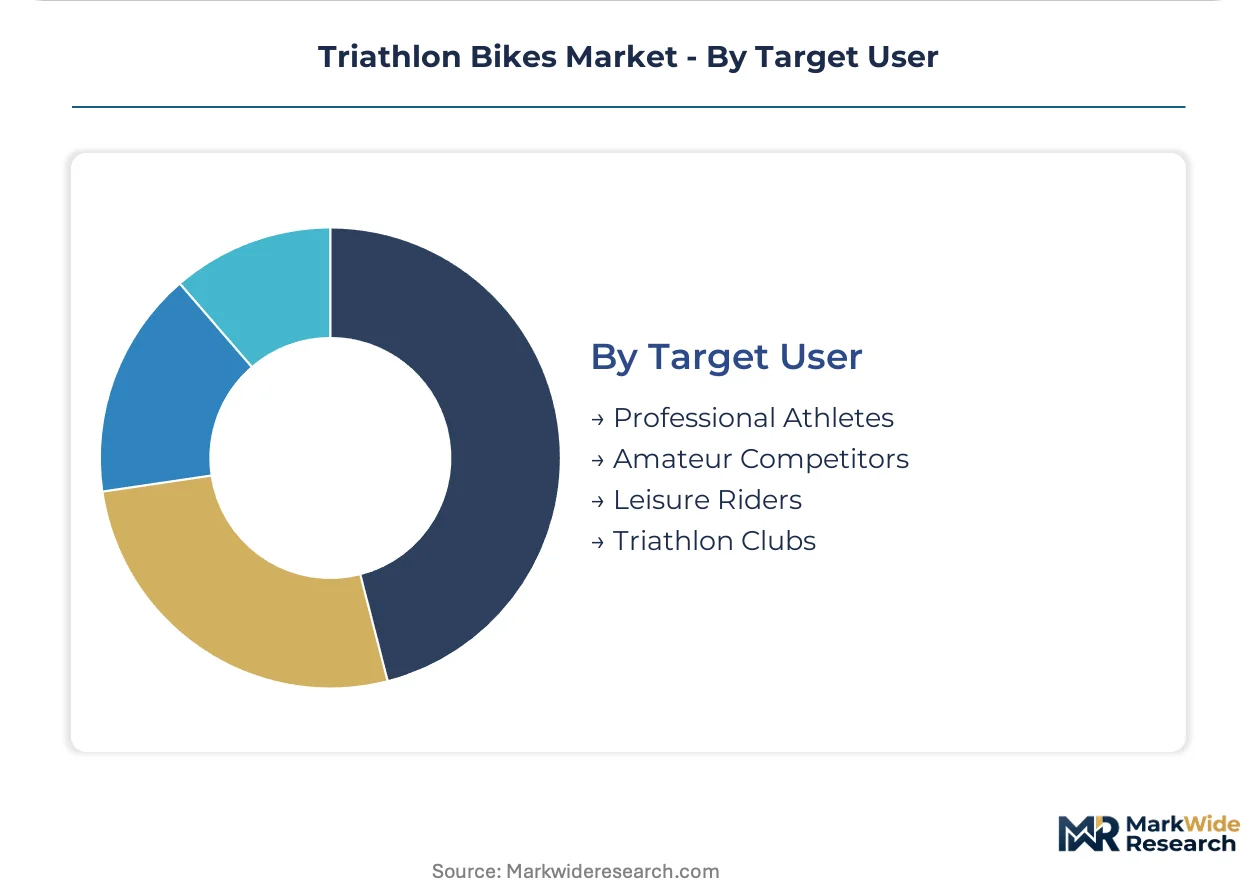
Amateur competitors are reorganizing demand patterns, forcing manufacturers to engineer aerodynamic gains at accessible price points.
- Amateur Competitors:Age-group athletes without sponsorship support now drive volume expansion in adjustable geometry and electronic shifting categories. Ironman-branded event density in Texas, California, and Florida is shortening their replacement cycles.
- Professional Athletes:UCI-registered and Ironman-elite competitors require wind tunnel-validated frames with team livery and sponsor component integration. Their equipment specifications influence aspirational purchasing downstream.
- Triathlon Clubs:Aggregated purchasing collectives in Sydney and Melbourne negotiate volume pricing through designated retail partnerships, compressing traditional margin structures.
- Leisure Riders:Fitness-oriented cyclists seeking triathlon bike geometry for recreational time trials and gran fondo events. Price sensitivity in this segment favors aluminum and entry-level carbon offerings.
Professional athletes hold installed capacity. Amateur competitors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber frame manufacturing clusters in Taiwan and China supply assembly operations across three continents. Raw material sourcing from Toray facilities in Japan and the United States feeds layup operations that shape regional competitive positioning. Finished bike distribution concentrates in markets with dense Ironman event calendars and established triathlon club infrastructure.
United States
Ironman-branded event density in Texas, California, and Florida drives replacement cycles among age-group competitors seeking equipment upgrades. The Consumer Product Safety Commission enforces frame integrity standards that shape carbon fiber testing protocols and layup specifications. Greater Phoenix and Boulder clusters host specialty retailers and fitting studios that anchor regional demand concentration.
Germany
REACH substance restrictions on epoxy resin hardeners force reformulation of carbon fiber prepregs used in European-market frames. The KBA and federal environmental regulators coordinate compliance verification for alternative curing agents. Stuttgart and Munich industrial zones concentrate frame builders with captive prepreg development capabilities.
Australia
Club-based purchasing collectives in Sydney and Melbourne aggregate amateur demand to negotiate volume pricing through designated retail partnerships. The TGA oversees product safety notification requirements for imported frames and component systems. Triathlon federation membership programs link directly to retail partnership structures in southeastern coastal metros.
Japan
METI industrial policy supports domestic carbon fiber supply chain resilience through Toray's aerospace-grade fiber production facilities. JIS standards govern bicycle safety testing alongside ISO 4210 harmonization for export market access. Osaka and Nagoya manufacturing corridors supply high-modulus prepregs to frame assemblers serving Asia-Pacific demand.
United Kingdom
Triathlon participation growth in London and southeast England drives demand for adjustable geometry platforms accommodating fit evolution. The Health and Safety Executive coordinates with trading standards on frame fatigue testing enforcement. Manchester and Bristol clusters host specialty distributors serving age-group competitors in northern and western regions.
Triathlon Bikes Market Competitive Landscape
Concentration sits with vertically integrated frame builders controlling carbon fiber layup operations and proprietary molding processes. Mid-tier assemblers dependent on third-party prepreg suppliers face margin compression from aerospace and automotive fiber allocation competition. Two strategic archetypes dominate: heritage engineering specialists leveraging aerodynamic R&D legacies, and scale manufacturers with captive supply chains and extensive dealer networks. Competitive moves center on adjustable geometry platform development and electronic shifting integration partnerships.
Within the heritage engineering tier, Cervelo and Quintana Roo exemplify aerodynamic-focused positioning rooted in time-trial machine optimization. Canyon and Giant occupy scale-driven positions with direct-to-consumer and dealer network distribution models respectively. Trek anchors the integrated manufacturing archetype through in-house carbon fiber production controlling quality and lead times. Specialized represents the fit-technology vector linking biomechanical assessment to frame geometry selection.
| Leading Market Players |
|---|
| Cervelo |
| Canyon |
| Trek |
| Quintana Roo |
| Felt |
| Specialized |
| Giant |
| BMC |
| Cadex |
| Others |
Pricing and Supply Chain Analysis
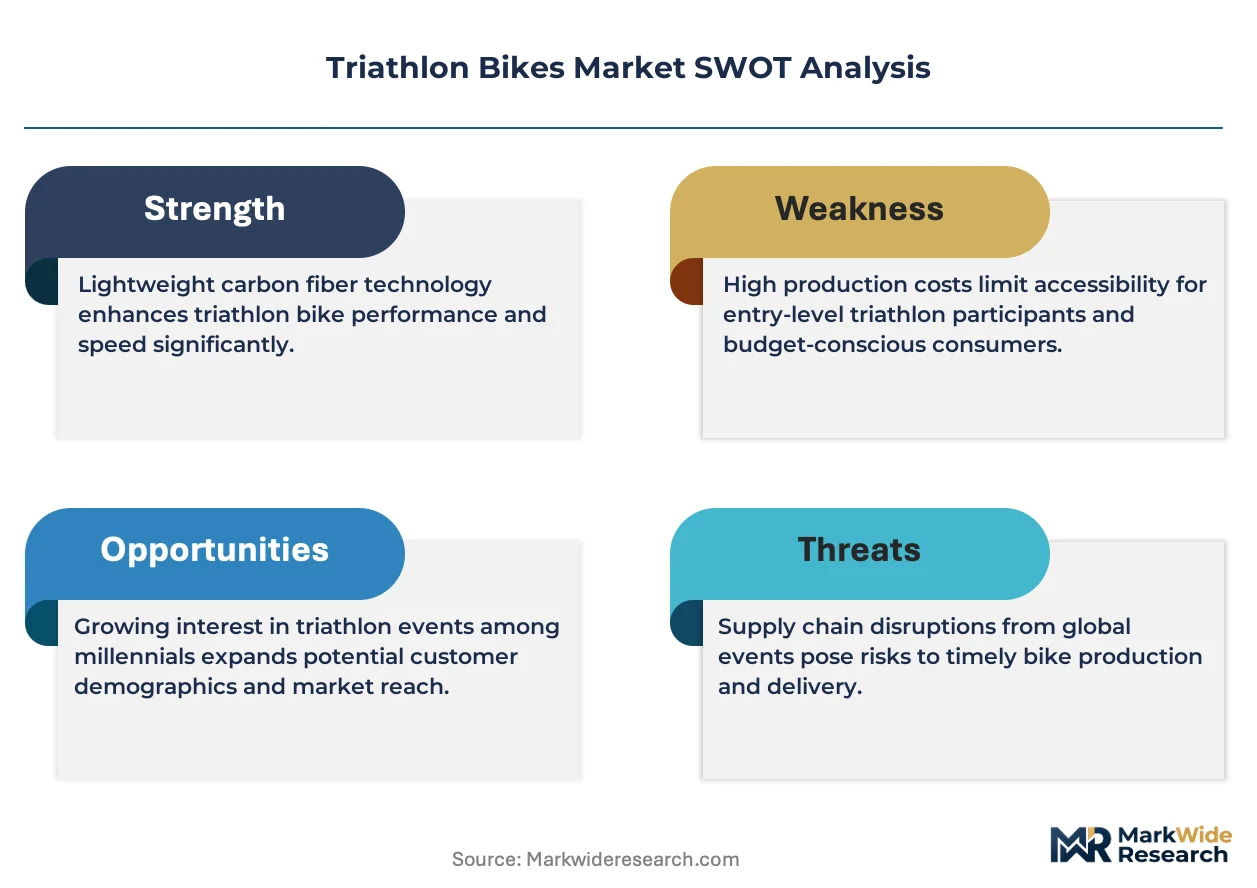
Long-term offtake contracts for Toray T1100G carbon fiber lock in both supply access and price visibility for frame builders, insulating premium manufacturers from aerospace allocation rationing while exposing mid-tier assemblers to spot-market volatility when automotive demand surges.
Pricing Analysis
ISO 4210 bicycle safety standards dictate the pricing tier structure by imposing compliance cost barriers that stratify manufacturers across certification-capable premium builders and uncertified economy assemblers. Price differentiation hinges on wind tunnel validation investment and electronic shifting integration depth. Cost compression in entry-level carbon is intensifying because aluminum hydroforming narrows the aerodynamic performance gap. First-time Ironman participants in Texas and Florida exhibit highest price sensitivity, while age-group competitors in Arizona and Colorado absorb premium positioning for professional-tier credibility.
Supply Chain Analysis
Inventory lead times for aerospace-grade prepreg stretch 16-24 weeks during automotive demand peaks, forcing frame builders to pre-position resin systems ahead of seasonal production cycles. Manufacturing gravity centers on Taiwan, China, and Japan, where Toray facilities feed layup operations with T1100G and nano-alloy resin systems. Raw material sourcing draws from Japanese carbon fiber production, Chinese molding equipment, and German epoxy hardener alternatives compliant with REACH restrictions. Single-source vulnerability concentrates in Toray's aerospace-grade fiber allocation, which prioritizes automotive and wind energy contracts during demand spikes. Distribution runs through specialty retailers in Ironman-dense markets and direct-to-consumer channels requiring technical assembly support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward aggregated amateur demand as triathlon clubs in Sydney and Melbourne consolidate purchasing intent, fragmenting individual retail relationships and compressing traditional margin structures through volume-negotiated partnerships.
For Market Incumbents: Compound aerodynamic R&D advantages into adjustable geometry platforms that capture repeat purchase intent from maturing age-group competitors facing fit evolution without frame replacement. Threat substitution from aluminum hydroforming narrows the carbon premium justification, demanding faster inventory turns through automated fiber placement investments. Backward integration into captive prepreg development insulates margin pools from aerospace allocation competition. For New Entrants and Emerging Players: Anchor in India's nascent triathlon federation infrastructure before established brands achieve dealer density in Goa and Mumbai. The most penetrable segment sits with first-time Ironman participants seeking durability-focused aluminum platforms at accessible price points. Go-to-market execution should leverage club-based purchasing collectives rather than individual retail channels, mirroring the Sydney and Melbourne aggregation model. For Investors and Strategic Acquirers: Capital is best deployed toward frame builders with captive carbon fiber layup capabilities and proprietary molding processes that sustain premium positioning against mid-tier assemblers dependent on third-party suppliers. Long-term viability over the analysis window favors manufacturers controlling quality and lead times through in-house production. The signal to watch is wireless electronic shifting protocol standardization, which decomposes proprietary ecosystem lock-in and opens component sourcing flexibility for smaller builders.| Strategic Initiative | Industry Significance |
|---|---|
| Adjustable Geometry Platform Development | Modular systems capture repeat purchase intent from maturing amateur competitors facing fit evolution. |
| Captive Carbon Fiber Layup Investment | In-house production insulates margin pools from Toray aerospace allocation rationing during demand surges. |
| Wireless Electronic Shifting Integration | ANT+ and Bluetooth protocol convergence opens component sourcing flexibility beyond proprietary ecosystems. |
| Club-Based Purchasing Partnership | Aggregated demand in Sydney and Melbourne compresses retail margins while securing volume commitments. |
| REACH-Compliant Prepreg Reformulation | Alternative epoxy hardener validation maintains European market access amid substance restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and manufacturer technical documentation, combining structured interviews with frame engineering directors, specialty retailer owners, triathlon club purchasing coordinators, and carbon fiber procurement leads with bottom-up and top-down triangulation against ISO 4210 certification databases, Ironman event participation records, and Toray fiber allocation disclosures.
Segmentation dimensions modeled span material composition, design feature integration, gear configuration architecture, and target user maturity across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating age-group participation growth, replacement cycle compression, and electronic shifting adoption velocity. Industry-specific forecast inputs include wind tunnel validation investment rates and club-based purchasing collective formation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained Ironman event calendar expansion and stable aerospace-grade carbon fiber allocation to bicycle manufacturing; material deviation in triathlon participation trends or automotive demand surges would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Shuttlecock Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Golf Ball Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Golf Gloves Market