
 Windsurf Masts Market | 2026-2036
Windsurf Masts Market Size, Share, and Industry Trends Forecast 2026-2036
Windsurf Masts Market Analytics
The EU Green Deal is restructuring procurement criteria across European water sports retail channels, compelling distributors to prioritize lower-carbon supply chains. Naish leverages its integrated manufacturing footprint to meet these sourcing protocols. Severne Sails anchors its competitive position through specialized carbon fiber R&D programs. Goya differentiates via deep control over Mediterranean distribution networks.
A windsurf mast is a tapered structural spar, typically constructed from carbon fiber prepreg, aluminum alloy, or hybrid layups, engineered to transfer sail loads to the board while managing bend curve and reflex characteristics under wind stress. Carbon masts command premium positioning due to superior stiffness-to-weight ratios that professional athletes demand, while aluminum masts occupy the volume-driven rental and training segments where durability economics dominate procurement decisions. Composite and hybrid designs are capturing intermediate recreational users seeking performance upgrades without full carbon pricing.
REACH compliance and CE marking requirements govern material safety and structural integrity for masts sold across European Union member states, directly influencing resin chemistry choices and factory audit protocols. The US EPA and California's DTSC regulate composite waste streams from manufacturing, shaping domestic production location decisions. ISO 12217 small craft standards further constrain design parameters for mast-board compatibility. Stakeholders must track evolving extended producer responsibility frameworks that will determine cost allocation between manufacturers and end-of-life recyclers.
Market Dynamics
Carbon fiber prepreg supply concentration in Japan and Taiwan is constraining mast manufacturers' ability to scale production, forcing procurement teams to secure multi-year resin contracts ahead of competitive sailing seasons.
Growth Catalysts
- EU Green Deal procurement mandates:European distributors must now verify lifecycle carbon data for water sports equipment, accelerating demand for low-carbon mast manufacturing processes.
- Competitive sailing circuit expansion:Olympic and World Sailing event calendars are extending carbon mast replacement cycles as athletes prioritize stiffness-to-weight optimization.
- Hossegor-La Torche cluster density:French Atlantic coast windsurfing schools are consolidating fleet purchases, creating volume pull for rental-grade aluminum and hybrid mast configurations.
Market Restraints
- Toray carbon fiber price volatility:Aerospace demand competing for prepreg supply is elevating raw material costs for premium mast segments.
- Single-source prepreg dependency:Japanese suppliers control high-modulus fiber grades, exposing manufacturers to geopolitical shipping disruptions.
- Aluminum mast performance ceiling:Recreational users seeking bend curve precision face technical limitations that compress upgrade timelines.
Strategic Opportunities
- Mediterranean rental network expansion:Greek and Croatian island operators are modernizing fleets, opening white space for mid-tier composite mast penetration.
- Extended producer responsibility frameworks:EU member states are piloting composite recycling mandates that reward manufacturers with closed-loop material recovery systems.
- AI-assisted bend curve modeling:Computational design tools are converging with automated filament winding to reduce prototype iteration cycles.
Industry Challenges
- Filament winding technician scarcity:Specialized composite layup skills are concentrating at legacy aerospace facilities, constraining mast factory expansion.
- CE marking timeline compression:Structural integrity testing protocols for new mast geometries are extending certification cycles by 4-6 months.
- Legacy board compatibility integration:Retrofit mast-base standardization across 1990s-era equipment is fragmenting aftermarket demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windsurf Masts Market |
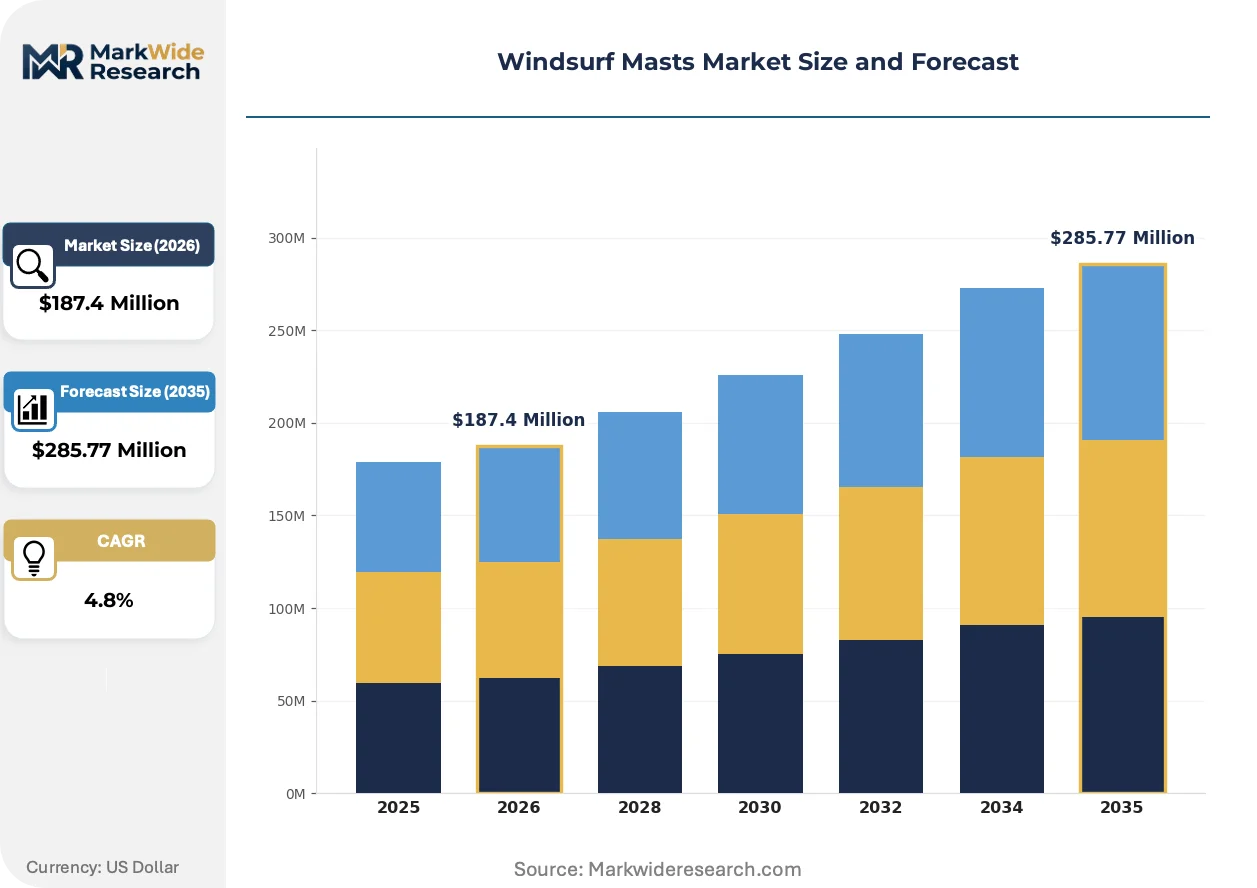
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Masts, Aluminium Masts, Carbon Masts, Hybrid Masts Application: Recreational, Competitive, Professional, Training End User: Amateur Surfers, Professional Athletes, Schools, Rental Shops Design: Flex Masts, Rigid Masts, Adjustable Masts, Fixed Masts |
| Companies Covered | Naish, Aerotech, Chinook Sailing Products, Goya, Ezzy Sails, North Sails, Severne Sails, Simmer Style, Exocet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windsurf Masts Market Evolving Landscape
Material science advances and regulatory disclosure requirements are restructuring how mast manufacturers design, certify, and distribute products across European and Asia-Pacific sailing corridors.
Bio-based epoxy resin systems are integrating into carbon fiber prepreg formulations to reduce cradle-to-gate carbon intensity. Windsurfing schools in coastal France are piloting these masts for rental durability validation. The technology is integrating lifecycle accounting into procurement scoring, compressing competitive advantage for early adopters.
REACH Article 33 substance disclosure rules are mandating full supply chain chemical transparency for composite water sports equipment. Mast manufacturers must now document resin hardener compositions through tier-three suppliers. European distributors are responding by consolidating sourcing around audited factory networks with pre-submitted technical files.
Rental operators are unbundling mast replacement from board package purchases, creating spot-market demand for certified refurbished units. Mediterranean sailing schools are leading this shift, establishing regional refurbishment hubs. France and Italy display the strongest concentration of certified pre-owned mast transactions.
Windsurf Masts Market Segmentation
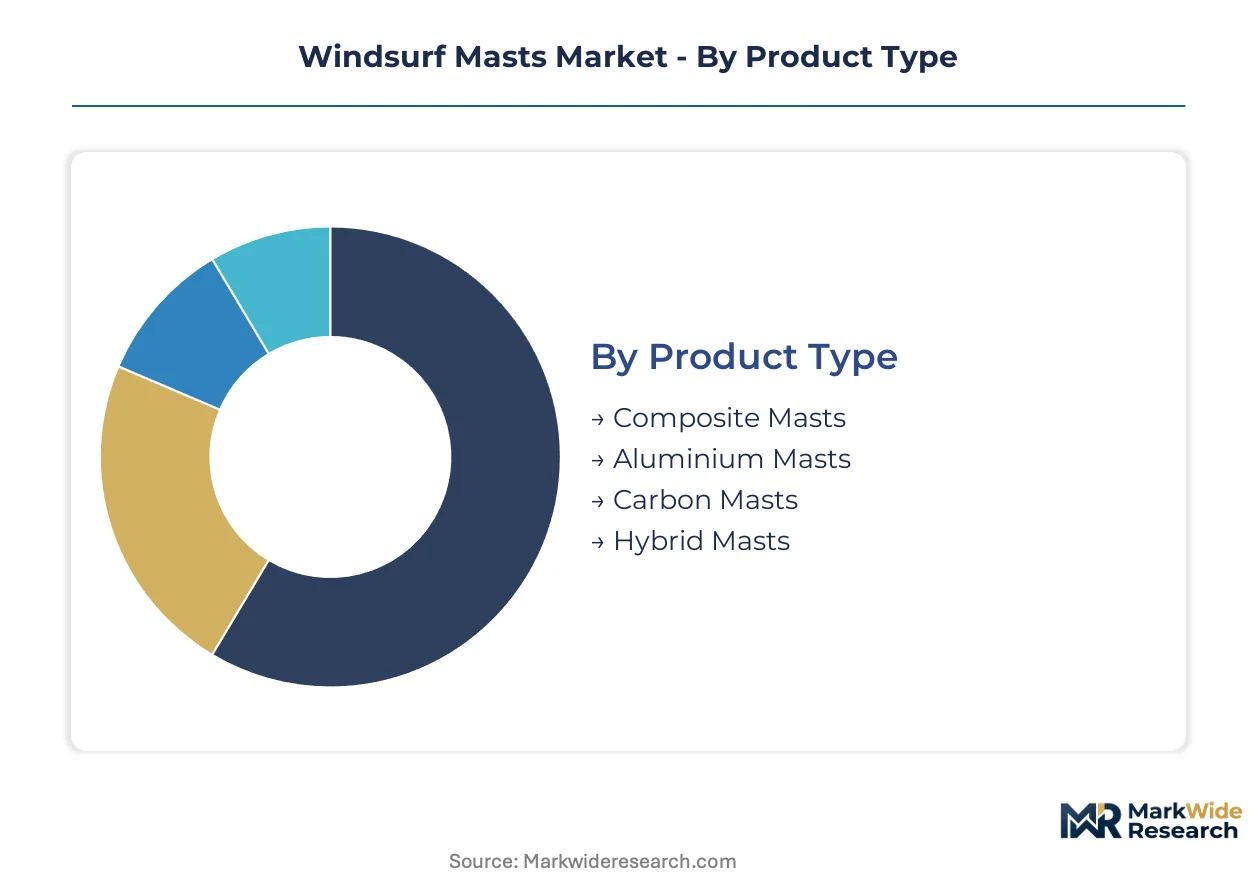
Mast replacement cycles diverge sharply across user types and performance tiers. Professional athletes replace carbon masts seasonally while rental operators amortize aluminum units across multi-year fleet rotations. Understanding these segment-specific durability economics shapes procurement timing and margin capture.
Product Type:
Upgrade trajectories map directly to material composition, with recreational users climbing from aluminum toward carbon as skill progression accelerates replacement frequency.
- Carbon Masts:High-modulus carbon fiber prepreg construction delivers superior stiffness-to-weight ratios essential for competitive bend curve precision. Olympic sailing circuits and World Sailing events concentrate procurement in France and Spain, where athletes prioritize reflex response over unit cost. Toray supply constraints are extending lead times for premium grades.
- Aluminium Masts:Extruded 6061-T6 or 7075-T6 aluminum alloys dominate volume economics through impact resistance and field-repairability. Hossegor and La Torche rental clusters in coastal France anchor fleet procurement, prioritizing dent tolerance over weight savings. Schools favor these for beginner durability validation.
- Composite Masts:Glass fiber and lower-modulus carbon hybrids occupy mid-tier positioning for recreational users seeking performance upgrades without full carbon pricing.
- Hybrid Masts:Aluminum base sections married to carbon tops blend durability economics with upper-mast responsiveness for intermediate progression markets.
Aluminium Masts sit at the top of the volume ranking, with Carbon Masts climbing the fastest.
Application:
Cost tier stratification separates casual weekend use from dedicated competitive programming, with equipment investment scaling to commitment intensity.
- Competitive:World Sailing circuit athletes and national team programs demand ISO-certified bend curves with documented reflex characteristics. Mediterranean training bases in Greece and Croatia concentrate high-frequency replacement cycles. CE marking timelines compress procurement windows ahead of event seasons.
- Professional:Sponsored athletes and coaching staff operate on manufacturer-supported equipment rotations with direct factory relationships. French Atlantic coast professionals anchor regional demand clusters.
- Recreational:Weekend sailors and holiday users prioritize rental accessibility over ownership, driving spot-market demand through Mediterranean island operators.
- Training:Windsurfing schools and certification programs amortize equipment across high-cycle student use, favoring standardized bend curves for instructional consistency.
Recreational captures the widest user base, while Competitive applications are expanding most quickly.
End User:
Customer type determines procurement channel preference, with institutional buyers consolidating volume through direct manufacturer negotiation.
- Rental Shops:Fleet operators in coastal France and Italian Adriatic resorts consolidate multi-unit purchases around durability specifications and refurbishment protocols. Extended producer responsibility frameworks are reshaping end-of-life cost allocation.
- Schools:Certification bodies and instructional programs standardize equipment for curriculum consistency, creating pull for mid-tier composite configurations.
- Professional Athletes:Individual competitors and national team members prioritize custom bend curve specification through direct factory relationships.
- Amateur Surfers:Individual recreational buyers fragment across retail channels, with online direct-to-consumer growth displacing traditional surf shop distribution.
Rental Shops command the largest institutional volume, with Schools gaining share fastest.
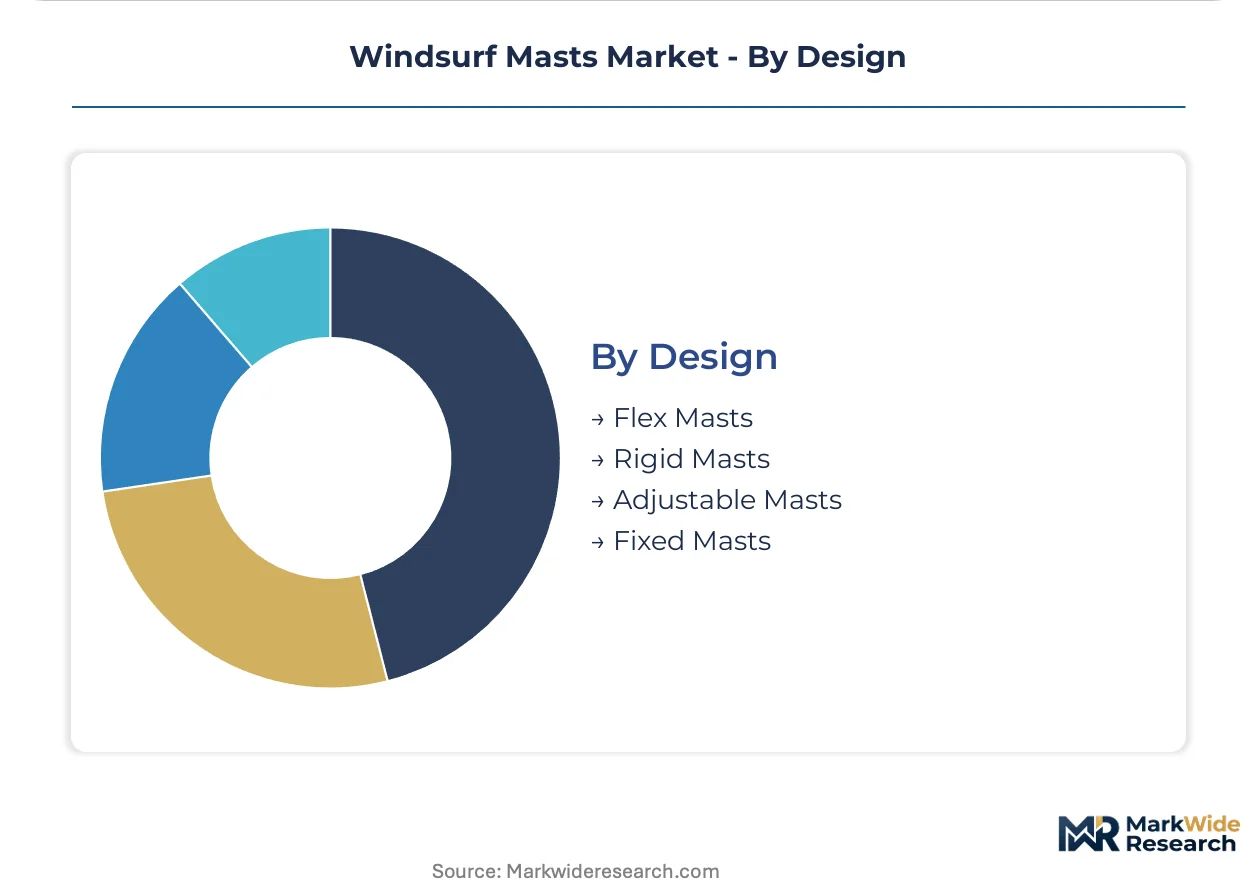
Design:
Volume concentration favors standardized fixed geometries, though adjustable systems capture traveling sailors seeking multi-condition versatility.
- Fixed Masts:Constant curve and hard-top bend profiles dominate production scale, with standardized lengths enabling interchangeability across sail quivers. Manufacturing automation favors fixed-geometry filament winding.
- Flex Masts:Variable reflex characteristics suit wave sailing disciplines where gust absorption protects equipment and rider. Hawaiian and Canary Islands wave specialists concentrate demand.
- Rigid Masts:Minimal deflection designs serve slalom and racing formats where power transmission efficiency dominates comfort considerations.
- Adjustable Masts:Telescoping or modular systems enable length variation for traveling sailors, though mechanical complexity elevates cost and maintenance requirements.
Fixed Masts anchor production volume, with Flex Masts showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Windsurf mast manufacturing traces its commercial origins to Hawaiian board shapers and California aerospace engineers who adapted filament winding techniques for marine applications during the late 1970s. European demand crystallized around Mediterranean training circuits and Atlantic wave sailing destinations. Contemporary procurement patterns reflect this bifurcated heritage.
France
EU Green Deal disclosure mandates are restructuring distributor sourcing protocols across Atlantic and Mediterranean coastlines. REACH Article 33 compliance timelines compress procurement windows for rental fleet operators. The Hossegor-La Torche corridor anchors volume demand, where schools consolidate multi-unit aluminum mast purchases ahead of summer instructional seasons.
United States
EPA composite waste regulations and California DTSC hazardous material protocols shape domestic manufacturing location decisions. Hawaii and California retain design engineering concentration, though production has shifted offshore. Maui-based product development teams coordinate with Asian filament winding facilities for competitive circuit supply.
Spain
World Sailing event calendars concentrate athlete equipment procurement around Mediterranean training bases in Catalonia and the Balearic Islands. CE marking requirements govern structural integrity certification for masts sold through European retail channels. Tarifa and Pozo Izquierdo host testing programs for prototype bend curve validation.
Greece
Island rental operators are modernizing fleets, creating pull for mid-tier composite mast configurations across Cyclades and Dodecanese sailing corridors. Extended producer responsibility pilot programs are reshaping end-of-life cost allocation for composite water sports equipment. Naxos and Paros cluster refurbishment hub development.
Australia
ISO 12217 small craft standards constrain mast-board compatibility parameters for products distributed through Asia-Pacific channels. TGA-equivalent product safety frameworks influence import documentation requirements. Perth and Sydney coastal schools standardize equipment for curriculum consistency across certification programs.
Windsurf Masts Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and distribution control dimensions. The vendor base stratifies into three tiers: integrated manufacturers with captive carbon fiber supply relationships, specialist sail lofts with mast co-development programs, and regional fabricators serving rental fleet replacement cycles. Consolidation pressure concentrates among mid-tier composite specialists facing Toray prepreg allocation constraints. Dominant competitive moves include Mediterranean distribution network acquisition and automated filament winding capacity expansion.
Within the integrated manufacturing tier, Naish and Severne Sails exemplify archetypes of supply chain control and specialized R&D positioning respectively. Goya occupies a position within Mediterranean distribution-focused specialists. These three entities represent contrasting strategic postures: Hawaiian-originated vertical integration, European carbon fiber program concentration, and Spanish network density.
| Leading Market Players |
|---|
| Naish |
| Aerotech |
| Chinook Sailing Products |
| Goya |
| Ezzy Sails |
| North Sails |
| Severne Sails |
| Simmer Style |
| Exocet |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists dominate windsurf mast manufacturing, with generational ownership structures in coastal France and Maui anchoring pricing discipline through patient capital and multi-decade supplier relationships. Their financing patterns favor long-term resin contract commitments over spot-market procurement, insulating premium carbon mast pricing from aerospace demand volatility while compressing margins for aluminum rental-grade competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by material certification and performance tier. Carbon fiber prepreg grades certified for World Sailing competition command substantial premiums over recreational aluminum units, with CE marking tier and ISO bend curve documentation serving as primary differentiation drivers. Pricing pressure stems from Toray supply allocation constraints elevating raw material costs for premium segments. Rental fleet operators in coastal France display highest price sensitivity, while Olympic athletes demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Carbon fiber prepreg supply rests on Japanese and Taiwanese specialty producers, with Toray Industries and Formosa Plastics anchoring high-modulus fiber availability. Resin chemistry, filament winding equipment, and aerospace-grade tooling constitute critical input dependencies. Single-source vulnerability concentrates in Japanese high-modulus fiber grades, exposing manufacturers to geopolitical shipping disruptions. Distribution runs through Mediterranean sailing school networks and direct-to-athlete factory relationships for competitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The windsurf masts market functions as a regulatory compounder, with EU Green Deal lifecycle disclosure mandates accelerating procurement protocol transformation across European water sports retail channels.
For Market Incumbents: Hedge against Toray prepreg allocation constraints by securing multi-year carbon fiber supply agreements ahead of competitive sailing seasons. Invest in automated filament winding capacity expansion to offset technician scarcity at legacy aerospace facilities. CE marking timeline compression represents a critical threat requiring pre-submitted technical file preparation with ECHA-compliant resin documentation. For New Entrants and Emerging Players: EU Green Deal procurement mandates in France open a window for bio-based epoxy resin mast offerings with documented cradle-to-gate carbon intensity. Target Mediterranean rental network modernization in Greece and Croatia, where island operators seek mid-tier composite configurations. Pursue certified refurbishment hub partnerships as an entry angle, leveraging extended producer responsibility pilot programs for competitive positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators serving rental fleet replacement cycles, with fragmented Mediterranean distribution networks offering consolidation opportunities. Long-term viability favors integrated manufacturers with captive carbon fiber relationships and automated production scale. Watch Toray supply allocation decisions as the critical inflection indicator for premium segment margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Supply | Captive Toray prepreg allocation secures competitive sailing circuit procurement priority against aerospace demand. |
| Automated Filament Winding Capacity Expansion | Addresses technician scarcity constraining mast factory scaling across European and Asia-Pacific production corridors. |
| Mediterranean Distribution Network Acquisition | Greek and Croatian island operator consolidation creates pull for mid-tier composite mast penetration. |
| CE Marking Pre-Certification Investment | ECHA-compliant technical file submission compresses structural integrity testing timelines by 4-6 months. |
| Closed-Loop Composite Recycling Partnership | EU extended producer responsibility pilots reward manufacturers with certified material recovery systems. |
Research Methodology
Multiple input streams — primary interviews with mast manufacturers, rental fleet operators, and competitive athletes; secondary validation through trade customs data and sailing federation procurement records; and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned filament winding technicians, EU water sports distributors, and Mediterranean sailing school procurement managers. Secondary sources included REACH Article 33 disclosure databases, World Sailing equipment certification registries, and French Atlantic coast tourism authority fleet investment reports.
Data-stream reconciliation across product type, application tier, end-user category, and regional regulatory cluster dimensions shaped the analytical framework. Carbon fiber grade availability, aluminum alloy pricing indices, and rental fleet depreciation schedules informed industry-specific forecast inputs. CAGRs were derived through segment-level volume buildups validated against aggregate market sizing.
Revisions become necessary when Toray supply allocation shifts, EU Green Deal enforcement timelines accelerate, or extended producer responsibility frameworks expand beyond pilot jurisdictions. A small set of named triggers — aerospace prepreg demand spikes, REACH substance restriction amendments, and Mediterranean tourism recovery patterns — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Mouthguard Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Global Wakeboarding Equipment Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Rally Sport Riding Gear Market