
 Europe Stand-Up Paddleboard Market | 2026-2036
Europe Stand-Up Paddleboard Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stand-Up Paddleboard Market Foresight
REACH is broadening compliance costs for imported PVC and epoxy resins, reshaping supplier qualification thresholds across the continent. Jobe Sports leverages its Dutch manufacturing base to sustain shorter lead times for rental fleet operators. Tahe Outdoors anchors its position through integrated composite production in France. Red Paddle Co differentiates via proprietary drop-stitch technology and direct-to-consumer channel control.
A stand-up paddleboard is a buoyant, human-propelled watercraft typically measuring 9 to 14 feet in length, constructed from layered PVC, EPS foam cores, or carbon fiber composites, and designed for stability through increased width and volume relative to traditional surfboards. Inflatable variants dominate unit volume due to portability and reduced storage requirements, while solid boards command margin pools in performance racing and dedicated surf zones. The professional end-user segment concentrates demand around competition-grade carbon fiber construction, whereas rental services favor durable polyethylene and PVC configurations for fleet turnover resilience.
EMA guidelines on chemical exposure in recreational products and the EU Green Deal's plastics transition targets jointly pressure material substitution timelines. France's national environmental agency and Spain's coastal development authorities enforce overlapping standards on beach equipment composition and end-of-life handling. Stakeholders must monitor regulatory divergence between national implementation schedules and harmonized EU deadlines to align procurement and R&D commitments.
Market Dynamics
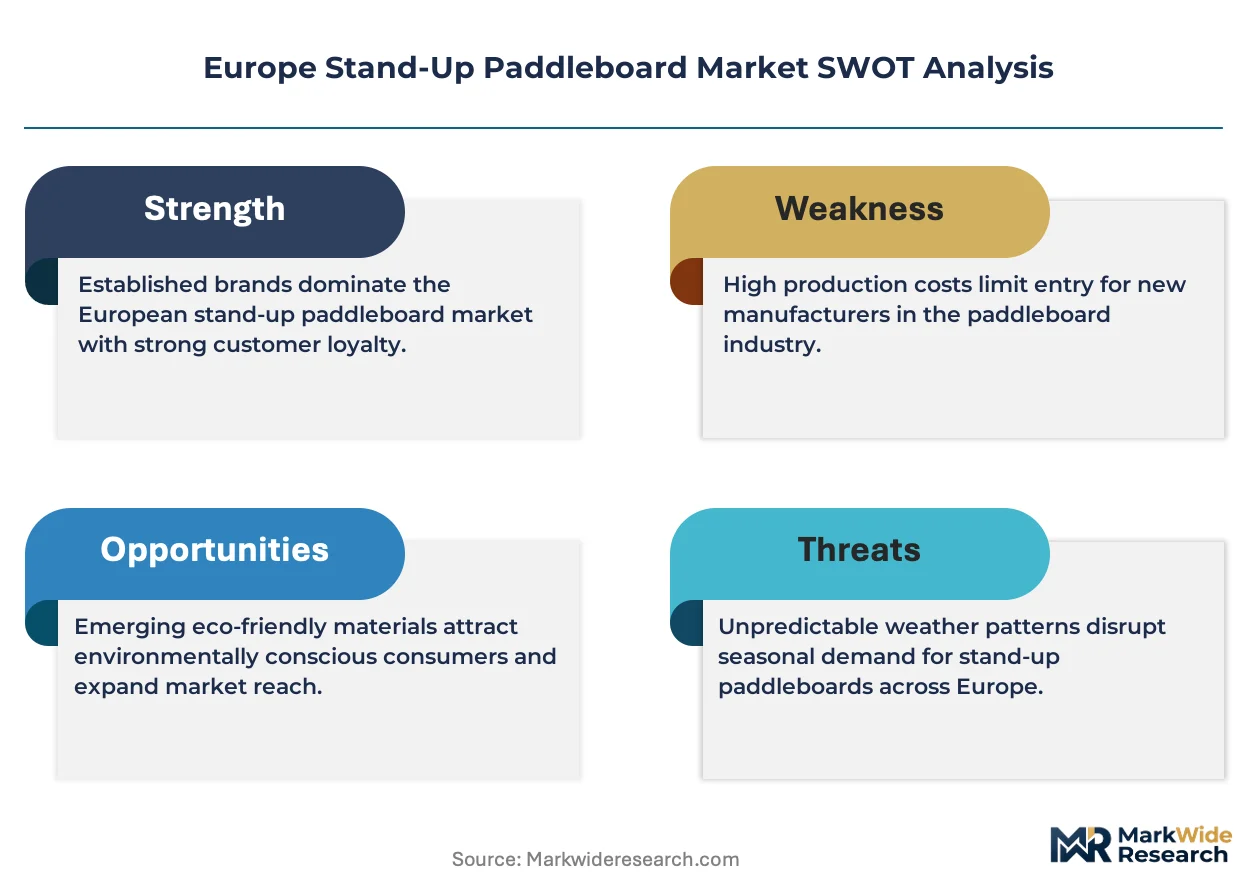
REACH compliance deadlines are forcing material substitution across European supply chains, compressing margins for PVC-dependent manufacturers while rewarding early adopters of bio-based resins. Rental fleet operators in France and Spain now prioritize durability specifications over unit cost in procurement decisions.
Growth Catalysts
- EU Green Deal plastics transition targets:Mandatory recyclable content thresholds are accelerating R&D investment in thermoplastic polyurethane alternatives and closed-loop manufacturing processes.
- Coastal tourism infrastructure expansion:Marina development authorities in Portugal and Croatia are allocating dedicated paddleboard zones, creating captive demand for rental fleet operators.
- Drop-stitch fabrication advances:Higher-density weave patterns are extending inflatable board lifespans, eroding the performance gap with rigid composite constructions in recreational segments.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations and ECHA authorization bottlenecks are squeezing margin pools for carbon fiber composite producers.
- Asian manufacturing concentration:Dependence on Chinese PVC textile suppliers exposes European brands to shipping cost spikes and customs clearance delays.
- Seasonal demand compression:Northern European climates restrict viable operating months, forcing inventory carrying costs onto distributors and rental operators.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit rising participation rates in water sports with minimal dedicated retail infrastructure, creating first-mover advantages for direct-to-consumer entrants.
- Integrated experience packages:Hotels and wellness resorts in the Balearic Islands are bundling paddleboard instruction with accommodation, opening B2B procurement channels distinct from traditional retail.
- CE marking harmonization:Streamlined conformity assessment procedures for recreational watercraft are reducing time-to-market for innovative hull designs and safety accessories.
Industry Challenges
- Composite technician scarcity:Hand-layup carbon fiber fabrication requires specialized labor pools concentrated in Brittany and Basque Country, constraining production scaling.
- End-of-life collection infrastructure:National implementation schedules for extended producer responsibility diverge across member states, complicating pan-European product stewardship programs.
- Inflation-weld seam reliability:Automated bonding processes for drop-stitch construction demand precision calibration that smaller contract manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stand-Up Paddleboard Market |
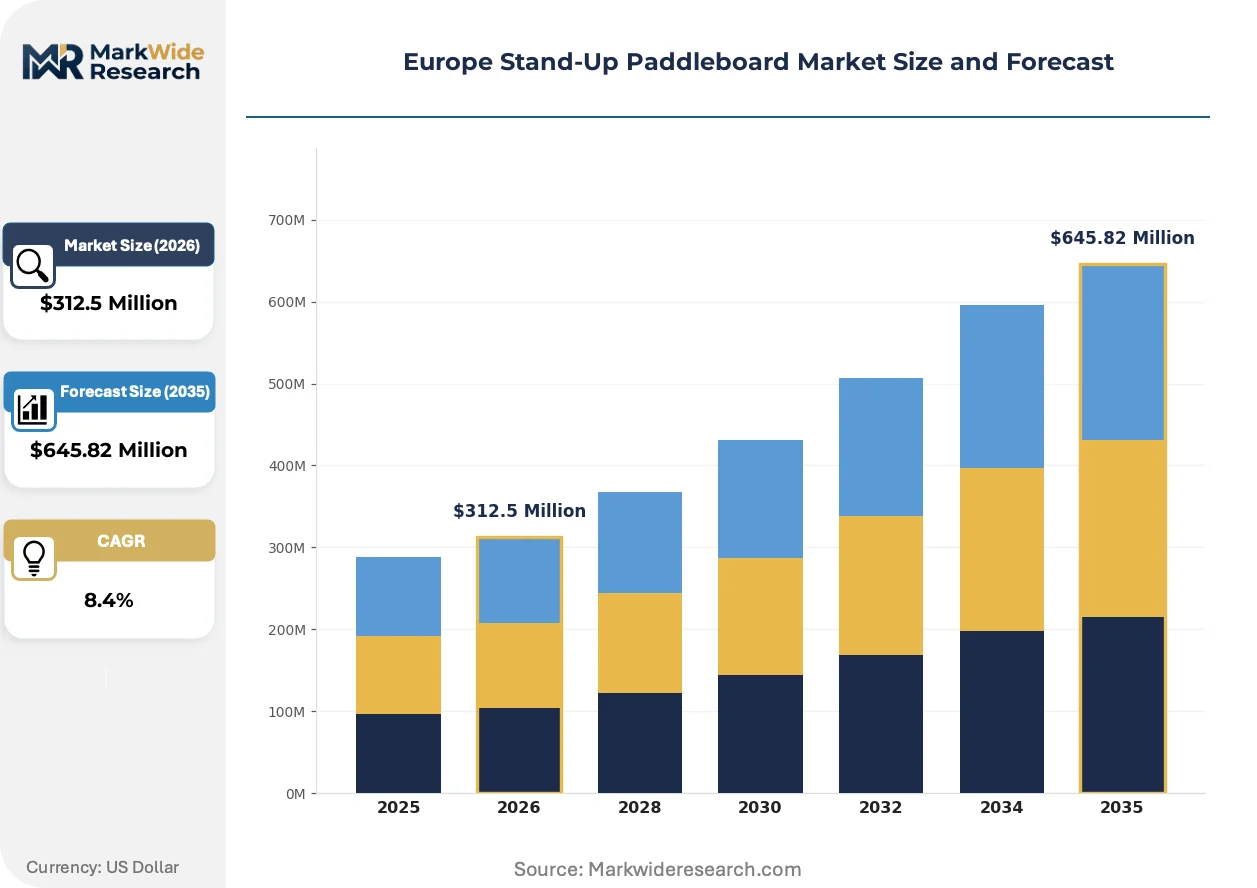
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Solid, Tourer, Racing End User: Recreational, Professional, Rental Services, Schools Material: Polyethylene, PVC, EPS Foam, Carbon Fiber Application: Leisure, Fitness, Competition, Adventure |
| Companies Covered | Jobe Sports, Tahe Outdoors, Red Paddle Co, BIC Sport, Naish International, Starboard, Aqua Marina, MOAI, Fanatic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stand-Up Paddleboard Market Shifts & Advancements
Material science breakthroughs and regulatory pressure are converging to redefine product architecture and go-to-market economics across European paddleboard manufacturing. Sustainability credentials now function as competitive differentiators rather than optional premiums.
Plant-based epoxy resins derived from lignin and agricultural waste streams are rewriting durability benchmarks for rigid board construction. Premium racing clubs in France and Italy are adopting these formulations despite cost premiums, validating performance parity claims. The shift is compressing market share for petroleum-dependent suppliers unable to certify bio-content percentages.
REACH authorization requirements for isocyanates in polyurethane foams are tightening formulation disclosure obligations. Manufacturers serving the German and Austrian markets face accelerated compliance timelines compared to southern European counterparts. The regulatory divergence is fragmenting product line strategies, with some brands pursuing regional SKUs rather than unified pan-European portfolios.
Rental operators are consolidating procurement through cooperative purchasing agreements, displacing traditional distributor intermediaries. French coastal municipalities and Spanish surf schools are pooling fleet orders to extract volume pricing and standardized maintenance protocols. The behavioral shift concentrates buying power among fewer decision-makers, privileging suppliers with dedicated B2B account infrastructure over pure retail brands.
Europe Stand-Up Paddleboard Market Segmentation
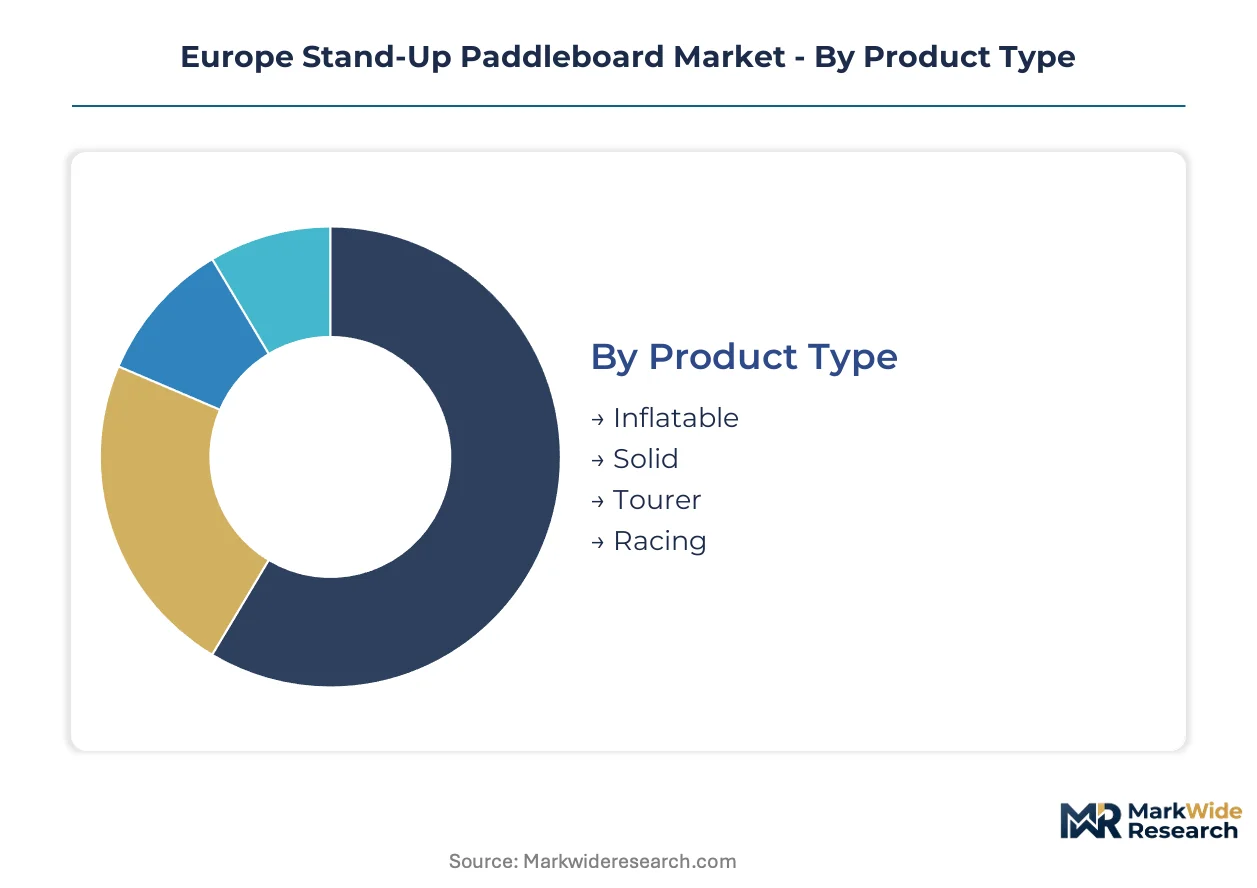
Segmentation in the European paddleboard market separates volume-driven inflatable rentals from premium solid constructions where margin pools concentrate. Manufacturers must align material choices and distribution channels to distinct performance requirements across recreational and professional use cases.
Product Type:
Inflatable variants dominate unit shipments while solid boards capture value concentration in performance segments.
- Inflatable:Drop-stitch PVC construction with reinforced seams enables roll-up portability and reduced storage footprints. Rental fleets across French and Spanish coastal municipalities favor these specifications for seasonal inventory turnover and transport logistics.
- Solid:Rigid composite hulls from EPS foam cores or carbon fiber laminates deliver torsional stiffness for surf zones and racing circuits. Portuguese marinas and Italian racing clubs drive procurement of epoxy-infused constructions where glide efficiency justifies price premiums.
- Tourer:Extended hull geometries prioritize straight-line tracking over maneuverability for multi-day coastal expeditions.
- Racing:Narrow beam profiles and displacement hulls optimize for competitive sprint and long-distance formats.
Today's leader: Inflatable. Tomorrow's challenger: Racing.
End User:
Procurement authority fragments between individual consumers and institutional fleet operators with divergent durability specifications.
- Recreational:Casual paddlers in Mediterranean coastal zones prioritize stability and price accessibility over technical performance.
- Professional:Athletes and certified instructors demand CE-marked equipment with documented load ratings and impact resistance for liability coverage.
- Rental Services:Fleet operators concentrate purchasing power through cooperative agreements, extracting volume pricing and standardized maintenance protocols from suppliers with dedicated B2B infrastructure.
- Schools:Surf schools and water sports academies require high-visibility colorways and reinforced nose sections for instructional durability.
Recreational users anchor current volume. Rental services are expanding most quickly through municipal procurement consolidation.
Material:
REACH compliance timelines and EU Green Deal targets are fragmenting supplier qualification thresholds across resin categories.
- Polyethylene:Rotomolded construction delivers impact resilience for school fleets and beginner zones where board-to-board contact is frequent.
- PVC:Drop-stitch textile technology enables inflatable manufacturing scale, though ECHA authorization bottlenecks for plasticizer additives are compressing margins for petroleum-dependent suppliers.
- EPS Foam:Expanded polystyrene cores serve as the structural substrate for most solid board laminates, with recyclability concerns driving substitution research in France and Germany.
- Carbon Fiber:Prepreg layup constructions command premium positioning in competition segments where stiffness-to-weight ratios determine performance outcomes.
PVC retains volume leadership. Carbon fiber faces margin pressure from bio-based epoxy alternatives.
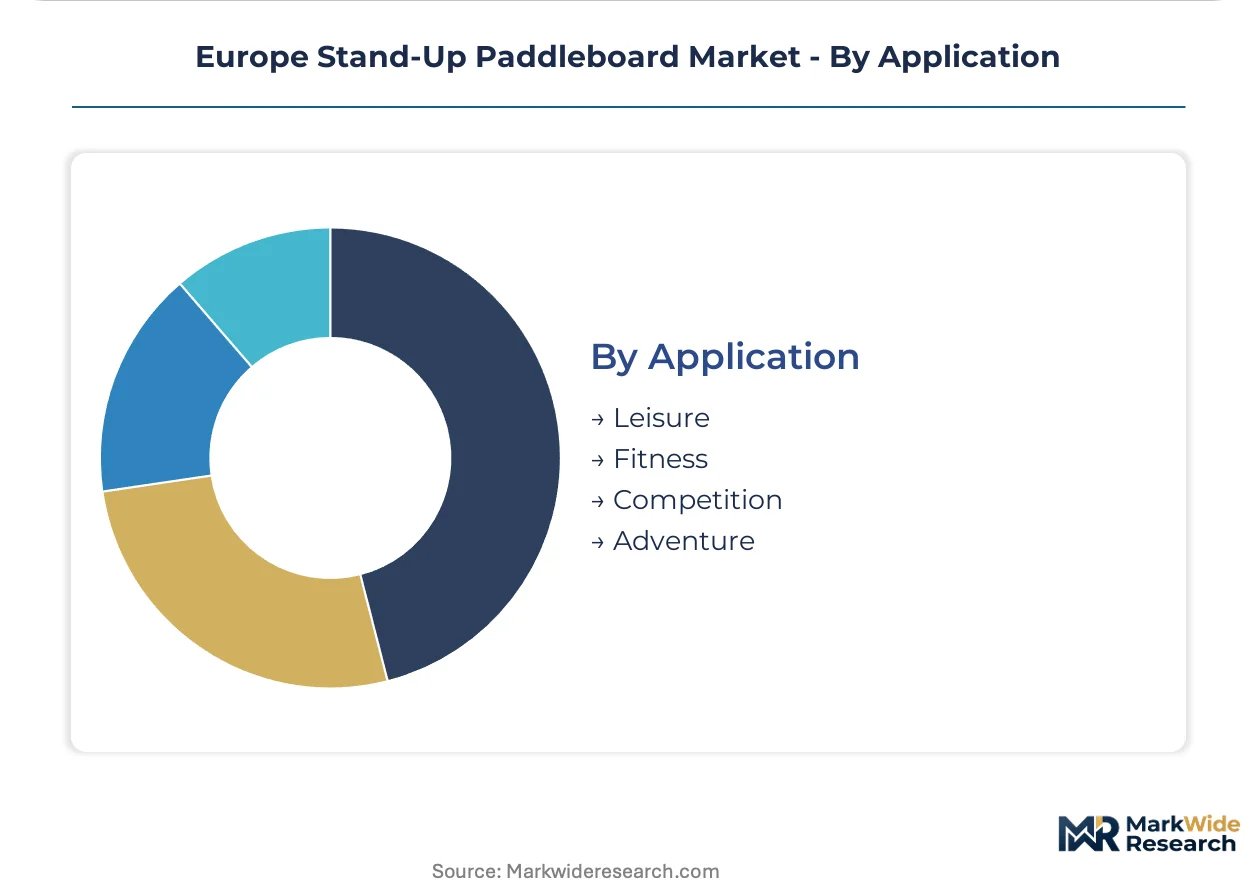
Application:
Usage context determines hull geometry, fin configuration, and accessory integration requirements.
- Leisure:Flatwater paddling in protected harbors and inland waterways emphasizes stability and deck pad comfort for extended sessions.
- Fitness:Yoga and core training applications drive demand for wide, stable platforms with anchor points and bungee storage.
- Competition:Sprint and technical race formats in the Basque Country and Brittany require hydrodynamic optimization and standardized hull dimensions under governing body rules.
- Adventure:Multi-day expeditions along Croatian and Greek coastlines necessitate cargo capacity and durability for open-water conditions.
Leisure commands installed base. Adventure is gaining share fastest through wellness tourism bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized composite technicians cluster along Brittany and Basque Country coastlines, anchoring Europe's rigid board manufacturing base. These skilled labor pools concentrate near racing circuits and surf schools that demand hand-layup carbon fiber construction. Their geographic lock-in shapes regional supply capabilities.
France
Marina infrastructure expansion in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine drives fleet procurement from rental operators. The national environmental agency enforces extended producer responsibility timelines that compress material substitution schedules. Tahe Outdoors maintains integrated composite production in Brittany, supplying racing clubs and surf schools with epoxy-infused constructions.
Spain
Coastal tourism authorities in Catalonia and Andalusia allocate dedicated paddleboard zones within marina developments. The country's coastal development authorities impose overlapping standards on beach equipment composition and end-of-life handling. Barcelona and Málaga host consolidated rental operator cooperatives that pool fleet orders and extract standardized maintenance protocols.
Portugal
Lisbon and Algarve regions exhibit surging recreational participation alongside minimal domestic manufacturing presence. EU Green Deal plastics transition targets accelerate demand for recyclable content thresholds in imported equipment. Local surf schools concentrate purchasing power through municipal procurement channels distinct from traditional retail distribution.
Germany
Inland waterway paddling in Bavaria and Baden-Württemberg sustains year-round demand despite seasonal compression elsewhere. ECHA authorization bottlenecks for isocyanates in polyurethane foams tighten formulation disclosure obligations faster than southern European counterparts. Stuttgart and Munich anchor distributor networks serving Alpine lake tourism and fitness applications.
Italy
Competitive racing circuits in Tuscany and Liguria command premium carbon fiber procurement from specialized fabricators. CE marking harmonization for recreational watercraft reduces time-to-market for innovative hull designs. Milan and Genoa host composite workshops supplying displacement hull constructions for sprint and long-distance formats.
Europe Stand-Up Paddleboard Market Competitive Landscape
The competitive structure tilts toward specialized fabricators with captive composite production capabilities. European brands maintain proximity advantages to rental fleet operators through shorter lead times and localized service infrastructure. Three archetypes dominate: integrated manufacturers controlling resin-to-retail workflows, technology licensors monetizing proprietary drop-stitch patents, and distributor-branded importers competing on price accessibility. Capacity expansion and direct-to-consumer channel development represent the dominant competitive vectors reshaping procurement relationships.
Among Dutch and French integrated producers, Jobe Sports and Tahe Outdoors exemplify the manufacturing-anchor archetype through regional production bases. Red Paddle Co occupies a position on the technology-specialist vector, representing proprietary fabrication approaches that differentiate inflatable constructions. These three entities anchor the competitive landscape without exhaustive market coverage.
| Leading Market Players |
|---|
| Jobe Sports |
| Tahe Outdoors |
| Red Paddle Co |
| BIC Sport |
| Naish International |
| Starboard |
| Aqua Marina |
| MOAI |
| Fanatic |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between CE-marked racing constructions and uncertified recreational imports manifests in divergent margin structures and sourcing footprints across European paddleboard manufacturing. Premium hull fabricators in Brittany and the Basque Country command price premiums through captive composite production, while mass-market inflatable suppliers compete on landed cost from Asian textile converters.
Pricing Analysis
Bundled rental-service packages versus unbundled equipment-only sales split the pricing architecture across European paddleboard procurement. Three-tier pricing structure across premium, standard, and economy levels aligns with CE certification status, brand heritage, and after-sales service bundling. Pricing pressure stems from ECHA authorization bottlenecks for isocyanate-based polyurethane foams, compressing margins for petroleum-dependent suppliers. Rental fleet operators exhibit lowest price sensitivity due to cooperative purchasing power, while individual recreational buyers in Eastern Europe drive volume at economy tiers.
Supply Chain Analysis
EU Green Deal domestic-content mandates and France's extended producer responsibility timelines are reshaping sourcing decisions toward regional resin suppliers and recyclable textile converters. Manufacturing gravity draws from China for drop-stitch PVC textiles, the Netherlands for rotomolded polyethylene hulls, and France for hand-layup carbon fiber composites. Supply chain risk centers on single-source dependence for specialized epoxy resin formulations subject to REACH authorization delays. Distribution runs through marina-based rental cooperatives in France and Spain, direct-to-consumer channels for premium brands, and seasonal distributor networks in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European paddleboard manufacturing hinges on bio-based resin substitution cost curves flattening and rental-fleet operators consolidating procurement around full-service suppliers rather than equipment-only vendors.
For Market Incumbents: Hedge against REACH compliance fragmentation by qualifying multiple resin suppliers across bio-based and petroleum-derived categories before authorization bottlenecks harden. Secure captive composite technician pipelines in Brittany and Basque Country through apprenticeship partnerships with regional racing clubs. Diversify beyond PVC-dependent inflatable production into thermoplastic polyurethane alternatives to preempt EU Green Deal plastics transition penalties. For New Entrants and Emerging Players: Direct-to-consumer digital channels in Poland and Romania bypass thin retail infrastructure and capture rising participation rates with minimal competitive density. Target surf schools and municipal procurement channels in Portugal where domestic manufacturing absence creates import dependency. Bundle instructional content and seasonal storage services with equipment sales to differentiate from pure retail incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative rental purchasing concentrates buying power among fewer decision-makers, privileging suppliers with dedicated B2B account infrastructure. Long-term viability favors vertically integrated fabricators controlling resin formulation through hull finishing rather than brand licensors dependent on contract manufacturing. Watch for inflection signals in bio-based epoxy cost parity claims validated by premium racing club adoption in France and Italy.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Resin Qualification | REACH authorization timelines reward early adopters with supplier preference from rental cooperatives in France. |
| Rental Fleet B2B Infrastructure | Cooperative purchasing agreements in Barcelona and Málaga displace distributor intermediaries and concentrate account control. |
| Drop-Stitch Density R&D | Higher weave patterns extend inflatable lifespans and erode performance gaps with rigid boards in recreational segments. |
| Eastern European DTC Launch | Minimal dedicated retail infrastructure in Poland and Romania creates first-mover advantages for digital-native entrants. |
| Extended Producer Responsibility Compliance | France's national environmental agency timelines compress material substitution schedules and reward closed-loop manufacturing investments. |
Research Methodology
Bottom-up rental fleet and recreational user modeling reconciled against top-down resin import and hull production tracking forms the analytical core of this study. Primary interviews with composite workshop owners, marina procurement officers, surf school operators, and ECHA regulatory affairs specialists combined with secondary validation from EU trade databases, French environmental agency filings, and CE marking conformity assessment records. Triangulation across these sources anchors volume and value estimates.
Input-output matrices link material cost structures to finished product pricing across inflatable, solid, and racing hull categories over the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, material composition, and application context, with regional regulatory clusters capturing divergence between REACH implementation schedules. CAGRs derive from installed base turnover rates, fleet expansion plans from coastal tourism authorities, and substitution elasticities between bio-based and petroleum-derived resin categories.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic polyurethane and lignin-derived epoxy would alter the outlook if cost parity arrives faster than baseline assumptions. Forecasts reflect documented assumptions regarding ECHA authorization timelines, EU Green Deal implementation schedules, and cooperative purchasing consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Concussion Helmets Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Tetherball Market
Sports Equipment
Balance Bike Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Cricket Ball Market
Sports Equipment
BMX Bikes Market