
 Australia Gym Accessories Market | 2026-2036
Australia Gym Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Gym Accessories Market Insights
The capability gap between integrated manufacturers and import-reliant distributors is collapsing as domestic warehousing costs surge. Technogym Australia Pty Ltd anchors its position through captive service networks across Sydney and Melbourne. VERVE Fitness Pty Ltd specializes in Olympic-grade barbell production from its Queensland facility. Johnson Health Tech Australia Pty Ltd competes on electronic-integrated accessories with programmable resistance modules.
Australia gym accessories encompass strength-training implements, recovery tools, and supportive gear manufactured from vulcanized rubber, cast iron, open-cell foam, or thermoplastic polymers, typically rated by load capacity, durometer hardness, and dimensional tolerance for repeated biomechanical stress. These products serve commercial fitness centers, home training environments, and athletic conditioning programs requiring standardized equipment for progressive overload protocols. Weights and resistance bands dominate unit volume, while foam rollers command premium positioning in the recovery segment where physiotherapy clinics drive specification-grade procurement. The materials dimension splits between rubber-dominant floor-based equipment and metal-dominant load-bearing apparatus, with foam gaining share in portable recovery categories favored by corporate gym installations.
ACCC mandatory safety standards govern product labeling and structural integrity for load-bearing accessories, while ACCC consumer guarantees enforce replacement obligations that elevate warranty costs for offshore suppliers. The Therapeutic Goods Administration intersects where recovery accessories make therapeutic claims, requiring separate registration pathways for massage rollers marketed to physiotherapy practices. Stakeholders must monitor evolving product liability thresholds as state-level consumer protection offices intensify post-incident investigations of failed resistance equipment.
Market Dynamics
Domestic warehousing cost surges are collapsing the capability gap between integrated manufacturers and import-reliant distributors, forcing wholesale restructuring of sourcing strategies across the Australian gym accessories supply base.
Growth Catalysts
- ACCC product safety standards:Mandatory material compliance requirements for rubber-coated weights are accelerating domestic certification investments, creating barrier advantages for local producers who pre-emptively adapted vulcanization processes.
- Home fitness enthusiasts:Persistent demand from residential training environments sustains volume for adjustable dumbbells and resistance bands, insulating the market from commercial gym cyclicality.
- Victoria and New South Wales metropolitan density:Concentrated gym infrastructure in these states supports viable specialty retail channels that import-reliant distributors struggle to replicate in dispersed geographies.
Market Restraints
- Thermoplastic polymer input volatility:Feedstock price swings for open-cell foam production compress margin predictability for recovery tool manufacturers lacking long-term supply contracts.
- Offshore supplier warranty cost elevation:ACCC consumer guarantee enforcement creates replacement obligation asymmetries that disadvantage import-dependent distributors against domestic producers with captive service networks.
- Cast iron sourcing concentration:Load-bearing apparatus manufacturers face structural vulnerability from limited Australian foundry capacity, forcing reliance on concentrated Asian supply nodes.
Strategic Opportunities
- Queensland manufacturing expansion:Olympic-grade barbell production capabilities established in this state demonstrate viable path for metal-dominant equipment regionalization away from import dependency.
- Physiotherapy clinic procurement specification:Recovery accessories with therapeutic positioning can access premium pricing tiers through TGA registration pathways, segmenting above consumer-grade competition.
- Electronic-integrated resistance modules:Convergence of programmable load technology with traditional strength equipment opens specification-grade procurement channels previously captured by cardio equipment suppliers.
Industry Challenges
- Durometer hardness calibration expertise:Vulcanized rubber compound consistency requires specialized polymer engineering talent scarce in Australian manufacturing labor pools.
- Biomechanical stress testing certification timelines:ACCC structural integrity validation for load-rated accessories extends product launch cycles, compressing competitive response windows.
- Legacy distributor inventory reconfiguration:Import-reliant wholesalers face working capital strain from safety stock builds required to offset elongated sea freight schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Gym Accessories Market |
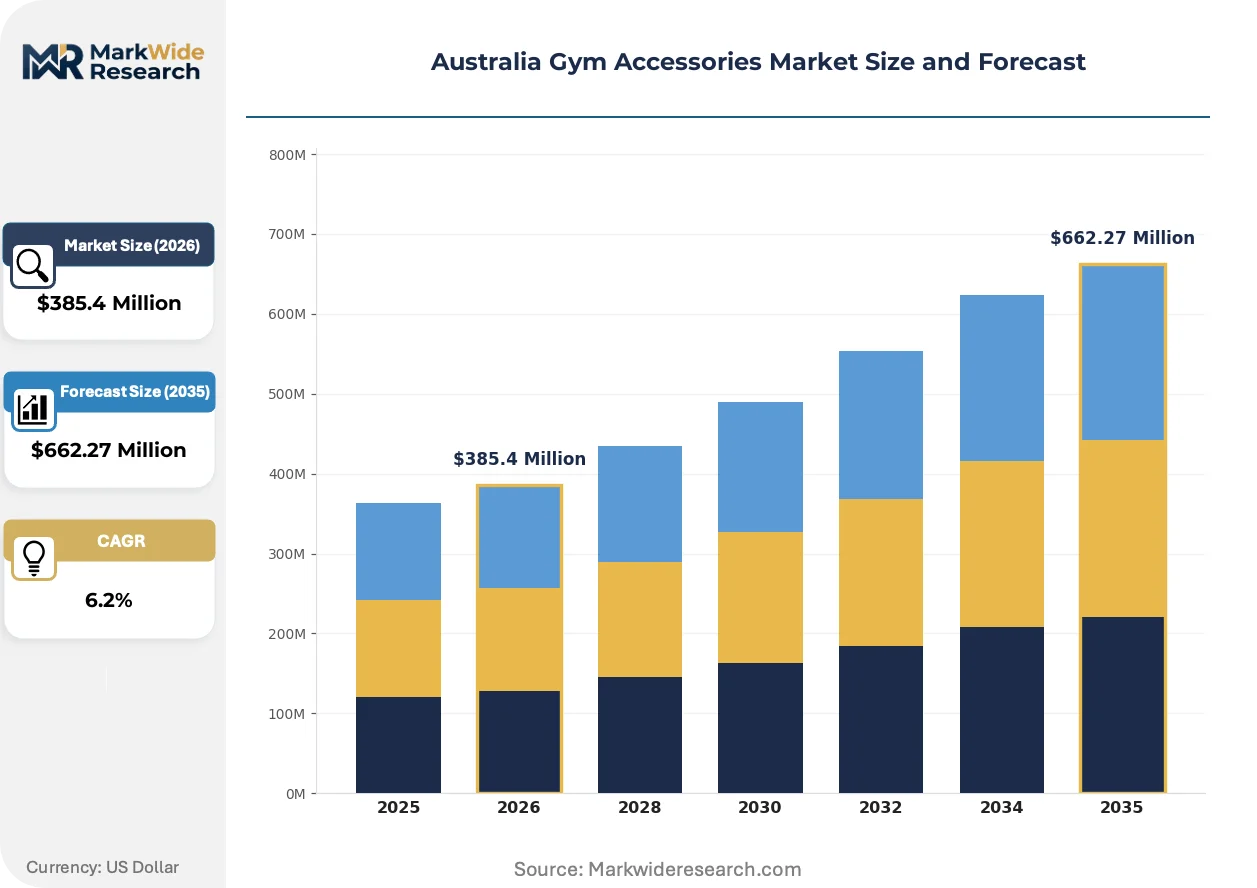
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weights, Bands, Mats, Foam Rollers End User: Home Users, Fitness Centers, Sports Teams, Corporate Gyms Material: Rubber, Foam, Metal, Plastic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Aussie Fitness Equipment Pty Ltd, Peloton, Johnson Health Tech Australia Pty Ltd, Precor, NordicTrack, Technogym Australia Pty Ltd, VERVE Fitness Pty Ltd, Life Fitness, Monsta Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Gym Accessories Market Trends and Innovations
Programmable resistance technology and material science advances are fragmenting traditional equipment categories, while regulatory enforcement intensifies differentiation between specification-grade and consumer-grade supply tiers.
Smart load modules with embedded force sensors and Bluetooth connectivity are decomposing the boundary between strength accessories and cardio equipment. Commercial fitness centers in Sydney and Melbourne are adopting these systems at accelerated replacement cycles. The technology is compressing standalone dumbbell and barbell procurement into integrated platform purchases that lock facilities into proprietary ecosystems.
TGA registration requirements for massage rollers marketed with therapeutic claims are reshaping recovery accessory go-to-market economics. Physiotherapy practices now demand documentation packages that consumer-channel suppliers cannot assemble. The specification-grade segment is responding by segregating product lines between clinical and retail channels with divergent compliance investment profiles.
Corporate wellness programs are consolidating gym equipment procurement through facilities management contractors rather than direct vendor relationships. Specialty retailers in Victoria face disintermediation as national corporate contracts bypass traditional distribution. This channel compression is most visible in Melbourne's CBD commercial building installations where building managers specify standardized equipment packages across multiple tenant gyms.
Australia Gym Accessories Market Segmentation
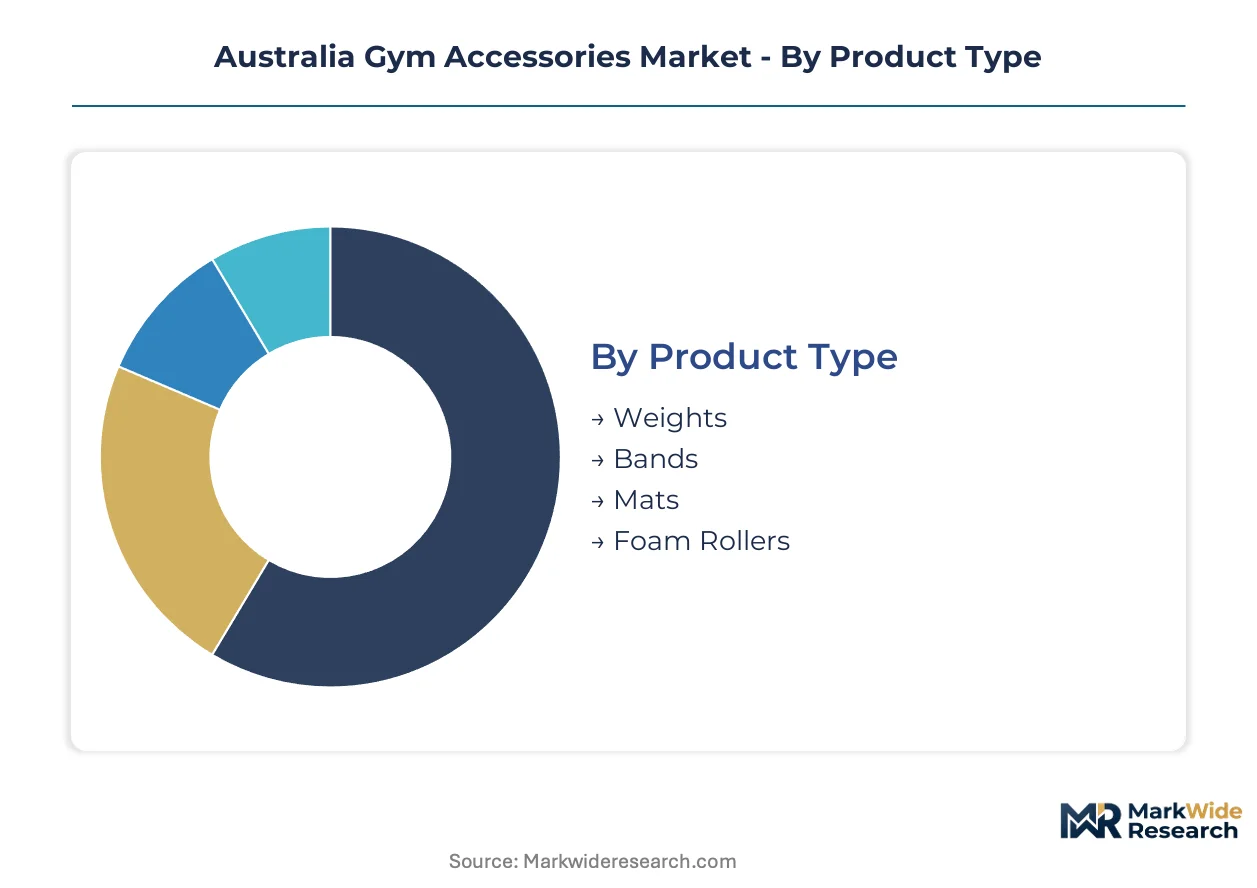
Segmentation in the Australia gym accessories market reveals how ACCC compliance costs and metropolitan infrastructure density create divergent profitability profiles across product categories and channel structures.
Product Type:
ACCC structural integrity standards apply unevenly across product categories, with load-bearing equipment facing mandatory certification timelines that reshape competitive economics.
- Weights:Cast iron and rubber-coated implements dominate commercial procurement volumes in Victoria and New South Wales, where metropolitan gym density supports specification-grade procurement with extended warranty obligations. ACCC mandatory safety standards for rubber vulcanization processes elevate compliance costs that disadvantage import-reliant distributors against domestic producers with captive certification capabilities.
- Bands:Elastic resistance implements manufactured from natural rubber latex or synthetic thermoplastic elastomers serve home fitness enthusiasts seeking portable progressive overload solutions. Demand concentrates in residential training environments across Sydney and Melbourne suburbs, insulating this segment from commercial gym cyclicality.
- Mats:Polymer-composite flooring surfaces rated for impact absorption and durometer hardness.
- Foam Rollers:Open-cell polyethylene recovery tools with therapeutic positioning requirements.
Weights handles the majority of throughput; Foam Rollers is expanding most quickly on share.
End User:
Customer type determines procurement channel access and compliance documentation requirements, with institutional buyers demanding specification-grade certification unavailable through consumer retail pathways.
- Home Users:Residential training environments in Queensland and Western Australia sustain volume for adjustable dumbbells and resistance bands through online retail channels. These buyers prioritize space-efficient storage and modular load progression over commercial-grade durability ratings.
- Fitness Centers:Commercial facilities in metropolitan Melbourne and Sydney require ACCC-certified load-bearing equipment with documented biomechanical stress testing. Procurement runs through specialty retail channels that provide installation and maintenance services.
- Sports Teams:Athletic conditioning programs with standardized equipment protocols.
- Corporate Gyms:Facilities management contractors consolidating building-wide procurement.
Home Users anchor volume throughput; Corporate Gyms is gaining share fastest.
Material:
Input cost volatility and Australian manufacturing capacity constraints fragment sourcing strategies across material categories, with rubber and metal facing opposing supply-side pressures.
- Rubber:Vulcanized compounds for floor-based equipment and resistance implements require specialized polymer engineering talent scarce in Australian labor pools. Queensland manufacturers have established Olympic-grade production capabilities that reduce import dependency for barbell sleeves and bumper plates.
- Metal:Cast iron and steel load-bearing apparatus face structural vulnerability from limited domestic foundry capacity. Manufacturers rely on concentrated Asian supply nodes for raw material inputs, compressing margin predictability during freight cost surges.
- Foam:Open-cell polyethylene for portable recovery categories.
- Plastic:Thermoplastic polymers for injection-molded accessory components.
Metal handles the majority of throughput; Foam is climbing the fastest on share.
Distribution Channel:
Channel selection determines warranty cost exposure and customer service obligation intensity, with ACCC consumer guarantee enforcement creating structural advantages for domestic warehousing configurations.
- Online Retail:E-commerce platforms serving home fitness enthusiasts across dispersed geographies bypass specialty retail overhead but face elongated return logistics for defective load-bearing equipment. These channels concentrate in price-sensitive consumer segments with limited specification-grade penetration.
- Specialty Stores:Melbourne and Sydney metropolitan retailers provide installation, maintenance, and warranty fulfillment services that ACCC obligations require. These channels capture commercial fitness center procurement through relationship-based specification selling.
- Supermarkets:Mass-market retail for entry-level resistance bands and basic recovery tools.
- Wholesale:Bulk distribution to institutional buyers and facilities management contractors.
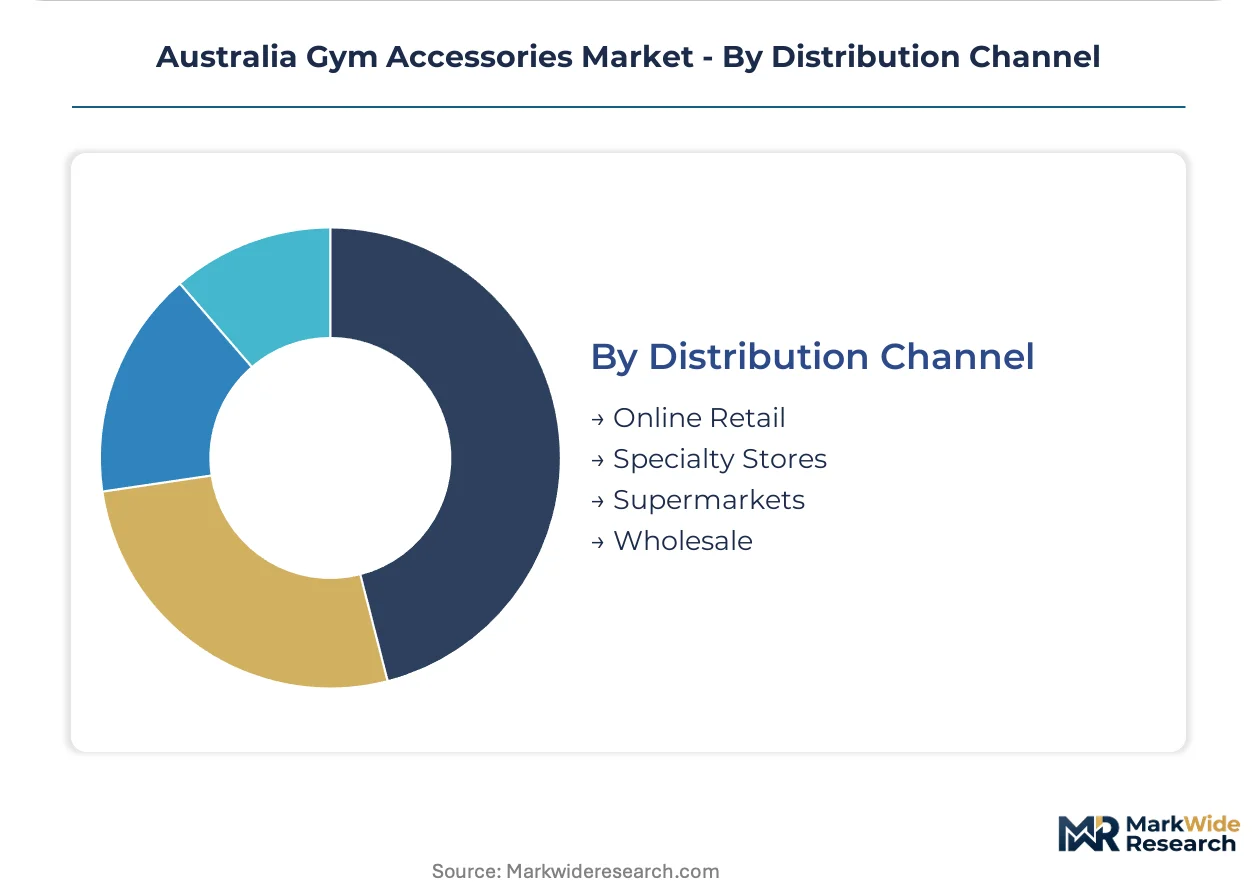
Specialty Stores handles the majority of throughput; Online Retail is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
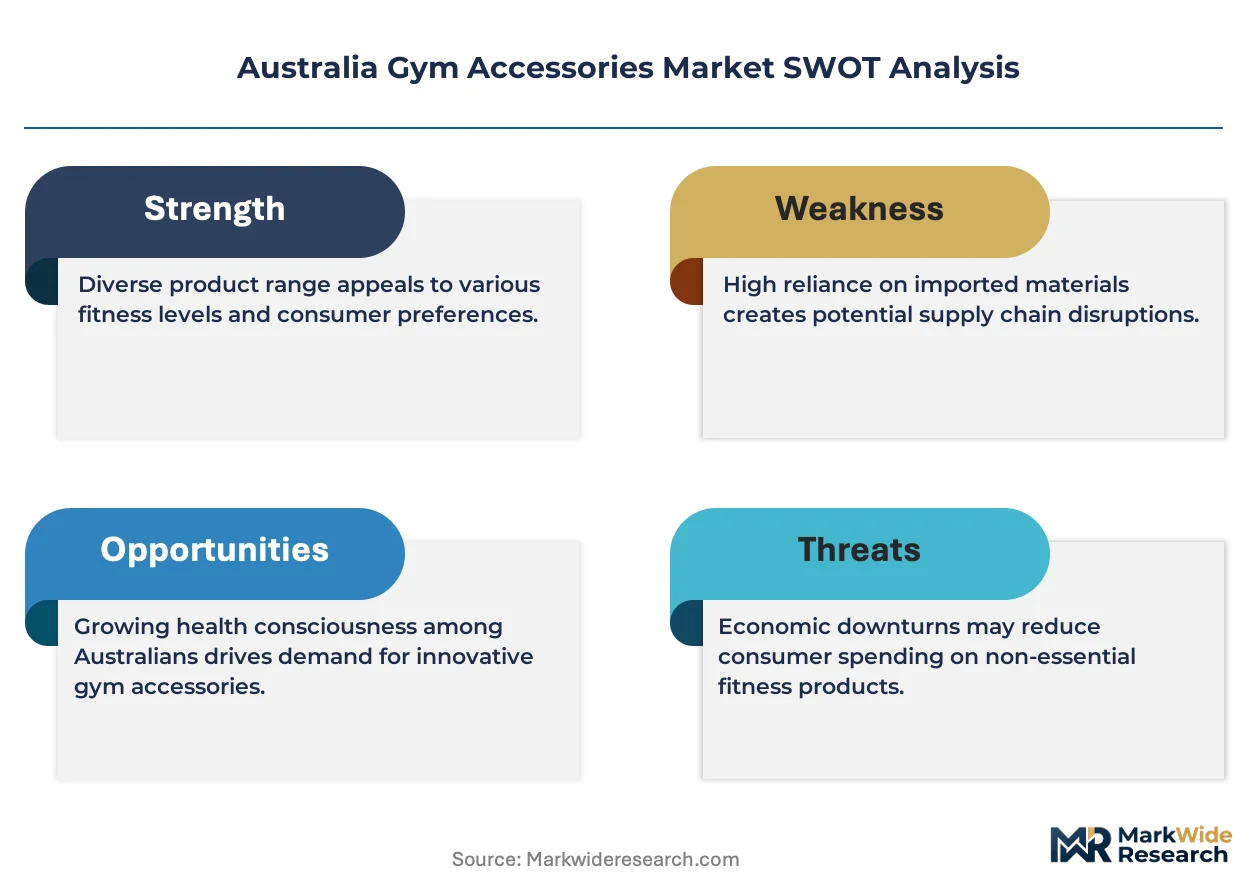
Victoria commands premium pricing power over Queensland due to metropolitan gym density and specialty retail infrastructure, while Western Australia trades at a discount reflecting dispersed logistics costs and import-dependent supply chains.
New South Wales
Sydney's commercial fitness center concentration drives specification-grade procurement for load-bearing equipment with extended warranty terms. The ACCC consumer guarantee enforcement elevates replacement obligations that domestic warehousing configurations handle more efficiently than offshore distributors. Specialty retailers in metropolitan Sydney and Newcastle maintain captive service networks that lock in corporate gym contracts.
Victoria
Melbourne's CBD corporate wellness programs consolidate procurement through facilities management contractors, bypassing traditional retail channels. The state's Therapeutic Goods Administration registration pathways enable premium positioning for recovery accessories marketed to physiotherapy practices. Barbell and bumper plate demand concentrates in Melbourne's inner suburbs where home fitness enthusiasts occupy converted warehouse training spaces.
Queensland
Brisbane and Gold Coast residential developments incorporate building-standard gym installations that specify space-efficient adjustable dumbbells. The state's Olympic-grade barbell production capabilities reduce import dependency for metal-dominant equipment. VERVE Fitness Pty Ltd anchors regional manufacturing from its Queensland facility, supplying domestic certification-advantaged products to eastern seaboard markets.
Western Australia
Perth's geographic isolation elongates sea freight schedules and elevates safety stock requirements for import-reliant distributors. The state's mining sector sustains demand for durable load-bearing equipment in remote site gyms with limited maintenance access. Local warehousing costs compress margins for rubber-coated weight suppliers lacking domestic vulcanization capabilities.
South Australia
Adelaide's smaller metropolitan scale limits viable specialty retail channels, pushing procurement toward online platforms with elongated return logistics. The state's consumer protection office intensifies post-incident investigations of failed resistance equipment, elevating liability exposure for offshore suppliers. Home fitness volume sustains demand for portable resistance bands through direct-to-consumer channels.
Australia Gym Accessories Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with electronic-integrated specialists commanding specification-grade premiums while import-reliant distributors compete on price in consumer segments. The vendor base splits between domestic manufacturers with captive certification capabilities and offshore-dependent wholesalers facing ACCC compliance cost asymmetries. Three archetypes dominate: integrated domestic producers, electronic-technology licensors, and import-reliant volume distributors. Competitive moves concentrate on regional manufacturing expansion and strategic partnerships with facilities management contractors.
Within the integrated domestic tier, VERVE Fitness Pty Ltd and Technogym Australia Pty Ltd exemplify contrasting approaches to captive service network deployment. Johnson Health Tech Australia Pty Ltd occupies a position bridging electronic integration and traditional strength equipment, representing the technology-convergence archetype that programmable resistance modules enable. These three anchors demonstrate how ACCC compliance investments and metropolitan density access separate sustainable positioning from structural margin compression.
| Leading Market Players |
|---|
| Aussie Fitness Equipment Pty Ltd |
| Peloton |
| Johnson Health Tech Australia Pty Ltd |
| Precor |
| NordicTrack |
| Technogym Australia Pty Ltd |
| VERVE Fitness Pty Ltd |
| Life Fitness |
| Monsta Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Ninety-day sea freight schedules from Asian foundries to Australian ports compress pricing power for import-reliant distributors while elevating inventory carrying costs. This lead-time exposure fragments the market between domestic producers with captive certification capabilities and offshore-dependent wholesalers facing ACCC compliance cost asymmetries.
Pricing Analysis
Configured-to-order pricing for specification-grade equipment with embedded force sensors commands substantial premiums over standard adjustable dumbbell and resistance band offerings. Three-tier pricing structure across premium, standard, and economy levels separates TGA-registered recovery tools for physiotherapy clinics from consumer-grade alternatives. Price differentiation hinges on ACCC certification investment and after-sales service bundling. Cost compression in the import-reliant tier is intensifying because elongated freight schedules force safety stock builds that strain working capital. Home fitness enthusiasts demonstrate highest price sensitivity through online retail channels, while corporate facilities management contractors show lowest sensitivity when specification-grade warranties are bundled.
Supply Chain Analysis
Inventory positions above ninety days for cast iron inputs signal structural vulnerability in load-bearing apparatus production. Australian manufacturers draw from concentrated Chinese and Indian foundry capacity for raw metal inputs, while vulcanized rubber compounds source from Southeast Asian polymer processors. Raw material dependencies center on thermoplastic elastomers for resistance bands, open-cell polyethylene for foam rollers, and cast iron for weight plates. Single-source vulnerability runs through limited domestic foundry capacity for Olympic-grade barbell production. Distribution runs through Melbourne and Sydney specialty retailers for commercial fitness centers, with online platforms capturing residential demand across dispersed geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as programmable resistance technology decomposes traditional equipment categories, creating distinct specification-grade and consumer-grade niches with divergent compliance investment profiles.
For Market Incumbents: Fortify captive service networks across Victoria and New South Wales to lock in corporate gym contracts before facilities management contractors consolidate procurement further. Deepen backward integration into Queensland-based vulcanization capabilities to neutralize ACCC compliance cost advantages held by regional producers like VERVE Fitness. Certification investment in TGA registration pathways represents the critical lever for premium recovery accessory positioning. For New Entrants and Emerging Players: Lead with electronic-integrated resistance modules targeting physiotherapy clinic procurement channels where documentation requirements exclude consumer-grade competitors. Western Australia and South Australia present the most penetrable geographies given elongated supply chains that disadvantage import-reliant incumbents. Direct-to-corporate wellness program sales bypass specialty retail channel saturation in Melbourne and Sydney CBD installations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because domestic warehousing cost surges are collapsing the capability gap between integrated manufacturers and import-reliant distributors, forcing wholesale restructuring. Acquisition targets with Queensland manufacturing footprints and captive ACCC certification capabilities offer structural margin protection. The signal to watch is facilities management contractor consolidation velocity in metropolitan commercial building installations.| Strategic Initiative | Industry Significance |
|---|---|
| Queensland Manufacturing Expansion | Reduces import dependency for metal-dominant equipment through regional foundry investment. |
| TGA Registration Pathway Investment | Unlocks premium physiotherapy clinic procurement channels for recovery accessories. |
| Programmable Resistance Module Development | Captures specification-grade procurement previously controlled by cardio equipment suppliers. |
| Facilities Management Contractor Partnership | Secures multi-tenant corporate gym contracts bypassing traditional retail channels. |
| Captive Service Network Deployment | Locks in commercial fitness center relationships through ACCC-mandated warranty fulfillment. |
Research Methodology
Desk research of customs trade data, ACCC product safety filings, and Therapeutic Goods Administration registration databases preceded structured interviews with commercial gym procurement managers, physiotherapy clinic equipment specifiers, and specialty retail channel partners. Primary fieldwork with Queensland-based manufacturers and Victorian facilities management contractors combined with secondary validation from industry association membership directories and state-level consumer protection office enforcement records. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to establish market size parameters.
Variance decomposition across product type, end user category, material composition, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by throughput contributions and pricing power differentials. Forecast inputs incorporated ACCC compliance cost evolution, freight rate volatility assumptions, and metropolitan gym density projections for Victoria and New South Wales.
The analysis sits within stated boundaries; outcomes outside sustained residential fitness demand or intensified ACCC enforcement would require recalibration. Forecasts reflect documented assumptions regarding supply chain restructuring velocity and regulatory compliance investment trajectories specific to load-bearing equipment categories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Smart Fitness Wear Market
Smart Gym Equipment
Smart Fitness Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Singapore Gym Accessories Market