
 Bicycle Helmet Market | 2026-2036
Bicycle Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Helmet Market Analysis
Helmet subscription services bundled with bike-share memberships is expanding the addressable consumer base beyond traditional retail purchasers. Specialized Bicycle Components leverages direct-to-consumer channels to sustain premium positioning in the performance segment. Trek Bicycle Corporation anchors North American distribution through dealer network density. KASK S.p.A. competes in European road cycling with Italian manufacturing heritage and pro-team sponsorships.
A bicycle helmet is a protective headgear device constructed from an outer polycarbonate shell bonded to an inner expanded polystyrene (EPS) foam liner, engineered to absorb impact energy through controlled compression and distribute force across the cranial surface during collision events. Its primary commercial purpose is to reduce traumatic brain injury risk for cyclists across recreational, commuter, and competitive applications. Open Face designs occupy the volume position in commuter and urban segments where ventilation and weight tradeoffs favor daily usability. Carbon Fiber material grades command the margin pool in competitive cycling where gram reduction justifies price premiums. EPS Foam formulations represent the fastest-growing technical subsegment as multi-density layering advances impact absorption performance.
The Consumer Product Safety Commission (CPSC) mandates impact testing protocols for all helmets sold in the United States, while the European Committee for Standardization enforces EN 1078 certification requirements across EU member states. These frameworks create compliance cost barriers for new entrants while driving incumbent R&D investment in multi-certification platform designs. Stakeholders must monitor evolving e-bike speed classifications and corresponding helmet standard revisions that could bifurcate product portfolios between traditional cycling and powered mobility segments.
Market Dynamics
MIPS rotational impact technology is forcing incumbent manufacturers to retool entire product lines while EN 1078 certification requirements in the European Union create compliance cost barriers that reshape competitive positioning across all price tiers.
Growth Catalysts
- E-bike speed reclassifications:Powered mobility segments in Germany and the Netherlands are triggering helmet standard revisions that expand addressable product portfolios beyond traditional cycling applications.
- Urban infrastructure investment:Metropolitan cycling networks in Copenhagen, Amsterdam, and Portland are normalizing daily helmet use among commuter populations previously resistant to adoption.
- MIPS technology licensing:Rotational impact protection systems are becoming a de facto performance benchmark that commands price premiums and accelerates replacement cycles across certified product lines.
Market Restraints
- EPS foam supply concentration:Expanded polystyrene resin production clusters in East Asia create input cost volatility and logistics exposure for manufacturers without captive supply arrangements.
- Multi-certification platform costs:Simultaneous CPSC, EN 1078, and AS/NZS compliance requirements impose R&D overhead that disadvantages smaller competitors lacking scale economies in testing infrastructure.
- Substitution from shared mobility:Dockless e-scooter operators in Paris and Berlin are deploying lower-protection headgear that captures price-sensitive urban trips at helmet expense.
Strategic Opportunities
- Subscription bundling models:Helmet-as-a-service offerings integrated with bike-share memberships in London and New York are unlocking non-traditional consumer segments beyond retail purchasers.
- Carbon fiber grade penetration:Advanced composite manufacturing is automating production cost curves that previously confined high-margin competitive cycling products to elite amateur segments.
- Children's mandate expansion:Mandatory helmet laws for minors in France and Spain are institutionalizing early-age usage patterns that sustain replacement demand through adult life stages.
Industry Challenges
- Biomechanical testing talent scarcity:Specialized crash simulation engineers capable of validating multi-density EPS layering configurations command premium compensation that strains R&D staffing budgets.
- Certification timeline compression:Accelerated EN 1078 revision cycles are forcing simultaneous platform redesigns that conflict with seasonal product launch windows.
- Legacy mold inventory stranding:Existing tooling investments in single-density foam configurations face accelerated obsolescence as MIPS-integrated designs become baseline market expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Helmet Market |
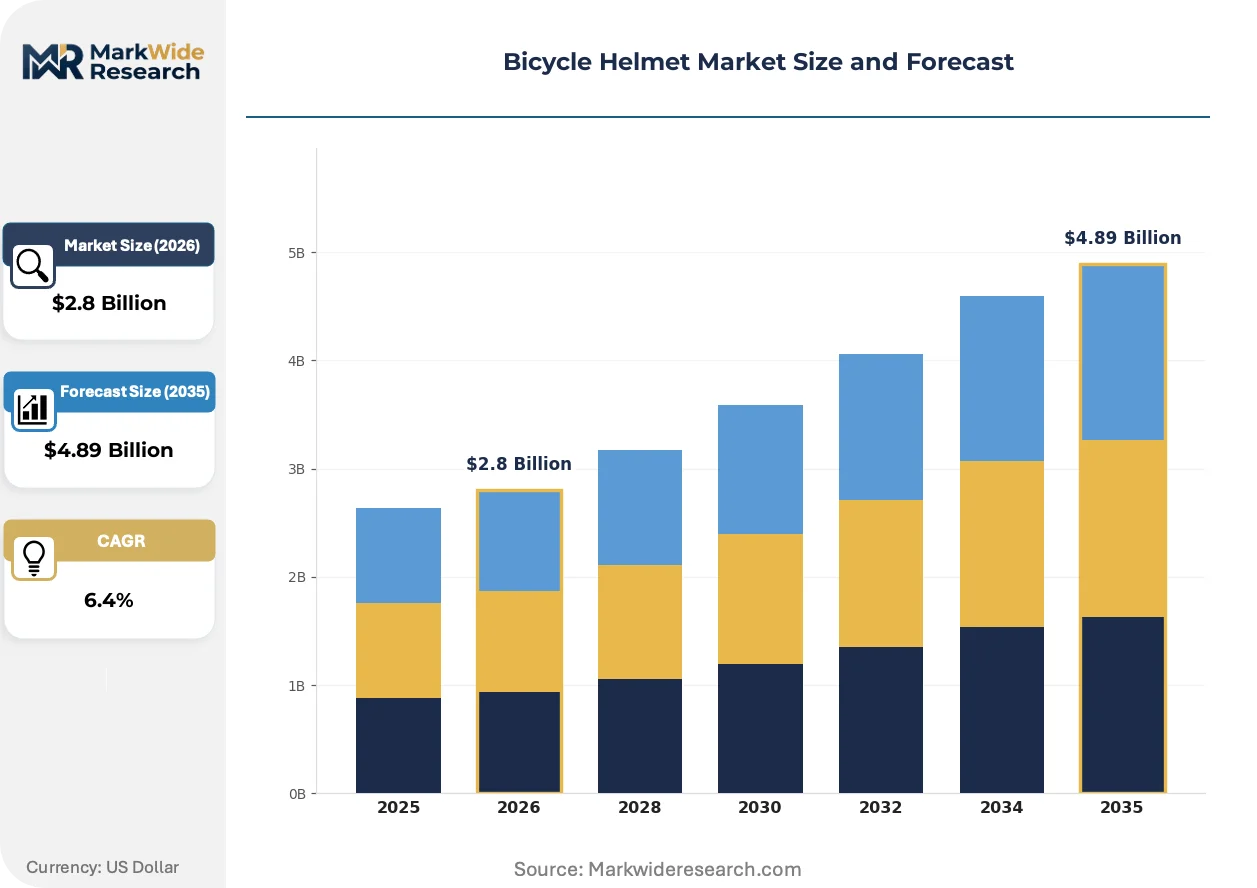
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Face, Open Face, Half Shell, Visor Material: Polycarbonate, EPS Foam, Carbon Fiber, Fiberglass End User: Children, Adults, Sports Enthusiasts, Commuters Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | Vista Outdoor Operations LLC, Trek Bicycle Corporation, Specialized Bicycle Components, SCOTT Sports SA, Dorel Sports, Giro Sport Design, Bell Helmets, KASK S.p.A., Giant Bicycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Helmet Market Emerging Trajectories
Smart sensor integration and automated manufacturing processes are compressing development timelines while regulatory harmonization efforts across North America and Europe reshape certification strategies. Material science advances in impact-absorbing foams are creating performance differentiation that transcends traditional brand loyalty.
Multi-density EPS foam layering is automating impact energy management through precisely engineered compression zones that adapt to collision severity. Competitive cycling teams in Italy and Belgium are specifying these configurations for gram-optimized protection. The technology is automating quality control protocols that previously required manual inspection, reducing unit rejection rates and shortening production cycles.
REACH chemical restrictions in the European Union are phasing out certain flame-retardant additives in polycarbonate shell formulations, forcing reformulation investments across all export-oriented manufacturers. The ECHA regulatory trajectory is compressing supplier qualification timelines for compound vendors. German and Dutch distributors are prioritizing inventory positions that anticipate enforcement date windows.
Direct-to-consumer channel expansion is fragmenting traditional dealer network dependencies as performance-oriented cyclists in the United States and Australia research specifications through digital platforms before purchase. Subscription services bundled with bike-share memberships are displacing single-transaction retail relationships in urban commuter segments. This pattern concentrates most visibly in metropolitan markets where dockless fleet operators negotiate bulk helmet procurement contracts.
Bicycle Helmet Market Segmentation
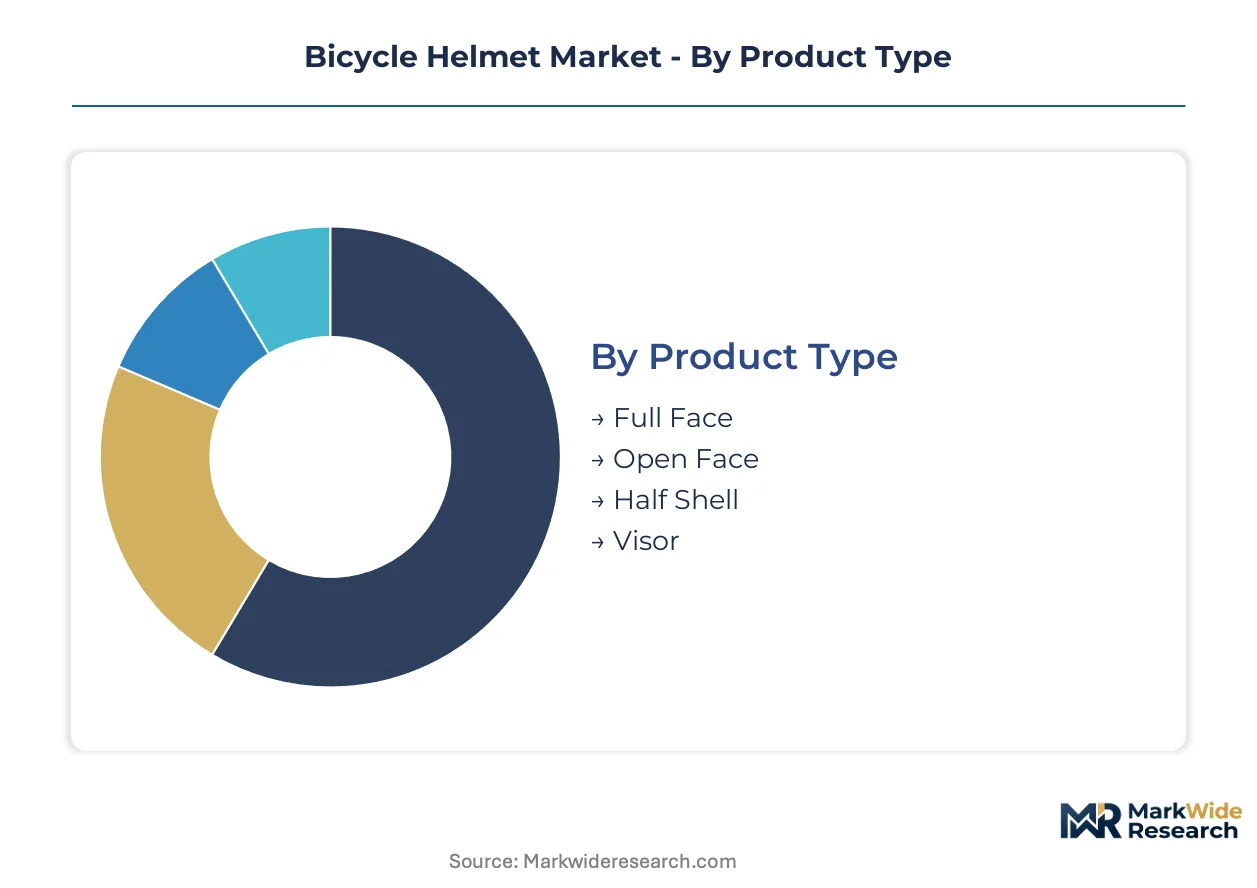
Segmentation in the bicycle helmet market reveals divergent technical requirements across use cases, from gram-obsessed competitive cyclists to parents purchasing mandated protection for school commutes. Material specifications and distribution economics create distinct margin pools that reward specialized positioning over undifferentiated volume plays.
Product Type:
Open Face configurations dominate unit economics through commuter volume, while Full Face variants capture premium positioning in gravity disciplines where chin protection commands non-negotiable specification.
- Open Face:These helmets expose the chin and jaw region to optimize ventilation and weight for daily urban cycling. Demand concentrates in Amsterdam and Copenhagen metropolitan networks where helmet normalization campaigns have shifted commuter behavior. The design sacrifices maximum protection for thermal comfort during multi-kilometer commutes in temperate climates.
- Full Face:Integrated chin bars and extended temporal coverage protect against facial trauma during downhill mountain biking and BMX racing. German and Austrian alpine bike parks mandate these specifications for rental fleet compliance, institutionalizing replacement cycles through seasonal damage accumulation. Shell complexity elevates manufacturing cost bases significantly above open-face alternatives.
- Half Shell:Minimalist coverage prioritizing occipital and parietal protection for low-speed urban environments.
- Visor:Detachable or integrated sun shields addressing glare reduction for road cyclists in high-latitude summer conditions.
Mature deployment sits with Open Face configurations in established European cycling cities. Newer deployment is concentrated in Full Face variants as Asian-Pacific gravity parks expand trail infrastructure.
Material:
Cost tier stratification separates commodity inputs from performance grades, with manufacturing automation compressing historical premiums on advanced composites.
- EPS Foam:Expanded polystyrene liners absorb impact through controlled cellular compression, forming the universal energy management substrate across all price tiers. Multi-density layering configurations are gaining share fastest in competitive segments where Italian and Belgian pro teams specify graduated compression zones. REACH chemical restrictions are forcing reformulation investments in flame-retardant additive packages.
- Carbon Fiber:Aerospace-grade prepregs deliver sub-200-gram shell weights for stage racing applications where rotational inertia affects neck strain over climbing durations. Automated layup processes in Taiwanese contract manufacturers are democratizing access previously confined to sponsored elite amateurs. Price positioning remains 4-8x above polycarbonate equivalents.
- Polycarbonate:Injection-molded outer shells providing abrasion resistance and weather sealing at mass-market cost structures.
- Fiberglass:Intermediate composite offering impact dispersion properties between polycarbonate and carbon fiber for mid-tier performance positioning.
Volume manufacturing concentrates on EPS Foam and Polycarbonate pairings for retail margins. Technical differentiation investments are flowing toward Carbon Fiber automation and multi-density foam engineering.
End User:
Regulatory mandates and life-stage replacement patterns create predictable demand windows that vary dramatically by purchaser decision-making autonomy.
- Commuters:Urban professionals integrating cycling into multimodal transit routines in London, New York, and Berlin. Subscription bundling with bike-share memberships is displacing traditional retail relationships. MIPS technology penetration runs highest in this segment as daily use justifies premium positioning.
- Children:Mandatory helmet laws for minors in France, Spain, and several German Länder institutionalize early-age usage patterns. Parents exhibit low price sensitivity on safety-rated products, supporting margin premiums for CPSC and EN 1078 certified designs. Replacement cycles accelerate through growth-phase head circumference changes.
- Adults:Recreational weekend cyclists with intermittent usage patterns and deferred replacement behavior.
- Sports Enthusiasts:Competitive and serious amateur cyclists prioritizing aerodynamic and weight specifications.
Replacement predictability sits with Children through mandated age-based sizing. Margin expansion is concentrating in Commuters through subscription-model lifetime value capture.
Distribution Channel:
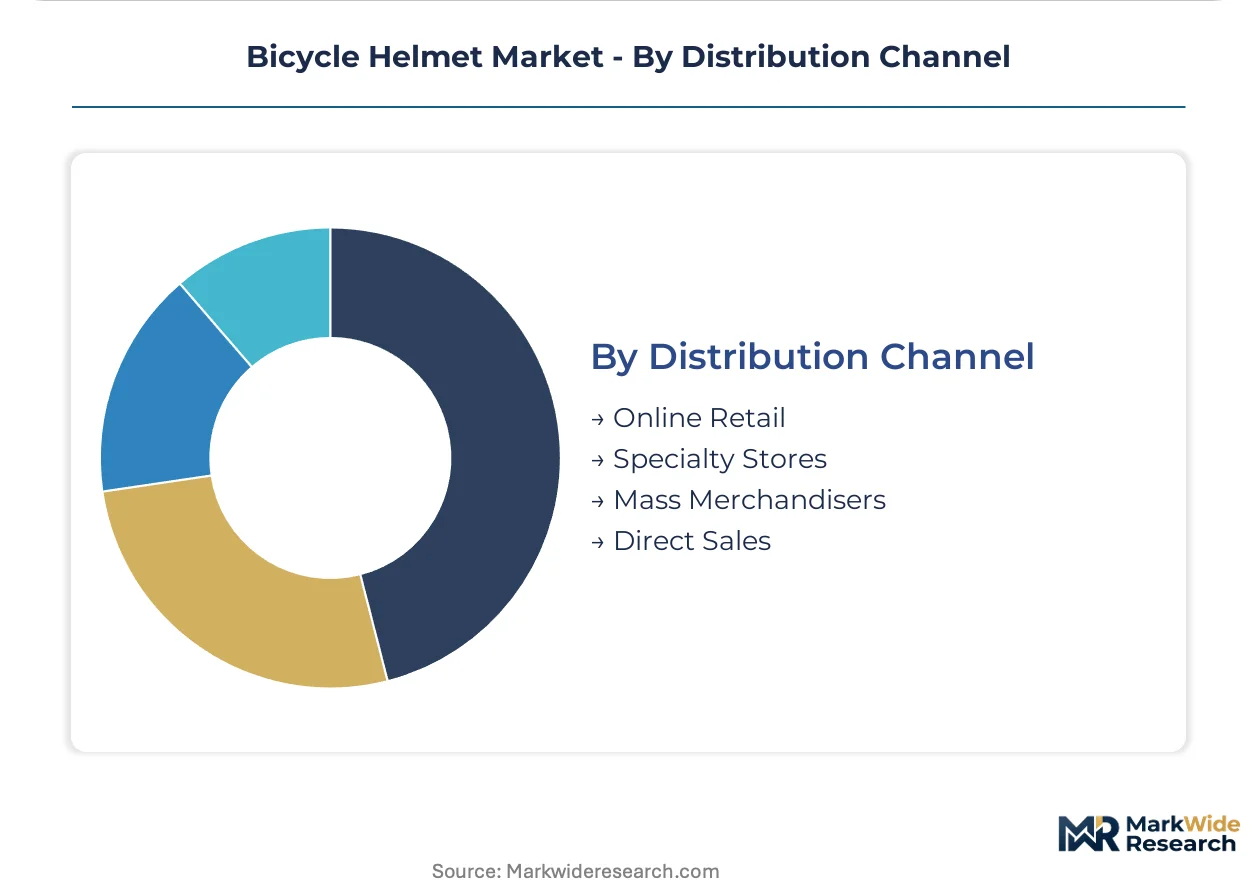
Channel fragmentation reflects divergent customer research behaviors between specification-driven performance buyers and convenience-oriented urban adopters.
- Online Retail:Digital platforms enable direct comparison of MIPS certification status, weight specifications, and ventilation scores for research-intensive purchasers. Specialized Bicycle Components and similar performance brands leverage owned channels to sustain premium positioning without dealer margin stacking. Return logistics complexity limits trial rates for fit-critical purchases.
- Specialty Stores:Professional fitting services and immediate inventory availability support higher conversion on premium-price configurations. Trek Bicycle Corporation anchors North American presence through dealer network density. Staff expertise in cranial measurement and retention system adjustment justifies service premiums.
- Mass Merchandisers:Big-box retail capturing price-sensitive occasional cyclists through basic CPSC-compliant offerings.
- Direct Sales:Manufacturer-owned channels eliminating intermediary margins for brand-loyal repeat purchasers.
Service integration sits with Specialty Stores through fitting expertise. Volume scaling is concentrating in Online Retail as direct-to-consumer infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen's metropolitan cycling network anchors European helmet normalization, with Amsterdam and Berlin replicating its infrastructure investment model across distinct regulatory environments.
Germany
Mandatory helmet laws for children in multiple Länder institutionalize early-age usage patterns that sustain replacement demand. KBA oversight of e-bike speed classifications triggers helmet standard revisions for powered mobility segments. Manufacturing concentrates in Baden-Württemberg, where precision tooling suppliers serve both automotive and cycling equipment producers.
United States
Urban professionals in New York and Portland integrate cycling into multimodal transit routines, normalizing daily helmet adoption. CPSC impact testing protocols mandate compliance for all domestic sales, creating certification cost barriers for new entrants. Trek Bicycle Corporation anchors North American distribution through dealer network density concentrated in Midwest manufacturing corridors.
Netherlands
Amsterdam's metropolitan cycling infrastructure supports the highest per-capita helmet normalization rate among established European cycling cities. E-bike speed reclassifications under Dutch transport authority guidelines expand addressable product portfolios beyond traditional cycling. Distribution clusters in Randstad benefit from port logistics connecting Asian component suppliers to European assembly operations.
Italy
Pro-team sponsorships and competitive cycling heritage drive premium positioning in road cycling segments. EN 1078 certification requirements enforced across EU member states reshape product specifications for export-oriented manufacturers. KASK S.p.A. competes from Lombardy, leveraging Italian manufacturing heritage in high-performance protective equipment.
France
Mandatory helmet laws for minors expand addressable consumer segments through institutionalized early-age usage. ANSM and CNIL regulatory frameworks intersect with product safety and data protection requirements for smart helmet integrations. Cycling infrastructure investment in Paris supports subscription bundling models with dockless fleet operators negotiating bulk procurement contracts.
Bicycle Helmet Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated manufacturers control molding and assembly while specialist brands outsource production to Asian contract foundries. The vendor base spans three tiers: multinational sporting goods conglomerates with diversified equipment portfolios, dedicated cycling equipment specialists with deep category focus, and private-label assemblers serving mass-market retail channels. Strategic moves concentrate on MIPS technology licensing agreements and direct-to-consumer channel expansion that fragments traditional dealer dependencies.
Within the specialist tier, KASK S.p.A. and SCOTT Sports SA exemplify European heritage positioning that commands premium pricing through pro-team visibility and competitive cycling credibility. Among diversified sporting goods operators, Vista Outdoor Operations LLC occupies a position spanning multiple outdoor equipment categories, while Dorel Sports anchors mass-market volume through retail channel density. Trek Bicycle Corporation and Specialized Bicycle Components represent the integrated manufacturer archetype, controlling design, distribution, and brand positioning across performance and commuter segments.
| Leading Market Players |
|---|
| Vista Outdoor Operations LLC |
| Trek Bicycle Corporation |
| Specialized Bicycle Components |
| SCOTT Sports SA |
| Dorel Sports |
| Giro Sport Design |
| Bell Helmets |
| KASK S.p.A. |
| Giant Bicycles |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between MIPS-integrated premium tiers and basic CPSC-compliant entry levels manifests in divergent margin structures and supply chain configurations. EN 1078 compliance costs in European markets anchor pricing floors for export-oriented manufacturers while multi-density EPS foam sourcing concentrates procurement leverage among Taiwanese and Chinese compound suppliers.
Pricing Analysis
Cost-down pressure on standard-tier helmets accelerates because automated polycarbonate molding in Chinese contract foundries compresses unit economics for undifferentiated products. Three-tier pricing structure across premium, standard, and economy levels reflects MIPS licensing fees, carbon fiber shell grades, and polycarbonate commodity positioning respectively. Price differentiation hinges on EN 1078 and CPSC dual-certification status. Commuter segments exhibit lowest price sensitivity where subscription bundling obscures per-unit visibility, while mass-market retail purchasers at big-box channels drive hardest negotiation.
Supply Chain Analysis
Direct-to-specialty-store channels handle premium fitting-service demand while mass-merchandiser procurement consolidates volume through distributor intermediaries. Manufacturing concentrates in Taiwan, China, and Vietnam where precision molding equipment and EPS foam compounding capabilities cluster. Raw material dependencies center on expanded polystyrene resin, aerospace-grade carbon fiber prepregs, and polycarbonate pellets. Single-source vulnerability runs through East Asian EPS foam production where petrochemical feedstock volatility transmits directly to liner costs. Distribution runs through dealer networks for premium brands and direct-to-consumer platforms for performance specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EN 1078 certification requirements create barrier-to-entry moats that protect incumbent positions from undifferentiated import competition.
For Market Incumbents: Lock in MIPS technology licensing exclusivities through multi-year agreements that foreclose competitor access to rotational impact protection systems. Secure captive EPS foam supply arrangements with Taiwanese compounders to insulate margin structures from petrochemical volatility. Certification timeline compression under accelerated EN 1078 revision cycles threatens seasonal product launch windows.
For New Entrants and Emerging Players: Launch via subscription bundling partnerships with bike-share operators in metropolitan markets where traditional retail relationships remain unformed. Children's helmet mandates in France and Spain present the most penetrable entry point given parental low price sensitivity and predictable replacement cycles. Direct-to-consumer digital channels enable specification comparison without dealer network infrastructure investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified sporting goods conglomerates seeking cycling category exposure. Long-term viability favors manufacturers with integrated molding capabilities and multi-certification platform designs rather than asset-light brand licensors. Watch e-bike speed reclassification announcements from German KBA and Dutch transport authorities as inflection indicators for helmet standard revision timing.
| Strategic Initiative | Industry Significance |
|---|---|
| MIPS Technology Licensing | Secures rotational impact protection differentiation that commands price premiums across certified product lines. |
| Multi-Certification Platform Investment | Enables simultaneous CPSC and EN 1078 compliance that opens dual-market revenue streams. |
| Subscription Bundling Partnership | Captures lifetime value from bike-share members beyond traditional single-transaction retail relationships. |
| Carbon Fiber Manufacturing Automation | Compresses production cost curves that previously confined high-margin products to elite segments. |
| Captive EPS Foam Supply Arrangement | Insulates margin structures from East Asian petrochemical feedstock volatility and logistics exposure. |
Methodological Framework
Independent corroboration across primary interviews with helmet product managers, cycling retail buyers, regulatory compliance officers, and EPS foam procurement leads underwrites the qualitative findings. Secondary validation draws from CPSC certification databases, EN 1078 testing records, customs trade data for polycarbonate and carbon fiber imports, and bicycle industry association membership directories. Bottom-up manufacturer capacity assessments triangulate against top-down consumer expenditure estimates across commuter, children, and sports enthusiast segments.
Comparable-period anchoring to historical certification adoption curves and e-bike penetration rates establishes the forecast window baseline. Segmentation modeling spans product type, material grade, end-user category, and distribution channel across the projection horizon. CAGRs derive from unit shipment trajectories and average selling price evolution by tier. MIPS licensing penetration rates and urban cycling infrastructure investment pipelines constitute key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for smart sensor integration or biodegradable foam materials would alter the outlook. Forecasts reflect assumptions regarding regulatory harmonization timelines and e-bike speed classification stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Football Equipment Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
US Fencing Market
Sports Equipment
Hydration Belt Market