
 Europe Educational Robot Market | 2026-2036
Europe Educational Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Educational Robot Market Insights
The capability gap between industrial-grade component sourcing and consumer-facing assembly operations is redrawing competitive boundaries in Europe. FANUC Corporation leverages its precision servo motor expertise to supply high-reliability actuators for educational platforms. The LEGO Group anchors its position through captive manufacturing of modular brick-compatible robotics elements. PAL Robotics competes by specializing in humanoid platforms designed for European university research partnerships.
Educational robots are programmable electro-mechanical systems incorporating servo actuators, microcontrollers, and sensor arrays, typically operating at voltages between 5V and 24V, designed to teach programming logic, mechanical engineering principles, and autonomous system behavior through hands-on interaction. Humanoid robots command premium positioning in STEM education applications due to their anthropomorphic engagement advantages for student retention. Coding robots are gaining fastest in primary school deployments where block-based programming interfaces lower instructor training barriers. Sensor-based systems occupy mature margin pools in extracurricular tutoring centers that prioritize hardware durability over software sophistication.
CE marking requirements under EU machinery directives govern electrical safety and electromagnetic compatibility for classroom-deployed robotics. ECHA REACH regulations restrict hazardous substances in plastic housings and electronic components, directly influencing supplier qualification processes. The EU AI Act imposes risk-classification obligations on machine learning-enabled tutoring functions that adapt to individual student performance. Stakeholders must monitor harmonized standard updates from European standardization bodies as these will determine which sensor architectures and AI training methodologies achieve market access across member states.
Market Dynamics
The EU AI Act risk-classification framework is forcing educational robot vendors to rearchitect sensor architectures and machine learning pipelines before classroom deployment, compressing development timelines while elevating compliance costs.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification obligations for adaptive tutoring functions are accelerating vendor investment in explainable AI architectures, creating competitive differentiation for early certifiers.
- German national digital education initiatives:Federal funding for STEM infrastructure in secondary schools is expanding procurement budgets for programmable electro-mechanical systems across federal states.
- Humanoid platform anthropomorphic engagement:University research partnerships in France and Spain are prioritizing bipedal robots for cognitive science and human-robot interaction studies.
Market Restraints
- Precision servo motor supply concentration:Industrial-grade actuator sourcing remains concentrated among Japanese and German industrial automation suppliers, exposing educational platform assemblers to lead time volatility.
- ECHA REACH substance restrictions:Hazardous substance limitations in plastic housings and electronic components are disqualifying legacy Asian component suppliers from European qualification processes.
- Block-based programming substitution:Low-cost tablet-based coding applications are displacing entry-level sensor-based hardware in primary school budgets.
Strategic Opportunities
- Eastern European underpenetration:Poland, Romania, and Czechia exhibit sub-15% robotics curriculum adoption in public secondary education, presenting first-mover expansion corridors.
- Extracurricular tutoring center channel:After-school STEM academies in Italy and Netherlands are unbundling hardware durability from software sophistication, creating margin pools for sensor-focused specialists.
- EU Green Deal circular economy incentives:Modular brick-compatible robotics elements qualify for sustainable procurement preferences in public sector tenders.
Industry Challenges
- Harmonized standard update tracking:European standardization bodies are revising electromagnetic compatibility requirements faster than vendor certification cycles, creating market access uncertainty.
- Cross-functional talent scarcity:Educational robot development requires simultaneous competence in mechanical engineering, pedagogy, and EU regulatory compliance, a combination rarely found in single hiring pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Educational Robot Market |
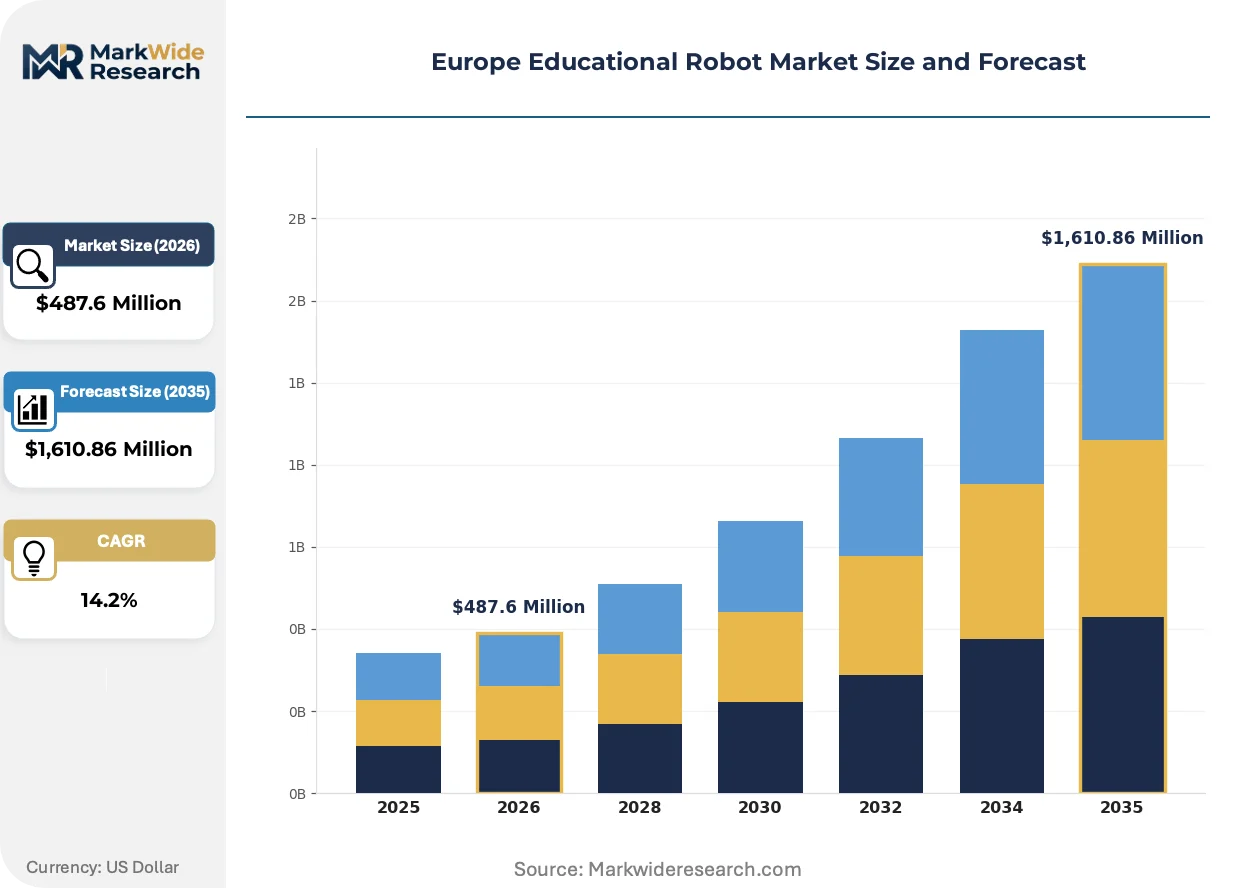
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humanoid Robots, Robotic Kits, Drones, Coding Robots Application: STEM Education, Special Needs Education, Extracurricular Activities, Classroom Learning End User: Primary Schools, Secondary Schools, Tutoring Centers, Educational Institutions Technology: Artificial Intelligence, Machine Learning, Sensor-Based Systems, Visual Recognition |
| Companies Covered | FANUC Corporation, Robotis, The LEGO Group, VEX Robotics, Makeblock, SoftBank Robotics Group, PAL Robotics, Dobot, ABB Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Educational Robot Market Trends and Innovations
Generative AI integration is fragmenting traditional educational robot architectures, splitting the market between edge-deployed inference engines and cloud-dependent adaptive tutoring systems with divergent hardware requirements.
Edge-deployed microcontroller inference is fragmenting the dominance of cloud-connected educational platforms. Primary schools in Denmark and Finland are prioritizing on-device processing to satisfy GDPR data minimization requirements. This shift compresses margins for vendors dependent on recurring software-as-a-service revenue models.
The EU AI Act risk-classification framework is mandating human oversight protocols for machine learning-enabled tutoring functions. Vendors must now document training data provenance and algorithmic explainability before CE marking. University research partnerships in Germany and Belgium are delaying procurement until harmonized standards clarify compliance pathways.
Public sector procurement consolidation is compressing vendor sales cycles across European ministries of education. National framework agreements in France and Spain are displacing fragmented municipal purchasing, favoring suppliers with established public sector compliance infrastructure. Smaller vendors without dedicated government relations functions are retreating toward private tutoring center channels.
Europe Educational Robot Market Segmentation
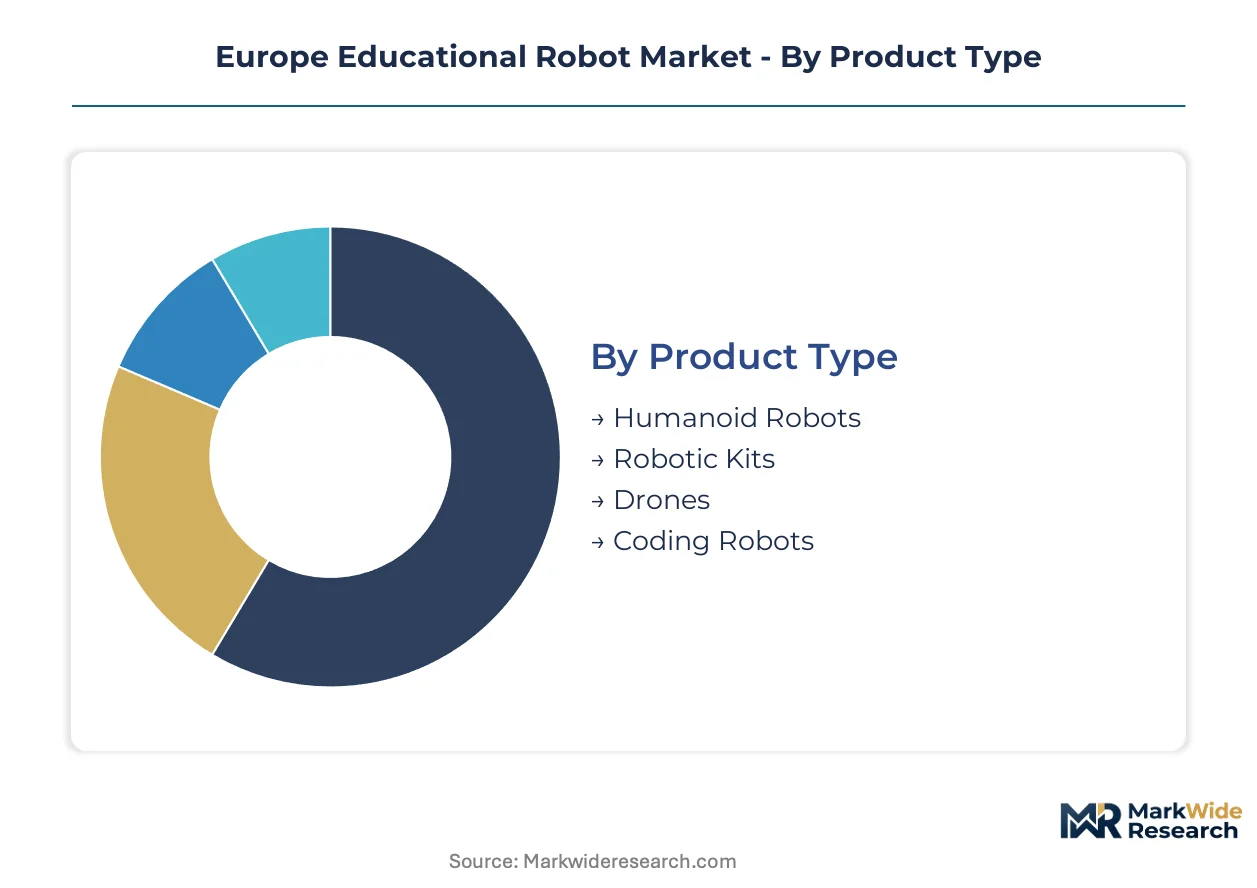
Educational robot architectures diverge sharply across European procurement channels. National curriculum mandates in Germany and France favor programmable hardware with explicit pedagogical outcomes, while Italian and Dutch tutoring centers prioritize hardware durability over software sophistication.
Product Type:
Humanoid robots concentrate demand in Western European university partnerships, while modular kits dominate Eastern European secondary school budgets seeking scalable entry points.
- Humanoid Robots:Bipedal platforms integrate precision servo actuators operating between 12V and 24V with anthropomorphic joint configurations. French and Spanish cognitive science departments are prioritizing these systems for human-robot interaction research, driven by EU AI Act requirements for documented algorithmic explainability in adaptive tutoring functions.
- Coding Robots:Entry-level platforms feature block-based programming interfaces and low-voltage microcontroller architectures. Danish and Finnish primary schools are deploying these for GDPR-compliant edge processing, displacing cloud-dependent alternatives from procurement shortlists.
- Robotic Kits:Modular electro-mechanical assemblies with brick-compatible interfaces support progressive skill-building across age cohorts.
- Drones:Quadcopter and hexacopter platforms teach aerodynamic principles and autonomous navigation algorithms in extracurricular STEM academies.
Humanoid robots command the established base. The steepest expansion runs through coding robots.
Application:
Cost tier stratification separates premium university research deployments from volume-driven primary school hardware.
- STEM Education:Comprehensive curricula integrating mechanical engineering, programming logic, and autonomous system behavior through hands-on electro-mechanical platforms. German federal states are expanding procurement budgets for programmable systems, anchored by national digital education initiatives.
- Classroom Learning:Structured pedagogical deployments within formal lesson plans require CE-marked electrical safety and electromagnetic compatibility certification. Belgium and Netherlands ministries are consolidating framework agreements, compressing vendor sales cycles toward established public sector compliance infrastructure.
- Special Needs Education:Adaptive interfaces and sensory feedback systems address diverse learning requirements in supported environments.
- Extracurricular Activities:After-school programs and tutoring centers prioritize hardware durability over software sophistication, creating margin pools for sensor-focused specialists.
STEM education absorbs the premium tier. Classroom learning is gaining share fastest in consolidated procurement markets.
End User:
Volume concentration sits with secondary schools, while margin extraction favors tutoring centers with unbundled service models.
- Secondary Schools:Federal and state-level funding streams across Germany, France, and the United Kingdom are expanding robotics curricula through national digital education initiatives. These institutions require full EU AI Act compliance for any machine learning-enabled tutoring functions.
- Tutoring Centers:After-school STEM academies in Italy and the Netherlands operate outside centralized procurement frameworks. This channel unbundles hardware durability from software sophistication, rewarding sensor-based specialists with mature margin pools.
- Primary Schools:Block-based programming interfaces lower instructor training barriers, though tablet-based coding applications are displacing entry-level hardware in budget-constrained environments.
- Educational Institutions:Universities and vocational training centers demand humanoid platforms for research partnerships and advanced engineering instruction.
Secondary schools anchor volume procurement. Tutoring centers represent the most attractive margin expansion trajectory.
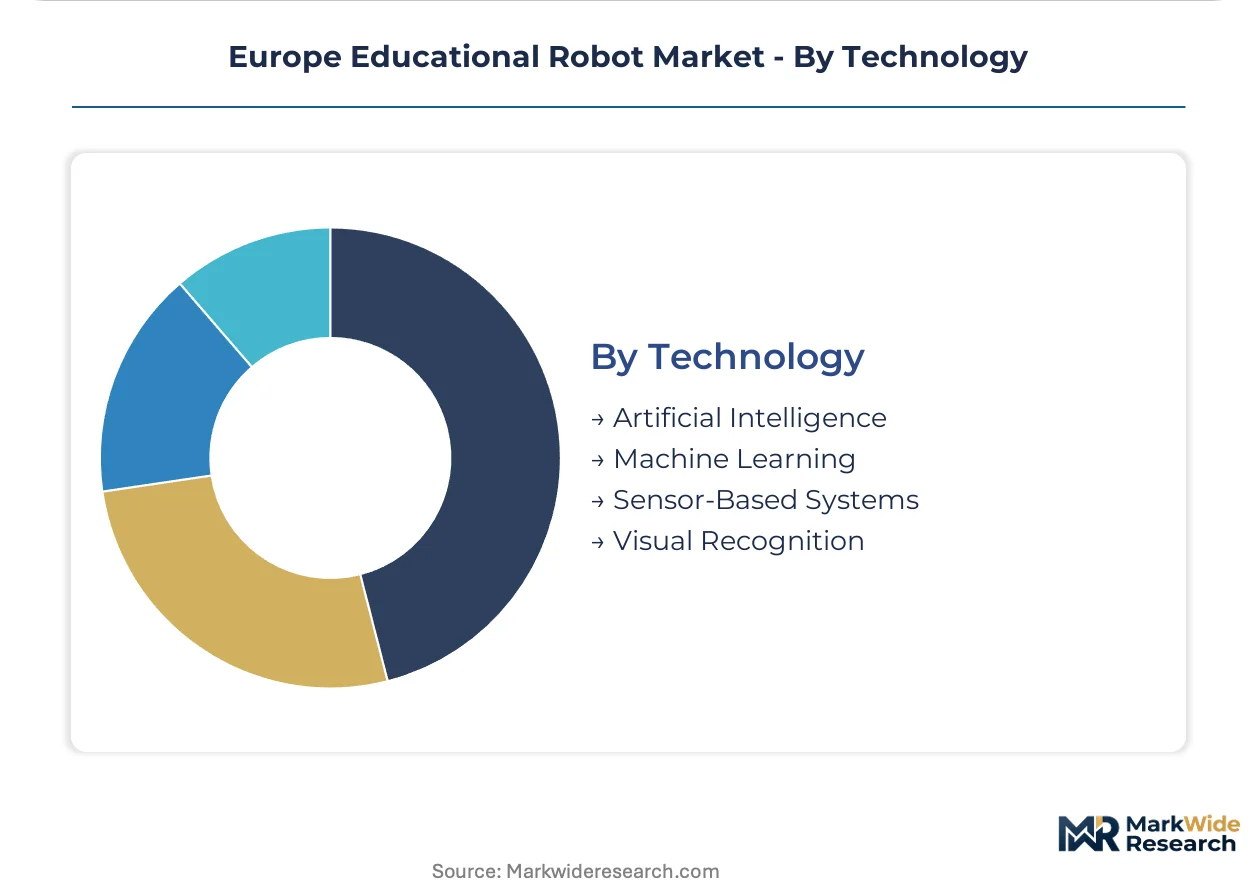
Technology:
Supply concentration for industrial-grade actuators and sensor arrays shapes competitive positioning across technology tiers.
- Sensor-Based Systems:Arrays of proximity, tactile, and environmental sensors enable reactive behaviors without complex processing architectures. Extracurricular tutoring centers in Italy and the Netherlands favor these systems for hardware durability in high-usage environments.
- Artificial Intelligence:Machine learning-enabled tutoring functions require documented training data provenance and human oversight protocols under EU AI Act risk-classification frameworks. University research partnerships in Germany and Belgium are delaying procurement until harmonized standards clarify compliance pathways.
- Machine Learning:Adaptive algorithms modifying content delivery based on individual student performance patterns face elevated regulatory scrutiny.
- Visual Recognition:Camera-based object and gesture detection systems enable interactive programming exercises and environmental mapping.
Sensor-based systems defend the installed base. Artificial intelligence is climbing the fastest despite regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Western European procurement frameworks, while Eastern European markets trade hardware durability against constrained public education budgets. German and French national digital initiatives absorb volume at standard-tier pricing. Polish and Romanian municipalities face longer sales cycles without consolidated framework agreements.
Germany
Federal-state funding streams for STEM infrastructure are expanding robotics curricula across secondary schools. The KBA and federal digital education initiatives mandate CE-marked programmable systems with documented pedagogical outcomes. Bavaria's Munich-Stuttgart corridor hosts precision actuator suppliers serving university research partnerships.
France
National framework agreements are consolidating procurement from fragmented municipal purchasing toward centralized ministry contracts. The ANSM and CNIL enforce GDPR-compliant edge processing requirements for classroom-deployed AI-enabled tutoring functions. The Île-de-France region anchors cognitive science research prioritizing humanoid platforms with algorithmic explainability documentation.
United Kingdom
Post-Brexit regulatory divergence is creating dual compliance burdens for vendors serving both UK and EU markets. The Department for Education's national curriculum mandates are expanding programmable hardware procurement in state secondary schools. Greater London's EdTech cluster concentrates adaptive tutoring system development for export markets.
Italy
Extracurricular tutoring centers in Milan and Turin are unbundling hardware durability from software sophistication, creating margin pools for sensor-focused specialists. ECHA REACH substance restrictions are disqualifying legacy Asian component suppliers from qualification processes. The Emilia-Romagna robotics corridor hosts aftermarket service providers for high-usage after-school environments.
Poland
Sub-15% robotics curriculum adoption in public secondary education presents first-mover expansion corridors for scalable entry-level platforms. The country's national standardization body is harmonizing electromagnetic compatibility requirements with EU machinery directives. Warsaw's emerging EdTech cluster is piloting modular brick-compatible systems for budget-constrained municipal procurement.
Europe Educational Robot Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with industrial automation heritage separating precision actuator suppliers from consumer-facing assembly operations. The vendor base organizes around three strategic tiers: industrial-grade component suppliers, captive manufacturing specialists, and humanoid platform researchers. Consolidation pressures are accelerating through national framework agreements that favor established public sector compliance infrastructure. Dominant competitive moves include strategic partnerships with university research programs and portfolio diversification into GDPR-compliant edge processing architectures.
Within the industrial heritage tier, FANUC Corporation and ABB Group exemplify precision servo motor expertise supplying high-reliability actuators for educational platforms. PAL Robotics occupies a specialized position designing humanoid systems for European university research partnerships. The LEGO Group anchors the captive manufacturing archetype through modular brick-compatible robotics elements produced in-house.
| Leading Market Players |
|---|
| FANUC Corporation |
| Robotis |
| The LEGO Group |
| VEX Robotics |
| Makeblock |
| SoftBank Robotics Group |
| PAL Robotics |
| Dobot |
| ABB Group |
| Others |
Pricing and Supply Chain Analysis
Tablet-based coding applications displacing entry-level sensor hardware in primary school budgets simultaneously shift component sourcing toward Asian microcontroller foundries and compress margin pools for European electro-mechanical assemblers. This substitution dynamic redraws procurement geography while intensifying price competition in the sub-200 euro segment.
Pricing Analysis
The customization-premium spread separates configured-to-order university research platforms from standard-tier secondary school deployments. Three-tier pricing structure across premium, standard, and economy levels reflects CE certification grade and algorithmic explainability documentation under EU AI Act requirements. Cost compression in the economy tier is intensifying because block-based tablet substitutes eliminate hardware procurement entirely. Tutoring centers in Italy and the Netherlands exhibit the highest price sensitivity, while German university partnerships absorbing federal research funding show the least.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion are elevating landed costs for Japanese precision servo motors and Taiwanese microcontroller shipments. Component sourcing draws from Germany for industrial-grade actuators, Japan for high-reliability servo systems, and China for plastic housings and sensor arrays. Single-source vulnerability concentrates in precision actuator supply where FANUC and ABB dominate educational platform specifications. Distribution runs through national ministry framework agreements in France and Spain alongside fragmented municipal procurement in Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's educational robot market represents an early-cycle expansion story justified by sub-15% robotics curriculum penetration in Polish and Romanian public secondary education against accelerating EU AI Act compliance investment cycles.
For Market Incumbents: Consolidate public sector compliance infrastructure to capture French and Spanish national framework agreement consolidation. Deepen captive supply of precision actuators through partnerships with German industrial automation suppliers to offset Japanese sourcing concentration risk. Prioritize CE marking pre-certification for explainable AI architectures ahead of harmonized standard finalization. For New Entrants and Emerging Players: Lead with GDPR-compliant edge processing architectures targeting Danish and Finnish primary school procurement shortlists. Poland and Romania present the most penetrable geography given fragmented municipal purchasing without consolidated frameworks. Position through modular brick-compatible robotics elements qualifying for EU Green Deal sustainable procurement preferences. For Investors and Strategic Acquirers: The market sits at a standards-clarification phase that favors vertically integrated component suppliers over pure-play software vendors. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than pedagogical content differentiation. Acquisition targets should demonstrate established ECHA REACH qualification processes and dedicated government relations functions. Watch harmonized electromagnetic compatibility standard updates from European standardization bodies as the critical inflection signal for market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Pre-Certification | Early algorithmic explainability documentation creates competitive differentiation ahead of harmonized standard finalization. |
| Precision Actuator Supply Partnership | German and Japanese industrial automation relationships secure high-reliability component allocation amid sourcing concentration. |
| GDPR-Compliant Edge Processing Architecture | On-device inference satisfies Danish and Finnish data minimization requirements displacing cloud-dependent alternatives. |
| Eastern European Distribution Buildout | Direct municipal engagement in Poland and Romania captures first-mover position before framework agreement consolidation. |
| Modular Brick-Compatible System Development | LEGO-compatible interfaces qualify for EU Green Deal circular economy procurement preferences in public tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with educational technology procurement officers at German federal state ministries, French cognitive science department heads, Italian after-school STEM academy operators, and component sourcing managers at European robot assemblers. Secondary validation drew from EU AI Act implementation guidance documents, ECHA REACH substance restriction updates, CE marking harmonized standards databases, and national digital education initiative budget disclosures. Bottom-up demand modeling across procurement channels triangulated against top-down market sizing from vendor shipment data.
Across the analysis window, forecasts applied segment-specific growth trajectories for humanoid platforms, coding robots, sensor-based systems, and modular kits against end-user penetration curves in secondary schools, tutoring centers, and primary education. Modeled dimensions included product architecture, application context, technology tier, and geographic adoption cluster. CAGRs derived from polynomial trend fitting to historical procurement volumes adjusted for EU regulatory compliance investment cycles and federal funding program timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or accelerated German federal STEM budget expansion would require recalibration. Forecasts reflect assumptions regarding harmonized standard publication timing and REACH substance restriction implementation consistency. Specific risk factors include electromagnetic compatibility requirement revisions outpacing vendor certification cycles and tablet-based coding application substitution accelerating beyond modeled rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cordless Router Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Cleaning Robot Market