
 North America Automated Liquid Handling Market | 2026-2036
North America Automated Liquid Handling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automated Liquid Handling Market Analytics
Multi-source procurement for precision dispensing components is broadening as instrument manufacturers diversify supplier bases to mitigate lead-time volatility. Hamilton Company anchors its position through captive manufacturing of precision syringe pumps in Nevada. Beckman Coulter competes via deep integration of liquid-level sensing with its Biomek workstation portfolio. Danaher Corp. controls distribution density through its Pall Life Sciences channel network across the United States and Canada.
Automated liquid handling encompasses electromechanical systems that aspirate, dispense, and transfer microliter-to-milliliter volumes with positional accuracy below one millimeter, employing air-displacement or positive-displacement mechanisms coupled to robotic XYZ gantries. These systems eliminate manual pipetting variability in quantitative workflows ranging from ELISA preparation to next-generation sequencing library construction. Workstation-class platforms currently dominate capital expenditure budgets due to their modular deck configurations and third-party device integration capabilities. Academic institutions represent the fastest-growing end-user category as NIH funding priorities shift toward reproducibility infrastructure and core facility modernization. Software automation layers command expanding margin pools as laboratories prioritize protocol standardization and cloud-connected fleet management over hardware-only procurement.
FDA oversight of diagnostic device manufacturing under 21 CFR Part 820 shapes equipment validation requirements, while EPA Good Automated Laboratory Practices influence environmental testing laboratory procurement specifications. Health Canada Medical Device Licensing imposes parallel conformity obligations for cross-border instrument deployment. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions affecting disposable tip chemistries and their compatibility with existing fluid path architectures.
Market Dynamics
Contract Research Organizations are consolidating high-throughput screening workflows onto unified robotic platforms, compressing capital deployment timelines and reshaping vendor qualification criteria across pharmaceutical and biotechnology laboratories.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in pharmaceutical laboratories are accelerating equipment replacement cycles and validating investments in compliant automated systems.
- NIH reproducibility infrastructure funding:Academic core facility modernization programs are expanding procurement budgets for workstation-class liquid handling platforms.
- Next-generation sequencing library construction:Clinical diagnostics laboratories are automating nucleic acid preparation workflows to match rising sample volumes.
Market Restraints
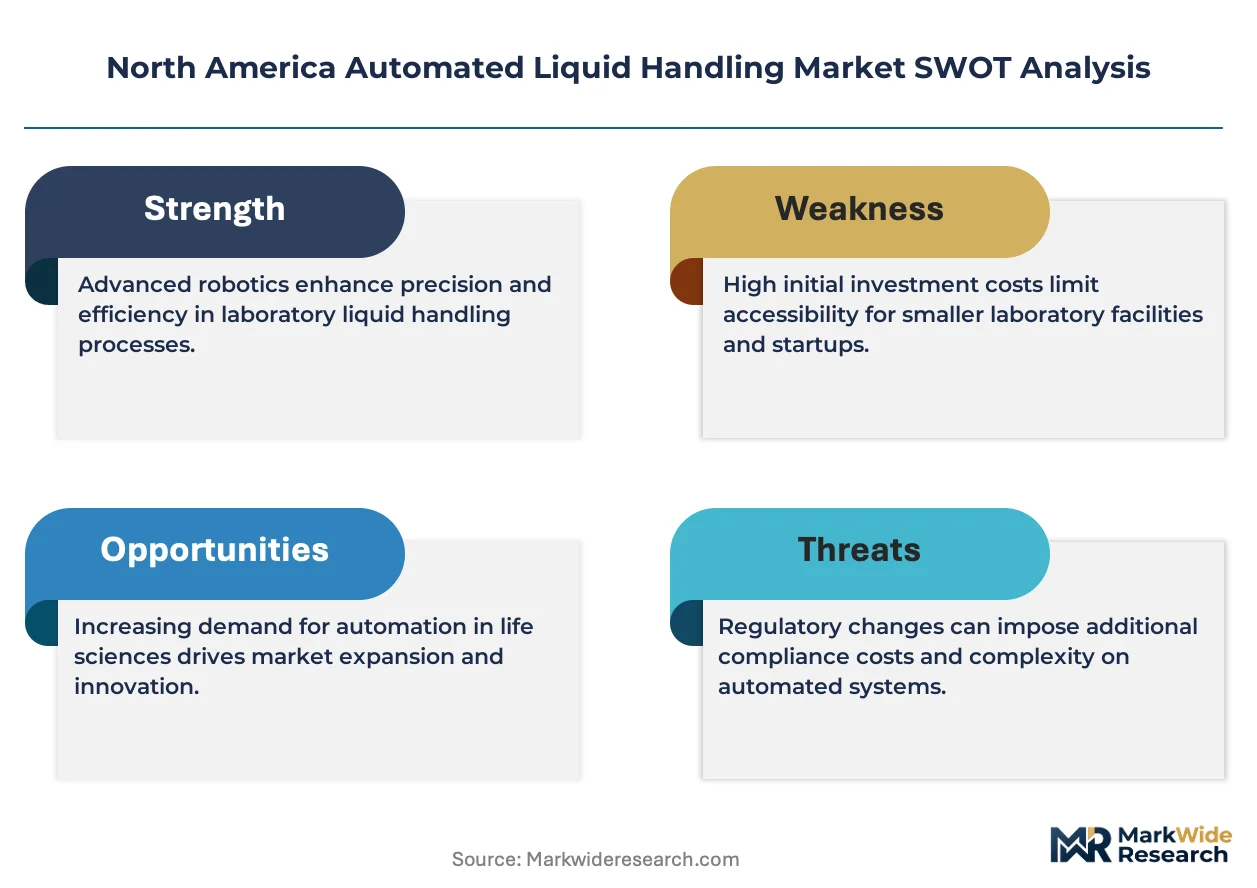
- Precision component supply concentration:Syringe pump and linear actuator manufacturing clusters in specific Asian manufacturing regions create lead-time volatility for North American instrument assemblers.
- Per- and polyfluoroalkyl substance restrictions:EPA regulatory pressure on disposable tip chemistries threatens compatibility with legacy fluid path architectures.
- Capital intensity barriers:Workstation-class platform acquisition costs limit penetration among mid-sized environmental testing laboratories.
Strategic Opportunities
- Cloud-connected fleet management software:Laboratories are prioritizing protocol standardization and remote monitoring capabilities over hardware-only procurement.
- Canadian cross-border deployment:Health Canada Medical Device Licensing alignment with FDA validation protocols reduces regulatory friction for unified North American product strategies.
- Cell therapy manufacturing automation:GMP-compliant aseptic liquid handling systems address emerging demand from regenerative medicine production facilities.
Industry Challenges
- Multi-omics workflow integration:Laboratories struggle to harmonize automated liquid handling protocols across genomics, proteomics, and metabolomics pipelines without extensive custom programming.
- Validation documentation burdens:FDA 21 CFR Part 820 diagnostic device manufacturing oversight extends equipment qualification timelines and strains quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automated Liquid Handling Market |
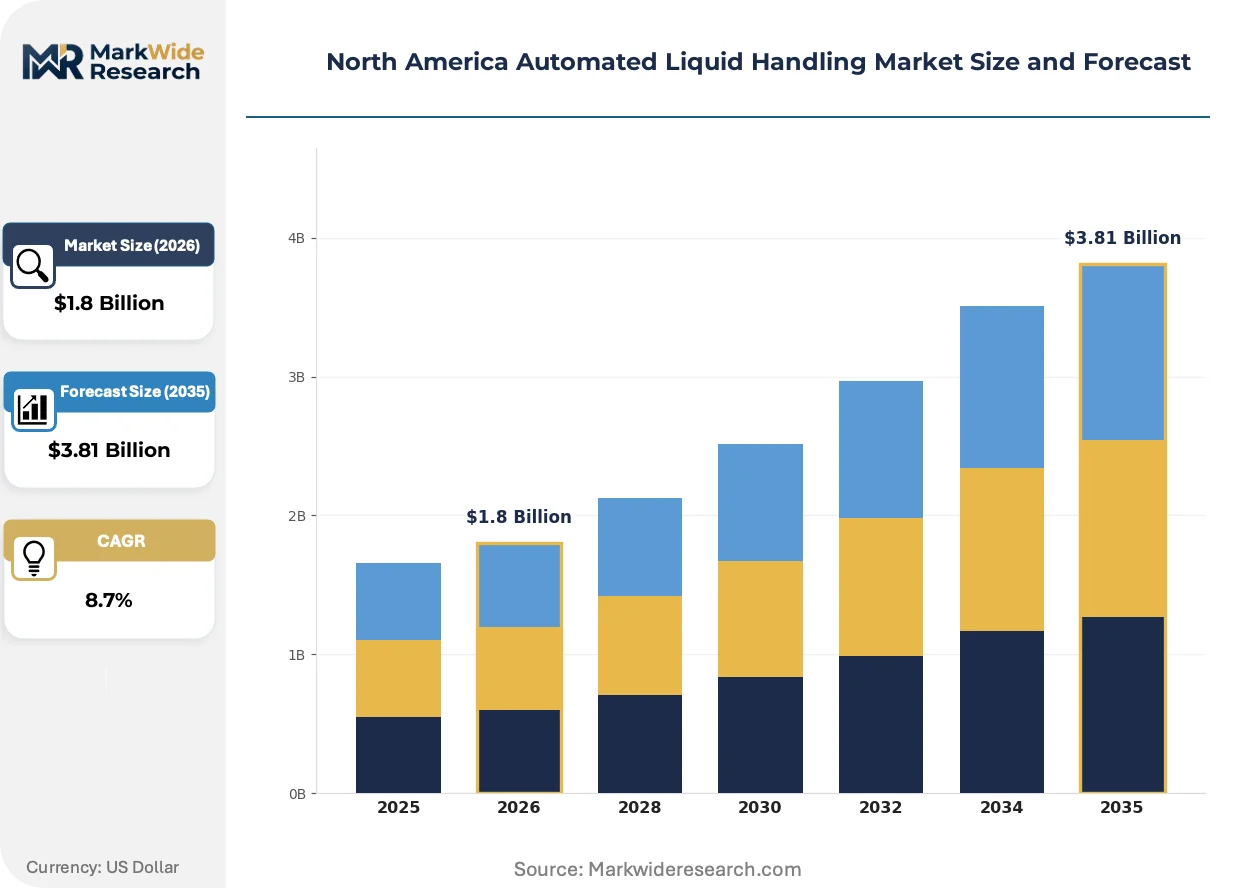
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Multi-Channel, Workstations, Automators End User: Pharmaceuticals, Biotechnology, Academic Institutions, Contract Research Organizations Technology: Robotic Systems, Dispenser Technology, Liquid-Level Sensors, Software Automation Application: Drug Discovery, Genomic Research, Clinical Testing, High-Throughput Screening |
| Companies Covered | Thermo Fisher Scientific Inc., Hamilton Company, Agilent Technologies Inc., Danaher Corp., Beckman Coulter, Mettler-Toledo International Inc., PerkinElmer Inc., Sartorius AG, Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automated Liquid Handling Market Evolving Landscape
Software automation layers are capturing expanding margin pools as laboratories prioritize data integrity, remote diagnostics, and predictive maintenance over standalone hardware specifications.
Positive-displacement pipetting mechanisms are overtaking air-displacement architectures in clinical diagnostics applications where viscosity variation and volatile solvent handling demand absolute volume accuracy. Reference laboratories in the Boston-Cambridge corridor are deploying these systems for patient sample aliquoting at throughputs exceeding ten thousand samples daily. The shift is compressing competitive differentiation around raw positional accuracy metrics while elevating liquid-level sensing and clot detection as purchase determinants.
EPA Good Automated Laboratory Practices are tightening validation documentation requirements for environmental testing laboratories engaged in hazardous waste characterization and drinking water compliance monitoring. The framework mandates audit trails for every aspirate and dispense operation, forcing equipment vendors to embed cryptographic timestamping and user authentication modules. Commercial laboratories in the Great Lakes region are delaying procurement decisions until vendors demonstrate full GLP compliance module integration.
Academic core facilities are unbundling after-sales service contracts from capital purchases, negotiating direct relationships with regional field service organizations for faster response times. The Massachusetts Institute of Technology and Harvard Medical School core facilities have pioneered multi-vendor maintenance pooling agreements that cross-train technicians on competing workstation platforms. This restructuring is visible across NIH-funded institutions prioritizing instrument uptime guarantees over manufacturer-branded service tiers.
North America Automated Liquid Handling Market Segmentation
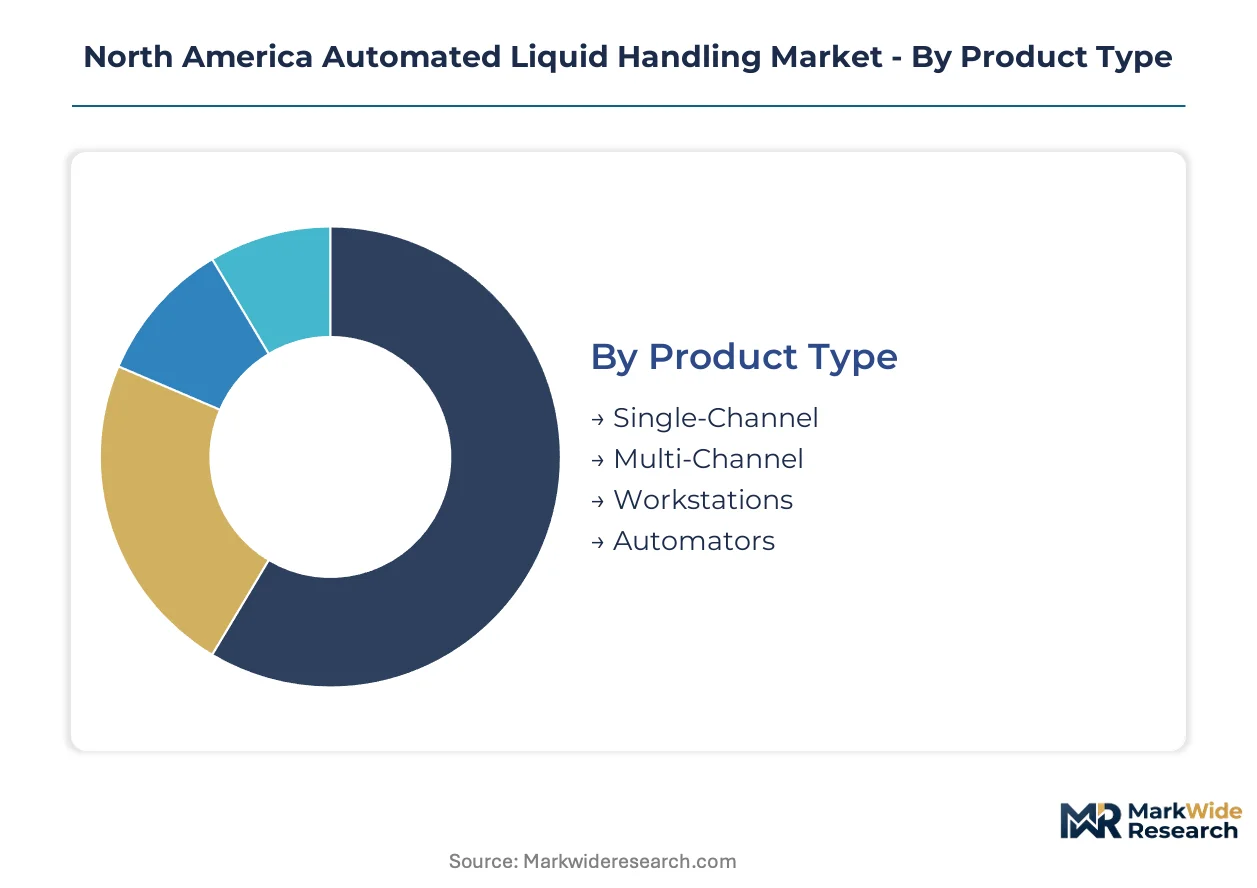
Equipment replacement cycles across North American laboratories vary sharply by segment, with compliance mandates and throughput requirements driving divergent upgrade timelines. Understanding these segment-specific dynamics clarifies where capital deployment concentrates and which technology layers capture expanding margin pools.
Product Type:
Replacement cycles for liquid handling hardware correlate directly with deck modularity and third-party integration depth, pushing laboratories toward platforms that extend functional lifespan through software upgrades rather than full hardware swaps.
- Workstations:Modular deck configurations support ELISA preparation, nucleic acid extraction, and next-generation sequencing library construction through interchangeable pipetting heads and third-party device integration. Pharmaceutical laboratories in the Boston-Cambridge corridor prioritize these platforms for their protocol flexibility and FDA 21 CFR Part 11 compliance modules.
- Automators:Large-scale integrated systems consolidate multiple liquid handling steps with robotic plate handling and environmental control for high-throughput screening operations. Contract Research Organizations deploy these for compound library management where daily throughputs exceed fifty thousand samples.
- Multi-Channel:Parallel pipetting architectures accelerate plate-based assays with eight-to-ninety-six simultaneous dispensing channels for genomics and proteomics workflows.
- Single-Channel:Precision dispensing for cell-based assays and low-volume reactions where positional accuracy below 0.1 millimeters is mandatory.
Workstations sit at the top of the volume ranking, with Automators climbing the fastest as CROs consolidate fragmented screening infrastructure onto unified platforms.
End User:
Customer procurement authority shapes technology selection, with centralized core facilities exercising different vendor qualification criteria than distributed R&D groups.
- Contract Research Organizations:High-throughput screening demands and compressed project timelines drive preference for robotic platforms with 24/7 uptime guarantees and remote diagnostic capabilities. CROs in the Research Triangle Park and San Diego clusters negotiate fleet-management software bundles that standardize protocols across multiple sites.
- Academic Institutions:NIH reproducibility infrastructure funding is modernizing core facilities with workstation-class platforms that serve multiple principal investigators through shared access models. Harvard Medical School and Stanford University have pioneered multi-vendor maintenance pooling agreements.
- Pharmaceuticals:FDA validation requirements for diagnostic device manufacturing under 21 CFR Part 820 extend equipment qualification timelines and elevate documentation standards.
- Biotechnology:Cell therapy manufacturing automation is emerging as a specialized demand segment for GMP-compliant aseptic liquid handling systems.
Contract Research Organizations command the largest installed base, with Academic Institutions expanding most quickly as federal funding priorities shift toward reproducibility infrastructure.
Technology:
Margin capture is concentrating in software layers as hardware commoditization accelerates and laboratories prioritize data integrity over raw positional specifications.
- Software Automation:Protocol standardization, cloud-connected fleet management, and predictive maintenance modules are commanding premium pricing over hardware-only procurement. These systems embed cryptographic timestamping and user authentication for EPA Good Automated Laboratory Practices compliance.
- Robotic Systems:XYZ gantry architectures with sub-millimeter positional accuracy form the mechanical foundation for workstation and automator platforms, with air-displacement and positive-displacement pipetting mechanisms.
- Liquid-Level Sensors:Capacitive and pressure-based detection systems enable clot detection and volume verification in clinical diagnostics applications.
- Dispenser Technology:Solenoid valve, piezoelectric, and peristaltic pumping architectures for non-contact dispensing in high-density plate formats.
Robotic Systems retain the highest shipment volumes, with Software Automation gaining share fastest as recurring revenue models displace one-time hardware sales.
Application:
Workflow integration complexity varies by application, with multi-omics pipelines demanding more extensive custom programming than standardized clinical assays.
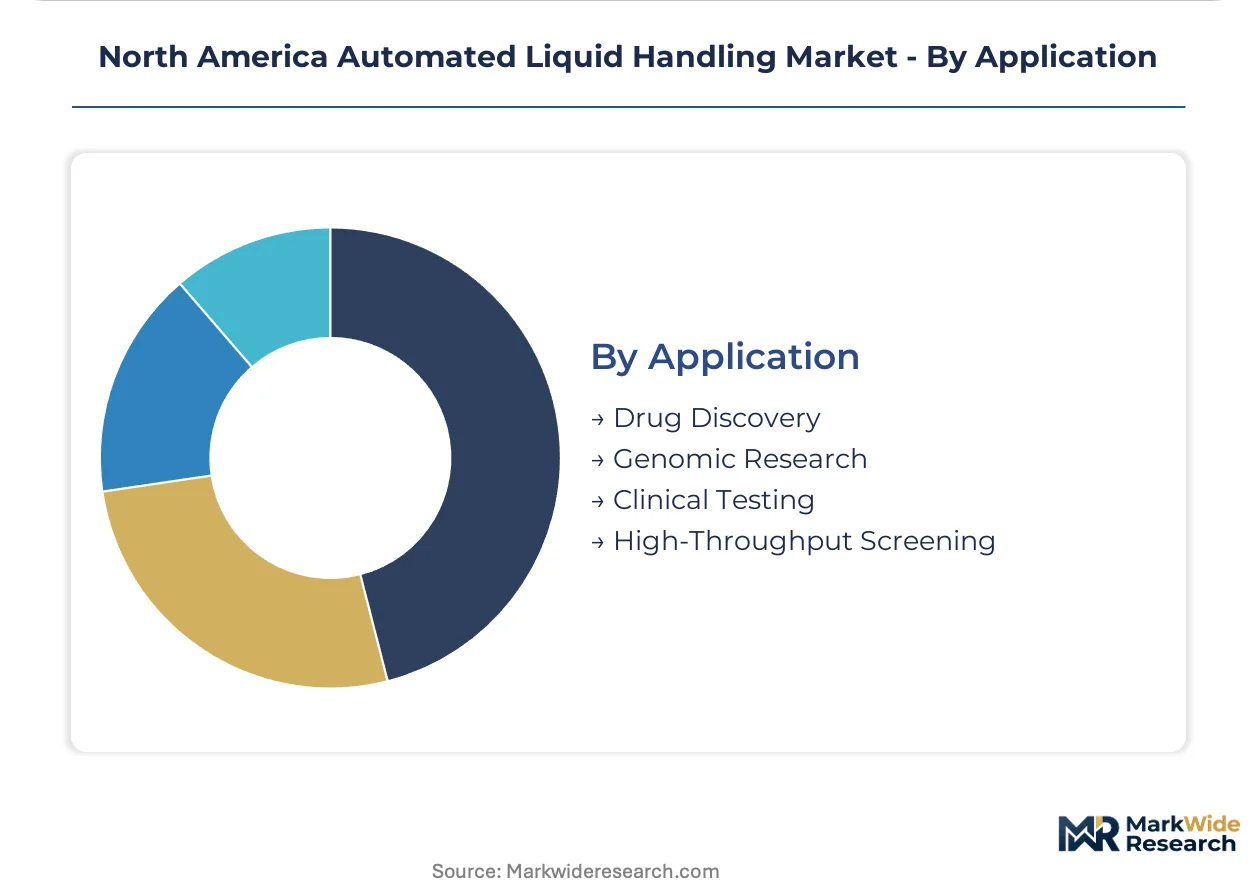
- High-Throughput Screening:Compound library management and assay miniaturization for pharmaceutical lead identification require integrated plate handling, environmental control, and data management systems. Reference laboratories process over ten thousand samples daily.
- Genomic Research:Next-generation sequencing library construction automation is expanding rapidly as clinical diagnostics laboratories match rising sample volumes with robotic nucleic acid preparation workflows.
- Drug Discovery:Target validation and lead optimization workflows spanning biochemical and cell-based assays.
- Clinical Testing:Patient sample aliquoting and diagnostic assay preparation with full audit trail documentation for regulatory compliance.
High-Throughput Screening dominates capital deployment, with Genomic Research showing the steepest expansion trajectory as sequencing costs continue falling and clinical adoption broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors North American demand for automated liquid handling systems, with Massachusetts laboratories driving workstation-class platform procurement for FDA-compliant drug discovery workflows.
United States
Pharmaceutical laboratories in New Jersey and North Carolina deploy robotic liquid handlers for high-throughput screening under FDA 21 CFR Part 11 mandates. The NIH reproducibility infrastructure funding program is modernizing academic core facilities across the Research Triangle Park. San Diego's biotechnology cluster is consolidating screening infrastructure onto unified automator platforms.
Canada
Environmental testing laboratories in Ontario and Quebec are upgrading equipment to meet EPA Good Automated Laboratory Practices alignment with Health Canada Medical Device Licensing requirements. The Great Lakes region commercial laboratories are delaying procurement until vendors demonstrate full GLP compliance module integration. Toronto's clinical diagnostics sector is expanding nucleic acid preparation automation.
Mexico
Contract manufacturing organizations in Baja California and Mexico City Metro are adopting workstation-class platforms for pharmaceutical quality control under COFEPRIS regulatory convergence with FDA validation protocols. The Bajío Region medical device manufacturing corridor is attracting automated liquid handling deployment for diagnostic device production. Monterrey-based CROs are negotiating fleet-management software bundles.
Northeast Corridor
Academic institutions from Boston through Washington D.C. are unbundling after-sales service contracts from capital purchases under NIH core facility modernization priorities. Harvard Medical School and MIT have pioneered multi-vendor maintenance pooling agreements. The Philadelphia pharmaceutical corridor is driving demand for GMP-compliant aseptic liquid handling systems.
Pacific Northwest
Cell therapy manufacturing facilities in Seattle and Portland are emerging as specialized demand centers for regenerative medicine production automation. Washington State's environmental testing laboratories are embedding cryptographic timestamping modules for EPA audit trail compliance. The region's biotechnology startups are prioritizing cloud-connected fleet management over hardware-only procurement.
North America Automated Liquid Handling Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software automation layers and service unbundling. The market structure concentrates around instrument manufacturers with captive precision component production and those with deep distribution channel control. Three archetypes dominate: vertically integrated precision pump fabricators, platform-agnostic software vendors, and multi-vendor service aggregators. Competitive moves center on backward integration into syringe pump manufacturing and forward integration into cloud-based protocol management systems.
Within the vertically integrated tier, Hamilton Company anchors its position through captive manufacturing of precision syringe pumps in Nevada. Danaher Corp. exemplifies distribution density control through its Pall Life Sciences channel network across the United States and Canada. Beckman Coulter occupies a position emphasizing liquid-level sensing integration with workstation portfolios. These three entities represent distinct strategic postures: captive supply chain security, channel reach maximization, and sensing technology differentiation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Hamilton Company |
| Agilent Technologies Inc. |
| Danaher Corp. |
| Beckman Coulter |
| Mettler-Toledo International Inc. |
| PerkinElmer Inc. |
| Sartorius AG |
| Bio-Rad Laboratories Inc. |
| Others |
Value Network & Pricing Analysis
Precision syringe pump manufacturing costs in Nevada and Asian component sourcing feed into a three-tier pricing structure across premium, standard, and economy levels, with FDA 21 CFR Part 11 compliance modules commanding tier premiums and academic buyers negotiating stripped-down hardware configurations.
Pricing Analysis
Input-cost pass-through from linear actuator and capacitive sensor sourcing runs through workstation-class platform pricing, with air-displacement mechanisms anchoring economy tiers and positive-displacement architectures with liquid-level sensing capturing premium positioning. Price differentiation hinges on FDA validation documentation depth and cloud-connected fleet management software bundling. Pricing pressure stems from academic core facilities unbundling after-sales service contracts and negotiating direct regional maintenance relationships. Contract Research Organizations exhibit lowest price sensitivity due to 24/7 uptime guarantee requirements, while mid-sized environmental testing laboratories face capital intensity barriers.
Supply Chain Analysis
Domestic-content mandates under Health Canada Medical Device Licensing and FDA 21 CFR Part 820 are reshaping sourcing patterns, pushing instrument assemblers toward dual-source qualification for critical fluid path components. Manufacturing clusters in China, Japan, and South Korea supply syringe pumps and precision dispensing tips, while Nevada captive production anchors North American supply security. Raw material dependencies center on medical-grade polymers, piezoelectric ceramics, and linear motion bearings. Single-source vulnerability concentrates in specialized positive-displacement tip chemistries facing EPA per- and polyfluoroalkyl substance restrictions. Distribution runs through Pall Life Sciences channel networks and direct academic core facility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automated liquid handling rests on software automation layers displacing hardware-only procurement, with cloud-connected fleet management and predictive maintenance modules capturing recurring revenue premiums.
For Market Incumbents: Deploy backward integration into precision syringe pump manufacturing to secure supply continuity against Asian lead-time volatility. Consolidate position by embedding cryptographic timestamping and EPA Good Automated Laboratory Practices compliance modules as standard features, neutralizing emerging software-only entrants. Channel control through multi-vendor maintenance pooling agreements defends against academic core facility service unbundling.
For New Entrants and Emerging Players: Capture white-space in cell therapy manufacturing automation for GMP-compliant aseptic liquid handling systems, where regenerative medicine production facilities lack specialized vendors. Target mid-sized environmental testing laboratories in the Great Lakes region with GLP compliance module leasing models, bypassing capital intensity barriers. Go-to-market through regional field service organization partnerships accelerates credibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where precision component supply concentration meets expanding software automation margin pools. Long-term viability favors platform-agnostic software vendors with protocol standardization capabilities and vertically integrated instrument manufacturers with captive Nevada production. Watch for EPA per- and polyfluoroalkyl substance restriction enforcement as inflection signal for disposable tip chemistry replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Fleet Management Launch | Laboratories prioritize protocol standardization over hardware-only procurement. |
| Precision Syringe Pump Backward Integration | Hamilton Company's Nevada captive manufacturing anchors supply security. |
| EPA GLP Compliance Module Integration | Great Lakes environmental laboratories delay procurement pending validation. |
| Multi-Vendor Maintenance Pooling Agreements | Harvard Medical School and MIT pioneered cross-trained technician networks. |
| Cell Therapy Manufacturing Automation Development | GMP-compliant aseptic systems address regenerative medicine production demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical laboratory directors, academic core facility managers, CRO procurement leads, and biomedical equipment distributors with secondary validation against FDA 21 CFR Part 11 guidance documents, EPA Good Automated Laboratory Practices protocols, NIH funding allocation databases, and Health Canada Medical Device Licensing records. Bottom-up shipment tracking and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework, with workstation-class platforms, CRO demand clusters, software automation layers, and genomic research applications receiving distinct growth coefficients. CAGRs derived from replacement cycle analysis, compliance mandate timelines, and federal funding trajectory modeling. Forecast inputs incorporated NIH reproducibility infrastructure allocation patterns and EPA regulatory enforcement probability.
Regulatory enforcement delays, precision component supply disruptions, and academic budget freeze triggers are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Medical Robots Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Europe Educational Robot Market