
 Network Analysis Module (NAM) Market | 2026-2036
Network Analysis Module (NAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Network Analysis Module (NAM) Market Foresight
Aftermarket service revenue from legacy probe hardware is narrowing as subscription-based cloud analytics displace perpetual-license models. Cisco Systems leverages its installed base of routing infrastructure to bundle NAM capabilities at the network edge. SolarWinds anchors its position through channel density among mid-market IT administrators seeking unified visibility tools.
A Network Analysis Module constitutes an integrated hardware-software system capturing packet-level traffic data at throughput rates exceeding 100 Gbps, applying deep-packet inspection and flow analysis to diagnose latency, congestion, and security anomalies across enterprise and carrier networks. Cloud-based deployment now captures the fastest expansion as elastic compute resources eliminate capital-intensive probe farms, while on-premises solutions retain dominance among financial services and defense sectors with strict data-sovereignty requirements. Analytics software solutions command the deepest margin pools where machine-learning inference engines differentiate vendor offerings.
FCC net-neutrality rulings and NIST cybersecurity frameworks shape product certification requirements for NAM vendors serving US critical infrastructure operators. The EU AI Act imposes conformity-assessment obligations on automated anomaly-detection modules, effectively raising compliance barriers for non-European suppliers. Stakeholders must monitor evolving encryption standards as TLS 1.3 and post-quantum cryptography protocols progressively blind conventional deep-packet inspection architectures.
Market Dynamics
Telecom infrastructure operators are consolidating traffic visibility tools into unified telemetry fabrics, collapsing separate probe hardware and software analytics into single subscription platforms that eliminate capital-intensive refresh cycles.
Growth Catalysts
- EU AI Act compliance mandates:Automated anomaly-detection modules deployed across carrier networks in Germany, France, and Italy now require conformity assessments, creating certified-vendor preference windows for European suppliers.
- Industrial IoT density in Germany:Manufacturing clusters around Stuttgart and Munich are procuring edge-computing NAM appliances to monitor deterministic latency in time-sensitive networking environments.
- 5G standalone core deployments:Service-based architecture disaggregates control and user planes, necessitating distributed packet brokers that inspect traffic at multiple network function virtualization nodes.
Market Restraints
- TLS 1.3 encryption proliferation:Perfect forward secrecy protocols prevent session-key extraction, blinding conventional deep-packet inspection engines that rely on passive decryption for payload analysis.
- Silicon supply concentration:Advanced programmable logic devices and high-speed memory modules for 100 Gbps+ capture cards depend on fabrication capacity concentrated in Taiwan and South Korea.
- Defense-sector data-sovereignty requirements:NATO member procurement rules and national security classifications prevent cloud-native NAM adoption across military and intelligence network segments.
Strategic Opportunities
- Post-quantum cryptography transition:NIST standardization of quantum-resistant algorithms creates replacement demand for inspection architectures compatible with hybrid key encapsulation mechanisms.
- India's smart city fiberization:Municipal broadband authorities in Bangalore, Hyderabad, and Pune are tendering for traffic analytics as part of integrated command-and-control center deployments.
- Unified observability convergence:Correlating packet-level telemetry with application performance metrics and infrastructure logs opens cross-sell paths into DevOps tooling budgets.
Industry Challenges
- Embedded systems firmware expertise:Designing line-rate packet processing pipelines requires rare combinations of FPGA programming, kernel-bypass networking, and hardware timing precision.
- Multi-vendor interoperability certification:Integrating NAM probes with existing network management platforms from Cisco, Juniper, and Arista demands extensive protocol testing and vendor-specific adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Analysis Module (NAM) Market |
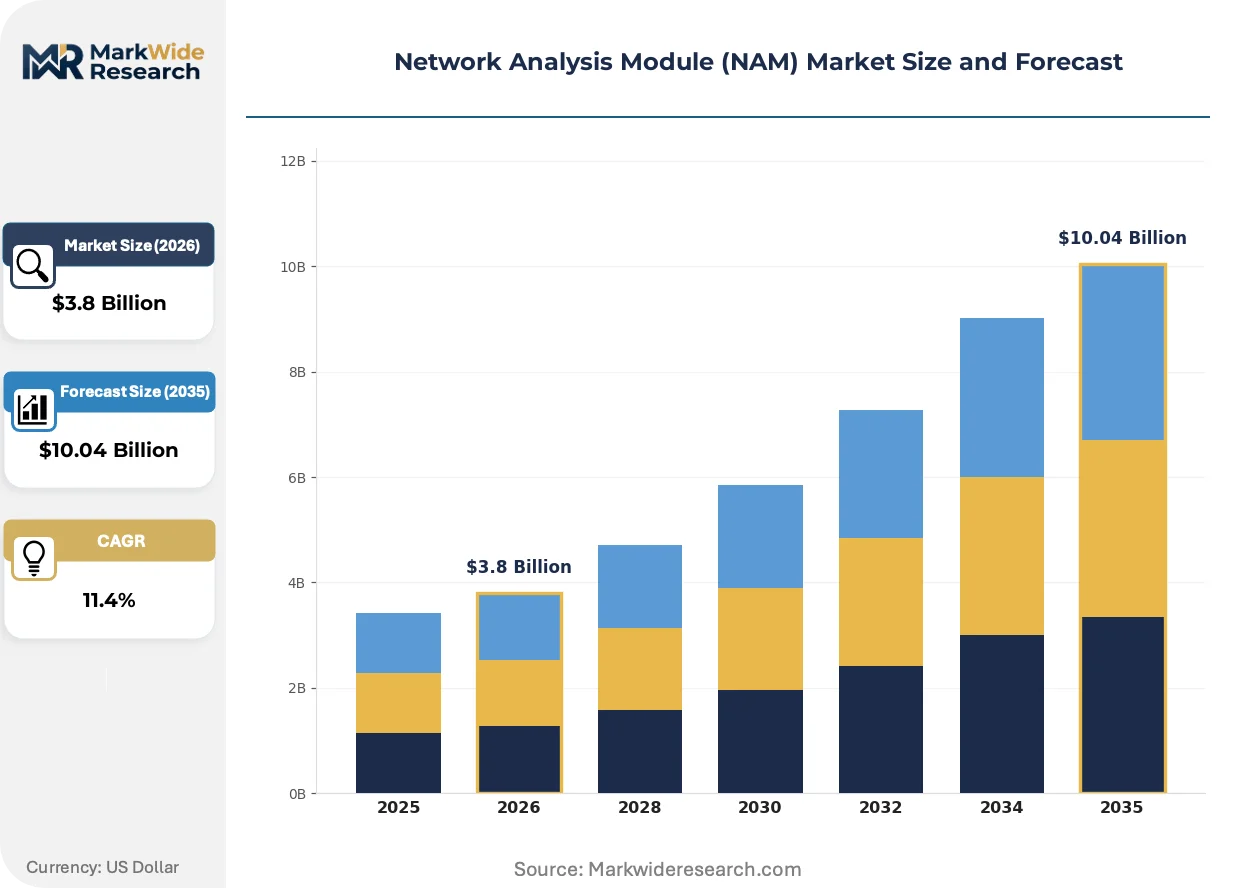
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Method: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecom Providers, Enterprises, Government Agencies, Educational Institutions Solution Type: Analytics Software, Monitoring Tools, Optimization Solutions, Automation Platforms Technology: Artificial Intelligence, Machine Learning, Big Data, Predictive Analytics |
| Companies Covered | Cisco Systems, SolarWinds, IBM Corporation, Microsoft, Riverbed Technology, NetScout Systems, Nagios Enterprises, LogicMonitor, ManageEngine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Analysis Module (NAM) Market Shifts & Advancements
Packet processing intelligence is migrating from dedicated appliances into software-defined layers, enabling elastic scaling that tracks traffic volatility without stranded capital.
SmartNICs and data processing units are virtualizing packet capture and analysis functions that previously required purpose-built hardware probes. Hyperscale cloud providers and large financial exchanges are deploying these programmable accelerators at server edge ports. This shift is compressing the addressable market for standalone NAM appliances while expanding subscription-based software licensing pools.
The EU AI Act imposes documented risk-management systems and human oversight requirements on automated network anomaly detection. Vendors must maintain technical documentation and quality management systems for conformity assessment. German and French carrier procurement teams are now requiring AI Act compliance certifications in RFP evaluation criteria.
Enterprise buyers are unbundling perpetual hardware-software bundles in favor of metered consumption models tied to actual traffic volumes. Managed security service providers are capturing this demand by offering NAM-as-a-service with embedded analyst support. This pattern is most pronounced among mid-market healthcare and retail organizations in the United States seeking to convert fixed network monitoring costs to variable operational expenditures.
Network Analysis Module (NAM) Market Segmentation
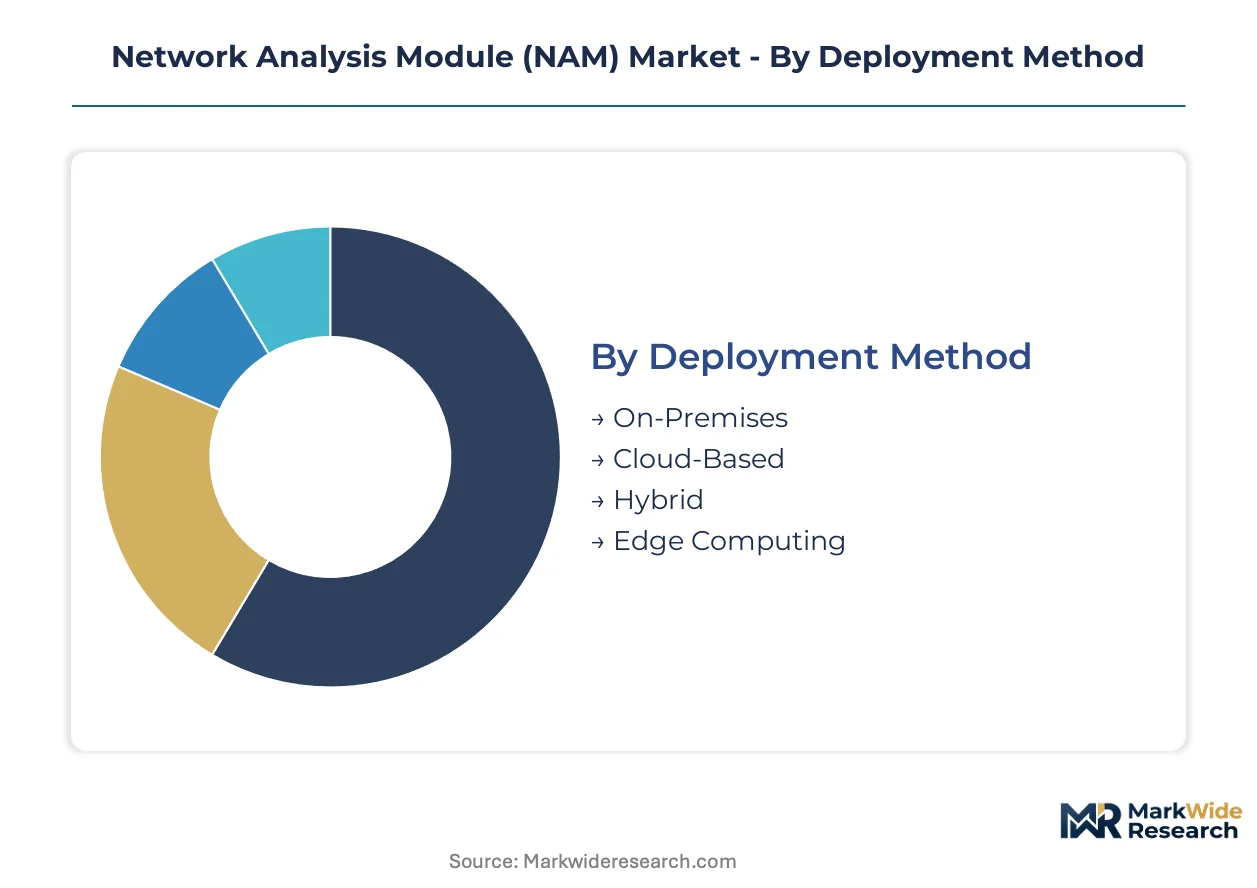
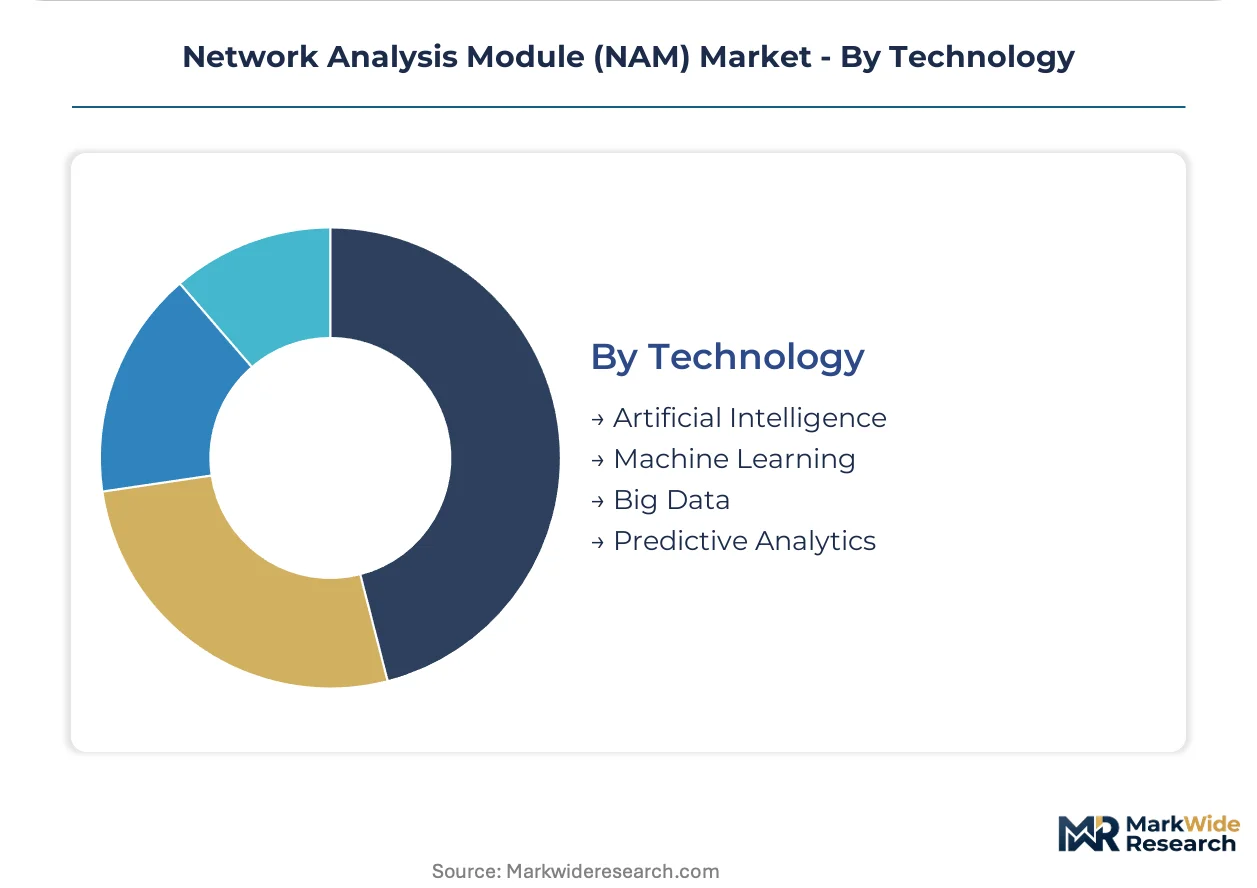
Deployment architecture, end-user requirements, and technology sophistication create distinct margin profiles across the NAM market. Vendors must align service intensity and pricing models to each segment's operational constraints and procurement patterns.
Deployment Method:
After-sales-service intensity varies sharply across deployment modes, with cloud-based solutions demanding continuous platform engineering while edge appliances require field maintenance networks.
- On-Premises:Hardware-software bundles installed within customer data centers deliver sub-100-microsecond packet capture latency for high-frequency trading floors in Frankfurt and Chicago. Financial services and defense sectors in Germany and the United States retain this model to satisfy data-sovereignty mandates from BaFin and NIST frameworks.
- Cloud-Based:Elastic compute pools eliminate stranded probe capacity during traffic spikes. Managed service providers in Bangalore and Dublin are capturing mid-market healthcare and retail organizations seeking to convert fixed monitoring costs to metered operational expenditures.
- Hybrid:Split architectures place sensitive traffic analysis on-premises while offloading historical storage to public cloud tiers.
- Edge Computing:Distributed appliances monitor deterministic latency in Stuttgart manufacturing clusters deploying time-sensitive networking.
By volume, On-Premises leads. By growth pace, Cloud-Based is ahead.
End User:
Cost tier differentiation separates capital-intensive carrier procurements from budget-constrained institutional deployments.
- Telecom Providers:Tier-1 operators in Germany, France, and Italy consolidate probe farms into unified telemetry fabrics. EU AI Act conformity assessments now filter vendor selection for automated anomaly-detection modules.
- Enterprises:Mid-market IT administrators prioritize unified visibility tools that correlate packet telemetry with application performance metrics.
- Government Agencies:NATO procurement rules and national security classifications prevent cloud-native adoption across military network segments.
- Educational Institutions:Campus networks in Pune and Hyderabad integrate traffic analytics into smart city command centers.
Telecom Providers command the deepest contract values. Enterprises are expanding most quickly as subscription models penetrate mid-market budgets.
Solution Type:
Margin pools concentrate where machine-learning inference engines differentiate vendor offerings from commodity monitoring.
- Analytics Software:Inference engines running on elastic cloud resources command recurring subscription premiums. German and French carrier procurement teams now require AI Act compliance certifications in RFP evaluation criteria.
- Monitoring Tools:Real-time dashboards and alerting systems form the baseline capability layer.
- Optimization Solutions:Congestion prediction and traffic engineering automation reduce operational expenditures for 5G standalone core operators.
- Automation Platforms:Self-healing network responses integrate with orchestration layers at multiple network function virtualization nodes.
Analytics Software captures the highest recurring margins. Automation Platforms are gaining share fastest as operator headcount constraints deepen.
Technology:
Supply concentration in programmable silicon shapes which technology layers vendors can differentiate.
- Artificial Intelligence:Automated anomaly detection requires documented risk-management systems and human oversight under EU AI Act mandates. Conformity assessment obligations raise compliance barriers for non-European suppliers.
- Machine Learning:Behavioral baselines adapt to encrypted traffic patterns as TLS 1.3 proliferation blinds conventional deep-packet inspection.
- Big Data:Historical traffic repositories enable forensic investigation and capacity planning.
- Predictive Analytics:Forecasting models anticipate congestion before service degradation impacts Stuttgart automotive production lines.
Artificial Intelligence anchors current RFP requirements. Machine Learning shows the steepest expansion trajectory as encryption adaptation becomes critical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial IoT deployments favor deterministic edge-computing appliances, while US financial services retain on-premises sovereignty models. Cloud-based elasticity dominates procurement patterns in Bangalore and Dublin mid-market segments. Regulatory fragmentation across the EU AI Act, FCC rulings, and India's smart city mandates creates distinct compliance-driven purchasing criteria.
Germany
Manufacturing clusters around Stuttgart and Munich drive edge-computing NAM procurement for time-sensitive networking environments. The EU AI Act imposes conformity-assessment obligations on automated anomaly-detection modules deployed across carrier networks. BaFin data-sovereignty mandates preserve on-premises dominance among Frankfurt high-frequency trading floors.
United States
Mid-market healthcare and retail organizations convert fixed monitoring costs to metered operational expenditures through managed security service providers. FCC net-neutrality rulings and NIST cybersecurity frameworks shape product certification requirements for critical infrastructure operators. Chicago financial exchanges maintain sub-100-microsecond latency requirements through hardware-software bundles.
India
Municipal broadband authorities in Bangalore, Hyderabad, and Pune tender for traffic analytics as part of integrated command-and-control center deployments. TRAI regulations govern telecommunications infrastructure procurement across smart city fiberization programs. Campus networks in educational institutions integrate NAM capabilities into urban surveillance and traffic management systems.
France
Tier-1 telecom operators consolidate probe farms into unified telemetry fabrics requiring AI Act compliance certifications in RFP evaluation criteria. ANSM and CNIL oversight extends to algorithmic transparency in automated network management systems. Paris-based carrier procurement teams filter vendor selection through documented risk-management system requirements.
United Kingdom
Enterprise buyers unbundle perpetual hardware-software bundles in favor of consumption models tied to actual traffic volumes. Post-Brexit regulatory divergence creates parallel certification tracks for EU AI Act and domestic cybersecurity standards. London financial services firms evaluate hybrid architectures splitting sensitive traffic analysis on-premises from historical cloud storage.
Network Analysis Module (NAM) Market Competitive Landscape
Capability concentration sits with specialized probe fabricators possessing FPGA programming and kernel-bypass networking expertise; scale advantage sits with infrastructure incumbents leveraging installed base relationships. The vendor landscape organizes around three archetypes: routing equipment bundlers, unified visibility platform specialists, and cloud-native analytics providers. Consolidation pressure intensifies as subscription models displace perpetual-license revenue streams. Dominant competitive moves include strategic bundling at network edges and channel density expansion among mid-market IT administrators.
Within the infrastructure bundler tier, Cisco Systems exemplifies scale-driven positioning through edge-integrated capabilities, while SolarWinds occupies the unified visibility specialist position through channel relationships with mid-market administrators. Riverbed Technology represents the application-performance correlation archetype, anchoring a segment where packet-level telemetry converges with infrastructure logs. These three companies illustrate how vendor positioning fragments across deployment architecture preferences rather than consolidating around homogeneous technology stacks.
| Leading Market Players |
|---|
| Cisco Systems |
| SolarWinds |
| IBM Corporation |
| Microsoft |
| Riverbed Technology |
| NetScout Systems |
| Nagios Enterprises |
| LogicMonitor |
| ManageEngine |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for advanced programmable logic devices creates simultaneous pricing tier compression at the hardware layer and supply vulnerability for 100 Gbps+ capture card vendors. This single-source dependency forces tier-1 NAM appliance manufacturers to absorb silicon cost volatility while subscription-based software providers escape component exposure entirely.
Pricing Analysis
Long-term offtake agreements dominate carrier procurement in Germany and France, where EU AI Act compliance certifications now filter vendor selection. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled analytics engines from basic monitoring dashboards and unbundled probe hardware. Cost compression in the appliance tier intensifies because SmartNIC virtualization collapses standalone probe demand. Mid-market healthcare organizations in the United States exhibit highest price sensitivity, converting fixed perpetual licenses to metered SaaS expenditures through managed security service providers.
Supply Chain Analysis
Contract manufacturing for high-speed memory modules and FPGA programming concentrates among Taiwanese and South Korean foundries with limited second-source alternatives. Raw material dependencies span gallium nitride substrates, high-bandwidth memory stacks, and specialized optical transceivers. Single-source vulnerability in programmable silicon creates procurement risk for vendors serving defense-sector data-sovereignty requirements. Distribution runs through direct enterprise sales teams for on-premises deployments and hyperscaler marketplaces for cloud-native analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SmartNIC-based traffic virtualization threatens standalone probe incumbents with functional substitution, forcing defensive repositioning around software-defined layers and compliance-certified analytics engines.
For Market Incumbents: Harden installed-base relationships by bundling NAM capabilities at Cisco routing infrastructure edge ports, neutralizing cloud-native entrants through channel density expansion. Prioritize EU AI Act conformity assessment investment to capture certified-vendor preference windows in German and French carrier RFPs. Vertical integration into FPGA programming expertise defends against SmartNIC commoditization.
For New Entrants and Emerging Players: India's smart city fiberization in Bangalore, Hyderabad, and Pune offers white-space penetration with lower incumbent saturation than European telecom markets. Municipal broadband authorities tendering for integrated command-and-control centers represent the most penetrable buyer archetype. Lead with NAM-as-a-service consumption models that convert fixed monitoring costs to operational expenditures for mid-market healthcare and retail segments.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized probe fabricators possessing kernel-bypass networking and hardware timing precision capabilities. Long-term viability hinges on machine-learning inference engine differentiation as TLS 1.3 encryption proliferation blinds conventional deep-packet inspection. Watch for post-quantum cryptography standardization as inflection signal triggering replacement demand for inspection architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Conformity assessments create preference windows for European suppliers in German carrier networks. |
| SmartNIC Virtualization Partnership | Programmable accelerators at server edge ports compress standalone appliance addressable markets. |
| Edge Computing Appliance Deployment | Stuttgart manufacturing clusters procure deterministic latency monitoring for time-sensitive networking. |
| Post-Quantum Cryptography Transition | NIST standardization creates replacement demand for hybrid key encapsulation inspection architectures. |
| Managed Security Service Bundling | Mid-market US healthcare organizations convert fixed costs to metered operational expenditures. |
Research Methodology
Operator-level perspectives from carrier network architects, enterprise IT administrators, managed security service provider engineers, and defense-sector procurement officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC filings, hyperscaler capex disclosures, EU regulatory conformity assessment databases, and TRAI smart city tender documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across deployment architectures and end-user categories.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling deployment method, end-user vertical, solution type, and technology sophistication as core segmentation dimensions. CAGRs derived from elasticity-adjusted adoption curves incorporating 5G standalone core rollout pace, EU AI Act implementation timelines, and TLS 1.3 encryption penetration rates. Industry-specific forecast inputs included SmartNIC deployment trajectories at hyperscale cloud providers and industrial IoT density projections for German manufacturing clusters.
Practitioners should monitor NIST post-quantum cryptography standardization progress, Taiwanese foundry capacity utilization, and EU AI Act enforcement patterns for early signals requiring forecast revision. Quarterly review of carrier RFP evaluation criteria, SmartNIC virtualization adoption rates, and defense-sector cloud-native exemption waivers is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
US Video Analytics Market
Analytics
Statistical Analytics Market
Analytics
Content Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Global System Monitoring Market
Analytics
Application Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
Europe Emotion Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Global Social Intelligence Market
Analytics
Global Telco Data Monetization Market
Analytics
Europe Network and Location Analytics Market
Analytics
Condition Monitoring Service Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
TV Analytics Solutions Market
Analytics
APAC Retail Analytics Market