
 AI Assisted Robots Market | 2026-2036
AI Assisted Robots Market Size, Share, and Industry Trends Forecast 2026-2036
AI Assisted Robots Market Outlook
China is rewriting competitive dynamics through massive domestic robot production expansion. FANUC Corporation anchors Japanese precision manufacturing heritage while extending its servo-motor dominance into AI-driven motion control. NVIDIA Corporation leverages GPU-accelerated edge computing to differentiate its robotics platform from conventional programmable logic controller architectures.
AI assisted robots integrate machine perception, adaptive control algorithms, and actuation systems to perform tasks with minimal human intervention in unstructured environments. These systems typically operate with sub-millimeter positioning accuracy and cycle times under 100 milliseconds for pick-and-place operations. Industrial robots command the largest installed base, while collaborative robots capture the fastest expansion as small and medium enterprises seek fenceless automation. Computer vision represents the most technically mature technology layer, whereas natural language processing remains the least deployed but highest-potential interface for human-robot interaction.
The EU Machinery Directive and CE marking requirements shape product safety standards for robot deployment across European manufacturing facilities. OSHA guidelines in the United States govern collaborative robot workplace integration, while China's GB standards mandate functional safety certifications for industrial automation equipment. Stakeholders must monitor how divergent national AI governance frameworks reshape cross-border robot deployment protocols and data residency obligations.
Market Dynamics
Precision motion control hardware and GPU-accelerated edge computing are compressing robot response latencies below 100 milliseconds, eliminating the performance gap between AI-assisted systems and traditional programmable logic controllers in unstructured environments.
Growth Catalysts
- EU Machinery Directive safety protocols:Harmonized CE marking requirements for collaborative robots reduce compliance fragmentation across German, Italian, and French automotive assembly plants.
- Small and medium enterprise fenceless automation:Cobot deployments bypass traditional safety fencing, cutting integration costs and floor space requirements for tier-two and tier-three manufacturers.
- China's GB standards functional safety mandates:Domestic certification requirements accelerate replacement of legacy industrial equipment with AI-enabled alternatives in smart factory upgrades.
Market Restraints
- High-purity semiconductor supply concentration:Advanced servo motors and edge AI processors depend on Taiwanese and South Korean foundry capacity, creating single-point vulnerability.
- Natural language processing technical immaturity:Speech-to-intent accuracy in noisy industrial environments remains below deployment thresholds for safety-critical human-robot interaction.
- OSHA collaborative robot workplace guidelines:Evolving U.S. enforcement interpretations create compliance uncertainty during risk assessment and safeguarding verification.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive sectors subsidize first-mover robot deployments in previously manual assembly lines.
- Computer vision and force-torque sensor convergence:Multi-modal perception stacks enable bin-picking of deformable objects without pre-programmed grasp points.
- Robot-as-a-service distribution channels:Usage-based pricing models bypass capital expenditure barriers for contract manufacturers and seasonal production facilities.
Industry Challenges
- Mechatronics systems integration talent scarcity:Shortage of engineers capable of bridging mechanical design, control theory, and machine learning deployment.
- ISO 10218 and ISO/TS 15066 certification timelines:Multi-month validation cycles delay product launches and lock working capital in pre-revenue inventory.
- Legacy programmable logic controller interoperability:Proprietary fieldbus protocols and vendor-locked software stacks resist seamless AI module integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Assisted Robots Market |
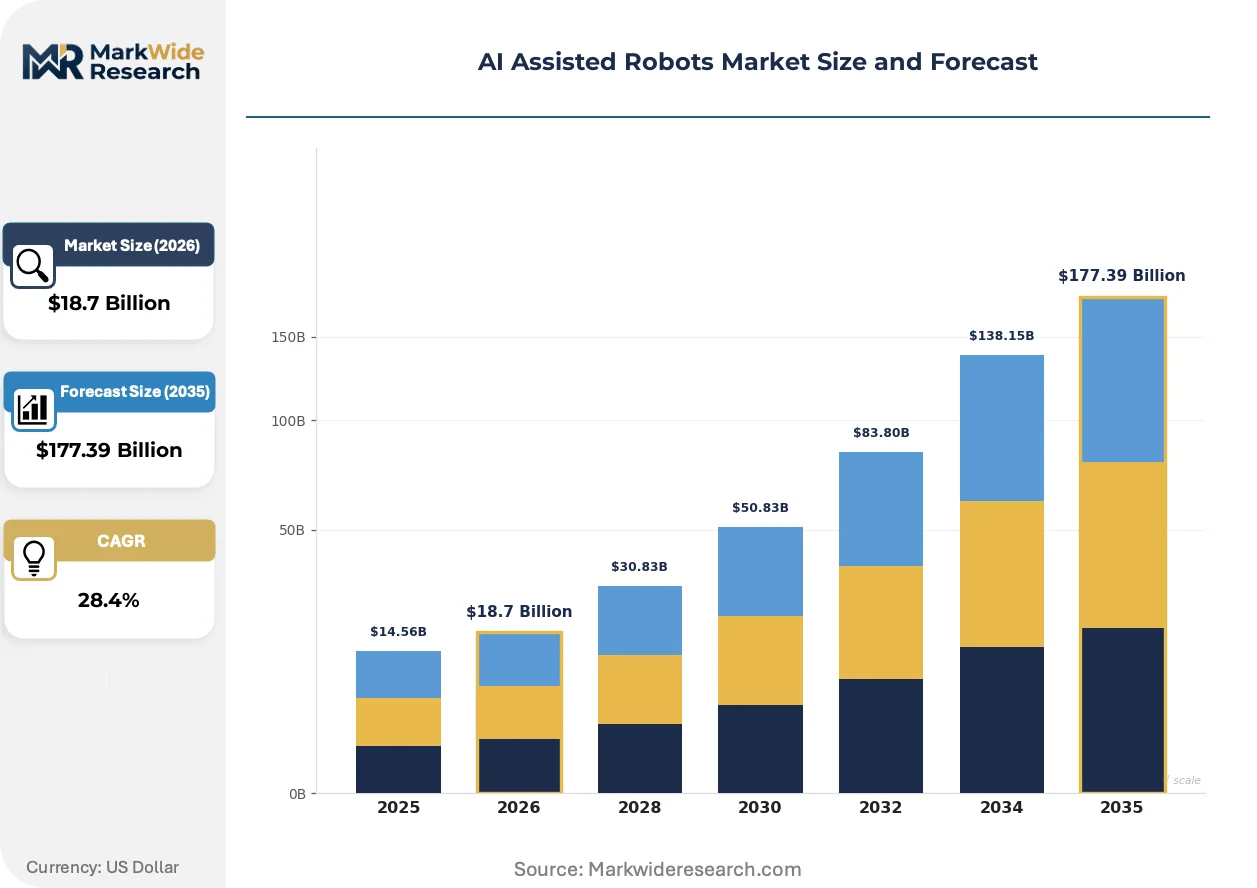
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Humanoid Robots, Collaborative Robots Application: Manufacturing, Healthcare, Logistics, Agriculture End User: Enterprises, Hospitals, Retailers, Educational Institutions Technology: Machine Learning, Computer Vision, Natural Language Processing, Sensor Fusion |
| Companies Covered | ABB, Boston Dynamics, NVIDIA Corporation, Intel Corporation, FANUC Corporation, YASKAWA ELECTRIC CORPORATION, NIDEC CORPORATION, Panasonic Corporation, Hanson Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Assisted Robots Market Strategic Shifts
GPU-native robotics software stacks are rewriting the economics of real-time motion planning, compressing algorithm development cycles and enabling deployment of capabilities previously restricted to research environments.
Transformer-based neural architectures for robot manipulation are rendering obsolete rule-based pick-and-place programming that required manual teach-pendant trajectory definition. Tier-one automotive suppliers in Stuttgart and Wolfsburg are deploying these systems for mixed-model assembly lines. The shift collapses reprogramming time from days to minutes, eliminating the changeover cost barrier that previously favored dedicated automation over flexible systems.
The EU AI Act risk classification framework imposes conformity assessment obligations on high-risk robotics applications including collaborative manufacturing and autonomous mobile platforms. Industrial integrators in Bavaria and Baden-Württemberg are restructuring quality management systems to document algorithmic transparency and human oversight protocols. Medical and logistics robot categories face the steepest compliance ramps, with notified body bottlenecks extending market access timelines.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into separately priced software updates, spare part subscriptions, and remote diagnostic tiers. German and Japanese robot OEMs are piloting predictive maintenance modules sold as annual licenses rather than included warranty features. Automotive end-users in Michigan and South Carolina are negotiating à-la-carte service menus, pressuring integrator margins while accelerating in-house technician upskilling investments.
AI Assisted Robots Market Segmentation
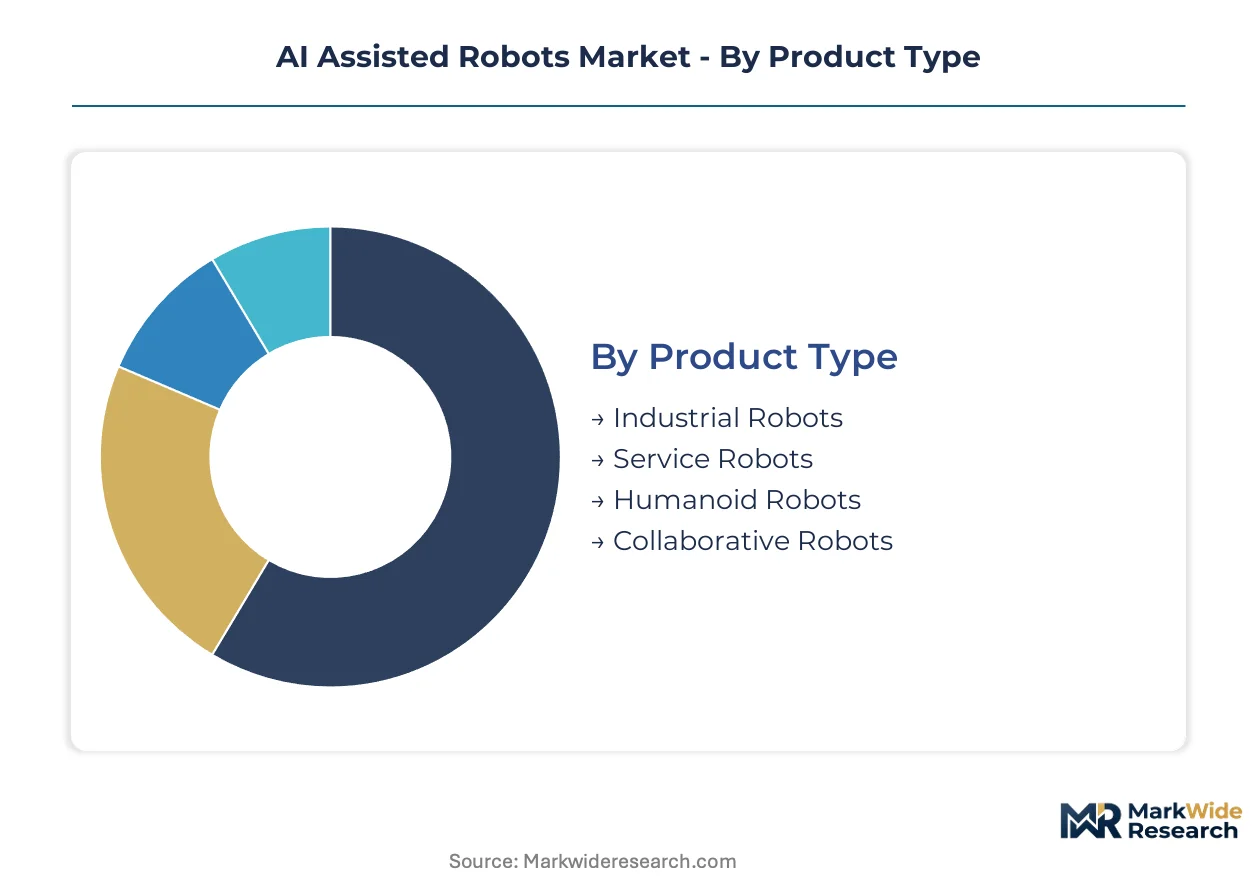
Segmentation in AI assisted robots reveals how hardware specifications, software stacks, and deployment contexts fragment purchasing decisions. Technical requirements diverge sharply between precision manufacturing and unstructured service environments, forcing vendors to specialize rather than generalize.
Product Type:
Cost tier stratification separates capital-intensive fixed installations from flexible, lower-barrier systems accessible to smaller operators.
- Industrial Robots:Heavy-payload articulated arms with six or more degrees of freedom dominate automotive body-in-white welding and powertrain assembly. German OEMs in Stuttgart and Wolfsburg specify these systems for sub-millimeter repeatability under continuous three-shift operation. Capital recovery cycles extend across seven to ten years, locking in long-term supplier relationships and proprietary maintenance ecosystems.
- Collaborative Robots:Force-limited articulated arms with power and force restricting safety features enable fenceless human-robot workcells. Tier-two electronics contract manufacturers in Shenzhen and Dongguan deploy these for mixed-model final assembly where batch sizes fall below 1,000 units. Force-torque sensors and collaborative safety certifications add 15-25% hardware premium over equivalent-payload industrial configurations.
- Service Robots:Mobile platforms with autonomous navigation stacks perform cleaning, security patrol, and inventory inspection in commercial facilities.
- Humanoid Robots:Bipedal platforms with dual-arm manipulation capability target research laboratories and pilot logistics operations requiring human-scaled workspace compatibility.
Industrial robots command the established base. The steepest expansion runs through collaborative robots.
Application:
Volume concentration tracks manufacturing intensity, with healthcare and logistics capturing disproportionate investment relative to operational robot counts.
- Manufacturing:Welding, material handling, assembly, and quality inspection absorb the majority of installed industrial robot capacity. Automotive final assembly plants in Michigan and South Carolina represent the densest concentration, with average facility deployments exceeding 1,000 units. Semiconductor packaging and electronics surface-mount operations in Taiwan and South Korea drive demand for high-speed SCARA and delta configurations.
- Logistics:Autonomous mobile robots and robotic picking systems address e-commerce fulfillment center throughput constraints. Amazon and Alibaba distribution networks in Nevada and Zhejiang operate fleets exceeding 100,000 mobile units combined. Last-mile delivery robots remain experimental, constrained by sidewalk navigation regulatory fragmentation across municipal jurisdictions.
- Healthcare:Surgical robots and rehabilitation systems require FDA, NMPA, or CE marking clinical validation cycles spanning 18-36 months.
- Agriculture:Harvesting robots and autonomous tractors target specialty crop operations in California and the Netherlands where labor availability constrains seasonal production.
Manufacturing retains the dominant share. Logistics is gaining share fastest.
End User:
Customer type determines procurement sophistication, with enterprises demanding integrated solutions and smaller entities prioritizing plug-and-play deployment speed.
- Enterprises:Multinational manufacturers and logistics operators specify custom-integrated robot workcells with manufacturing execution system connectivity. Automotive OEMs maintain dedicated automation engineering teams of 50-200 personnel. Capital expenditure approval thresholds above $5 million trigger multi-vendor competitive bidding and total cost of ownership modeling across 10-year horizons.
- Hospitals:Healthcare systems procure surgical and disinfection robots through group purchasing organizations with stringent clinical outcome requirements. Academic medical centers in Boston and Heidelberg pilot experimental systems for procedure-specific FDA or CE marking pathway development.
- Retailers:Grocery and general merchandise chains deploy inventory scanning and floor-cleaning robots to reduce overnight labor costs.
- Educational Institutions:Universities and technical colleges acquire research platforms and training cells for workforce development programs.
Enterprises dominate procurement volume. Hospitals show the most rapid budget allocation acceleration.
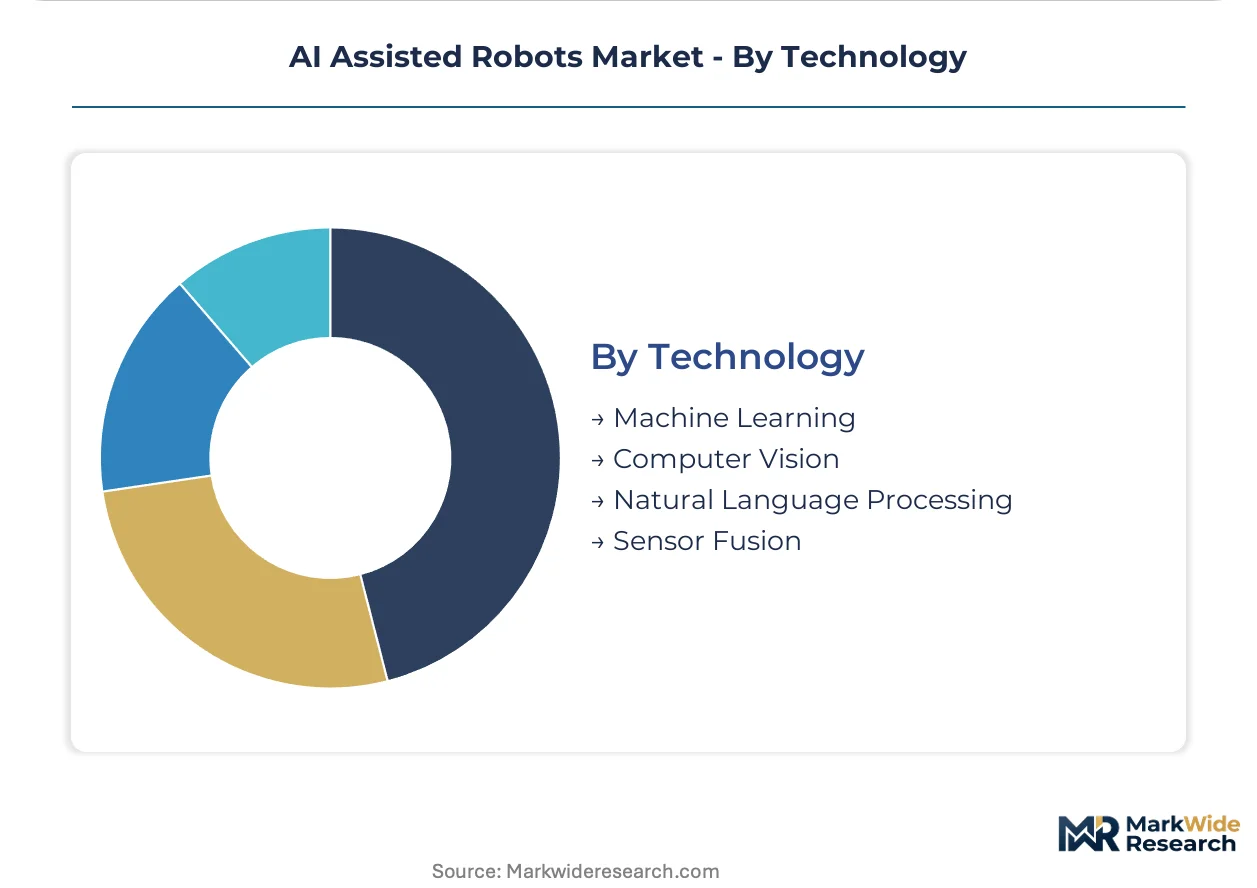
Technology:
Maturity gradients separate commercially deployed perception stacks from emerging interaction modalities still constrained by reliability thresholds.
- Computer Vision:2D and 3D camera systems with convolutional neural network object detection achieve 99.5%+ accuracy in structured lighting bin-picking applications. Intel RealSense and Basler camera modules integrate with ROS-Industrial middleware across FANUC, KUKA, and ABB controller architectures. Edge GPU acceleration enables sub-50-millisecond inference latencies for real-time grasp point generation.
- Machine Learning:Reinforcement learning and imitation learning algorithms reduce robot programming time for complex manipulation tasks. Google DeepMind and Berkeley AI Research demonstrations in cloth folding and deformable object handling remain laboratory-stage, with sim-to-real transfer reliability below commercial deployment thresholds.
- Natural Language Processing:Speech-to-intent systems for industrial human-robot interaction struggle with 85-90% accuracy in noisy factory environments.
- Sensor Fusion:LiDAR, IMU, and camera convergence enables robust SLAM for mobile robot navigation in dynamic warehouse environments.
Computer Vision anchors current deployments. Machine Learning is climbing the fastest toward production viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced servo motors and edge AI processors concentrate manufacturing capacity in Taiwan and South Korea, creating geographic chokepoints that shape deployment patterns across major consuming markets. Robot density and regulatory maturity diverge sharply between established manufacturing hubs and emerging automation frontiers.
China
Domestic manufacturers in Shenzhen and Dongguan pursue smart factory upgrades under GB standards functional safety mandates. MIIT industrial policy channels subsidies toward indigenous robot controller development. The Yangtze River Delta and Pearl River Delta absorb the heaviest concentration of industrial robot installations globally.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg accelerate cobot deployment under EU Machinery Directive safety protocols. CE marking requirements harmonize compliance across Bavarian and Baden-Württemberg manufacturing clusters. KBA and regional economic ministries coordinate workforce retraining for fenceless automation integration.
United States
Automotive end-users in Michigan and South Carolina negotiate à-la-carte robot service menus while accelerating in-house technician investments. OSHA collaborative robot workplace guidelines create compliance uncertainty during risk assessment verification. The Southeast and Midwest host the densest robot deployment outside automotive final assembly.
Japan
Precision manufacturing heritage anchors servo-motor dominance extending into AI-driven motion control. METI technology roadmaps prioritize human-robot collaboration standards development. The Chubu region around Nagoya maintains concentrated automotive and electronics robot demand.
India
Electronics and automotive sectors absorb PLI scheme subsidies for first-mover robot deployments in previously manual assembly lines. Maharashtra and Gujarat host contract manufacturers piloting fenceless cobot workcells for sub-1,000 unit batch production. BIS certification timelines extend market access for imported automation equipment.
AI Assisted Robots Market Competitive Environment
Industrial incumbents and AI-native entrants split the market between hardware-anchored ecosystems and software-defined platforms. Consolidation pressure concentrates around motion control intellectual property and edge computing acceleration. Three archetypes dominate: precision motion specialists, GPU-accelerated platform providers, and collaborative safety innovators. Competitive moves center on predictive maintenance module unbundling and multi-modal perception stack integration.
Within the precision motion tier, FANUC Corporation and YASKAWA ELECTRIC CORPORATION exemplify Japanese industrial heritage extending into adaptive control algorithms. NVIDIA Corporation occupies a distinct position bridging GPU-native software stacks with real-time robotics deployment. Among collaborative safety innovators, Boston Dynamics represents the research-to-production trajectory for mobile manipulation platforms.
| Leading Market Players |
|---|
| ABB |
| Boston Dynamics |
| NVIDIA Corporation |
| Intel Corporation |
| FANUC Corporation |
| YASKAWA ELECTRIC CORPORATION |
| NIDEC CORPORATION |
| Panasonic Corporation |
| Hanson Robotics |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration for advanced servo motors and edge AI processors creates dual vulnerability to pricing volatility and supply disruption, compressing hardware margins for system integrators while forcing tier-one automotive buyers in Stuttgart and Wolfsburg into long-term offtake contracts that lock in premium pricing tiers for qualified suppliers.
Pricing Analysis
EU Machinery Directive CE marking requirements dictate the pricing tier structure across European deployments, with force-torque sensor certification and collaborative safety validation adding 15-25% hardware premiums over equivalent-payload industrial configurations. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates German automotive OEMs from tier-two Chinese contract manufacturers from Indian PLI-subsidized first-movers. Cost compression in the economy tier is intensifying because BIS certification timelines for imported equipment extend working capital cycles. Tier-two electronics manufacturers in Shenzhen and Dongguan show the highest price sensitivity, while German automotive OEMs prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for the GPU accelerators and AI processors that power edge inference, while NIDEC and Japanese precision motor specialists control high-torque servo production. Component sourcing draws from Taiwan for semiconductors, Japan for precision motion hardware, and South Korea for memory and display modules. Single-source vulnerability for 7nm and below process nodes creates acute exposure to geopolitical trade restrictions. Distribution runs through authorized integrator networks in Bavaria and Baden-Württemberg, direct OEM relationships in Michigan and South Carolina, and emerging channel partnerships in Maharashtra and Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU Machinery Directive certification and ISO 10218 validation cycles creates substantial switching costs that protect incumbent market positions from displacement by lower-cost challengers lacking notified body relationships.
For Market Incumbents: Insulate controller software ecosystems through proprietary fieldbus protocol extensions that resist seamless AI module integration by third-party entrants. Deepen backward integration into edge AI processor supply through strategic foundry allocations in Taiwan, while accelerating predictive maintenance module unbundling to capture recurring revenue streams from automotive end-users in Michigan and South Carolina. For New Entrants and Emerging Players: Mid-market contract manufacturers in India and Southeast Asia represent the most penetrable entry point, with PLI scheme subsidies offsetting capital expenditure barriers for fenceless cobot deployments in sub-1,000 unit batch production. Tier-two electronics assembly in Dongguan and medical device contract manufacturing in Boston offer adjacent white-space with less entrenched incumbent relationships. A robot-as-a-service distribution model bypasses capital expenditure approval thresholds while accelerating proof-of-concept cycles. For Investors and Strategic Acquirers: GPU-native software stack specialists with real-time motion planning capabilities command premium valuations due to algorithm development cycle compression that research-stage competitors cannot replicate. Long-term viability hinges on bridging the sim-to-real transfer gap for reinforcement learning manipulation. The signal to monitor is transformer-based neural architecture deployment timelines in Stuttgart and Wolfsburg automotive plants, as acceleration indicates tipping point adoption that validates platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Module Unbundling | Transforms warranty-included features into annual software licenses, capturing recurring revenue from German automotive OEMs. |
| Multi-Modal Perception Stack Integration | Enables bin-picking of deformable objects without pre-programmed grasp points, collapsing reprogramming time from days to minutes. |
| GPU-Native Robotics Software Platform | Compresses algorithm development cycles through CUDA-accelerated edge computing, differentiating from PLC architectures. |
| Force-Torque Sensor Certification Investment | Secures CE marking under EU Machinery Directive, unlocking fenceless deployment in Bavarian automotive clusters. |
| Robot-as-a-Service Channel Development | Bypasses capital expenditure barriers for seasonal production facilities and contract manufacturers in India and Southeast Asia. |
Study Parameters
The analysis maps industrial robots, collaborative robots, service robots, and humanoid platforms, each validated through automation engineering directors, plant managers at tier-one automotive OEMs, robotics integrator technical leads, and aftermarket service heads. Primary interview intelligence triangulates against SEC 10-K filings from precision motion specialists, MIIT industrial policy disclosures, EU Machinery Directive implementation guidance, and customs data for servo motor and controller trade flows. Bottom-up unit deployment estimates reconcile with top-down manufacturing automation spending analysis.
Forecast assumptions hold fixed the EU AI Act risk classification timeline and OSHA collaborative robot enforcement interpretation, while varying China's GB standards adoption velocity and India's PLI scheme extension decisions across the projection horizon. Segmentation dimensions include product payload tier, application environment structured versus unstructured, end-user capital expenditure threshold, and technology maturity gradient from computer vision to natural language processing. CAGRs derive from installed base replacement cycles, smart factory upgrade intensity, and fenceless automation penetration rates in small and medium enterprises.
Practitioners should monitor semiconductor foundry utilization rates, notified body certification backlog durations, and sim-to-real transfer reliability metrics for early signals of supply constraint or demand inflection. Forecasts embed assumptions about regulatory harmonization progress and workforce retraining program effectiveness. Quarterly review of automotive OEM automation engineering headcount changes and tier-two manufacturer cobot pilot announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market